
 North America Hand Sanitizer Market | 2026-2036
North America Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hand Sanitizer Market Analysis
Aftermarket service revenue for dispenser maintenance and refill logistics is fragmenting across regional service networks and direct-to-facility contracts. GOJO Industries, Inc. dominates touch-free dispensing infrastructure in U.S. healthcare corridors. Ecolab Inc. anchors institutional supply relationships through bundled hygiene programs. Reckitt Benckiser Group plc leverages Lysol brand recognition to sustain retail shelf positioning against private-label encroachment.
Hand sanitizer denotes alcohol-based or non-alcohol antiseptic formulations typically containing ethanol, isopropanol, or benzalkonium chloride at concentrations meeting germicidal efficacy thresholds, manufactured through compounding, filtration, and sterile filling processes designed to reduce transient microbial flora on intact skin without water access. Gel formats occupy the largest volume share due to familiar user experience and controlled dosing mechanics, while foam formulations command premium positioning in healthcare settings where rapid coverage and reduced drip rates justify higher per-use economics. The institutional distribution channel carries the densest margin pool, though online direct procurement is capturing share among smaller education and hospitality buyers seeking subscription replenishment models.
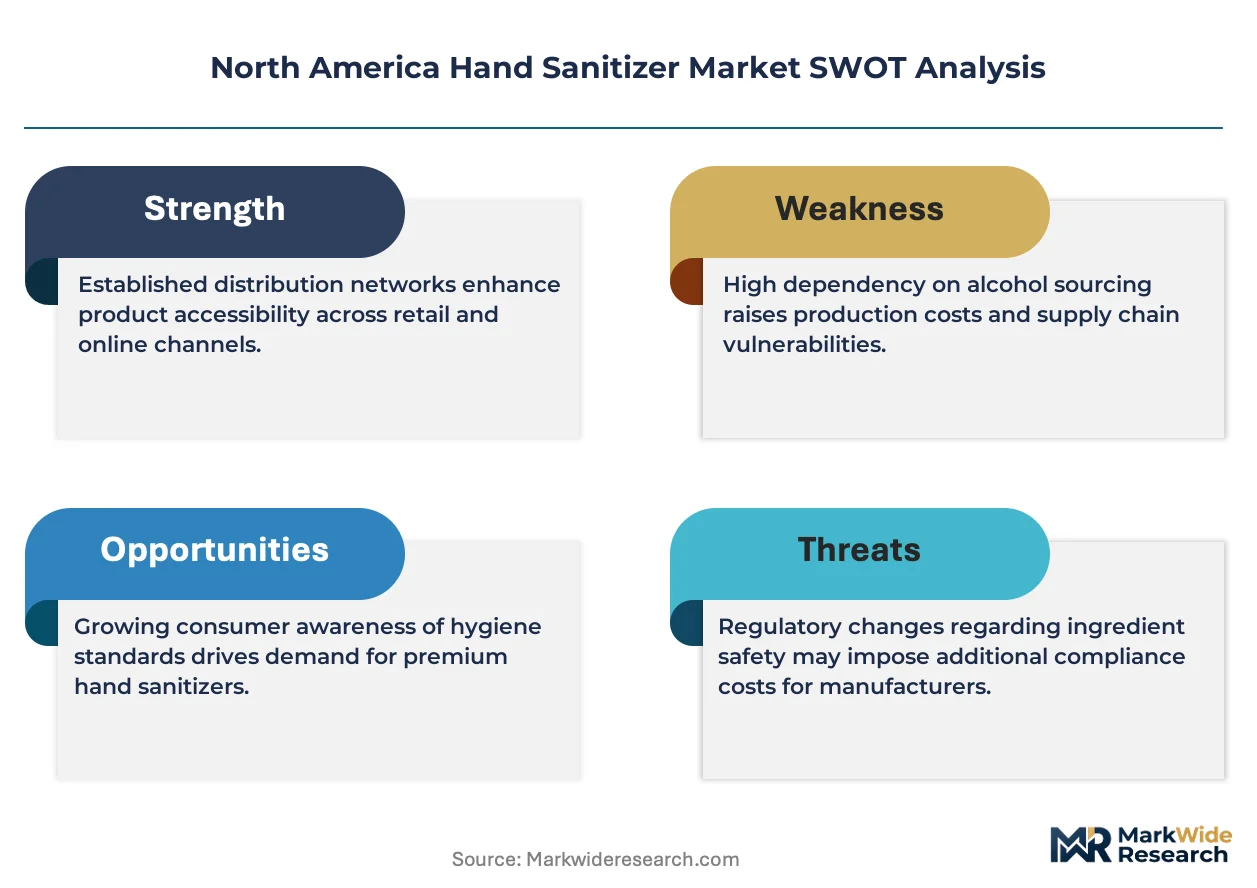
FDA OTC monograph enforcement and EPA surface disinfectant cross-claims govern formulation standards and marketing claims across the United States, while Health Canada and PMRA oversight in Canada establishes parallel but distinct labeling and efficacy requirements. The EPA's emerging scrutiny of quaternary ammonium compound environmental fate profiles may reshape non-alcohol formulation pipelines. Stakeholders must monitor evolving state-level procurement mandates favoring domestic manufacturing and sustainable packaging thresholds as these criteria penetrate hospital system RFP scoring matrices.
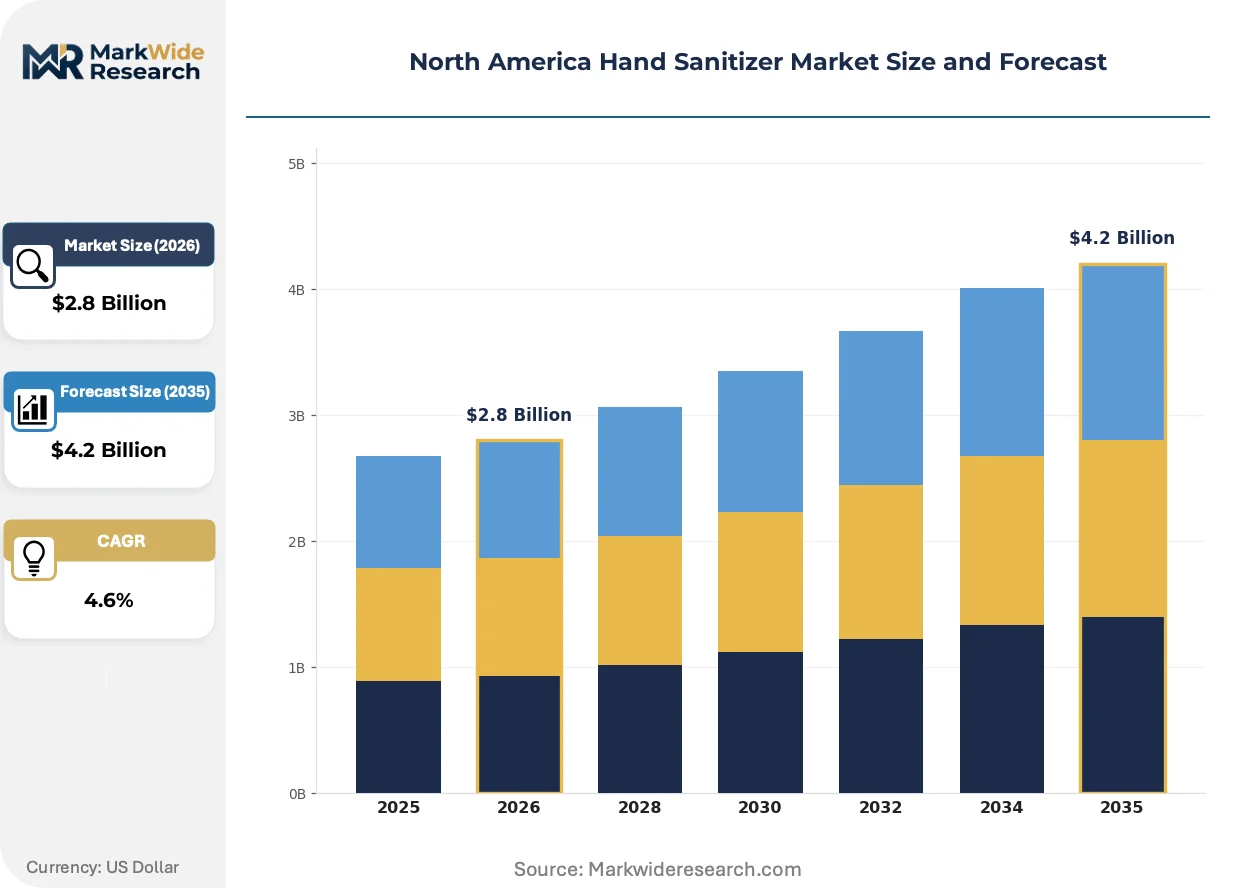
Market Dynamics
FDA OTC monograph enforcement is compressing formulation pipelines while hospital procurement consolidation concentrates purchasing power among fewer institutional buyers across the United States and Canada.
Growth Catalysts
- Hospital Infection Control Mandates:CMS reimbursement penalties for hospital-acquired infections drive bulk purchasing of alcohol-based rubs in U.S. acute care facilities.
- EPA Emerging Pathogen Protocol:The agency's List N expansion for SARS-CoV-2 efficacy claims sustains institutional stocking requirements in long-term care.
- Canada's Aging Facility Infrastructure:Provincial health authority capital programs retrofit hand hygiene stations across Ontario and Quebec long-term care networks.
Market Restraints
- Ethanol Feedstock Volatility:Corn-derived alcohol pricing swings squeeze margin structures for domestic compounders dependent on agricultural commodity cycles.
- Single-Source Dispenser Lock-In:Proprietary cartridge systems in U.S. healthcare corridors create switching costs that fragment aftermarket service competition.
- Quaternary Ammonium Scrutiny:EPA environmental fate assessments of benzalkonium chloride threaten non-alcohol formulation shelf space in eco-sensitive procurement channels.
Strategic Opportunities
- Mexico's Underpenetrated Institutional Channel:IMSS hospital network standardization creates first-mover openings for automated dispensing infrastructure in central Mexico corridors.
- Subscription Refill Models:Direct-to-facility replenishment platforms bypass traditional distribution markups for mid-size education and hospitality buyers.
- Sustainable Packaging Mandates:California's plastic waste reduction laws and similar state-level scoring criteria reward refillable bulk systems in hospital RFPs.
Industry Challenges
- Formulation Chemist Scarcity:FDA compliance expertise for OTC monograph submissions commands premium compensation, stretching mid-tier manufacturer R&D budgets.
- Legacy Dispenser Integration:Retrofitting touch-free sensors into existing wall-mounted infrastructure requires site-specific electrical work that complicates nationwide rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hand Sanitizer Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Wipe Packaging Type: Bottle, Sachet, Bulk, Dispenser Distribution Channel: Online, Retail, Institutional, Direct Sales End User: Healthcare, Education, Hospitality, Residential |
| Companies Covered | Reckitt Benckiser Group plc, GOJO Industries, Inc., Procter & Gamble Company, 3M Company, Henkel AG & Company, KGaA, Unilever plc, Ecolab Inc., The Clorox Company, Vi-Jon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hand Sanitizer Market Emerging Trajectories
Formulation science and dispensing hardware are converging to redefine efficacy claims and user compliance measurement in institutional settings.
Smart dispensing infrastructure is hybridizing. Sensor-equipped units track usage frequency by department and feed data into hospital infection control dashboards. U.S. health systems with Joint Commission accreditation pressure deploy these networks fastest. This convergence is compressing the traditional divide between product supply and compliance auditing services.
Health Canada's PMRA is tightening surface disinfectant cross-labeling prohibitions. The regulator now requires distinct efficacy testing for hand rub versus hard surface claims. Canadian manufacturers with dual-purpose portfolios face redundant toxicology study costs. Hospital procurement officers in Ontario and British Columbia increasingly specify single-purpose formulations to preempt labeling disputes.
Direct replenishment contracts are displacing distributor intermediaries. Smaller hospitality chains and private school networks now source bulk refills through manufacturer portals with automated reorder triggers. This channel compression is most visible in the U.S. Mountain West and Pacific Northwest where fragmented buyer geography previously sustained regional distributor margins.
North America Hand Sanitizer Market Segmentation
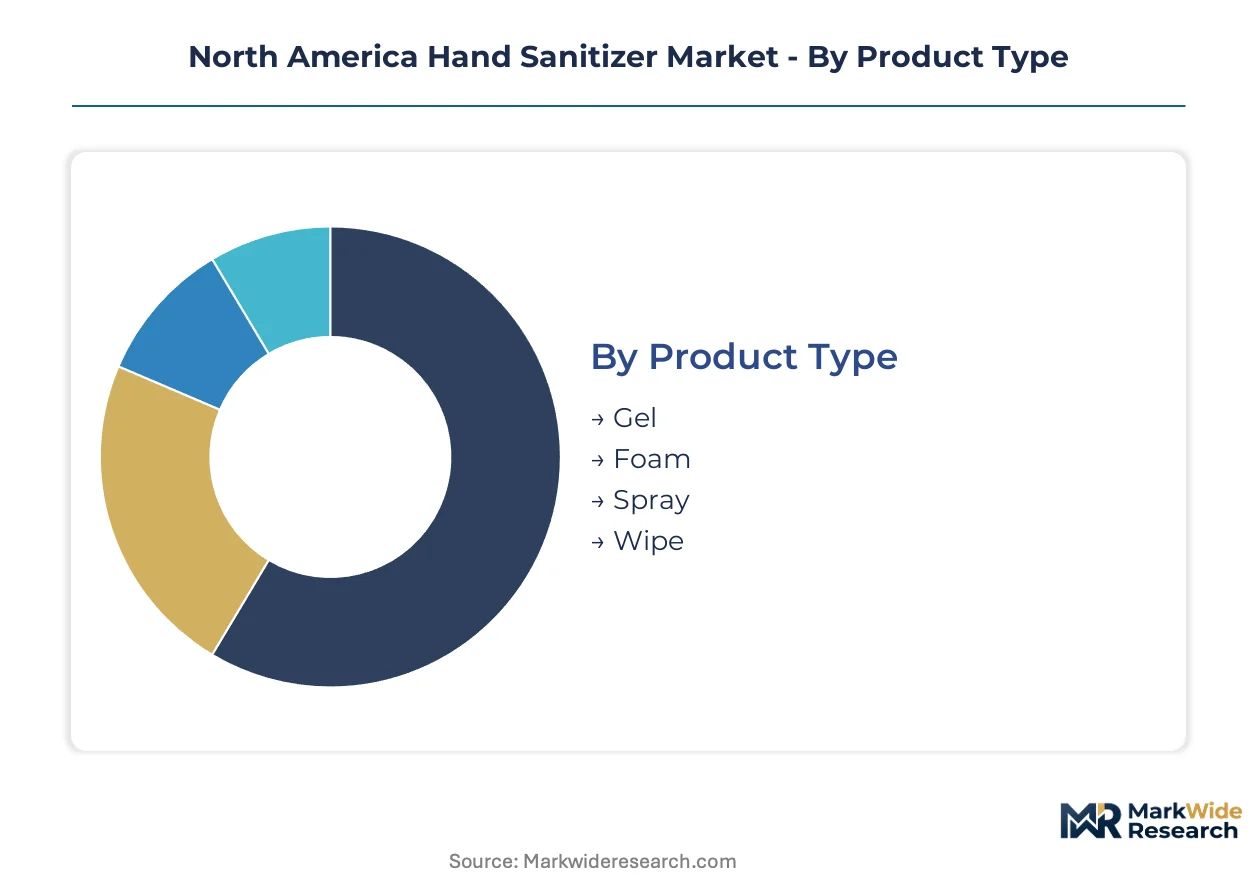
Segmentation in the North America hand sanitizer market reveals divergent procurement rhythms across product formats and buyer types. Hospital infection control mandates accelerate institutional turnover while retail channels respond to consumer preference shifts with longer planning cycles.
Product Type:
Gel formulations turn inventory fastest in mass retail channels, while foam and spray products cycle more slowly through healthcare procurement pipelines with extended contract terms.
- Gel:Viscous alcohol-based or non-alcohol formulations with controlled flow characteristics. U.S. hospital corridors and long-term care facilities in Ontario concentrate demand here as CMS reimbursement penalties for hospital-acquired infections drive standardized alcohol-rub protocols.
- Foam:Aerated low-viscosity formulations that expand on dispensing to cover skin surface rapidly. Healthcare settings in Quebec and British Columbia specify foam for rapid-coverage applications where reduced drip rates justify per-use economics above gel alternatives.
- Spray:Pump-dispensed liquid formulations offering portability for field applications. Remote healthcare clinics in Canada's northern territories and mobile veterinary services favor spray formats for kit-based deployment.
- Wipe:Saturated nonwoven substrates delivering pre-measured dosing. School districts across Texas and California specify wipe formats for classroom hygiene stations where student self-application requires controlled consumption.
Gel anchors the volume base while foam gains share at the steepest rate.
Packaging Type:
Packaging economics stratify sharply between single-use convenience and bulk institutional efficiency, with dispenser systems commanding the longest replacement cycles tied to capital equipment budgets.
- Bottle:Rigid or squeeze containers ranging from pocket-sized to liter volumes. Mass merchants in the U.S. Midwest and suburban retail corridors stock bottle formats as the default consumer purchase, with private-label penetration highest in this segment.
- Sachet:Single-use flexible pouches containing pre-measured doses. Airlines based in Dallas and Atlanta and hotel chains across Florida specify sachets for in-room amenities where waste reduction targets conflict with hygiene mandates.
- Bulk:Multi-liter containers for decanting into permanent dispensers. Hospital purchasing cooperatives in Illinois and Michigan negotiate bulk supply agreements with automated replenishment triggers tied to usage telemetry.
- Dispenser:Wall-mounted or freestanding units with proprietary cartridge interfaces. GOJO Industries touch-free infrastructure dominates U.S. healthcare corridors, while Ecolab anchors bundled hygiene programs through dispenser-locked supply contracts.
Bottle formats capture the highest absolute unit movement while dispenser systems generate the densest margin concentration.
Distribution Channel:
Channel selection determines pricing transparency and service bundling, with direct procurement compressing traditional distributor markups most aggressively in mid-market buyer segments.
- Online:E-commerce platforms and manufacturer-direct portals. Smaller hospitality chains in Colorado and private school networks in Washington State source through subscription replenishment models with automated reorder triggers.
- Retail:Mass merchants, drugstores, and convenience outlets. Reckitt Benckiser leverages Lysol brand recognition to defend shelf positioning against private-label encroachment in California and New York metro markets.
- Institutional:Group purchasing organizations and healthcare supply networks. Procurement consolidation among U.S. hospital systems concentrates purchasing power, with fewer buyers commanding larger contract volumes.
- Direct Sales:Manufacturer field representatives serving named accounts. Ecolab deploys this channel for bundled hygiene programs spanning hand sanitizer, surface disinfectants, and compliance auditing services.
Institutional channels carry the densest margin pool while online direct procurement expands most quickly among education and hospitality buyers.
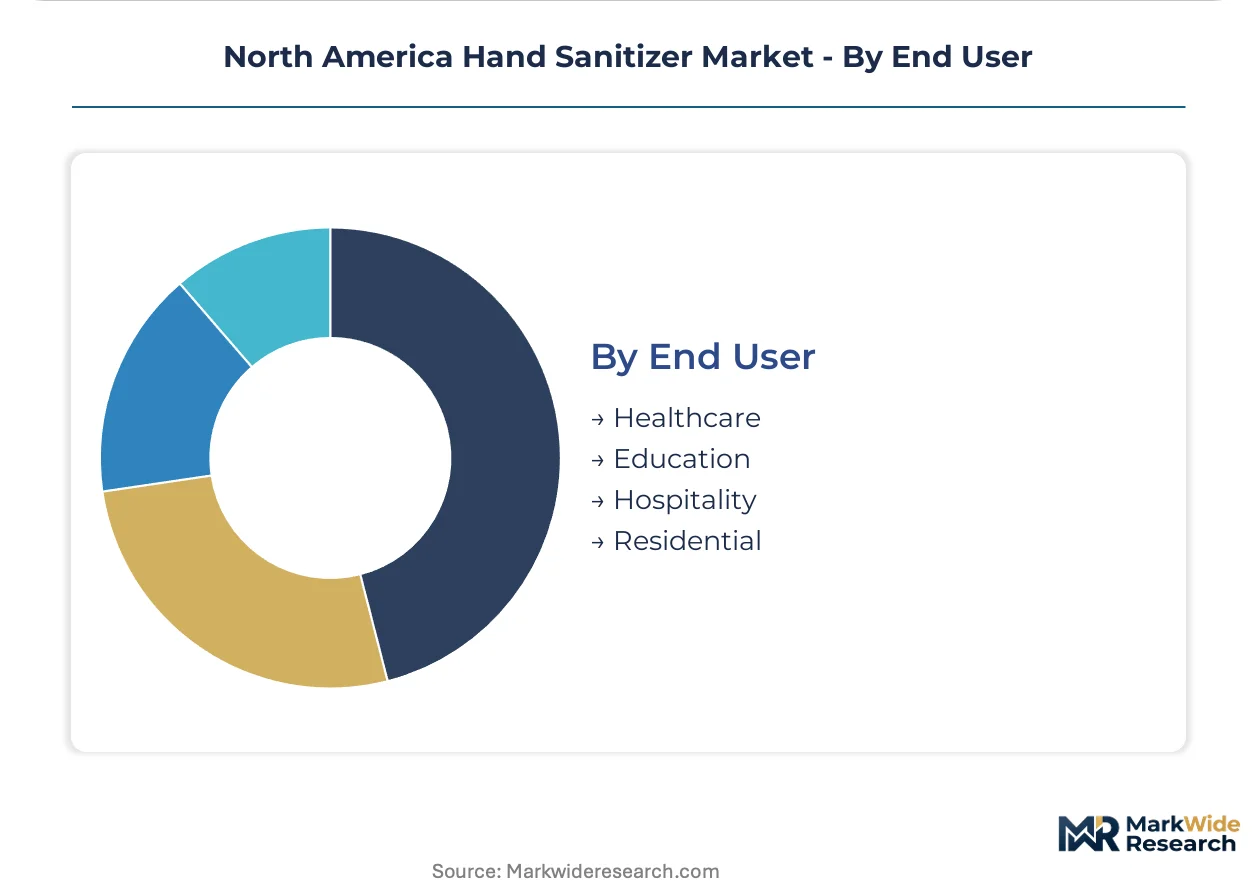
End User:
End-use segmentation maps directly to regulatory scrutiny intensity, with healthcare facing the strictest formulation standards and residential the most price-sensitive.
- Healthcare:Acute care hospitals, long-term care facilities, and outpatient clinics. FDA OTC monograph enforcement and Joint Commission accreditation pressure drive specification of alcohol-based rubs in U.S. facilities, while Health Canada PMRA oversight governs Canadian procurement.
- Education:K-12 districts and higher education campuses. California's plastic waste reduction laws and similar state-level scoring criteria reward refillable bulk systems in school RFPs.
- Hospitality:Hotels, restaurants, and event venues. Mexico's underpenetrated institutional channel creates first-mover openings for automated dispensing infrastructure in central Mexico corridors serving tourism corridors.
- Residential:Individual consumers purchasing for home use. Corn-derived ethanol pricing swings squeeze margin structures for domestic compounders serving this price-sensitive segment through retail intermediaries.
Healthcare anchors the volume base while education gains share at the steepest rate as facility retrofit programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes hand sanitizer primarily through institutional procurement pipelines, while Canada and Mexico exhibit divergent channel mixes favoring retail and emerging direct-to-facility models respectively.
United States
Hospital infection control mandates and CMS reimbursement penalties for hospital-acquired infections drive bulk purchasing of alcohol-based rubs in acute care facilities. FDA OTC monograph enforcement continues reshaping formulation standards and marketing claims for domestic manufacturers. Chicago and Detroit hospital purchasing cooperatives negotiate automated replenishment agreements tied to usage telemetry from smart dispensing infrastructure.
Canada
Provincial health authority capital programs retrofit hand hygiene stations across Ontario and Quebec long-term care networks with foam formulations specified for rapid-coverage applications. Health Canada PMRA oversight establishes distinct labeling and efficacy requirements separate from U.S. FDA frameworks. Toronto and Vancouver procurement officers increasingly specify single-purpose formulations to preempt cross-labeling disputes with surface disinfectant portfolios.
Mexico
IMSS hospital network standardization creates first-mover openings for automated dispensing infrastructure in central Mexico corridors serving tourism and manufacturing zones. The country's national health regulator governs antiseptic registration through centralized pharmaceutical oversight. Mexico City and Nuevo León facilities represent the densest near-term opportunity as procurement standardization displaces fragmented regional purchasing.
California
Plastic waste reduction laws and state-level scoring criteria reward refillable bulk systems in school and hospital RFPs across the Pacific Coast. California's environmental regulator enforces packaging mandates that penetrate procurement matrices ahead of federal standards. Los Angeles and San Francisco school districts specify wipe formats for classroom hygiene stations where student self-application requires controlled consumption protocols.
Texas
School districts across the state specify wipe formats for classroom hygiene stations while hospitality chains favor sachet amenities for in-room deployment. State procurement guidelines increasingly incorporate domestic manufacturing preferences into scoring algorithms. Dallas and Houston anchor distribution networks serving mid-continent education and hospitality buyers through regional service contracts.
North America Hand Sanitizer Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The North America hand sanitizer market structures around three distinct player tiers: multinational hygiene conglomerates with bundled service portfolios, specialized dispensing infrastructure providers with locked supply contracts, and regional compounders serving price-sensitive retail channels. Competitive moves center on procurement consolidation capture and aftermarket service revenue fragmentation rather than capacity expansion.
Within the institutional infrastructure tier, GOJO Industries, Inc. and Ecolab Inc. exemplify divergent approaches to healthcare corridor penetration. Reckitt Benckiser Group plc occupies a position representing brand-anchored retail defense against private-label encroachment. These three entities collectively illustrate how market position depends on channel-specific capability accumulation rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| GOJO Industries, Inc. |
| Procter & Gamble Company |
| 3M Company |
| Henkel AG & Company, KGaA |
| Unilever plc |
| Ecolab Inc. |
| The Clorox Company |
| Vi-Jon Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in U.S. ethanol distillation capacity following pandemic-era expansion drives aggressive contract bidding among domestic compounders while squeezing spot-market pricing for non-captive buyers. This utilization imbalance rewards institutional purchasers with long-term offtake agreements while pressuring regional formulators lacking backward integration into feedstock production.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement in U.S. healthcare corridors, with three-tier pricing structure across premium, standard, and economy levels differentiated by FDA OTC monograph compliance tier and dispenser system integration depth. Price differentiation hinges on Joint Commission certification bundling and automated replenishment service inclusion. Cost compression in standard-tier gel formulations is intensifying because corn-derived ethanol volatility transfers margin risk to non-integrated compounders. Residential retail channels exhibit highest price sensitivity, while hospital GPOs with telemetry-integrated dispenser networks show lowest sensitivity due to compliance auditing value-adds.
Supply Chain Analysis
Corn ethanol production concentrates in Iowa, Illinois, and Nebraska, with isopropanol sourcing anchored in Texas and Louisiana petrochemical corridors. Benzalkonium chloride feedstock draws from Chinese and Indian pharmaceutical intermediate suppliers, creating tariff exposure on non-alcohol formulation inputs. Single-source vulnerability pervades proprietary dispenser cartridge ecosystems, particularly GOJO Industries' locked healthcare infrastructure. Distribution runs through institutional GPOs and direct-to-facility portals, with regional distributor networks fragmenting in the Mountain West and Pacific Northwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across mid-market education and hospitality procurement creates viable entry niches as subscription replenishment platforms displace traditional distributor relationships. This demand-side shift toward direct manufacturer engagement rewards specialized service capabilities over manufacturing scale alone.
For Market Incumbents: Pre-empt private-label encroachment in retail channels by accelerating sustainable packaging certification investments ahead of California's plastic waste reduction law expansion. Lock hospital system relationships through telemetry-integrated dispenser infrastructure that raises switching costs for competing aftermarket service providers. Vertical integration into corn ethanol production mitigates feedstock volatility exposure threatening mid-tier margin structures. For New Entrants and Emerging Players: Mexico's IMSS hospital network standardization in central Mexico corridors represents the most penetrable entry point for automated dispensing infrastructure, with Nuevo León and Mexico City facilities offering first-mover positioning before procurement consolidation completes. U.S. private school networks in Washington State and Colorado hospitality chains demonstrate underserved demand for subscription refill platforms with automated reorder triggers. A direct-to-facility go-to-market angle bypasses entrenched distributor markups and captures procurement officers seeking usage telemetry integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart dispensing infrastructure as sensor hardware commoditization and software platform economics shift value capture toward data analytics capabilities. Long-term viability over the coming decade favors targets with installed base density in healthcare corridors and compliance auditing service revenue streams. Acquisition focus should center on regional compounders with FDA OTC monograph submission expertise and established hospital GPO relationships. The signal to watch is telemetry adoption velocity in Ontario and British Columbia long-term care networks as Canadian procurement standardization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Dispenser Infrastructure Deployment | Sensor-equipped units feeding hospital infection control dashboards satisfy Joint Commission accreditation pressure in U.S. acute care facilities. |
| Sustainable Packaging Certification | California's plastic waste reduction laws and state-level RFP scoring criteria reward refillable bulk systems ahead of federal mandates. |
| Direct-to-Facility Replenishment Platform | Subscription models with automated reorder triggers bypass distributor markups for mid-size education and hospitality buyers. |
| FDA OTC Monograph Compliance Investment | Formulation chemist expertise commands premium compensation, creating defensive moats against mid-tier manufacturer competition. |
| IMSS Network Standardization Capture | First-mover positioning in Mexico's central hospital corridors before procurement consolidation completes locks long-term supply relationships. |
Methodological Framework
A standing panel of infection control officers, hospital procurement managers, GPO contracts specialists, and formulation R&D directors provided ongoing calibration against primary fieldwork conducted across U.S. healthcare systems and Canadian provincial health authorities. Secondary validation drew from FDA OTC monograph filings, Health Canada PMRA registration databases, EPA List N efficacy claim records, hospital purchasing cooperative contract disclosures, and corn ethanol futures pricing data. Bottom-up facility-level demand modeling triangulated against top-down market sizing from trade association production statistics.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product format, packaging type, distribution channel, and end-use vertical including healthcare, education, hospitality, and residential procurement patterns. CAGRs derived from weighted average of historical volume trajectories and forward-looking procurement pipeline visibility, incorporating ethanol feedstock price elasticity coefficients and dispenser infrastructure replacement cycle assumptions.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity cycles, healthcare reimbursement policy, or cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding institutional procurement consolidation velocity and smart dispenser adoption curves. Cross-checking against EPA emerging pathogen protocol updates and state-level sustainable packaging mandate implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Biofilms Treatment Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Disinfection Equipment Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Antimicrobial Suture Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Hand Hygiene Market
Infection Control
Surgical Site Infections Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Hygiene Stations Market