
 Salivary Gland Infection Treatment Market | 2026-2036
Salivary Gland Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Salivary Gland Infection Treatment Market Analytics
Hospital procurement of advanced antibiotic and antiviral therapies is hardening as outpatient clinic referrals for sialadenitis management rise. Pfizer leverages its manufacturing scale to dominate oral antibiotic supply chains across North American hospital networks. Merck & Co. anchors injectable antiviral development through sustained R&D intensity in infectious disease platforms. GlaxoSmithKline competes in topical analgesic segments where brand strength supports pharmacy-level distribution control.
Salivary gland infection treatment encompasses pharmaceutical and device-based interventions targeting bacterial, viral, and obstructive pathologies of the parotid, submandibular, and sublingual glands, typically involving beta-lactam antibiotics, hydration protocols, and sialendoscopy-assisted drainage. Antibiotics remain the largest revenue pool within product type segmentation, though antivirals represent the fastest-growing category as mumps and cytomegalovirus-related sialadenitis recognition improves. Oral delivery mode occupies the highest volume share, while intravenous formulations capture concentrated margin pools in severe hospitalized cases requiring parenteral broad-spectrum coverage.
FDA antimicrobial stewardship guidelines restrict empirical broad-spectrum antibiotic prescribing, reshaping hospital formulary decisions toward targeted narrow-spectrum agents. EMA pharmacovigilance frameworks and WHO essential medicines standards further constrain off-label antiviral use, elevating documentation requirements for reimbursement. Stakeholders must monitor evolving resistance surveillance data and regulatory label expansions to align pipeline investments with constrained prescription environments.
Market Dynamics
FDA antimicrobial stewardship guidelines and EMA pharmacovigilance frameworks are compressing empirical prescribing freedom, forcing hospital formularies toward narrow-spectrum agents and elevating diagnostic precision requirements before therapy initiation.
Growth Catalysts
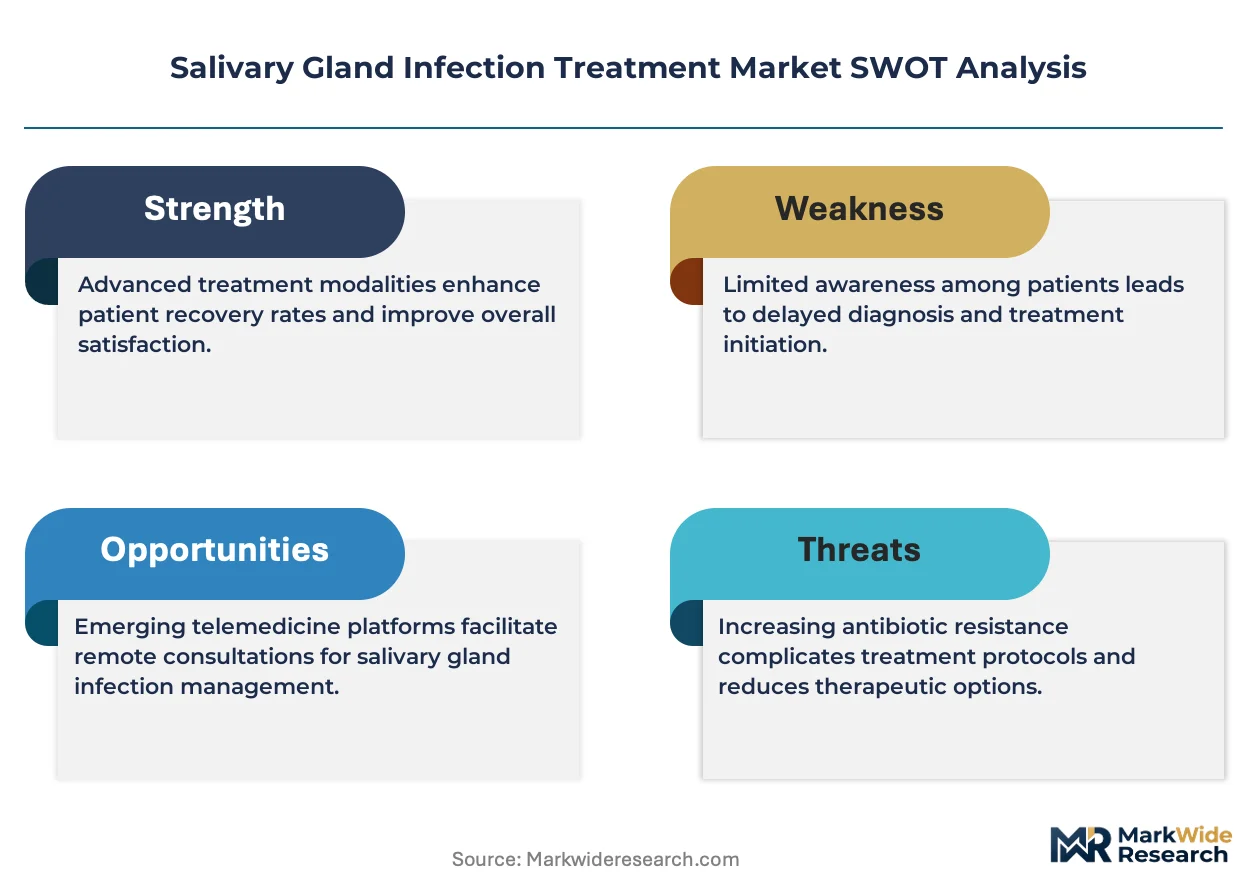
- Aging Demographics in Developed Economies:Japan, Germany, and the United States exhibit rising recurrent sialadenitis incidence as elderly populations expand, driving ENT service capacity investments and specialized referral networks.
- EMA Pharmacovigilance Frameworks:Tighter adverse event reporting requirements for broad-spectrum antibiotics are accelerating adoption of targeted diagnostic protocols that improve appropriate therapy matching.
- Sialendoscopy-Assisted Drainage:Minimally invasive interventional techniques are reducing hospitalization duration for obstructive sialadenitis, expanding outpatient procedure volumes and device utilization.
Market Restraints
- API Supply Concentration:Beta-lactam active pharmaceutical ingredient manufacturing clusters in India and China create vulnerability to export restriction shocks and quality enforcement actions.
- Diagnostic Cost Burden:Salivary gland ultrasound and cross-sectional imaging add procedural expense that delays definitive therapy initiation in resource-constrained settings.
- Antibiotic Resistance Surveillance:Rising Staphylococcus aureus and Streptococcus viridans resistance profiles narrow effective empirical options, complicating formulary design.
Strategic Opportunities
- Underpenetrated Ambulatory Surgery Centers:United States outpatient facilities lack standardized sialendoscopy programs, representing white space for device manufacturers and training consortiums.
- Antiviral Label Expansion:Cytomegalovirus and mumps-related sialadenitis recognition creates opportunity for off-label antiviral repositioning supported by targeted clinical evidence generation.
- Digital Therapeutics Integration:Smartphone-based hydration compliance monitoring and symptom tracking applications can reduce recurrence rates in chronic sialadenitis populations.
Industry Challenges
- Interventional ENT Training Pipeline:Sialendoscopy proficiency requires specialized fellowship exposure that remains concentrated in academic medical centers, limiting geographic procedure accessibility.
- Reimbursement Documentation Burden:Payers demand microbiologic confirmation before approving targeted antibiotic therapy, extending revenue cycle timelines and administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salivary Gland Infection Treatment Market |
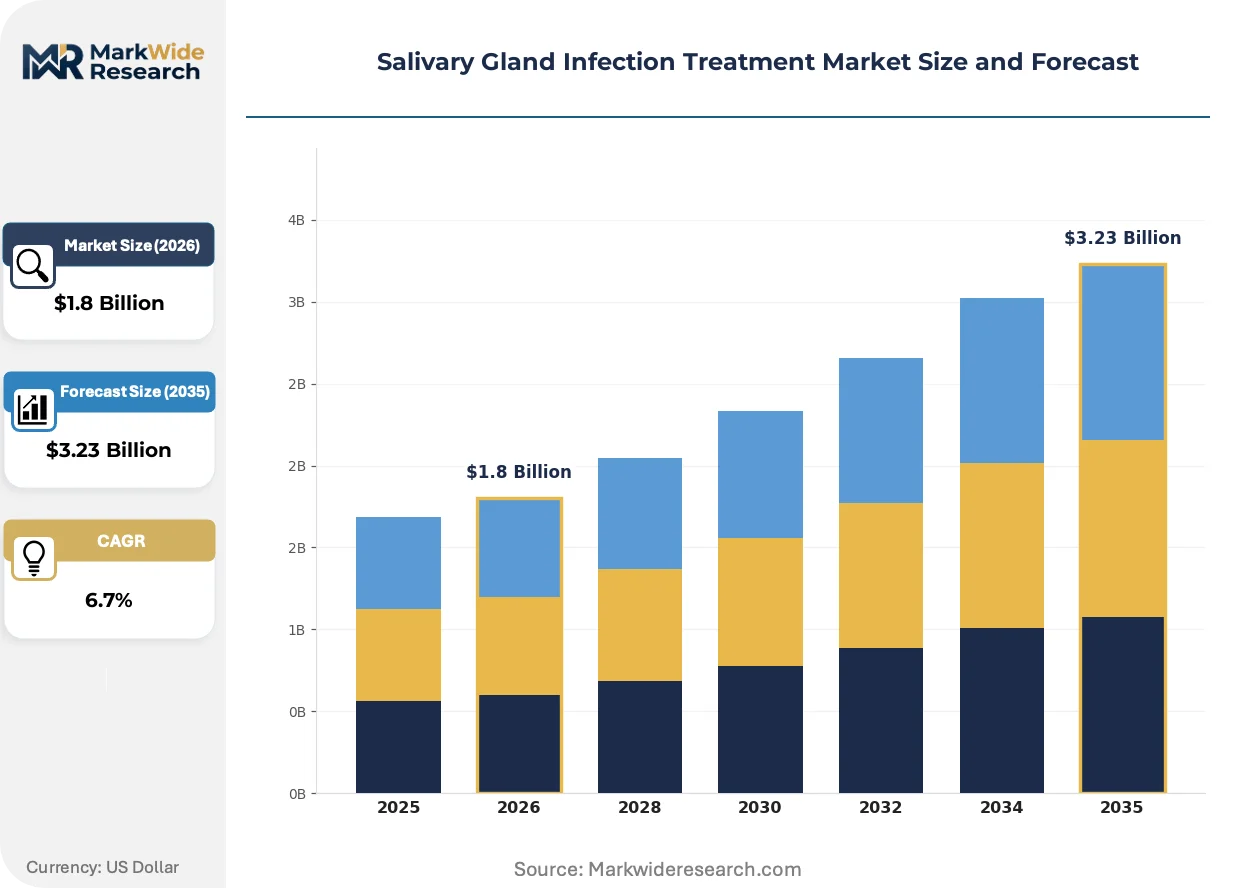
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Analgesics, Saliva Substitutes Therapy Area: Infectious Diseases, Oral Health, Women's Health, Pain Management End User: Hospitals, Outpatient Clinics, Diagnostic Labs, Home Care Delivery Mode: Oral, Injectable, Topical, Intravenous |
| Companies Covered | Johnson & Johnson Services, GlaxoSmithKline, Merck & Co., AbbVie, AstraZeneca, Pfizer, Allergan, FUJIFILM Holdings Corporation, Siemens Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salivary Gland Infection Treatment Market Evolving Landscape
Diagnostic precision technologies and minimally invasive interventional platforms are displacing empirical management protocols, while regulatory pressure on antimicrobial prescribing reshapes therapeutic decision workflows across hospital and outpatient settings.
Point-of-care salivary gland ultrasound is converging with artificial intelligence-assisted image interpretation to enable bedside differentiation between inflammatory, obstructive, and neoplastic pathologies. Emergency departments and urgent care networks in the United States are deploying portable systems to reduce unnecessary CT radiation exposure and accelerate appropriate specialty referral. This convergence is compressing time-to-diagnosis intervals and shifting initial evaluation away from radiology department dependency.
EMA pharmacovigilance frameworks now mandate enhanced adverse event documentation for off-label antiviral utilization in sialadenitis management, elevating prescriber liability exposure across European hospital networks. The industrial consequence manifests as formulary committee conservatism and preference for approved-label alternatives with established safety databases. Injectable antiviral segments face the most pronounced reimbursement scrutiny, with Germany's hospital payment system tightening case-based compensation for undocumented indications.
Hospital procurement committees are consolidating antibiotic purchasing through centralized pharmacy and therapeutics structures that prioritize narrow-spectrum agents with resistance stewardship credentials. Group purchasing organizations are displacing individual hospital formulary autonomy, concentrating contract negotiation leverage and compressing supplier margins. This behavioral shift is most visible in United States health systems where integrated delivery networks capture specialty pharmacy dispensing and influence prescriber behavior through real-time decision support embedded in electronic health records.
Salivary Gland Infection Treatment Market Segmentation
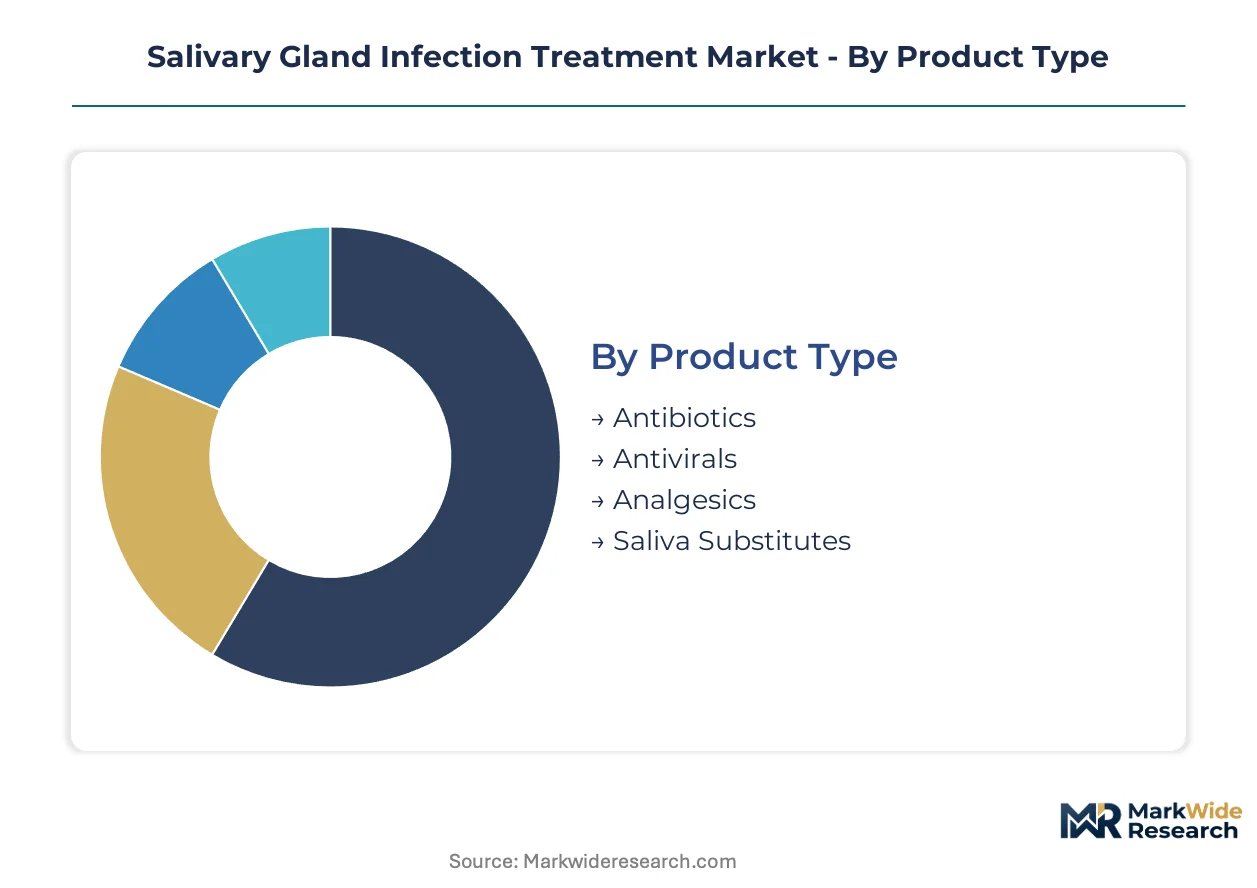
Segmentation reveals how capital deployment and regulatory pressure concentrate across distinct therapeutic modalities and care settings. Hospital formulary committees and outpatient procurement officers allocate budgets differently depending on infection severity, delivery infrastructure, and reimbursement pathways.
Product Type:
Antibiotic manufacturing demands the heaviest upfront investment in fermentation capacity and regulatory compliance infrastructure.
- Antibiotics:Beta-lactam formulations dominate hospital procurement volumes, with narrow-spectrum agents gaining preference under FDA antimicrobial stewardship mandates. United States integrated delivery networks concentrate purchasing through centralized pharmacy and therapeutics committees, favoring suppliers with resistance stewardship credentials.
- Antivirals:Injectable antiviral development requires specialized biologics manufacturing suites and cold-chain distribution networks. Cytomegalovirus and mumps-related sialadenitis recognition is accelerating demand in Japanese and German ENT referral centers.
- Analgesics:Topical NSAID formulations serve post-sialendoscopy pain management protocols.
- Saliva Substitutes:Polymer-based hydration adjuncts address xerostomia-driven recurrent infection risk in elderly populations.
Antibiotics absorb the bulk of installed capacity; antivirals are expanding most quickly.
Therapy Area:
Volume concentration aligns with referral pathway density and specialist availability across metropolitan hospital networks.
- Infectious Diseases:Empirical broad-spectrum coverage faces tightening constraints under EMA pharmacovigilance frameworks. Microbiologic confirmation requirements now precede targeted therapy approval in German and French hospital payment systems.
- Oral Health:Dental-ENT collaboration protocols in Japan drive submandibular sialadenitis recognition and early intervention.
- Women's Health:Sjögren's syndrome-associated sialadenitis creates chronic management demand in rheumatology-ENT crossover populations.
- Pain Management:Post-interventional analgesia protocols support sialendoscopy expansion in ambulatory surgery centers.
Infectious diseases commands the largest addressable patient pool; oral health demonstrates the steepest expansion trajectory as referral networks mature.
End User:
Facility type determines reimbursement coding complexity and capital equipment requirements for interventional procedures.
- Hospitals:Academic medical centers anchor sialendoscopy training pipelines and complex drainage procedures. United States hospital procurement committees consolidate antibiotic purchasing through group purchasing organizations, compressing supplier margins.
- Outpatient Clinics:ENT specialty practices in Germany and Japan are expanding sialadenitis management capacity as aging populations drive recurrent infection incidence.
- Diagnostic Labs:Salivary gland ultrasound and microbiologic confirmation services extend revenue cycle timelines before therapy authorization.
- Home Care:Hydration compliance monitoring and oral antibiotic completion support reduce recurrence rates in chronic cases.
Hospitals retain the dominant share of interventional procedure revenue; outpatient clinics are climbing the fastest as minimally invasive techniques displace inpatient admissions.
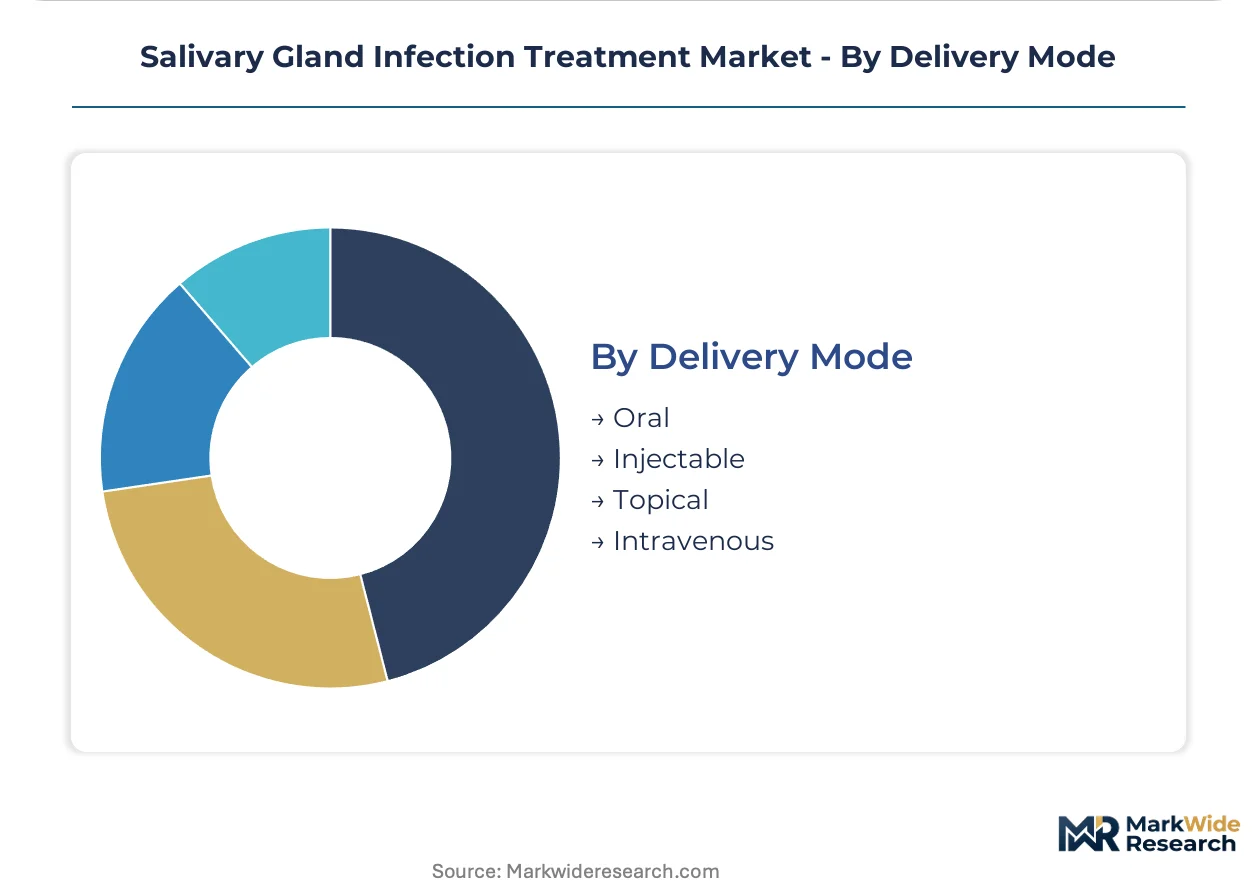
Delivery Mode:
Route selection hinges on infection severity, patient compliance capacity, and parenteral access infrastructure.
- Oral:Amoxicillin-clavulanate and clindamycin formulations capture the highest prescription volumes across North American pharmacy networks. Pfizer leverages manufacturing scale to dominate supply chains.
- Injectable:Severe hospitalized cases requiring parenteral broad-spectrum coverage generate concentrated margin pools. Merck anchors development through sustained R&D intensity in infectious disease platforms.
- Topical:Analgesic gels and antimicrobial rinses support post-procedure recovery protocols.
- Intravenous:Reserved for sepsis-risk presentations and immunocompromised patient populations.
Oral delivery maintains volume leadership; intravenous administration captures premium pricing in acute care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and pharmaceutical manufacturing clusters in China concentrate active pharmaceutical ingredient production, while aging demographics in Japan and Germany drive specialized ENT service expansion.
United States
Integrated delivery networks in California and Texas consolidate antibiotic purchasing through group purchasing organizations, compressing supplier margins. FDA antimicrobial stewardship guidelines restrict empirical broad-spectrum prescribing, reshaping hospital formulary decisions. The Boston-Cambridge biotechnology corridor anchors injectable antiviral development through sustained R&D intensity.
Germany
Aging populations in Bavaria and North Rhine-Westphalia expand recurrent sialadenitis incidence, driving ENT referral network investments. EMA pharmacovigilance frameworks mandate enhanced adverse event documentation for off-label antiviral use. The Munich-Stuttgart medical technology cluster concentrates sialendoscopy device manufacturing and interventional training programs.
Japan
Elderly demographic expansion in Tokyo and Osaka metropolitan areas elevates chronic sialadenitis management demand. PMDA regulatory frameworks align with international antimicrobial stewardship standards, tightening prescription protocols. The Kansai region's pharmaceutical manufacturing base supplies narrow-spectrum beta-lactam formulations across domestic hospital networks.
India
Hyderabad and Ahmedabad pharmaceutical zones dominate beta-lactam active pharmaceutical ingredient production for global antibiotic supply chains. CDSCO quality enforcement actions and export restriction vulnerabilities create supply uncertainty. The Pune-Mumbai corridor anchors contract manufacturing for North American and European hospital procurement networks.
China
Yangtze River Delta chemical parks concentrate fermentation capacity for antibiotic intermediates serving international markets. NMPA regulatory harmonization with WHO essential medicines standards elevates documentation requirements for export certification. The Shandong Peninsula's pharmaceutical industrial zone faces intensifying environmental compliance costs and capacity rationalization pressures.
Salivary Gland Infection Treatment Market Competitive Landscape
Top-tier vendors anchor hospital formulary contracting, while mid-cap specialists concentrate on narrow-spectrum antibiotic development and regional device distribution. The market exhibits tiered concentration around manufacturing scale, regulatory compliance infrastructure, and interventional ENT training network density. Three archetypes dominate: diversified pharmaceutical conglomerates with infectious disease platforms, specialized antiviral developers with biologics manufacturing suites, and medical device manufacturers with sialendoscopy portfolios. Competitive moves center on group purchasing organization contract consolidation and diagnostic-therapeutic bundling arrangements.
Within the diversified pharmaceutical tier, Pfizer and Merck & Co. exemplify scale-driven hospital supply chain anchoring, while GlaxoSmithKline occupies a position in topical analgesic segments where brand strength supports pharmacy-level distribution control. These entities represent manufacturing scale archetypes that dominate oral antibiotic and injectable antiviral procurement channels across North American and European networks.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| GlaxoSmithKline |
| Merck & Co. |
| AbbVie |
| AstraZeneca |
| Pfizer |
| Allergan |
| FUJIFILM Holdings Corporation |
| Siemens Healthcare |
| Others |
Value Network & Pricing Analysis
Specialized interventional ENT fellowship training concentrated in academic medical centers across the United States, Germany, and Japan creates labor-cost differentials that widen pricing spreads between premium sialendoscopy-assisted procedures and standard antibiotic therapy tiers.
Pricing Analysis
Short lead-time premiums for parenteral antibiotic availability in acute sepsis presentations command substantial markups over standard oral formulations stocked at pharmacy level. Three-tier pricing structure across premium, standard, and economy levels stratifies by manufacturing complexity and cold-chain requirements, with injectable antivirals capturing the highest tier. Pricing pressure stems from group purchasing organization consolidation in United States health systems, compressing supplier margins across oral antibiotic categories. Hospital procurement committees exhibit lowest price sensitivity for emergency parenteral reserves, while outpatient clinics face highest sensitivity for chronic maintenance antibiotics.
Supply Chain Analysis
Regional distribution centers in Hyderabad, Ahmedabad, and the Pune-Mumbai corridor anchor hub-and-spoke patterns for beta-lactam active pharmaceutical ingredient movement into North American and European hospital networks. Fermentation capacity draws from India and China for antibiotic intermediates, while specialized biologics manufacturing suites for injectable antivirals rest on United States and German infrastructure. Single-source vulnerability concentrates in Yangtze River Delta chemical parks facing environmental compliance rationalization. Distribution runs through centralized pharmacy and therapeutics committees at integrated delivery networks, displacing individual hospital formulary autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active pharmaceutical ingredient fermentation capacity constraints in Indian and Chinese manufacturing zones prop pricing power for suppliers with backward-integrated production or long-term offtake agreements.
For Market Incumbents: Cement formulary positioning by securing group purchasing organization contracts with antimicrobial stewardship credentials that satisfy FDA guidelines, while adding captive fermentation capacity in India or China to offset API supply concentration risks from export restriction shocks.
For New Entrants and Emerging Players: Begin with ambulatory surgery center sialendoscopy training partnerships in underserved United States metropolitan markets, where standardized interventional programs remain underdeveloped and device-manufacturer consortiums can capture procedure volume growth.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized antiviral developers possessing biologics manufacturing suites given cytomegalovirus and mumps-related sialadenitis label expansion catalysts. Long-term viability favors platforms with diagnostic-therapeutic bundling capabilities. Watch for EMA pharmacovigilance framework enforcement actions as inflection indicators for formulary conservatism shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Stewardship Certification | FDA guideline alignment secures group purchasing organization contract eligibility across United States health systems. |
| Sialendoscopy Training Consortium | Munich-Stuttgart medical technology cluster expansion addresses interventional ENT proficiency gaps in ambulatory settings. |
| API Backward Integration | Hyderabad pharmaceutical zone captive fermentation reduces exposure to CDSCO quality enforcement disruptions. |
| Antiviral Label Expansion | PMDA regulatory harmonization in Japan accelerates cytomegalovirus-related sialadenitis indication recognition. |
| Digital Therapeutics Integration | Smartphone-based hydration compliance monitoring reduces recurrence rates in chronic sialadenitis populations. |
Research Methodology
Multi-period observation of hospital formulary placement rates, antimicrobial resistance surveillance data, and sialendoscopy procedure volumes anchored the trend analysis, supplemented by interviews with ENT department heads, hospital pharmacy and therapeutics committee members, infectious disease specialists, and GPO contracts managers. Secondary validation drew from FDA antimicrobial stewardship guidance documents, EMA pharmacovigilance framework updates, hospital procurement databases, and CMS Medicare reimbursement coding records. Bottom-up patient-flow modeling and top-down pharmaceutical sales triangulation converged on segment-level estimates.
Input-output matrices mapped antibiotic prescription volumes against aging demographic projections and resistance profile shifts across the analysis window. Segmentation dimensions included product type, therapy area, end-user facility category, and delivery mode, with regional regulatory clusters capturing FDA, EMA, PMDA, CDSCO, and NMPA framework variations. CAGRs derived from fitted growth curves applied to historical volume baselines, incorporating microbiologic confirmation requirement changes and outpatient procedure migration trends as industry-specific forecast inputs.
Underlying measurement precision varies by segment; hospital procurement and interventional device categories carry tighter precision than home care and diagnostic lab services. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and API supply stability. Antibiotic resistance surveillance gaps and reimbursement documentation burden shifts in German and French hospital payment systems present specific revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
UV Disinfection Equipment Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Infection Control Supplies Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Denture Disinfectants Market
Infection Control
Virus Filtration Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Sterilization Monitoring Market
Infection Control
Infection Control Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market