
 Skin Antiseptic Market | 2026-2036
Skin Antiseptic Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Antiseptic Market Analytics
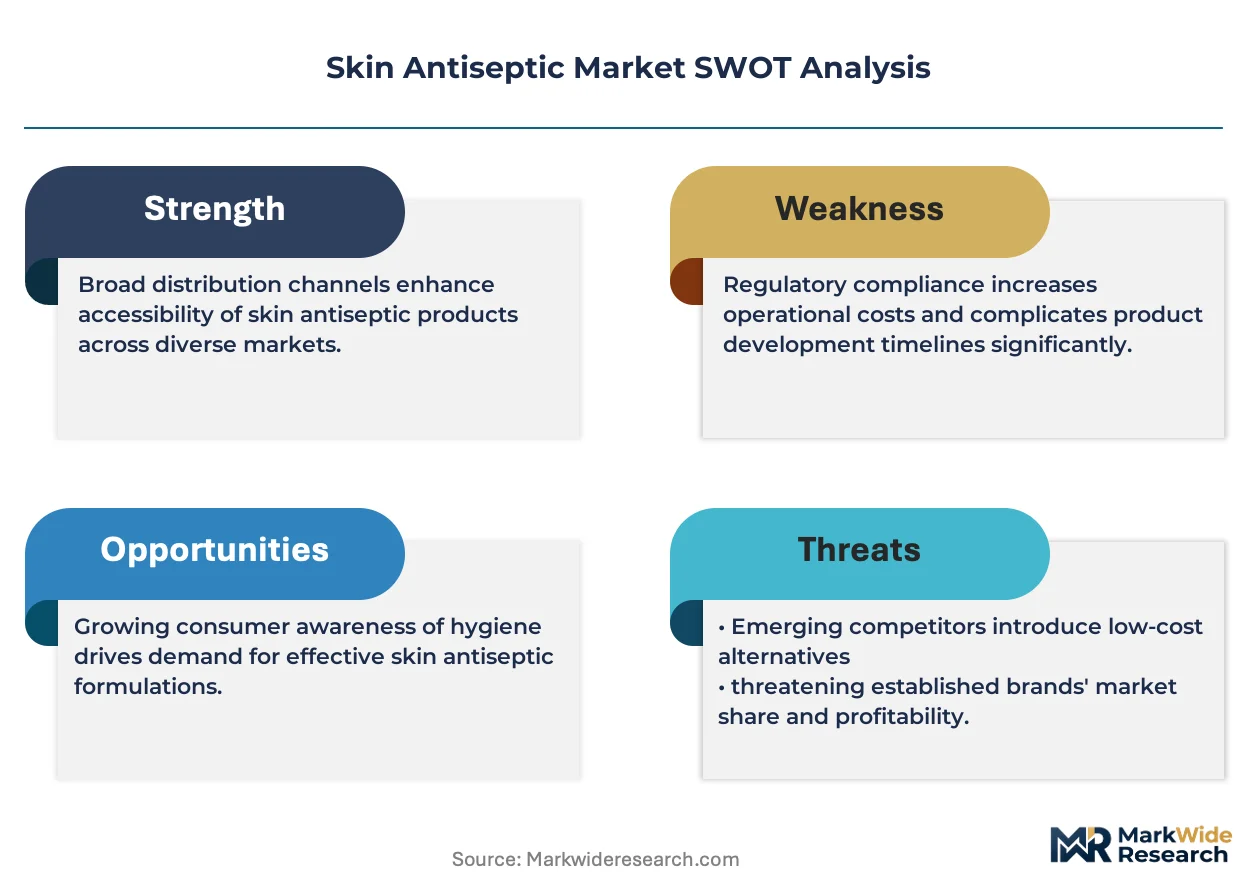
Asset-light leasing models for sterile preparation equipment are narrowing the capital barrier for mid-sized antiseptic suppliers. Johnson & Johnson leverages its hospital supply relationships to sustain contracted formulary positions. Becton, Dickinson and Company anchors its position through integrated delivery of applicators and prep solutions. Ecolab Inc. competes on the strength of its infection prevention service bundles tied to antiseptic consumption.
Skin antiseptics are topical antimicrobial formulations, typically containing chlorhexidine gluconate, povidone-iodine, or alcohol-based compounds, designed to reduce microbial load on intact skin prior to invasive procedures or wound management. These preparations function by disrupting microbial cell membranes or denaturing proteins, with efficacy measured by log reduction of colony-forming units within standardized contact times. Liquid antiseptics dominate hospital procurement due to lower per-unit cost and compatibility with institutional dispensing systems, while foam antiseptics capture preference in surgical settings where controlled coverage and reduced drip are valued. The wound care application segment shows structural momentum as home-based chronic wound management expands, though surgical applications retain the deepest margin pools through high-volume contracting.
FDA premarket notification requirements and EPA pesticide product registrations shape formulation standards and labeling claims for skin antiseptics in the United States, while ISO 10993 biocompatibility testing governs material safety for device-drug combination products. The European Medical Device Regulation and REACH chemical restrictions add compliance layers for suppliers serving multiple jurisdictions. Stakeholders must monitor evolving resistance surveillance data and regulatory guidance on persistent antimicrobial efficacy to align R&D portfolios with forthcoming standards.
Market Dynamics
FDA preoperative skin preparation guidance updates are compressing efficacy benchmarks for chlorhexidine and povidone-iodine formulations, forcing reformulation cycles across institutional suppliers while ambulatory surgical center expansion in the United States pulls volume toward outpatient protocols.
Growth Catalysts
- Regulatory tightening:FDA updates to preoperative skin preparation monographs are mandating higher log-reduction standards, pushing hospitals toward validated antiseptic systems.
- Outpatient migration:Ambulatory surgical centers in the United States are expanding procedural volume, creating concentrated demand for rapid-dry, single-use antiseptic applicators.
- Chronic wound protocols:Home-based wound management programs are incorporating sustained-release antiseptic dressings into standard care pathways.
Market Restraints
- Active ingredient concentration:Chlorhexidine gluconate supply from Indian pharmaceutical intermediate manufacturers faces periodic export restriction volatility.
- Biocompatibility testing burden:ISO 10993 cytotoxicity and sensitization studies for device-drug combinations extend product development timelines by 12-18 months.
- Alcohol-based substitution:Isopropyl alcohol swab protocols in low-acuity settings displace premium formulated antiseptics on cost grounds.
Strategic Opportunities
- Rural clinic penetration:Federally qualified health centers in the United States remain underpenetrated for preoperative skin preparation bundles.
- Combination device convergence:Antiseptic-impregnated surgical incise drapes pairing chlorhexidine with adhesive barrier technology open procedural integration channels.
- EPA green chemistry incentives:Safer Choice program recognition for reduced-residue formulations creates procurement preference in sustainability-mandated hospital systems.
Industry Challenges
- Microbiology validation capacity:Contract laboratories capable of ASTM E1173 surgical hand scrub testing face booking backlogs that delay product launches.
- Legacy dispensing system integration:Wall-mounted surgical scrub stations in older hospital infrastructure require adapter hardware for next-generation foam delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Antiseptic Market |
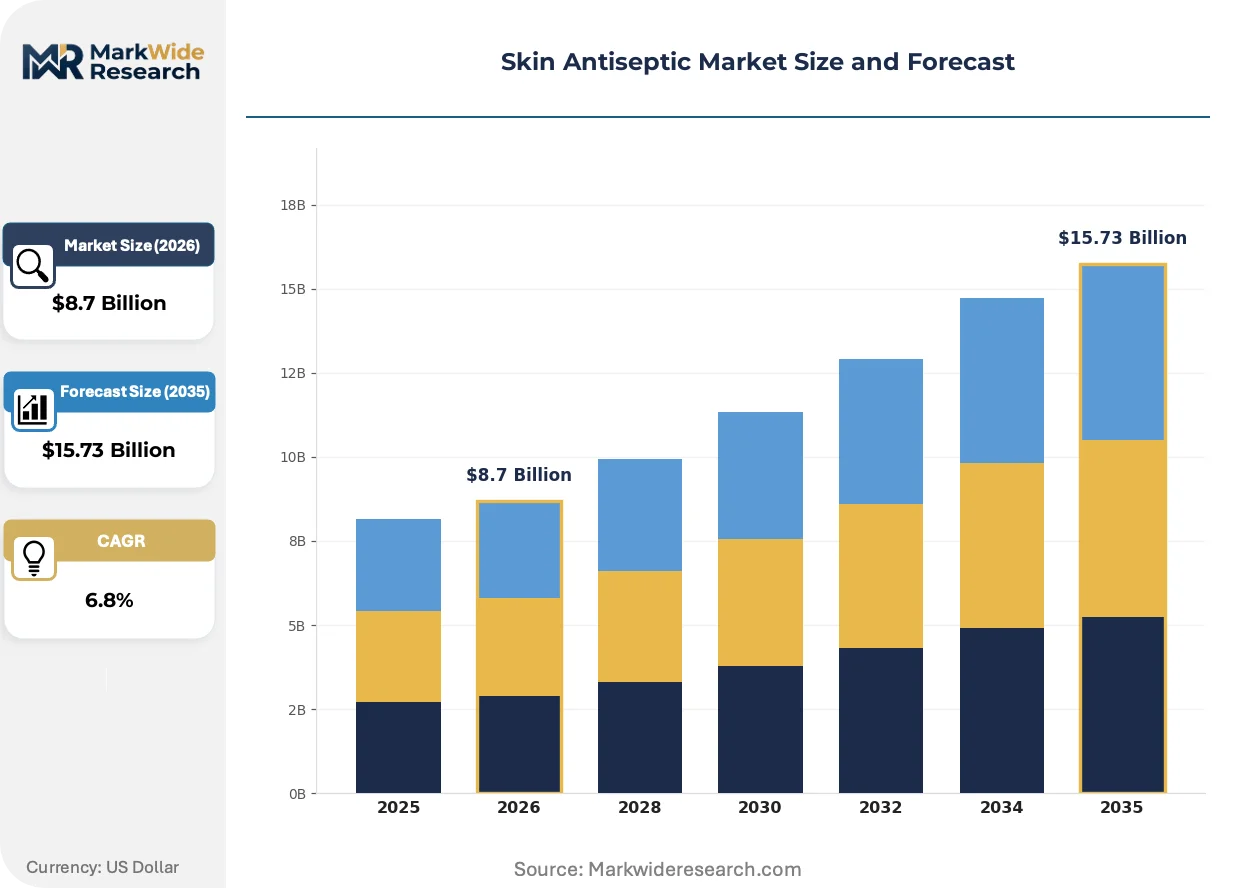
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Antiseptics, Gel Antiseptics, Spray Antiseptics, Foam Antiseptics Application: Surgical, Post-Surgical, Wound Care, Daily Hygiene End User: Hospitals, Clinics, Home Care, Laboratories Distribution Channel: Online Retail, Pharmacies, Hospital Supply, Supermarkets |
| Companies Covered | Becton, Dickinson and Company, Ecolab Inc., Johnson & Johnson, Solventum, B. Braun Melsungen AG, Schülke & Mayr GmbH, 3M Company, Cardinal Health Inc., Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Antiseptic Market Evolving Landscape
Formulation chemistry and application mechanics are diverging as manufacturers pursue persistent antimicrobial efficacy without compromising skin integrity, while regulatory agencies tighten post-market surveillance for resistance development.
Chlorhexidine-alcohol combinations are migrating from surgical hand preparation into preoperative patient skin preparation protocols. Academic medical centers in the United States are adopting these formulations for orthopedic and cardiac procedures where Staphylococcus aureus colonization reduction is critical. The shift is compressing market share for traditional povidone-iodine scrubs in high-acuity settings.
EPA pesticide product registration requirements for antimicrobial claims are expanding data submission obligations for persistent efficacy labeling. Manufacturers must now generate 6-hour and 24-hour residual kill data to support "continued antimicrobial activity" claims. Surgical antiseptic suppliers serving the United States market are restructuring regulatory affairs teams to manage dual FDA-EPA compliance pathways.
Hospital purchasing cooperatives are consolidating antiseptic procurement into standardized formulary contracts that bundle skin preparation with hand hygiene and environmental disinfection. Group purchasing organizations are displacing individual hospital negotiations, compressing supplier margins while locking in multi-year volume commitments. This concentration is most visible in the United States, where ten major health systems control approximately forty percent of inpatient surgical volume.
Skin Antiseptic Market Segmentation
Antiseptic procurement patterns diverge sharply across clinical settings, with hospital formulary committees, retail pharmacy buyers, and direct-to-consumer channels each imposing distinct performance and packaging requirements. Segmentation reveals where formulation chemistry, delivery mechanics, and regulatory compliance intersect with end-use economics.
Product Type:
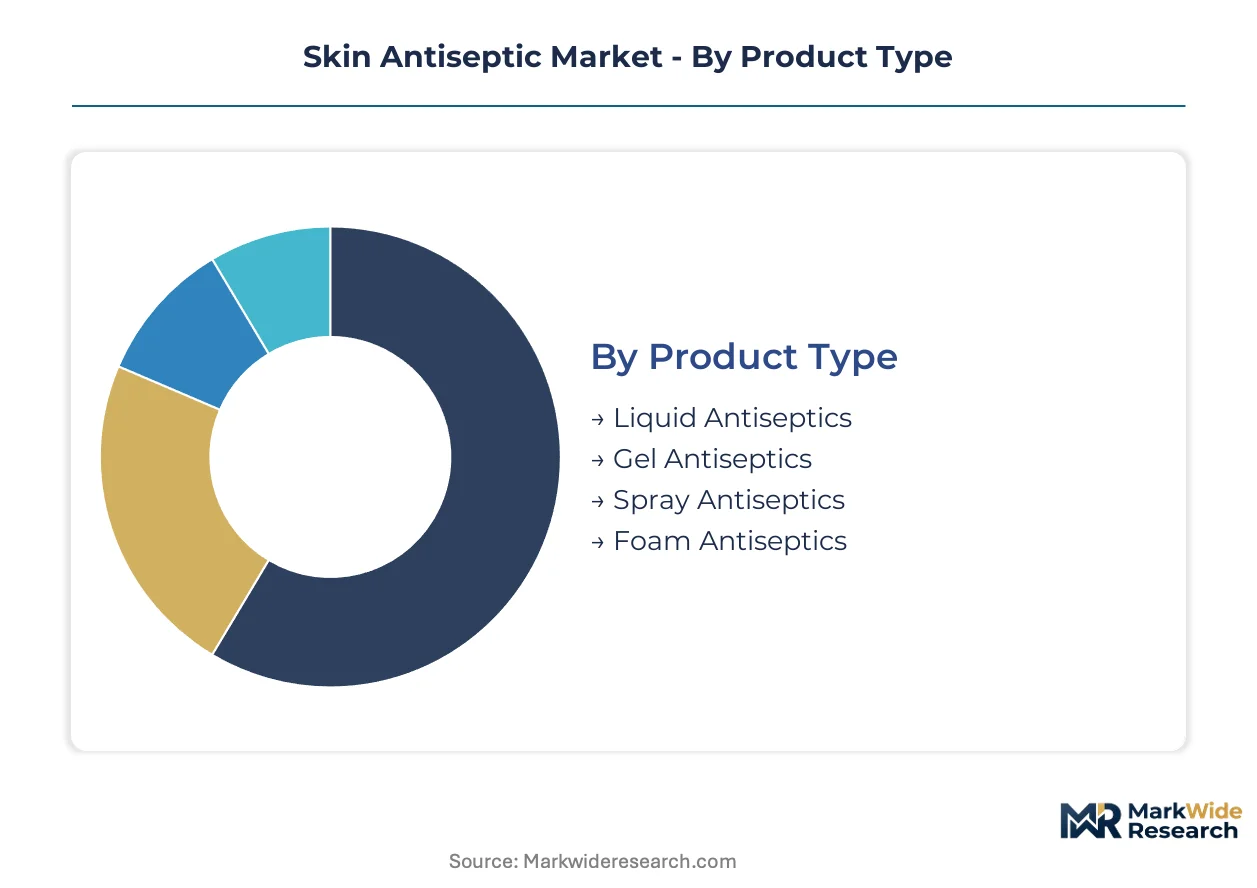
Liquid, gel, spray, and foam formats span a use-case spectrum from high-volume institutional dispensing to precision surgical application and portable consumer use.
- Liquid Antiseptics:Pourable aqueous or alcoholic solutions, typically chlorhexidine gluconate or povidone-iodine based, designed for compatibility with wall-mounted surgical scrub stations and bulk institutional dispensers. Demand concentrates in United States tertiary hospitals where formulary standardization favors lowest per-unit cost and seamless integration with existing infrastructure.
- Foam Antiseptics:Viscous aerated formulations delivered through pump or pressurized systems that cling to skin surfaces with reduced drip and controlled spread. Surgical suites in United States academic medical centers drive preference where orthopedic and cardiac protocols demand persistent antimicrobial efficacy without compromising sterile field integrity.
- Gel Antiseptics:Thickened aqueous or alcoholic preparations offering extended skin contact time and reduced runoff, commonly packaged in single-use sachets or tubes for procedure-specific application.
- Spray Antiseptics:Aerosol or pump-dispensed fine mists enabling rapid coverage of large surface areas, capturing demand in emergency medicine and field-based wound management where speed of application outweighs precision control.
The dominant share belongs to Liquid Antiseptics, while Foam Antiseptics is closing the gap fastest.
Application:
Clinical acuity and reimbursement environment shape antiseptic selection, with high-stakes surgical applications commanding premium formulations and home-based segments prioritizing convenience and cost.
- Surgical:Preoperative patient skin preparation and surgical hand scrub protocols requiring validated log-reduction performance against Staphylococcus aureus and other skin flora. United States ambulatory surgical centers are expanding procedural volume, pulling demand toward rapid-dry, single-use applicators that minimize turnover time between cases.
- Wound Care:Chronic wound management incorporating sustained-release antiseptic dressings and topical preparations for pressure ulcers, diabetic foot infections, and surgical site complications. Home-based care programs in the United States are integrating these products into standard pathways as hospital-at-home reimbursement expands.
- Post-Surgical:Incision site maintenance and suture line antisepsis during recovery phases, typically transitioning from institutional to outpatient or home settings.
- Daily Hygiene:Consumer-grade hand and body antisepsis for general infection prevention, competing with standard soap and alcohol-based hand rubs on price and perceived necessity.
Surgical applications command the deepest margin pools through high-volume contracting, while Wound Care is expanding most quickly as chronic disease prevalence rises and care migrates to residential settings.
End User:
Purchasing authority and reimbursement structure fragment demand across institutional procurement committees, individual clinicians, and direct consumer decision-making.
- Hospitals:Integrated health systems and standalone facilities with centralized pharmacy and materials management functions negotiating multi-year formulary contracts. Group purchasing organizations in the United States are consolidating antiseptic procurement into bundled contracts spanning skin preparation, hand hygiene, and environmental disinfection.
- Home Care:Patients and informal caregivers managing chronic wounds or post-surgical recovery outside institutional settings, purchasing through retail pharmacies, online channels, and durable medical equipment suppliers.
- Clinics:Federally qualified health centers, urgent care facilities, and specialty outpatient practices with limited procurement staff and price-sensitive purchasing patterns.
- Laboratories:Research and diagnostic facilities requiring antiseptic protocols for personnel protection and specimen handling containment.
Hospitals retain the largest volume concentration, while Home Care is gaining share fastest as reimbursement shifts and patient preference drive care site migration.
Distribution Channel:
Channel economics and customer access requirements determine packaging specifications, minimum order quantities, and technical support intensity.
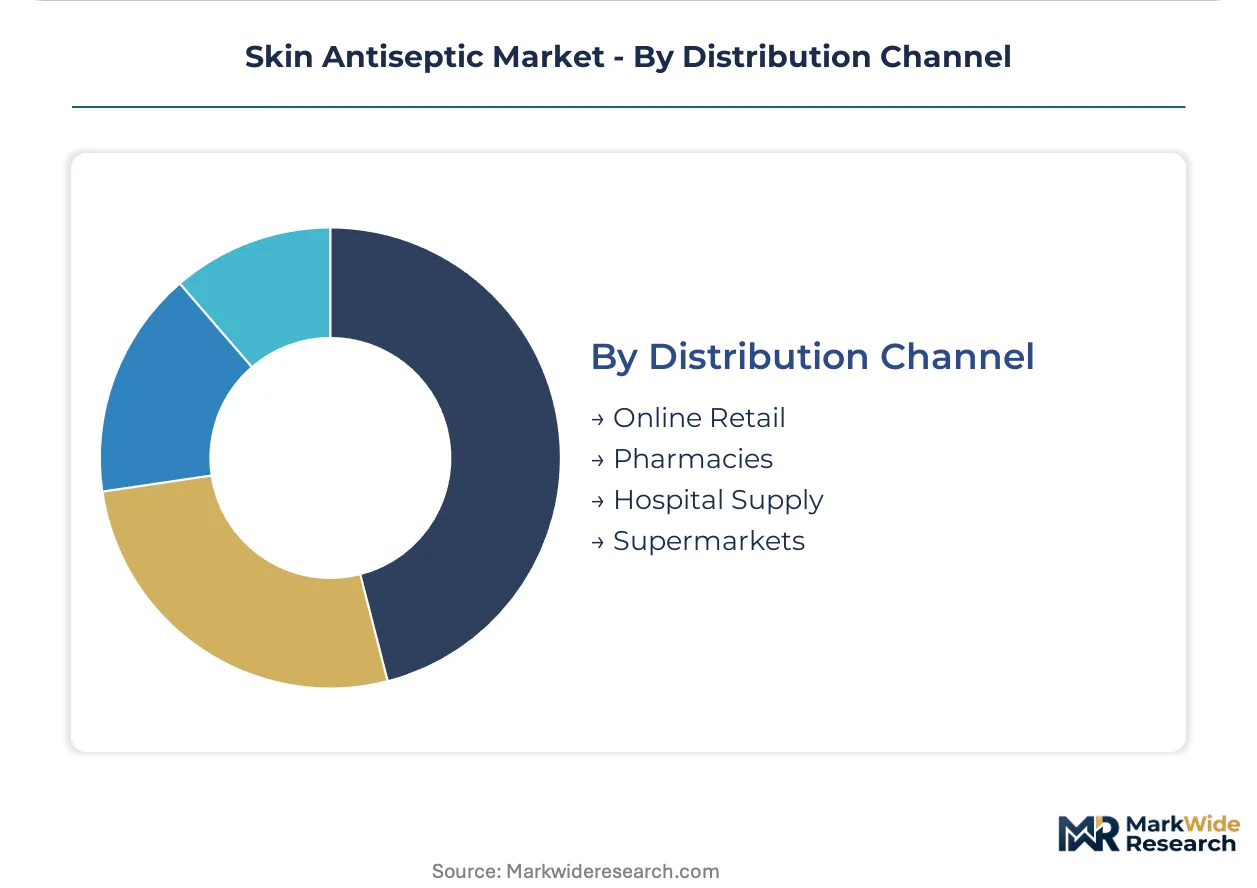
- Hospital Supply:Direct distribution through specialized medical-surgical distributors and manufacturer sales representatives serving institutional procurement committees with just-in-time delivery and formulary compliance documentation.
- Pharmacies:Retail and outpatient pharmacy chains stocking consumer and professional-grade antiseptics for prescription and over-the-counter purchase.
- Online Retail:E-commerce platforms enabling direct-to-consumer and direct-to-clinic purchasing with expanded product selection and competitive pricing transparency.
- Supermarkets:Mass-market retail channels carrying limited SKUs of consumer antiseptic products competing primarily on price and brand recognition.
Hospital Supply channels capture the dominant institutional volume, while Online Retail is climbing the fastest as procurement digitization accelerates across clinic and home care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA preoperative skin preparation guidance updates and EPA pesticide registration requirements are tightening efficacy benchmarks across major markets, while ambulatory surgical center expansion and chronic wound management programs reshape demand geography.
United States
Ambulatory surgical centers in Texas and Florida are expanding procedural volume, pulling antiseptic demand toward rapid-dry applicators. FDA premarket notification requirements for device-drug combinations extend development timelines for suppliers entering the market. The Greater Boston cluster anchors academic medical center adoption of chlorhexidine-alcohol protocols for orthopedic procedures.
Germany
University hospitals in Baden-Württemberg and Bavaria are standardizing preoperative skin preparation bundles across integrated delivery networks. The European Medical Device Regulation and REACH chemical restrictions add compliance layers for formulation suppliers. The Rhine-Main metropolitan region concentrates manufacturing of surgical antiseptic delivery systems.
China
Class III hospital expansion in the Yangtze River Delta and Pearl River Delta is driving procurement of institutional antiseptic dispensers. NMPA medical device registration requirements for combination products are elevating documentation standards. Shanghai-based distributors are consolidating procurement for provincial hospital networks.
Japan
Metropolitan Tokyo hospitals are adopting persistent antimicrobial protocols for cardiac surgery preparation. PMDA quality management system audits for device-drug combinations enforce rigorous manufacturing documentation. The Osaka-Kobe industrial corridor hosts specialized contract manufacturers for antiseptic-impregnated surgical products.
India
Medical tourism hubs in Maharashtra and Karnataka are upgrading surgical suite antiseptic protocols to international accreditation standards. CDSCO medical device rules for notified categories are formalizing import and manufacturing requirements. Hyderabad's pharmaceutical intermediate manufacturers supply chlorhexidine gluconate active ingredients to global formulation houses.
Skin Antiseptic Market Competitive Landscape
Channel-controlling players compete with product-specialist players for formulary positioning in consolidated procurement environments. Hospital supply relationships and infection prevention service bundles determine contract retention. Three archetypes dominate: diversified medical device conglomerates with surgical suite integration capabilities, infection control specialists with service-based differentiation, and pharmaceutical-distribution hybrids with formulary access. Competitive moves concentrate on strategic partnerships with group purchasing organizations and portfolio diversification into combination device-drug products.
Within the diversified medical device tier, Becton, Dickinson and Company and Johnson & Johnson exemplify players leveraging hospital supply infrastructure for formulary anchoring. Ecolab Inc. occupies a distinct position as an infection prevention specialist competing through service-bundle integration. These three represent the dominant competitive archetypes shaping procurement dynamics in United States health systems.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Ecolab Inc. |
| Johnson & Johnson |
| Solventum |
| B. Braun Melsungen AG |
| Schülke & Mayr GmbH |
| 3M Company |
| Cardinal Health Inc. |
| Mölnlycke Health Care |
| Others |
Value Network & Pricing Analysis
Overcapacity in Indian chlorhexidine gluconate intermediate production is compressing raw material costs while simultaneously eroding supplier pricing power in downstream formulation markets. This utilization dynamic forces antiseptic manufacturers to choose between absorbing margin pressure or pursuing volume-based contracting to maintain hospital formulary positions.
Pricing Analysis
Certification level creates the primary spread across skin antiseptic tiers, with FDA 510(k)-cleared device-drug combinations commanding substantial premiums over EPA-registered pesticide products. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth, with academic medical centers least sensitive to price and federally qualified health centers most constrained. Cost compression in the standard tier is intensifying because group purchasing organizations are consolidating procurement into multi-year bundled contracts spanning skin preparation, hand hygiene, and environmental disinfection.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk planning for chlorhexidine gluconate sourcing. Active ingredient production concentrates in India, China, and Germany, with formulation and packaging distributed across regional manufacturing hubs. Supply chains draw from pharmaceutical intermediate suppliers, specialty chemical manufacturers, and medical device converters, with single-source vulnerability in ASTM E1173 testing laboratory capacity creating qualification bottlenecks. Distribution runs through specialized medical-surgical distributors serving institutional procurement committees with just-in-time delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skin antiseptic market is recovering from a cyclical trough driven by deferred hospital capital expenditure programs during reimbursement uncertainty. Surgical procedure volume normalization and ambulatory surgical center expansion are restoring demand momentum across institutional channels.
For Market Incumbents: Pre-empt formulary displacement by accelerating chlorhexidine-alcohol combination product registrations ahead of FDA guidance tightening. Backward integration into active ingredient sourcing from Indian pharmaceutical intermediate manufacturers reduces supply volatility exposure. Capacity addition in Texas and Florida ambulatory surgical center corridors captures outpatient migration volume. Certification investment in dual FDA-EPA compliance pathways defends against emerging entrants lacking regulatory affairs scale. For New Entrants and Emerging Players: Rural clinic penetration in the United States represents the most accessible white-space target, with federally qualified health centers remaining underpenetrated for preoperative skin preparation bundles. EPA Safer Choice program recognition for reduced-residue formulations opens procurement preference in sustainability-mandated hospital systems. A direct-to-clinic online retail go-to-market angle bypasses established distributor relationships that incumbents control. For Investors and Strategic Acquirers: Capital is best deployed toward infection prevention service-bundle specialists with embedded antiseptic consumption contracts. The five-to-ten year viability window favors platforms integrating formulation supply with applicator device manufacturing and clinical training services. Watch for inflection signals in group purchasing organization contract renewal cycles, where incumbent lock-in periods create acquisition timing windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Device-Drug Combination | Accelerates access to academic medical center formulary committees requiring validated persistent efficacy claims. |
| EPA Safer Choice Certification | Unlocks procurement preference in health systems with sustainability mandates and green chemistry incentives. |
| Group Purchasing Organization Partnership | Secures multi-year volume commitments across integrated delivery networks consolidating antiseptic procurement. |
| Backward Integration into Active Ingredient Supply | Reduces exposure to Indian export restriction volatility and chlorhexidine gluconate price swings. |
| Antiseptic-Impregnated Surgical Incise Drape Launch | Captures procedural integration channels in orthopedic and cardiac surgery suites seeking barrier-adhesive combinations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA pesticide product registrations, hospital procurement databases, and group purchasing organization contract disclosures. The research program combined structured interviews with hospital pharmacy directors, infection prevention officers, biomedical engineers, and GPO contracts managers with bottom-up and top-down triangulation across institutional dispensing data and manufacturer shipment records.
Forecast inputs include surgical procedure volume trajectories, ambulatory surgical center expansion rates, chronic wound prevalence trends, and regulatory guidance evolution across the analysis window. The analytical framework models demand by product type, application, end user, and distribution channel, with CAGRs derived from log-linear trend fitting adjusted for formulary contract cycle timing. Industry-specific forecast inputs incorporate FDA preoperative skin preparation monograph update schedules and EPA residual efficacy data submission requirements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medical device conglomerates or private equity-backed platform consolidators would shift outcomes through accelerated M&A or pricing repositioning. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Personalized Skin Care Products Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Preoperative Skin Preparation Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Tinted Sunscreen Market
Skincare
Incontinence Skin Care Products Market
Skincare
Skincare Serums Market
Skincare
Ampoule Cream Market
Skincare
Anti-Aging Services Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
CBD Skin Care Market
Skincare
Sensitive Skin Care Products Market
Skincare
Encapsulated Retinol Market