
 Golf Irrigation Market | 2026-2036
Golf Irrigation Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Irrigation Market Foresight
Multi-source component procurement is consolidating as manufacturers reduce supplier fragmentation across valve, sensor, and controller categories. Toro Company leverages its vertically integrated controller manufacturing to sustain margin stability across North American distribution. Hunter Industries anchors its position through deep R&D intensity in rotor engineering, while Rain Bird competes aggressively on smart controller interoperability with third-party soil sensors.
Golf irrigation encompasses engineered water delivery systems designed to distribute treated or reclaimed water across turfgrass playing surfaces at specified flow rates, pressures, and uniformity coefficients to maintain consistent agronomic conditions. These systems integrate underground PVC or HDPE distribution networks with pop-up rotary sprinklers, drip emitters for native landscape buffers, and centralized control architectures to optimize water application efficiency across variable terrain and microclimates. Sprinkler systems dominate installed base value due to decades of proven performance on fairways and greens, though sensor technologies represent the fastest-expanding margin pool as superintendents adopt soil moisture probes and weather stations to reduce consumptive water use. Smart irrigation within the technology dimension is displacing conventional timer-based architectures as capital investment shifts toward cloud-connected, evapotranspiration-driven scheduling platforms.
EPA WaterSense specifications and state-level turf irrigation ordinances in California, Texas, and Florida shape product certification requirements and limit market access for non-compliant equipment. The Federal Inflation Reduction Act extends tax incentives toward water-efficient infrastructure retrofits, redirecting municipal facility budgets toward certified system overhauls. Stakeholders must monitor evolving groundwater withdrawal permits and reclaimed water quality standards as these regulatory instruments increasingly determine total cost of ownership calculations and replacement cycle timing.
Market Dynamics
Water scarcity stress across the southwestern United States is accelerating capital replacement cycles as superintendents face tightening groundwater withdrawal permits and escalating reclaimed water tariffs. EPA WaterSense certification tightening and state-level turf irrigation ordinances in California, Texas, and Florida are compressing product eligibility windows and redirecting procurement toward compliant system architectures.
Growth Catalysts
- EPA WaterSense Certification Mandates:Federal procurement eligibility restrictions are forcing municipal golf facilities toward certified controller and sensor retrofits, expanding addressable market for compliant equipment manufacturers.
- Reclaimed Water Infrastructure Expansion:Arizona and California utilities are extending purple pipe networks to golf clusters, reducing freshwater dependency and enabling system upgrades compatible with lower-quality water chemistries.
- Soil Sensor Proliferation:Capacitance-based moisture probes and weather station integration are reducing consumptive water use by fifteen to thirty percent on retrofitted courses, generating measurable operational savings that justify capital expenditure.
Market Restraints
- Copper and PVC Resin Volatility:Distribution network materials face input cost swings tied to construction sector demand cycles, compressing margin stability for system integrators locked into fixed-price municipal contracts.
- Controller Chip Supply Concentration:Semiconductor fabrication for irrigation-specific microcontrollers concentrates in Taiwan and South Korea, exposing lead time vulnerability for North American controller assembly operations.
- Legacy Timer Architecture Persistence:Decades-old electromechanical controllers remain operational on budget-constrained municipal courses, delaying smart system adoption despite measurable efficiency gains.
Strategic Opportunities
- Desert Southwest Expansion:Nevada and New Mexico golf developments are greenfielding smart irrigation from inception, bypassing retrofit friction and establishing reference architectures for water-stressed regions.
- Federal Inflation Reduction Act Incentives:Tax credits for water-efficient infrastructure retrofits are unlocking municipal capital pools previously allocated to deferred maintenance categories.
- Cloud-Evapotranspiration Convergence:Satellite weather data integration with mobile superintendent platforms is enabling real-time scheduling adjustments that were previously impossible with standalone controller architectures.
Industry Challenges
- Certification Timeline Compression:EPA WaterSense protocol updates are accelerating retesting requirements, forcing manufacturers to maintain parallel development tracks for pending and certified product lines.
- Turfgrass-Agronomy Skill Shortage:Superintendents capable of interpreting soil sensor telemetry and calibrating ET-based scheduling algorithms remain scarce, limiting realized efficiency gains from installed smart systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Irrigation Market |
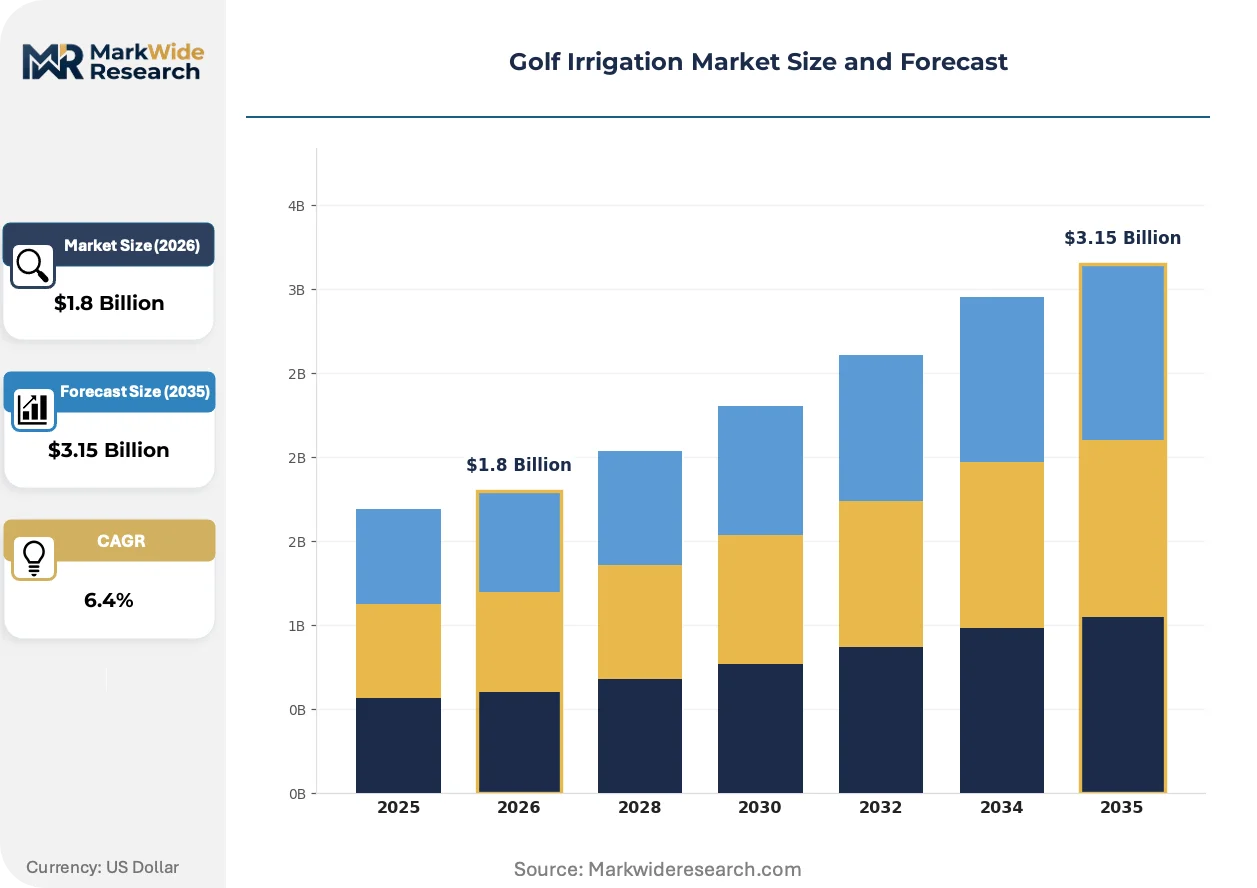
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprinkler Systems, Drip Irrigation, Sensor Technologies, Control Systems Technology: Smart Irrigation, Conventional Irrigation, Rainwater Harvesting, Automated Systems End User: Private Courses, Public Courses, Municipal Facilities, Golf Resorts Deployment: On-site Installation, Remote Monitoring, Maintenance Services, Upgrades |
| Companies Covered | Nelson Irrigation Corporation, Seeger Water, Rain Bird, Precision Golf Irrigation, Falco Lawn Sprinklers, Hunter Industries, ISCO Industries, Mid-America Golf and Landscape, Toro Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Irrigation Market Shifts & Advancements
Smart irrigation architectures are displacing conventional timer-based systems as capital flows toward cloud-connected platforms with evapotranspiration-driven scheduling. Three developments are compressing replacement cycles and reshaping competitive positioning.
Variable frequency drive pump controllers are converging with pressure-compensating valve networks to enable dynamic flow management across undulating terrain. Arizona resort operators are deploying these integrated systems to eliminate hydraulic zoning inefficiencies that wasted water on downhill slopes. The technology is converging with soil moisture feedback loops to create closed-loop irrigation that adjusts in real-time to rootzone conditions rather than calendar schedules.
California's Senate Bill 606 and Assembly Bill 1668 impose per-capita water use efficiency targets that cascade to golf course operating permits through urban water supplier mandates. These statutes are compelling superintendents to document consumptive use reductions through certified flow metering and reporting infrastructure. Florida courses are preemptively adopting equivalent monitoring architectures to withstand anticipated ordinance convergence.
Superintendent purchasing committees are consolidating vendor relationships to reduce system integration complexity, favoring manufacturers offering controller-sensor-valve bundled architectures over best-of-breed component sourcing. Arizona and California golf resorts are driving this pattern as they face compressed installation windows during shoulder seasons. The shift is most visible in metropolitan Phoenix and Palm Springs clusters where water district rebate programs require single-source warranty coverage.
Golf Irrigation Market Segmentation
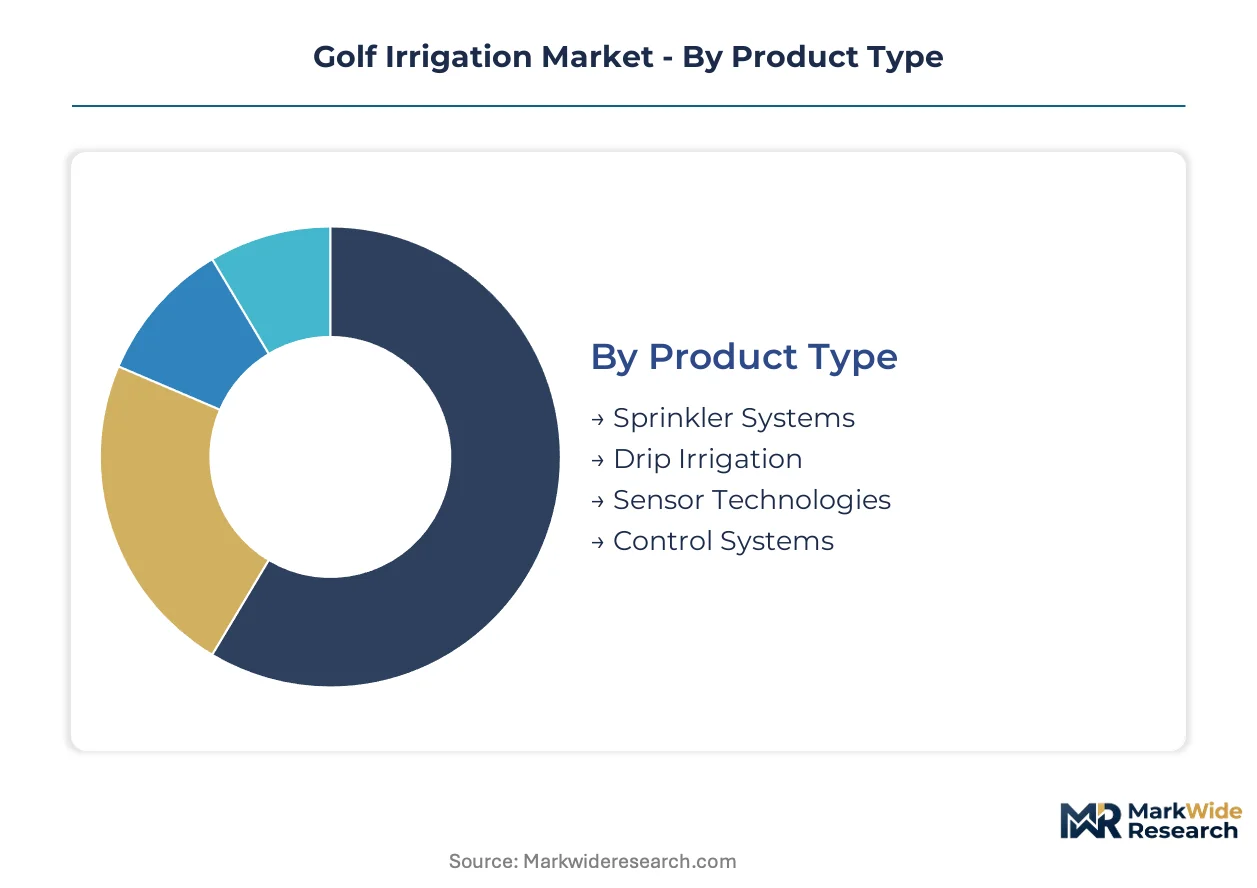
Golf irrigation procurement decisions cascade through multiple technical and operational dimensions. Equipment buyers weigh product durability against controller sophistication, while deployment choices determine long-term operational flexibility and vendor lock-in exposure.
Product Type:
Replacement cycles across product categories diverge sharply based on underground infrastructure longevity versus above-ground electronics obsolescence.
- Sprinkler Systems:Underground PVC and HDPE distribution networks paired with pop-up rotary sprinklers deliver specified flow rates and uniformity coefficients across fairways and greens. Arizona and California golf resorts prioritize brass-body rotor heads for reclaimed water compatibility as purple pipe networks expand.
- Sensor Technologies:Capacitance-based soil moisture probes and weather station arrays generate real-time telemetry for evapotranspiration-driven scheduling. Florida superintendents deploy these most aggressively to document consumptive use reductions ahead of anticipated ordinance tightening.
- Drip Irrigation:Pressure-compensating emitters serve native landscape buffers and out-of-play areas with lower uniformity requirements than turfgrass surfaces.
- Control Systems:Centralized architectures coordinate valve operation across hydraulic zones, with cloud-connected platforms displacing standalone timer boxes.
Sprinkler Systems sit at the top of the volume ranking, with Sensor Technologies climbing the fastest.
Technology:
Capital allocation patterns reveal superintendent risk tolerance for unproven architectures versus proven reliability.
- Smart Irrigation:Cloud-connected platforms integrate satellite weather data, soil moisture feedback, and mobile superintendent interfaces for real-time scheduling adjustments. Nevada and New Mexico greenfield developments deploy these from inception, bypassing retrofit friction entirely.
- Conventional Irrigation:Electromechanical timer boxes and standalone controllers persist on budget-constrained municipal courses where capital replacement cycles stretch across decades.
- Automated Systems:Programmable logic controllers manage pump stations and valve networks with minimal human intervention.
- Rainwater Harvesting:Collection and storage infrastructure reduces freshwater dependency on courses with adequate catchment area and storage capacity.
Smart Irrigation commands the highest capital allocation per installed acre, while Automated Systems deliver the most predictable operational expenditure profile.
End User:
Facility ownership structure shapes procurement authority, budget flexibility, and compliance urgency.
- Golf Resorts:Integrated hospitality operations combine irrigation investment with guest experience and water district rebate capture. Palm Springs and metropolitan Phoenix clusters drive bundled controller-sensor-valve procurement to satisfy single-source warranty requirements.
- Municipal Facilities:City-owned courses face compressed procurement windows tied to fiscal year cycles and federal WaterSense certification mandates for equipment eligibility.
- Private Courses:Member-governed boards approve capital projects through committee structures with variable agronomic expertise.
- Public Courses:Daily-fee operations balance water cost exposure against green fee pricing power in competitive local markets.
Golf Resorts lead absolute spending per facility, with Municipal Facilities expanding most quickly under IRA tax credit access.
Deployment:
Service revenue attachment rates vary by customer sophistication and internal maintenance capability.
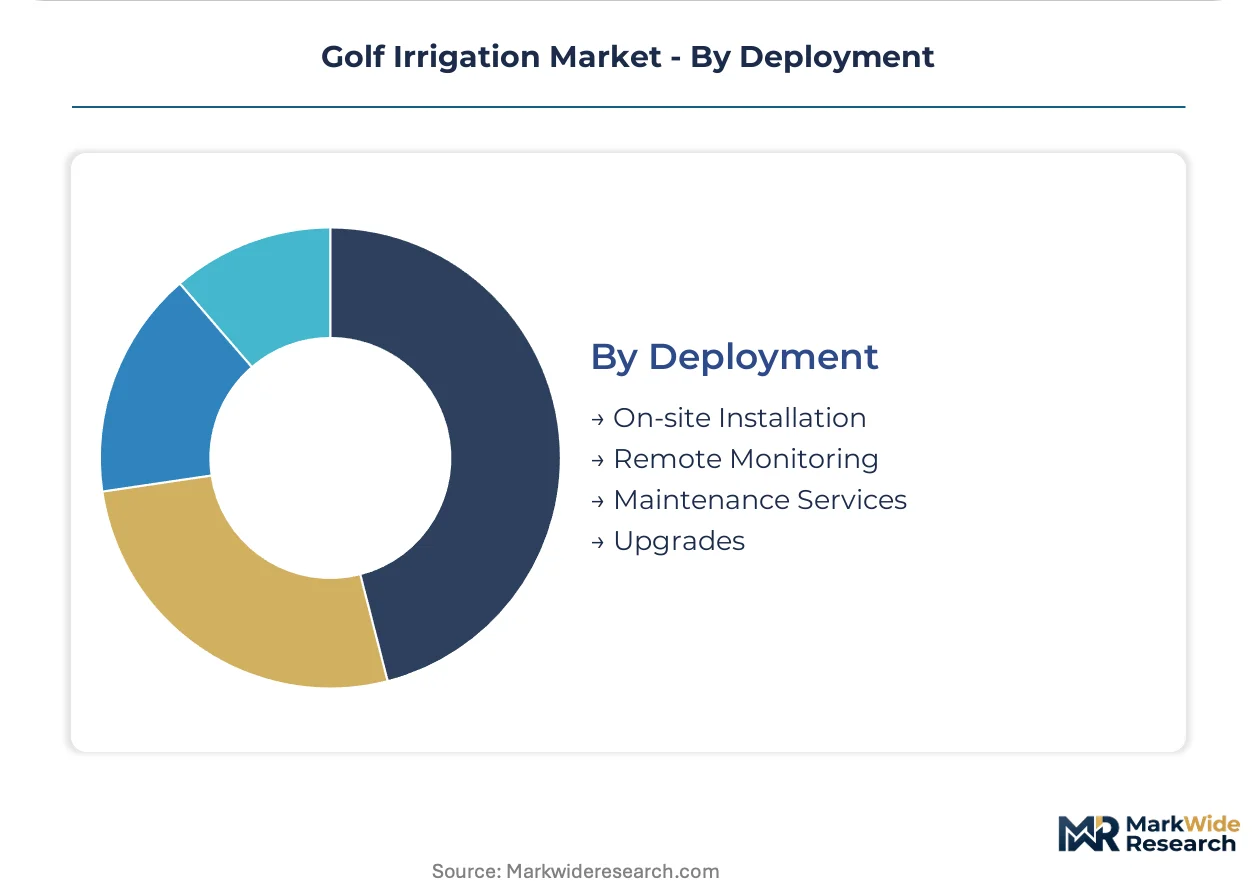
- On-site Installation:Trenching, pipe fusion, and sprinkler head placement require specialized equipment and seasonal scheduling around playing schedules.
- Remote Monitoring:Vendor-managed telemetry review and alert response reduces superintendent labor burden on technology-intensive architectures.
- Upgrades:Controller retrofits and sensor additions extend functional life of distribution infrastructure without full system replacement.
- Maintenance Services:Annual inspection, winterization, and component replacement contracts preserve warranty coverage and operational reliability.
On-site Installation anchors vendor revenue, with Remote Monitoring gaining share fastest as cloud platform adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Phoenix anchors worldwide golf irrigation demand as water stress intersects with high course density across the southwestern United States. The analysis spans five countries where climate pressure and course infrastructure create concentrated procurement activity.
United States
California and Arizona golf resorts drive system modernization as groundwater withdrawal permits tighten. EPA WaterSense certification mandates redirect municipal facility budgets toward compliant controller retrofits. Palm Springs and Scottsdale clusters deploy bundled controller-sensor-valve architectures to capture water district rebates.
Australia
Drought-prone courses across Victoria and New South Wales prioritize soil moisture probe integration to document consumptive use reductions. The country's national water regulator enforces Murray-Darling Basin extraction limits that cascade to golf operating permits. Melbourne metropolitan courses anchor smart system adoption through state-funded efficiency programs.
Spain
Andalusia and Valencia golf developments confront summer irrigation restrictions under national drought contingency protocols. The country's environmental ministry tightens reclaimed water quality standards for turfgrass application. Costa del Sol resorts invest in pressure-compensating valve networks to maintain uniformity across undulating terrain.
United Arab Emirates
Dubai and Abu Dhabi golf estates face escalating desalinated water tariffs that justify capital-intensive smart system deployment. The federal environment agency mandates flow metering infrastructure for all commercial turfgrass operations. Emirates Golf Club and surrounding developments establish reference architectures for closed-loop irrigation in arid climates.
Japan
Kanto region courses modernize aging timer-based systems ahead of anticipated municipal water use ordinances. METI efficiency standards for outdoor water equipment shape product eligibility for facility upgrades. Tokyo metropolitan clusters test satellite weather data integration to reduce consumptive use on high-value playing surfaces.
Golf Irrigation Market Competitive Landscape
Global majors compete with regional champions across controller manufacturing and distribution network integration. The vendor base concentrates around vertically integrated system architects and specialized component fabricators. Three archetypes dominate: full-stack irrigation platform providers, rotor engineering specialists, and regional installation-service integrators. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion through water-stressed golf clusters.
Among North American platform providers, Toro Company and Hunter Industries occupy positions as scale-driven full-stack architects. Rain Bird exemplifies the interoperability-focused tier through its controller compatibility emphasis. Nelson Irrigation Corporation represents the specialized component archetype with its engineering heritage in water application technology. These three anchors illustrate how competitive positioning diverges between bundled system warranty coverage and best-of-breed component sourcing strategies.
| Leading Market Players |
|---|
| Nelson Irrigation Corporation |
| Seeger Water |
| Rain Bird |
| Precision Golf Irrigation |
| Falco Lawn Sprinklers |
| Hunter Industries |
| ISCO Industries |
| Mid-America Golf and Landscape |
| Toro Company |
| Others |
Supply & Pricing Matrix
Copper and PVC resin volatility cascades through controller assembly operations into tiered pricing structures that separate WaterSense-certified architectures from legacy timer-based alternatives. Arizona golf resorts absorb premium positioning for brass-body rotor heads compatible with reclaimed water chemistries, while municipal facilities in California face compressed procurement windows that amplify price sensitivity for bundled system architectures.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication concentrates pricing pressure on smart controller tiers as Taiwan and South Korean chip supply tightens. Three-tier pricing structure across premium, standard, and economy levels differentiates by EPA WaterSense certification status and after-sales remote monitoring bundling. Cost compression in municipal contract tiers is intensifying because fixed-price agreements lock integrators into PVC resin and copper swings. Golf resorts demonstrate least price sensitivity due to water district rebate capture, while public daily-fee operations exhibit highest elasticity.
Supply Chain Analysis
Controller chip supply rests on Taiwanese and South Korean semiconductor fabricators, exposing North American assembly operations to lead time vulnerability. Brass alloy for reclaimed-water-compatible rotors draws from foundry capacity in China and India, while PVC resin feeds from petrochemical complexes along the US Gulf Coast. Single-source vulnerability concentrates in microcontroller sourcing for cloud-connected platforms. Distribution runs through manufacturer-direct channels for resort clusters and irrigation-specialist distributors serving municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA WaterSense protocol updates compound demand for certified retrofits, creating sustained procurement urgency across municipal golf facilities subject to federal equipment eligibility mandates.
For Market Incumbents: Lock in controller-sensor-valve bundled architectures to capture superintendent purchasing committee consolidation. Deepen backward integration into semiconductor sourcing to mitigate Taiwan fabrication concentration risk. Prioritize certification investment for parallel development tracks as EPA retesting requirements accelerate. For New Entrants and Emerging Players: Launch via remote monitoring service overlays atop existing distribution infrastructure to bypass capital-intensive manufacturing scale requirements. Target Nevada and New Mexico greenfield developments where smart irrigation deploys from inception without retrofit friction. Emphasize cloud-evapotranspiration convergence as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where regional installation-service integrators lack captive controller manufacturing capability. Five-to-ten-year viability favors full-stack platform providers with WaterSense-certified product depth over component specialists. Acquisition target archetype: mid-scale rotor engineering houses with R&D intensity in pressure-compensating valve networks. Watch soil sensor telemetry interpretation skill scarcity as the inflection indicator for realized efficiency gains.| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Certification Investment | Unlocks federal procurement eligibility for municipal facility retrofits under tightening mandates. |
| Backward Integration into Semiconductor Sourcing | Reduces lead time exposure from Taiwan and South Korean fabrication concentration. |
| Remote Monitoring Service Launch | Captures recurring revenue attachment as cloud platform adoption accelerates across resort clusters. |
| Brass Alloy Rotor Capacity Expansion | Positions for reclaimed water compatibility as purple pipe networks extend in Arizona and California. |
| Soil Sensor Telemetry Platform Integration | Addresses superintendent skill scarcity through automated evapotranspiration-driven scheduling algorithms. |
Research Methodology
Bottom-up golf course deployment modeling reconciled against top-down irrigation equipment manufacturing tracking forms the analytical core of this study. Primary interviews with golf course superintendents, municipal procurement officers, irrigation system integrators, and water district rebate program administrators combined with secondary validation from EPA WaterSense certification databases, state-level turf irrigation ordinance filings, and customs records for PVC resin and brass alloy imports. Triangulation between facility-level capital expenditure patterns and component manufacturer shipment data ensures coherence across volume estimates.
Historical replacement cycle analysis across timer-based and smart controller installed bases informs the projection framework throughout the forecast period. Segmentation dimensions span product type, technology tier, end-user ownership structure, and deployment service attachment. CAGRs derive from fitted trendlines adjusted for regulatory milestone impacts including IRA tax credit phase-ins and anticipated state ordinance convergences. Industry-specific forecast inputs incorporate superintendent purchasing committee consolidation patterns and water district rebate program eligibility requirements.
Several conditions sit outside the modeled scope, including extreme drought contingency declarations that trigger mandatory irrigation moratoria, and breakthrough desalination cost reductions that alter freshwater tariff structures. Forecasts reflect assumptions about regulatory timeline adherence and semiconductor supply normalization. A small set of named triggers warrants ongoing watch: EPA WaterSense protocol update frequency, groundwater withdrawal permit tightening velocity in California and Arizona, and reclaimed water quality standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market