
 Hops Market | 2026-2036
Hops Market Size, Share, and Industry Trends Forecast 2026-2036
Hops Market Analysis
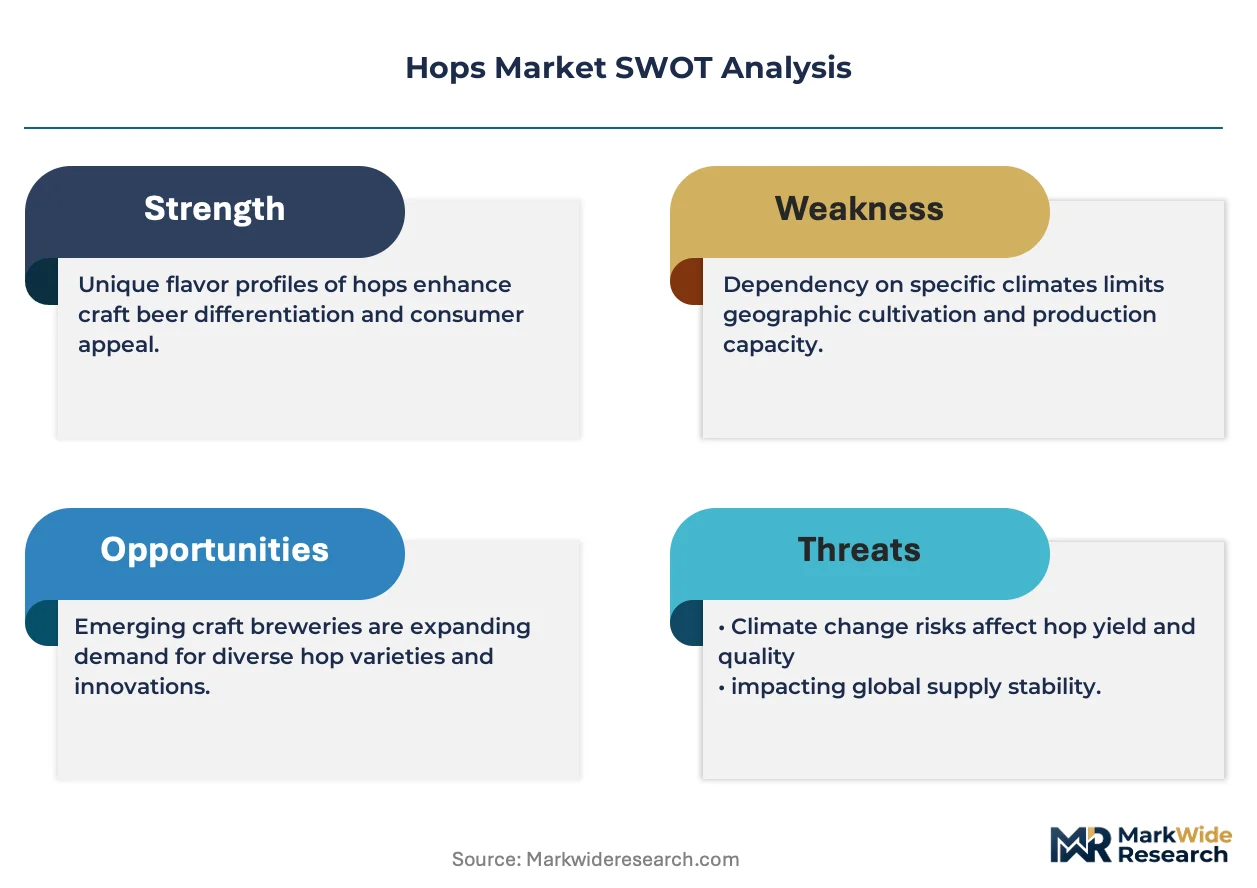
Buyer consolidation among multinational beverage conglomerates is repositioning contract structures toward longer-term supply agreements with preferred growers. Yakima Chief Hops leverages its cooperative ownership model to secure acreage commitments across Washington and Idaho. BarthHaas anchors European supply through integrated breeding programs in Germany and the Czech Republic. Hopsteiner competes on proprietary cultivar development, releasing disease-resistant strains that reduce pesticide dependency.
Hops are the female flower cones of Humulus lupulus, containing alpha acids that provide beer bitterness and essential oils that contribute aroma profiles; harvest timing, kiln drying temperature, and pelletization density determine final brewing performance. Hop pellets dominate commercial brewing for their storage stability and consistent utilization rates, while hop extracts concentrate alpha acids for large-scale lager production. Whole hops retain niche demand among craft brewers seeking dry-hop aroma intensity, and liquid hop formats are gaining traction in automated brewhouse systems.
FDA oversight of hop-derived food ingredients and EPA pesticide residue limits for agricultural chemicals shape cultivation compliance costs for United States growers. EU Green Deal targets and REACH chemical registration requirements influence European processing standards and export eligibility. Stakeholders must monitor water-rights adjudication in the Pacific Northwest and climate-adaptation breeding timelines as aridity pressures intensify across traditional growing zones.
Market Dynamics
Contract consolidation among multinational brewers is compressing supplier margins and extending payment terms across the Pacific Northwest growing belt. This buyer-side concentration is forcing growers to secure acreage commitments two to three harvest cycles in advance.
Growth Catalysts
- EU Green Deal agricultural standards:Sustainability-linked premiums for certified organic hops are redirecting European cultivation investment toward integrated pest management and soil conservation protocols.
- Craft brewing proliferation:Small-batch producers in the United States and Germany are diversifying aroma variety portfolios beyond traditional bittering strains.
- Climate-adaptive breeding:Disease-resistant cultivars with reduced water requirements are expanding viable growing territory into higher-elevation zones previously considered marginal.
Market Restraints
- Input cost volatility:Fertilizer and diesel price swings compress grower margins during seasons with adverse flowering conditions.
- Geographic supply concentration:The Yakima Valley's dominance creates systemic risk from single-region weather events or water-rights adjudication.
- Substitution pressure:Hop extracts and synthetic bittering agents threaten whole-flower and pellet demand in mass-market lager production.
Strategic Opportunities
- Emerging craft markets:Brazil and Mexico present underdeveloped demand for specialty aroma varieties as local brewing cultures mature.
- Liquid hop formats:Automated brewhouse integration is creating a new equipment-consumables bundled channel.
- Carbon certification premiums:Voluntary carbon accounting frameworks are enabling price differentiation for low-emission kiln-drying operations.
Industry Challenges
- Multi-year contract rigidity:Fixed-price agreements expose growers to cost inflation across the three-year cultivation cycle.
- Processing capacity bottlenecks:Pellet mill throughput constraints create harvest-period queuing and quality degradation risks.
- Phytosanitary compliance fragmentation:Divergent pesticide residue limits between FDA, EFSA, and importing nations multiply testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hops Market |
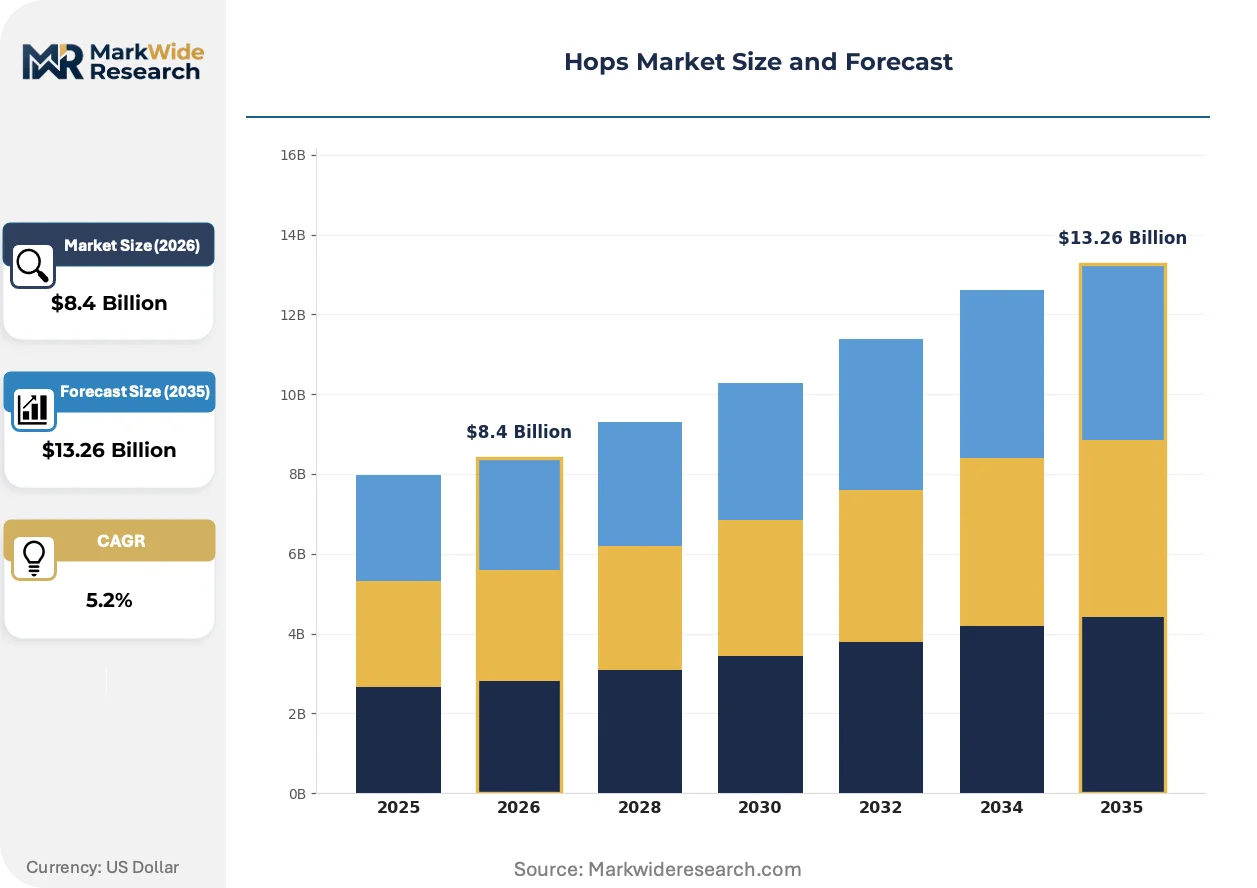
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Hops, Hop Pellets, Hop Extracts, Liquid Hops Application: Brewing, Food Flavoring, Nutraceuticals, Cosmetics End User: Brewery, Beverage Producers, Pharmaceuticals, Cosmetics Manufacturers Distribution Channel: Online Sales, Retail Stores, B2B Suppliers, Direct Sales |
| Companies Covered | John I. Haas, Crosby Hop Farm, Yakima Chief Hops, Haas Hops, Steiner Hops, Hopsteiner, Hops Direct, Glacier Hops Ranch, BarthHaas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hops Market Emerging Trajectories
Digital agriculture platforms and precision irrigation systems are recalibrating yield optimization across traditional growing regions. These technologies are compressing the information asymmetry between field operations and contract buyers.
Advanced kiln telemetry with real-time moisture monitoring is overtaking conventional static drying schedules. Craft breweries with quality-assurance laboratories are adopting these systems to secure lot-specific alpha acid consistency. The technology is overtaking legacy sensory evaluation as the primary arbitration mechanism in premium contract negotiations.
EPA pesticide re-registration timelines are extending active-ingredient availability windows for hop-specific chemistries. This regulatory friction is accelerating biological control agent adoption among Washington State growers. The EFSA parallel review process is creating divergent compliance catalogs for European and American export lots.
Direct contracting between growers and regional craft breweries is displacing merchant intermediaries in specialty aroma procurement. Small-scale brewers in Oregon and Bavaria are establishing multi-year relationships with named farms for single-origin releases. This channel shift is most visible in the India Pale Ale segment, where provenance marketing commands measurable price premiums.
Hops Market Segmentation
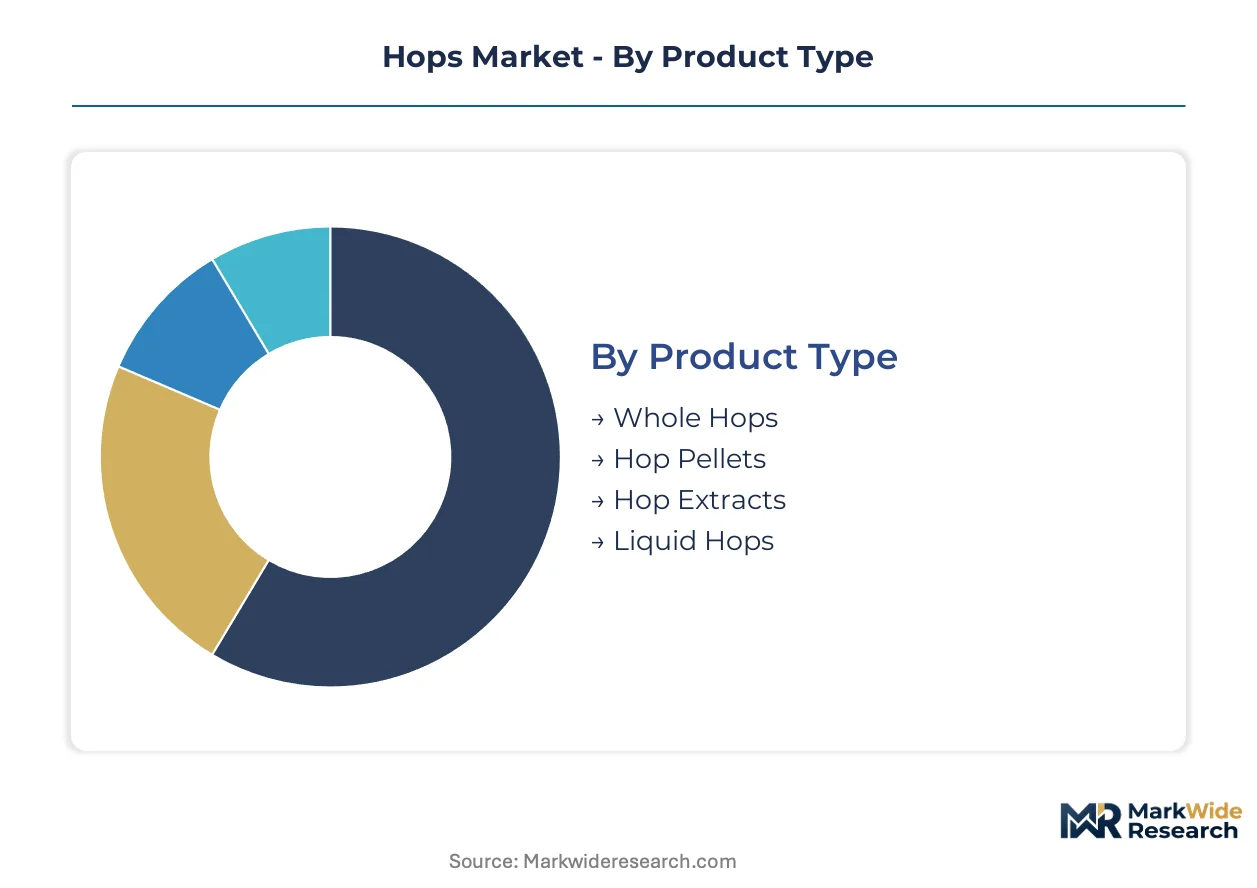
Hop format selection determines supply chain configuration, storage requirements, and brewing protocol compatibility. Procurement patterns diverge sharply between mass-market lager producers optimizing for alpha acid consistency and craft brewers prioritizing aromatic complexity.
Product Type:
Standalone formats dominate commodity procurement, while embedded systems integrate into automated brewhouse infrastructure.
- Hop Pellets:Compressed hop cones milled and extruded into standardized cylinders deliver consistent utilization rates and extended shelf stability. Demand concentrates among United States craft breweries and German export lager producers seeking reproducible bittering profiles; kiln-drying precision and pellet density specifications determine contract premiums.
- Whole Hops:Dried female flower cones retain volatile essential oils in intact lupulin glands for maximum dry-hop aroma intensity. Yakima Valley and Willamette Valley growers supply specialty lots to Oregon and Bavarian craft brewers marketing single-origin provenance; harvest timing and cold-chain logistics constrain viable shipping distances.
- Hop Extracts:Solvent or supercritical CO2 processing concentrates alpha acids and essential oils into standardized resin forms.
- Liquid Hops:Emulsified hop oil preparations enable automated dosing systems in high-throughput brewhouses.
Volume placements concentrate in Hop Pellets; the faster expansion belongs to Liquid Hops.
Application:
Primary brewing applications absorb the majority of alpha acid and essential oil volumes, while secondary uses extract specific bioactive compounds.
- Brewing:Bittering additions during wort boil and aroma additions during fermentation or conditioning define beer style parameters. United States India Pale Ale producers and German Pilsner breweries drive differentiated procurement—high-alpha bittering varieties versus noble aroma cultivars; water chemistry and malt bills dictate hop rate calculations.
- Food Flavoring:Hop extracts contribute bittering agents and natural preservatives to non-alcoholic beverages and savory formulations.
- Nutraceuticals:Xanthohumol and prenylflavonoid isolation targets dietary supplement applications.
- Cosmetics:Antioxidant and antimicrobial properties support skincare and haircare ingredient sourcing.
Revenue gravity sits with Brewing; Nutraceuticals is climbing the fastest.
End User:
Large-scale beverage conglomerates negotiate multi-year supply contracts, while fragmented craft producers purchase through merchant intermediaries or direct farm relationships.
- Brewery:Integrated brewing operations span multinational lager facilities to nanobatch craft producers. Germany and the United States host the densest concentration of procurement decision-makers; sustainability certification and carbon accounting increasingly influence supplier selection.
- Beverage Producers:Non-beer applications include hop waters, functional drinks, and hybrid fermented beverages.
- Pharmaceuticals:Standardized extracts supply clinical research and botanical drug development pipelines.
- Cosmetics Manufacturers:Natural ingredient formulators source hop-derived antioxidants for clean-label positioning.
Contract values peak with Brewery procurement; Pharmaceuticals shows steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order scale, geographic proximity to growing regions, and inventory turnover requirements.
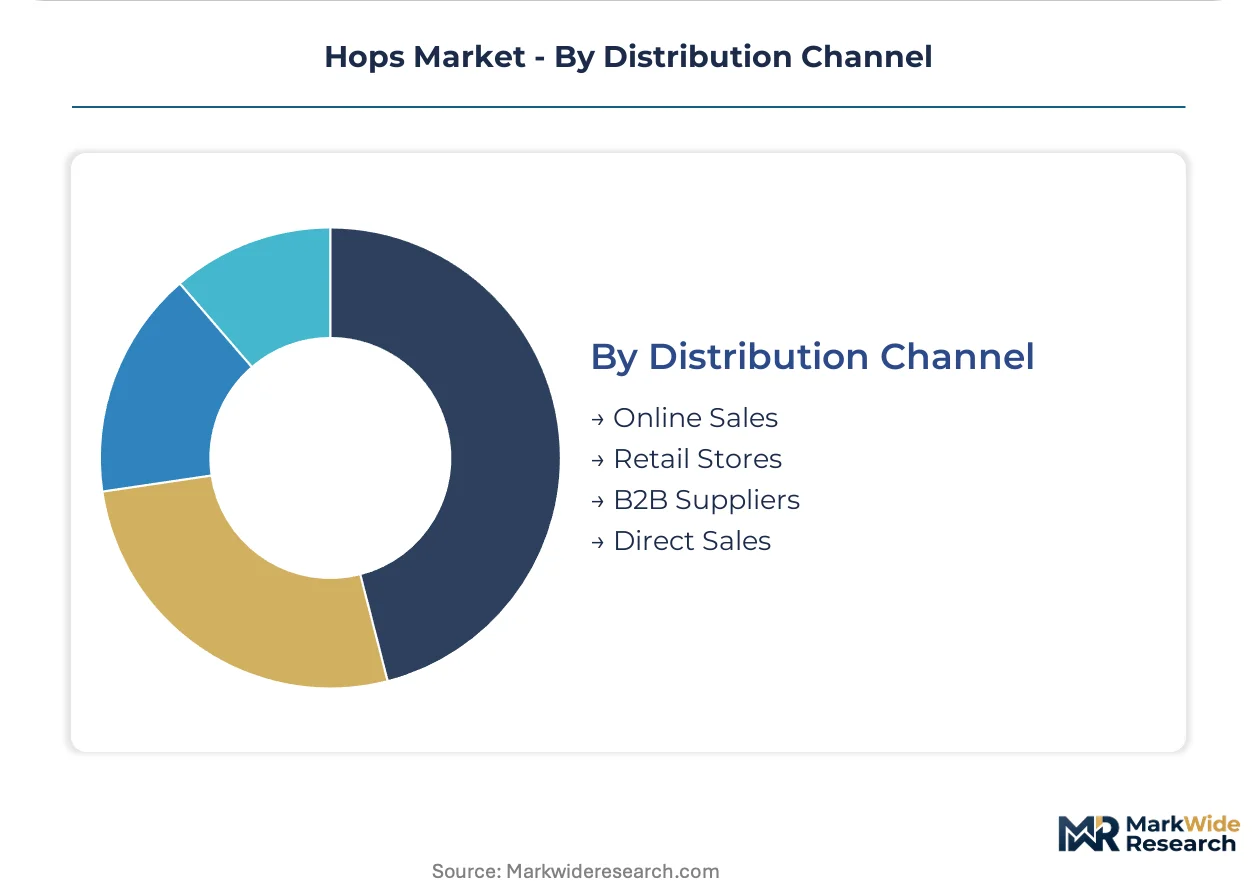
- B2B Suppliers:Merchant intermediaries aggregate volumes from multiple growing regions and provide quality assurance, financing, and logistics coordination. United States and German brewing clusters rely on established merchant networks; contract terms and lot traceability capabilities differentiate competitive positioning.
- Direct Sales:Named-farm relationships enable provenance marketing and variety exclusivity for limited releases.
- Online Sales:E-commerce platforms serve homebrewing enthusiasts and small-batch producers.
- Retail Stores:Physical distribution channels supply hobbyist and educational market segments.
Transaction volume concentrates through B2B Suppliers; Direct Sales gains share fastest among specialty aroma varieties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States craft breweries and German export lager producers concentrate hop procurement decisions in two distinct geographies. Yakima Valley growers supply alpha acid volumes for bittering applications. Hallertau and Tettnang cultivators preserve noble aroma variety heritage.
United States
Craft brewery proliferation in Oregon and Colorado drives specialty aroma variety demand. EPA pesticide residue limits and water-rights adjudication in Washington State reshape cultivation compliance costs. Yakima Valley and Willamette Valley growing clusters dominate global pellet and whole-flower export volumes.
Germany
Pilsner breweries and wheat beer producers sustain noble hop variety procurement. EU Green Deal agricultural standards redirect investment toward integrated pest management and soil conservation protocols. Hallertau, Tettnang, and Spalt growing regions anchor European aroma hop supply.
Czech Republic
Traditional Saaz variety cultivation supports Pilsner-style lager authenticity requirements. REACH chemical registration requirements influence processing standards for export eligibility. Žatec and Tršice growing zones maintain heritage cultivar germplasm banks.
Australia
Domestic craft brewing expansion and Asian export demand stimulate specialty variety trials. National chemical residue monitoring programs align with EFSA and FDA import thresholds. Tasmania's Derwent Valley hosts disease-free cultivation trials for Pacific Rim supply.
United Kingdom
Cask ale revival and India Pale Ale producers diversify heritage variety portfolios. Pesticide approval timelines under the national chemical regulator extend active-ingredient availability windows. Kent and Herefordshire growing counties supply traditional Fuggle and Golding varieties.
Hops Market Vendor Landscape
United States growers anchor one tier; German breeding specialists hold varietal heritage advantages. Supplier consolidation among multinational beverage conglomerates compresses margins and extends contract durations. Three archetypes dominate: cooperative-owned processors, integrated breeding-to-pellet operators, and proprietary cultivar developers. Competitive moves concentrate on multi-year acreage commitments and disease-resistant strain licensing.
Among United States-based processors, Yakima Chief Hops exemplifies cooperative ownership structures securing Washington and Idaho acreage. BarthHaas anchors European supply through integrated German and Czech breeding programs. Hopsteiner occupies a position within proprietary cultivar development, representing the disease-resistant strain segment that reduces pesticide dependency.
| Leading Market Players |
|---|
| John I. Haas |
| Crosby Hop Farm |
| Yakima Chief Hops |
| Haas Hops |
| Steiner Hops |
| Hopsteiner |
| Hops Direct |
| Glacier Hops Ranch |
| BarthHaas |
| Others |
Supply Flow & Price Mechanics
Kiln-drying energy costs cascade through hop contract structures, compressing margins for Washington State growers while concentrating pricing power among cooperative processors with captive pellet mill capacity. Alpha acid volatility and diesel-fueled logistics tether spot-market premiums to harvest-period fuel price swings across the Pacific Northwest.
Pricing Analysis
Volume placements concentrate in commodity-grade pellets where margins compress under multinational brewer consolidation, while specialty aroma varieties command sustainable premiums through provenance-linked contracts. Three-tier pricing structure across certified organic, conventionally grown, and extract-grade lots reflects EU Green Deal compliance costs and carbon certification investments. Pricing pressure stems from buyer-side contract consolidation extending payment terms to 90-120 days. Mass-market lager producers exhibit highest price sensitivity; single-origin craft buyers absorb premiums for named-farm traceability.
Supply Chain Analysis
Domestic-content requirements in Brazilian and Mexican brewing regulations are redirecting procurement toward hemisphere-sourced supply, reshaping traditional Pacific Northwest export flows. Raw material sourcing draws from Washington State and Idaho acreage for alpha acid volume, German Hallertau and Czech Saaz regions for noble aroma heritage, and Tasmanian trials for disease-free germplasm. Single-region concentration in Yakima Valley exposes global supply to Columbia River water-rights adjudication. Distribution runs through merchant intermediaries for multinational brewers and direct farm relationships for craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multinational brewer consolidation is compressing supplier margins and forcing merchant intermediaries and independent growers toward cooperative structures or exit. Buyer concentration now demands multi-year acreage commitments that weaker capitalized players cannot fulfill.
For Market Incumbents: Anticipate EPA pesticide re-registration delays by accelerating biological control agent adoption and securing integrated pest management certifications ahead of EU Green Deal alignment requirements. Deepen backward integration into precision kiln telemetry to capture carbon certification premiums and defend contract positions against disease-resistant cultivar licensors.
For New Entrants and Emerging Players: Regional craft breweries in Brazil and Mexico seeking specialty aroma variety provenance represent the most penetrable buyer archetype, underserved by incumbent merchant networks optimized for volume logistics. Target direct contracting relationships with named-farm marketing angles and liquid hop format bundling for automated brewhouse integration.
For Investors and Strategic Acquirers: Cooperative ownership conversions among distressed Washington State growers is the leading indicator that consolidation momentum will accelerate through the projection horizon. Position for acquisition of pellet mill capacity with cold-chain logistics assets and existing organic certification infrastructure; monitor water-rights adjudication rulings as inflection triggers for regional supply disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Cultivar Licensing | Disease-resistant strains reduce EPA compliance costs for Washington State growers. |
| Carbon Certification Investment | Low-emission kiln operations capture EU Green Deal-linked price premiums. |
| Liquid Hop Format Development | Automated dosing systems penetrate high-throughput brewhouse equipment channels. |
| Direct Farm Contracting | Named-farm relationships displace merchant intermediaries in IPA segment procurement. |
| Geographic Diversification | Tasmanian disease-free trials expand viable growing territory for Pacific Rim supply. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hop breeding program directors, craft brewery procurement managers, cooperative processing executives, and agricultural extension specialists. USDA National Agricultural Statistics Service acreage reports, BarthHaas crop surveys, EPA pesticide registration databases, and EU EFSA residue monitoring protocols provided cultivation and compliance benchmarks. Bottom-up variety-level volume estimates triangulated against top-down regional production aggregates.
Segmentation dimensions were modeled at product type granularity (pellets, whole hops, extracts, liquid formats), application tier (brewing, food flavoring, nutraceuticals, cosmetics), and end-user scale (multinational lager facilities versus nanobatch craft producers). CAGRs were derived from trend extrapolation of contract volume commitments and acreage expansion trajectories across the analysis window, incorporating climate-adaptive breeding timelines and water-rights adjudication scenarios as scenario-weighted inputs.
Revisions become necessary when EPA pesticide re-registration timelines extend beyond modeled windows, EFSA residue thresholds diverge from FDA limits creating export lot ineligibility, or Columbia River basin water-rights rulings restrict irrigation access. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mastic Gum Market
Ingredients
Mustard Oil Market
Ingredients
Egg Free Premix Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
North America Potato Protein Market
Ingredients
Specialty Malt Market
Ingredients
US Plant-Based Oils Market
Ingredients
Fermentation Ingredient Market
Ingredients
Lentils Flour Market
Ingredients
Africa Fats and Oil Market
Ingredients
Tomato Concentrate Market
Ingredients
Konjac Root Fiber Market
Ingredients
Beef Concentrate Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
China Corn Glucose Market
Ingredients
Oyster Shell Powder Market