
 Egg Free Premix Market | 2026-2036
Egg Free Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Free Premix Market Foresight
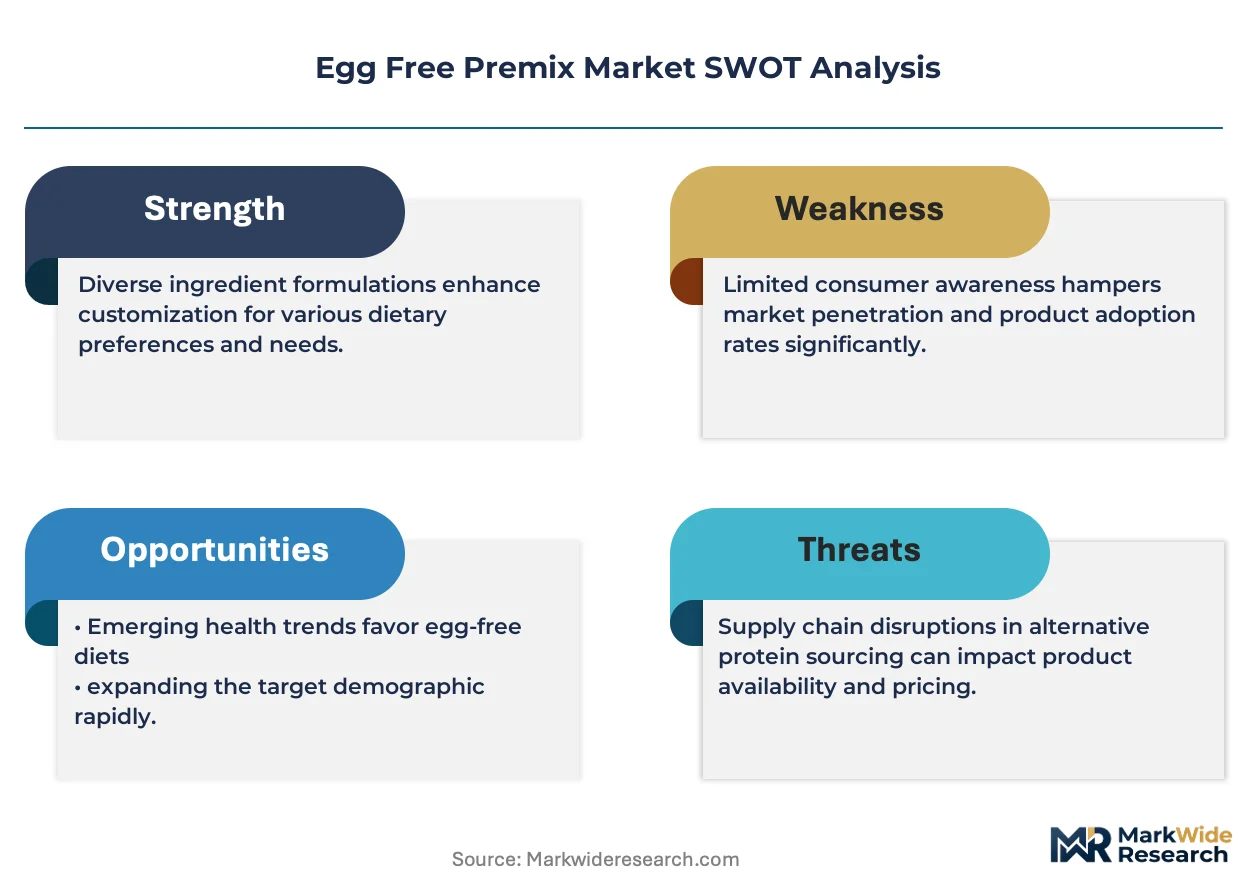
REACH compliance is pivoting the egg free premix sector toward cleaner-label ingredient sourcing. DeutscheBack leverages its Central European manufacturing footprint to supply industrial bakeries with certified clean-label concentrates. Orgran Natural Foods sustains competitive positioning through dedicated allergen-free production lines. Zion International Food anchors its presence in Middle Eastern markets through halal-certified powder formulations.
An egg free premix is a pre-blended combination of plant-based binders, emulsifiers, leavening agents, and stabilizers engineered to replicate the structural and functional properties of egg in baked goods and prepared foods, typically containing proteins from legumes, starches, or hydrocolloids at precise hydration ratios. Powder Mix dominates commercial procurement due to extended shelf stability and freight efficiency, while Liquid Concentrate captures premium positioning in food service channels requiring batch consistency. Snack Production represents the fastest-growing application segment as extruded and coated products shift away from egg-based wash systems.
The FDA's Food Safety Modernization Act and EFSA allergen labeling directives shape product development timelines and cross-border market access for reformulated premixes. India's FSSAI and China's SAMR impose divergent additive approval pathways that fragment formulation standardization. Stakeholders must monitor evolving national allergen thresholds and clean-label certification schemes to preempt compliance-driven reformulation cycles.
Market Dynamics
REACH compliance deadlines and the EU F-Gas Regulation are forcing commercial bakeries across Europe to abandon conventional egg-reliant formulations and source certified clean-label alternatives, compressing reformulation timelines from years to months.
Growth Catalysts
- Regulatory Pressure:The EU F-Gas Regulation and REACH compliance requirements in Europe mandate phase-out of certain processing aids, accelerating bakery sector migration toward plant-based binding systems.
- Industrial Baking Concentration:Germany's baking clusters around Munich and Hamburg are driving bulk procurement of egg-free concentrates as centralized production facilities seek supply chain simplification.
- Clean-Label Certification:Allergen-free production line investments by specialty ingredient processors are expanding certified capacity to meet food service channel specifications.
Market Restraints
- Input Cost Volatility:Legume protein and hydrocolloid prices fluctuate with agricultural yield cycles, squeezing margin stability for premix formulators.
- Technical Limitations:Current plant-based emulsifiers struggle to replicate egg yolk's heat-stable foam structure in high-sugar applications like meringues and angel food cakes.
- Regulatory Fragmentation:India's FSSAI and China's SAMR maintain divergent additive approval pathways, preventing standardized global formulations.
Strategic Opportunities
- Snack Production Pivot:Extruded and coated snack manufacturers are abandoning egg-based wash systems, opening volume demand for functional powder concentrates.
- Halal Certification Channel:Middle Eastern markets require halal-certified powder formulations, creating premium positioning for suppliers with dedicated production lines.
- Liquid Concentrate Food Service:Batch-consistent liquid formats are capturing institutional bakery and restaurant chain procurement previously locked into shell egg supply contracts.
Industry Challenges
- Formulation Expertise Gap:Industrial bakeries lack in-house knowledge of hydration ratios for legume protein and starch blends, requiring intensive technical support from premix suppliers.
- Cross-Border Compliance Timelines:EFSA allergen labeling directives and FDA Food Safety Modernization Act requirements impose divergent documentation burdens that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Free Premix Market |
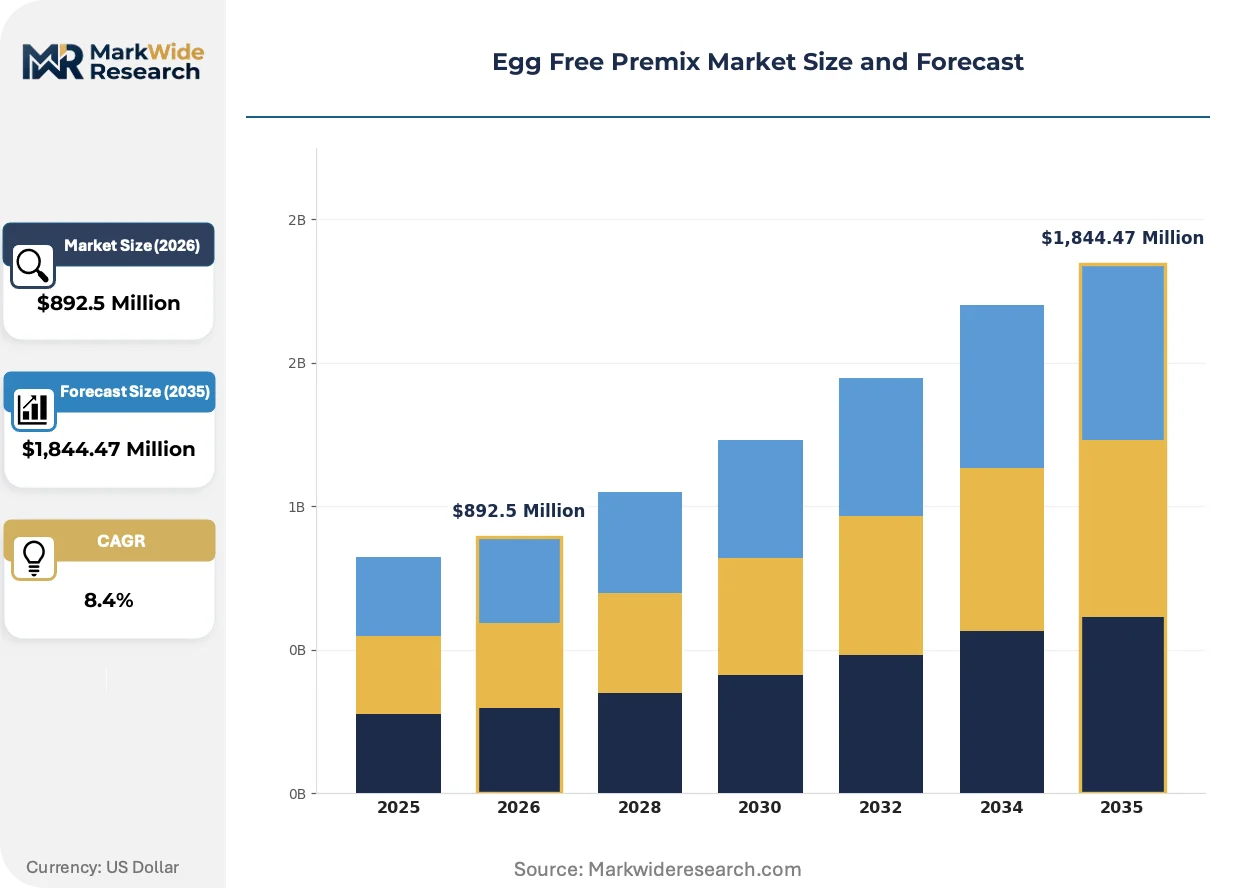
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,844.47 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Mix, Liquid Concentrate, Dough Mix, Batter Mix Application: Baking, Cooking, Food Service, Snack Production Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Restaurants, Bakeries, Home Cooks |
| Companies Covered | Bakenxt, Bakersville, Blue Bird Foods, Davars, Skyline Food Products, Zion International Food, Swissbake, DeutscheBack, Orgran Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Free Premix Market Shifts & Advancements
Precision fermentation-derived proteins and advanced hydrocolloid blending systems are rewriting the functional performance benchmarks for egg replacement, while regulatory convergence around clean-label standards compresses formulation disclosure requirements.
Fava bean and chickpea protein isolates are rewriting the structural integrity standards for egg-free baked goods. Artisan and industrial bakeries in Germany and France are adopting these concentrates at accelerating rates. The technology is rewriting the cost-performance tradeoff that previously favored conventional eggs in high-volume applications.
REACH authorization timelines and the EU Green Deal's chemical hazard classification protocols are tightening scrutiny on residual processing aids in plant-based ingredients. Formulators must now document supply chain absence of SVHCs across all raw material tiers. Powder premix categories face the steepest compliance burden due to their multi-ingredient composition.
Food service distributors are consolidating supplier relationships around single-source clean-label premix providers capable of batch-level allergen documentation. Institutional bakery chains in the United States and United Kingdom are disintermediating traditional ingredient brokers. This consolidation is most visible in contract manufacturing agreements where liability transfer demands end-to-end formulation transparency.
Egg Free Premix Market Segmentation
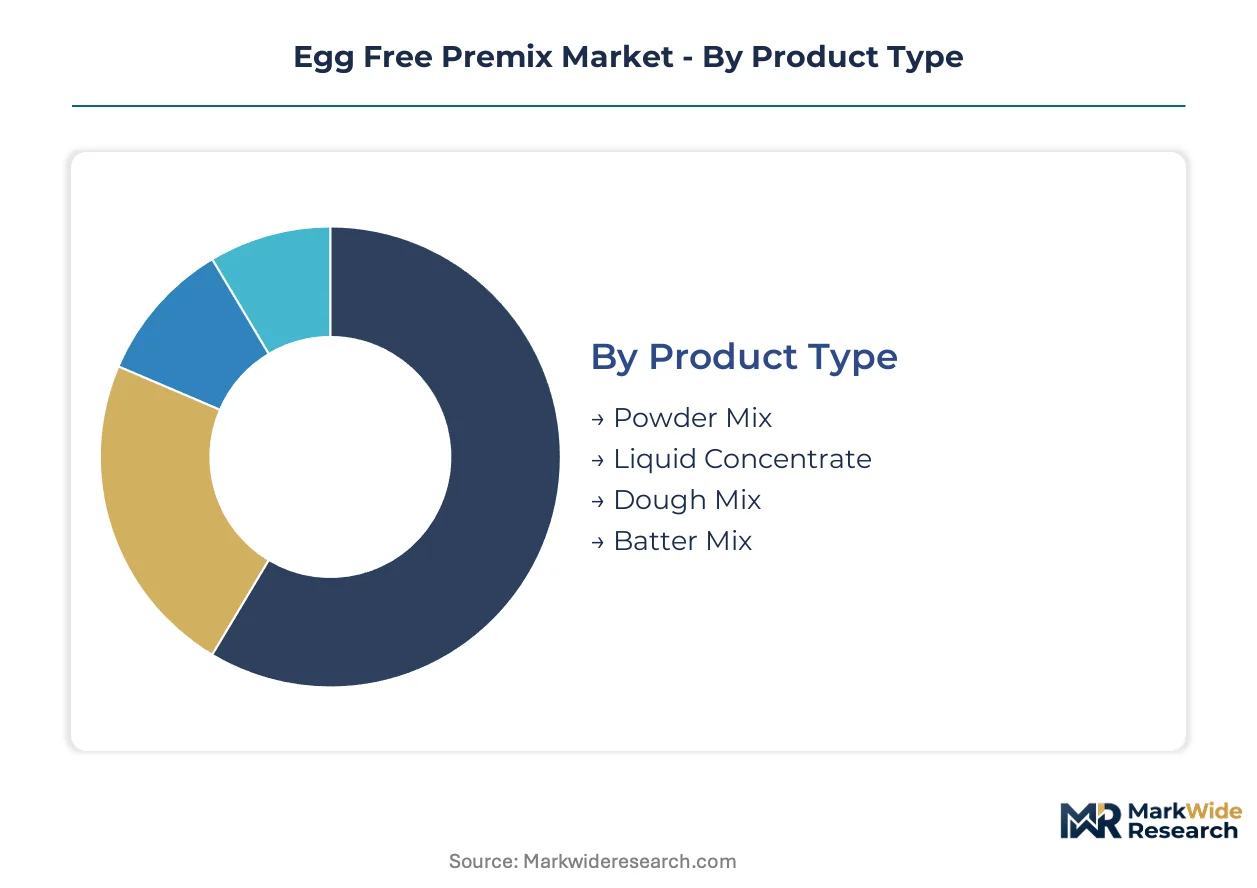
Egg free premix segmentation reveals how functional requirements, supply chain configurations, and procurement channels fragment demand across distinct technical specifications. Understanding these divides exposes where formulation investments concentrate and where margin compression threatens incumbent positioning.
Product Type:
Specification hierarchies separate shelf-stable formats from refrigerated concentrates, with hydration ratios and protein concentration levels defining procurement tradeoffs across industrial and artisanal end uses.
- Powder Mix:Dehydrated blends of legume proteins, modified starches, and hydrocolloids engineered for 12-18 month ambient stability. Commercial bakeries in Germany's industrial clusters around Munich and Hamburg drive bulk procurement for centralized production lines requiring freight efficiency and inventory flexibility.
- Liquid Concentrate:Pre-hydrated emulsion systems with precise solids content for batch-consistent dosing. Food service channels and restaurant chains capture this format to displace shell egg supply contracts without reformulating hydration protocols.
- Dough Mix:High-viscosity concentrates optimized for gluten network integration and fermentation tolerance. Artisan bakeries in France adopt these for laminated dough applications where fat-protein binding determines final texture.
- Batter Mix:Low-shear stable suspensions designed for coating and tempura systems. Snack manufacturers leverage these for extruded product lines abandoning egg-based wash adhesion.
Mature deployment sits with Powder Mix. Newer deployment is concentrated in Liquid Concentrate.
Application:
End-use intensity varies by thermal stress, structural demands, and clean-label certification requirements, redirecting supplier technical support resources toward the most formulation-critical segments.
- Baking:Bread, cake, and pastry applications requiring heat-stable foam structures and Maillard reaction substrates. Industrial facilities in Germany's baking corridor dominate volume procurement as REACH compliance deadlines compress reformulation timelines.
- Snack Production:Extruded, coated, and puffed products shifting from egg wash adhesion systems. This segment is expanding most quickly as Middle Eastern and Asian snack manufacturers seek halal-certified binding alternatives for export markets.
- Cooking:Sauces, dressings, and prepared meals needing emulsion stability without egg yolk lipoproteins. Food manufacturers in the United States target this segment for allergen-free retail label claims.
- Food Service:Institutional kitchens and restaurant chains requiring batch-scalable, labor-minimizing formats. Contract distributors consolidate procurement around single-source suppliers with documented allergen controls.
Volume concentration rests with Baking. Steepest expansion trajectory belongs to Snack Production.
Distribution Channel:
Channel selection reflects buyer scale, technical support needs, and documentation requirements for allergen traceability and clean-label certification.
- Direct Sales:Technical partnership models for industrial food manufacturers requiring customized hydration ratios and joint formulation development. EFSA allergen documentation and batch-level traceability dominate procurement criteria.
- Specialty Stores:Professional ingredient suppliers serving artisan bakeries and small-batch producers. France and Italy's regional baking supply networks sustain this channel through technical consultation services.
- Supermarkets:Packaged retail formats for home bakers and small commercial users. Clean-label front-of-pack claims drive shelf placement negotiations.
- Online Retail:Direct-to-consumer and small business procurement with technical documentation delivered digitally. This channel captures price-sensitive experimentation before volume commitment to direct sales contracts.
Margin stability favors Direct Sales. Channel experimentation clusters in Online Retail.
End User:
User sophistication determines formulation complexity tolerance, technical support intensity, and certification documentation requirements across the value chain.
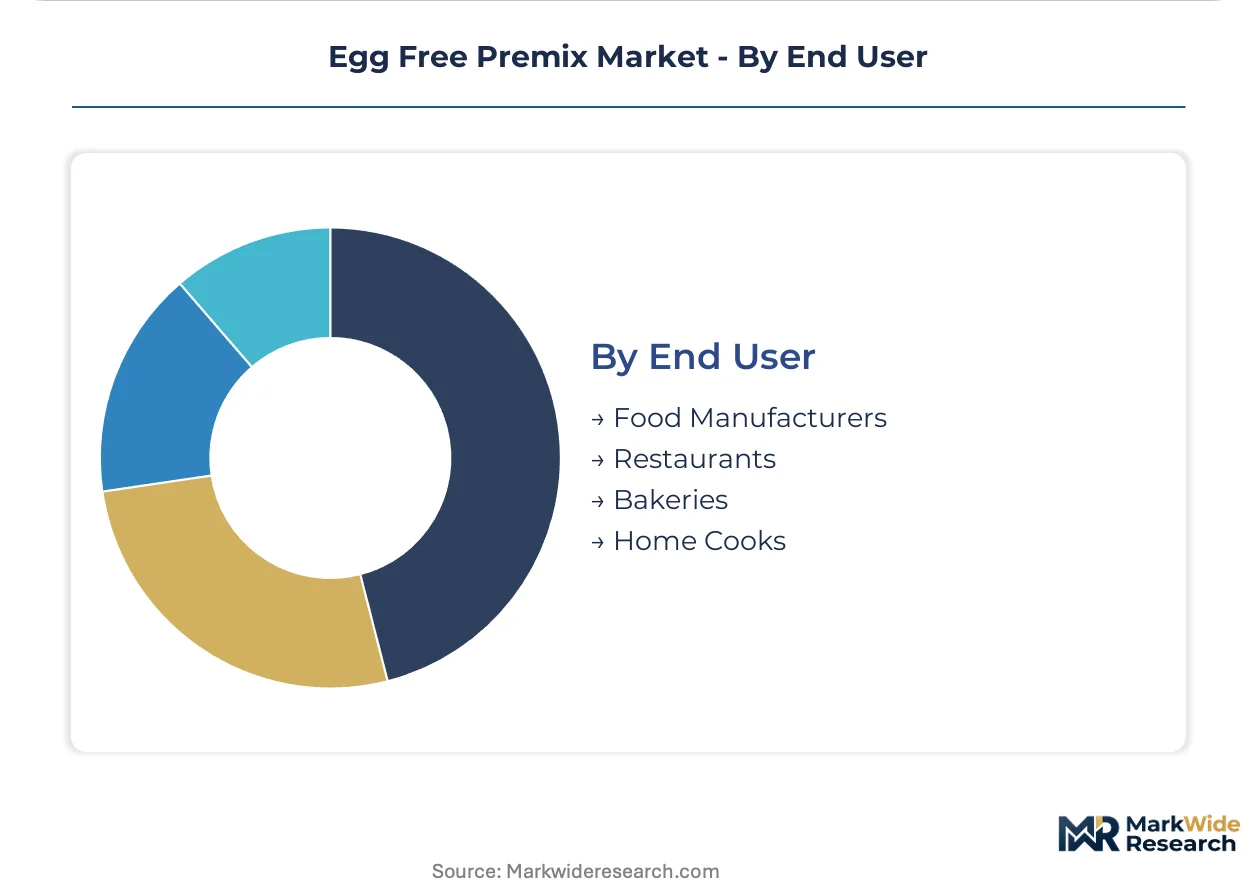
- Food Manufacturers:Large-scale processors with in-house R&D capabilities and stringent supplier audit protocols. FDA Food Safety Modernization Act compliance documentation and EFSA allergen thresholds shape procurement specifications.
- Restaurants:Chain and institutional operators seeking labor reduction and supply chain simplification. Batch consistency requirements favor liquid concentrate formats with pump-dispense compatibility.
- Bakeries:Industrial and artisanal producers spanning centralized facilities to neighborhood operations. Germany's concentration of industrial baking clusters creates geographic demand density for technical service investment.
- Home Cooks:Allergen-conscious consumers and plant-based dietary adherents purchasing retail formats. Clean-label ingredient disclosure and familiar protein sources influence purchase decisions.
Technical integration depth peaks with Food Manufacturers. Format experimentation concentrates among Home Cooks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the UAE and special economic corridors in India are accelerating plant-based ingredient manufacturing concentration. These zones offer tariff exemptions and streamlined customs processing for imported legume protein isolates. Industrial baking clusters in Germany and snack production hubs in the United States complete the geographic demand map.
Germany
Industrial baking corridors around Munich and Hamburg drive concentrated procurement of REACH-certified clean-label concentrates. The EU F-Gas Regulation mandates phase-out of conventional processing aids, compressing reformulation timelines for centralized production facilities. Bavaria's manufacturing density supports technical service investment from specialty ingredient suppliers.
United States
Snack manufacturers in the Midwest and Southeast are abandoning egg-based wash systems for extruded products. FDA Food Safety Modernization Act compliance documentation shapes procurement specifications for institutional bakery chains. Illinois and Georgia host the largest contract manufacturing agreements demanding batch-level allergen traceability.
India
FSSAI additive approval pathways are fragmenting formulation standardization for domestic and export-oriented processors. Gujarat and Maharashtra house the primary legume protein processing facilities supplying regional premix formulators. Special economic zones in these states offer duty drawbacks for hydrocolloid imports.
United Arab Emirates
Halal certification requirements for Middle Eastern export markets concentrate demand in Dubai's free trade zones. Jebel Ali port infrastructure enables re-export of certified powder formulations to Saudi Arabia and Egypt. Local food manufacturers leverage zone status to bypass standard import duties on chickpea protein isolates.
France
Artisan bakery networks in Île-de-France and Auvergne-Rhône-Alpes sustain specialty store distribution channels with technical consultation services. EFSA allergen labeling directives impose documentation burdens that favor established clean-label suppliers. Lyon and Paris host regional formulation development centers serving laminated dough applications.
Egg Free Premix Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: multinational ingredient conglomerates with broad hydrocolloid portfolios, regional bakery supply specialists with technical service depth, and allergen-free pure-plays with dedicated production lines. Capacity expansion and clean-label certification investments constitute the dominant competitive moves, with M&A activity concentrating on legume protein isolate suppliers.
Within the European specialist tier, DeutscheBack and Orgran Natural Foods exemplify divergent geographic anchoring strategies. DeutscheBack leverages its Central European manufacturing footprint to supply industrial bakeries with certified concentrates, while Orgran Natural Foods sustains competitive positioning through dedicated allergen-free production infrastructure. Zion International Food occupies a distinct position in Middle Eastern markets through halal-certified powder formulations. These three entities represent the archetype spectrum from regional technical specialists to certification-driven export platforms.
| Leading Market Players |
|---|
| Bakenxt |
| Bakersville |
| Blue Bird Foods |
| Davars |
| Skyline Food Products |
| Zion International Food |
| Swissbake |
| DeutscheBack |
| Orgran Natural Foods |
| Others |
Supply & Pricing Matrix
REACH authorization timelines and the EU Green Deal's chemical hazard classification protocols gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant formulators while rewarding certified clean-label suppliers with pricing premiums in German industrial baking clusters.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified concentrates from conventional alternatives and commodity-grade blends. Price differentiation hinges on certification grade and volume scale, with bulk procurement from Munich and Hamburg facilities commanding favorable terms. Cost compression in economy-tier powders is intensifying because agricultural yield volatility in legume protein sourcing squeezes margin stability for non-integrated formulators. Food manufacturers exhibit the least price sensitivity due to liability transfer requirements, while home cooks drive volume in price-responsive retail channels.
Supply Chain Analysis
Legume protein isolate supply rests on processing facilities in India, Canada, and Australia, with hydrocolloid sourcing concentrated among Southeast Asian seaweed processors and European specialty chemical manufacturers. Raw material dependencies center on chickpea and fava bean protein isolates, modified starches, and gellan gum systems. Single-source vulnerability in hydrocolloid supply creates exposure to climate-driven harvest disruptions and maritime logistics chokepoints. Distribution runs through direct technical partnerships for industrial accounts, with specialty stores and consolidated food service distributors serving downstream fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a cost-of-compliance barrier-to-entry moat, advantaging incumbent premix suppliers with existing REACH certification infrastructure against capital-constrained challengers.
For Market Incumbents: Lock in supply security through backward integration into legume protein processing or long-term offtake agreements with Canadian and Indian isolate suppliers. Expand certified clean-label capacity in Bavaria to capture compressed reformulation timelines from REACH deadlines. Threats from precision fermentation-derived proteins and emerging allergen-free pure-plays demand defensive patent positioning around hydrocolloid blending systems. For New Entrants and Emerging Players: Begin with halal-certified powder formulations for Middle Eastern export markets, where Jebel Ali zone infrastructure reduces duty exposure and certification requirements filter out established European competitors. Target snack production applications in the United States Midwest, where extruded product manufacturers seek egg wash alternatives without complex hydration expertise. A technical service partnership model with regional distributors overcomes the formulation expertise gap that blocks direct industrial penetration. For Investors and Strategic Acquirers: Consolidation of food service distributor relationships around single-source clean-label providers is the leading indicator that institutional procurement is shifting toward end-to-end formulation transparency. Long-term viability favors vertically integrated specialists with captive legume protein supply and dedicated allergen-free production lines. Watch for REACH authorization delays triggering accelerated M&A activity among European formulators facing compliance-driven restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Bavaria manufacturing density supports technical service investment from specialty ingredient suppliers. |
| Backward Integration | Captive chickpea protein processing insulates margin stability from agricultural yield volatility cycles. |
| Clean-Label Certification | REACH compliance documentation creates procurement preference among German industrial baking clusters. |
| Long-term Supply Agreement | Multi-year offtake contracts with Gujarat legume processors secure isolate access for export formulations. |
| Joint Venture | Dubai free trade zone partnerships enable halal-certified re-export to Saudi Arabia and Egypt markets. |
Research Methodology
Document review covered EFSA allergen labeling directives, FDA Food Safety Modernization Act guidance, and FSSAI additive approval pathways, complemented by interviews with industrial bakery procurement directors, specialty ingredient R&D formulators, food service distribution executives, and clean-label certification auditors. Secondary validation drew from customs trade data on legume protein isolate flows, REACH authorization timelines published by ECHA, and SEC filings from diversified ingredient conglomerates. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from production capacity assessments.
Cross-referencing historical pricing patterns from agricultural commodity indices against expert panel input on reformulation timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application intensity, distribution channel documentation requirements, and end-user technical sophistication. CAGRs were derived from demand elasticity coefficients and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated REACH compliance deadline phasing and F-Gas Regulation implementation schedules.
Underlying measurement precision varies by segment; powder mix and industrial baking applications carry tighter precision than emerging liquid concentrate and home cook categories due to established procurement data availability. Forecasts reflect assumptions on regulatory convergence timelines and clean-label certification adoption curves. Agricultural yield volatility, divergent national additive approvals, and precision fermentation technology maturation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oak Extract Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Corn Gluten Meal Market
Ingredients
Insect-Based Ingredients Market
Ingredients
Rose Hips Extract Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Aroma Ingredients Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Mustard Oil Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Cocoa Bean Extract Market
Ingredients
South America Malt Ingredient Market
Ingredients
Agarwood Oil Market
Ingredients
Textured Milk Protein Market