
 Europe Brewers Spent Yeast Market | 2026-2036
Europe Brewers Spent Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Brewers Spent Yeast Market Intelligence
The EU's Circular Economy Action Plan is pivoting the market's cost-of-entry calculus by creating new value for industrial by-products. German-based Leiber GmbH leverages deep specialization in brewers' yeast for animal nutrition and food applications. Global agribusiness firms like Cargill, Incorporated and ADM compete through extensive distribution networks and integrated supply chains, connecting breweries with large-scale feed producers across the continent.
Brewers spent yeast is the inactive Saccharomyces cerevisiae yeast remaining after the beer fermentation process. This co-product is rich in protein, essential amino acids, and B-complex vitamins, making it a valuable nutritional ingredient. While the animal feed end-user segment constitutes the largest market by volume, the nutraceuticals segment is expanding due to its use in human dietary supplements. Dry yeast products command a larger share than liquid yeast, owing to their extended shelf life and logistical advantages.
The European Food Safety Authority (EFSA) sets rigorous standards for any ingredient intended for the animal feed chain, including brewers spent yeast. Compliance with the EU's Feed Materials Register and associated hygiene regulations is mandatory for market access. These frameworks ensure product safety and traceability. Navigating the distinct R&D and regulatory requirements for feed versus food-grade applications remains a central strategic challenge for producers.
Market Dynamics
The European market's trajectory is defined by the EU's Circular Economy Action Plan, which reframes brewers' spent yeast from a low-value co-product into a strategic asset for sustainable protein supply chains, particularly within the animal feed industry.
Growth Catalysts
- Sustainable Feed Demand:The animal feed industry, particularly aquaculture, seeks sustainable, non-animal protein sources to reduce reliance on fishmeal and soy, creating strong pull-through for brewers' yeast.
- EU Policy Framework:The EU Green Deal and its Farm to Fork strategy provide a favorable regulatory environment for upcycling food industry by-products, encouraging investment in yeast processing infrastructure.
- Brewing Industry Concentration:Germany's high density of large-scale breweries and advanced feed manufacturing facilities creates an efficient ecosystem for the collection, processing, and consumption of spent yeast.
Market Restraints
- Supply Inconsistency:The availability and volume of raw spent yeast are directly dependent on beer production cycles, leading to seasonal fluctuations that can disrupt processor supply chains.
- Logistical Hurdles:The high moisture content and rapid perishability of liquid yeast create significant transportation and storage costs, limiting the economic viability of sourcing from smaller, distant breweries.
- Substitution by Alternatives:Competition from other plant-based proteins, such as soy protein concentrate and pea protein, which have more stable and scalable supply chains, constrains pricing power.
Strategic Opportunities
- Nutraceutical and Food Applications:Expanding use in human nutrition, including vegan protein powders and umami-rich food flavorings, offers higher-margin potential than the bulk animal feed segment.
- Advanced Extraction Technologies:Investment in enzymatic hydrolysis and purification techniques can unlock higher-value yeast extracts, beta-glucans, and nucleotides for premium functional feed and food applications.
- Eastern Europe Expansion:Developing collection and processing infrastructure in brewery-rich countries like Poland and the Czech Republic represents a significant volume growth opportunity.
Industry Challenges
- Quality Standardization:Ensuring consistent protein content, amino acid profiles, and freedom from contaminants across batches sourced from multiple breweries is a persistent operational challenge for processors.
- Dual-Path Certification:Navigating the separate and stringent regulatory pathways for feed-grade materials under EFSA and food-grade ingredients presents a significant compliance burden and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Brewers Spent Yeast Market |
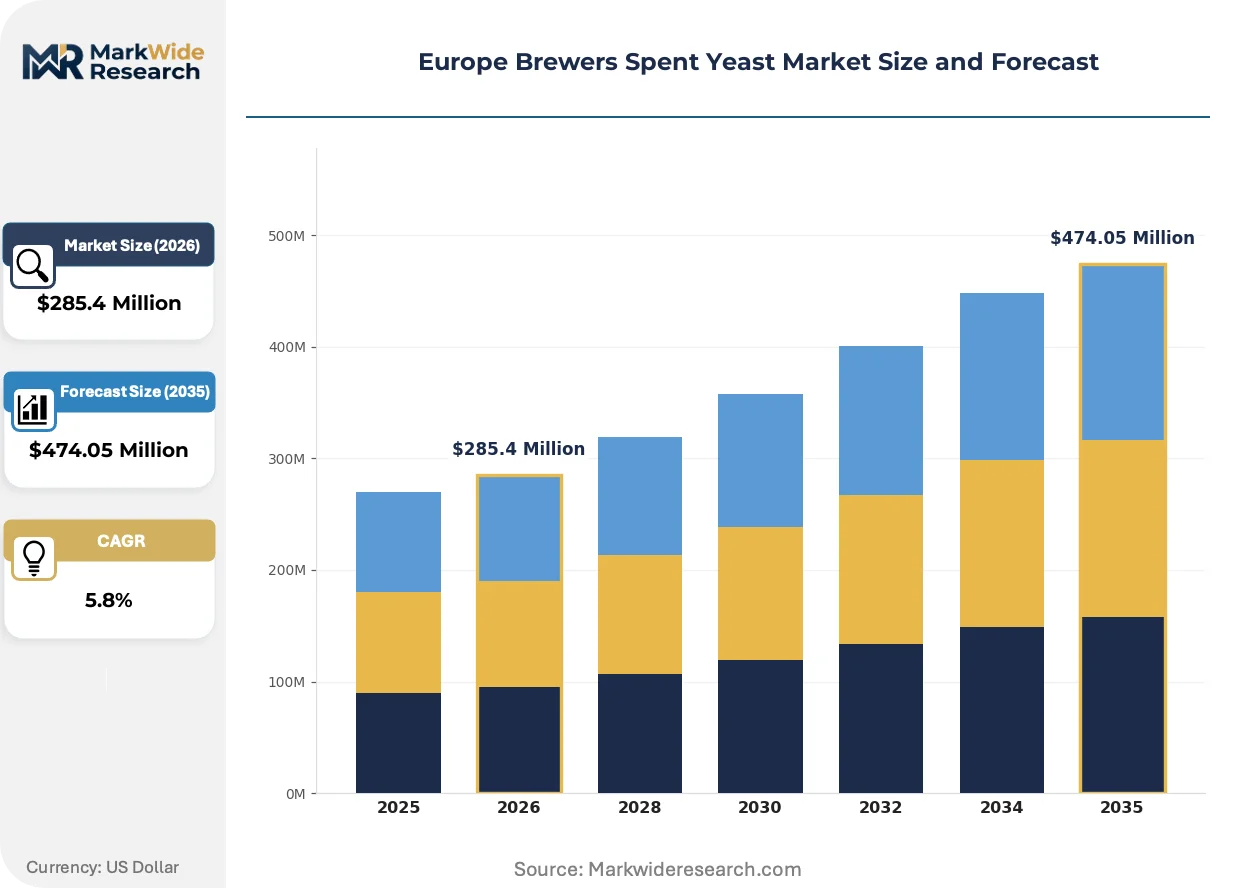
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Yeast, Liquid Yeast, Active Yeast, Instant Yeast End User: Bakeries, Distilleries, Nutraceuticals, Animal Feed Application: Baking, Fermentation, Fortification, Flavoring Distribution Channel: Online Stores, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Associated British Food plc, Lesaffre, Alltech, Leiber GmbH, Cargill, Incorporated, AngelYeast Co., Ltd., Lallemand Inc., Nutreco N.V., ADM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Brewers Spent Yeast Market Strategic Shifts & Innovations
Value creation is displacing waste management as the core operational principle. Technological advancements in processing and a clear policy direction toward circularity are enabling brewers to capture new value from what was once a disposal cost.
Enzymatic hydrolysis is a key processing technology that breaks down yeast cell walls to increase the bioavailability of proteins and release functional compounds. Animal nutrition formulators, especially in the piglet and aquafeed sectors, are actively specifying these enhanced products. This technology is rewriting the ingredient's role from a bulk protein to a functional additive for gut health and immunity.
The European Union's Farm to Fork Strategy reinforces the goals of the Circular Economy Action Plan, setting targets for sustainable food production and waste reduction. This policy directly incentivizes the upcycling of co-products like brewers' spent yeast, increasing its strategic value to breweries. The animal feed sector, under pressure to source sustainable ingredients, is the primary beneficiary of this increased, policy-driven supply.
A clear behavioral shift is visible as compound feed manufacturers' purchasing decisions evolve beyond simple cost-per-protein metrics. They now prioritize ingredients with documented functional benefits, traceability, and sustainability credentials. This trend marginalizes suppliers of unprocessed liquid yeast in favor of processors offering standardized, certified dry yeast products, a pattern most evident in the sophisticated German and Dutch markets.
Europe Brewers Spent Yeast Market Segmentation
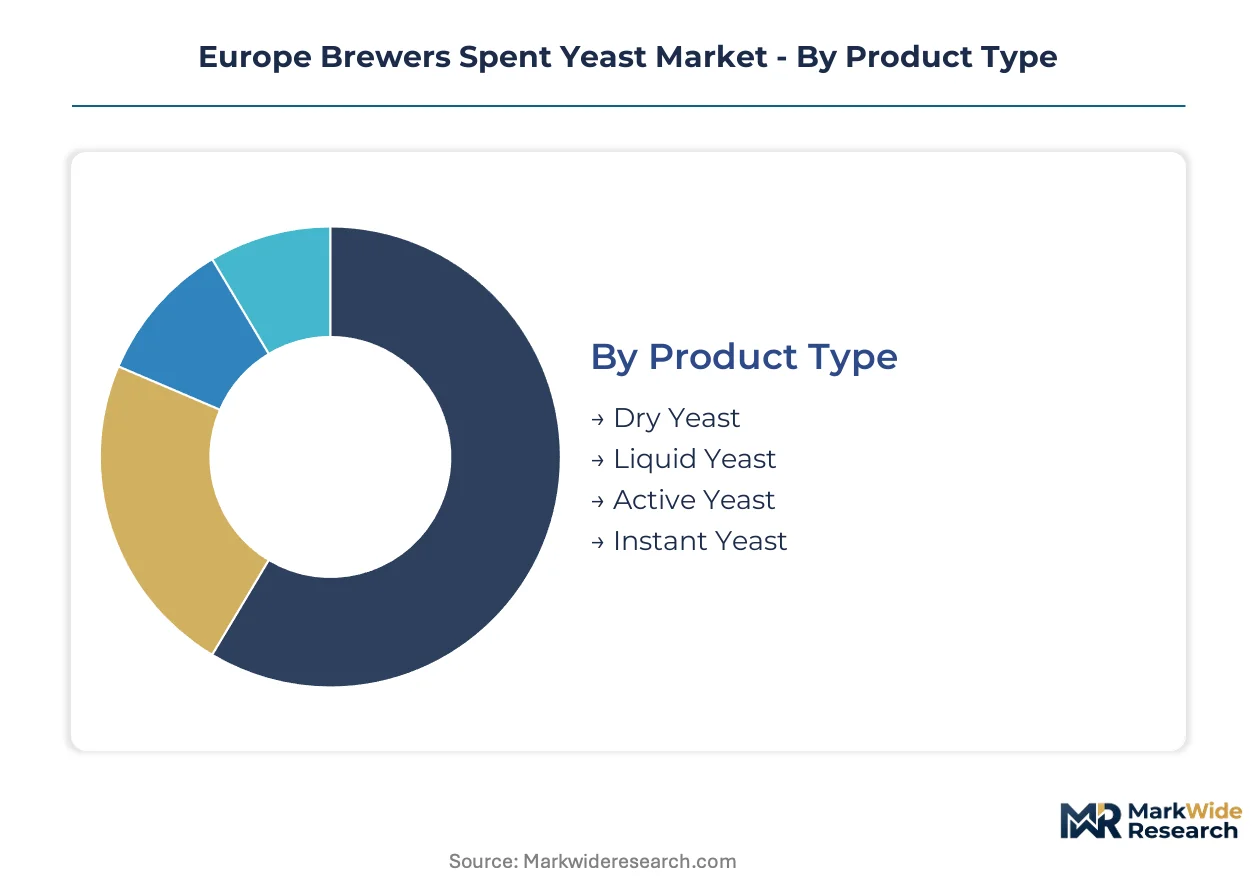
The European brewers spent yeast market differentiates across key dimensions, reflecting diverse processing needs and end-user applications. Understanding these segments clarifies the varying value propositions and strategic pathways for market participants. Each segment responds to distinct regulatory pressures and consumer preferences.
Product Type:
The market for brewers spent yeast is segmented by product form, indicating the level of processing and integration required for its end-use. Some forms are raw inputs, while others are highly refined for specific applications.
- Dry Yeast:This product form represents spent yeast that has been dehydrated, typically through spray drying, to a low moisture content. Its extended shelf life and reduced weight drive demand in large-scale animal feed operations across Germany and the Netherlands, where logistical efficiency is paramount.
- Liquid Yeast:Liquid yeast is the raw, unprocessed co-product directly from breweries, characterized by high moisture content and rapid perishability. Its localized demand stems from nearby feed manufacturers or waste treatment facilities, particularly in beer-producing regions of Central Europe, minimizing transportation costs.
- Active Yeast:This segment comprises yeast cells that retain metabolic activity, often used in specific fermentation processes beyond brewing.
- Instant Yeast:Instant yeast is a finely granulated, fast-acting dry yeast variant, primarily catering to industrial baking applications due to its rapid rehydration properties.
Volume placements concentrate in Liquid Yeast due to its direct co-product status; the faster expansion belongs to Dry Yeast.
End User:
The end-user segmentation highlights the diverse applications of brewers spent yeast across various industries, each valuing specific nutritional or functional attributes. These industries range from bulk commodity users to high-value ingredient formulators.
- Animal Feed:This segment utilizes brewers spent yeast as a protein-rich, palatable ingredient in livestock, poultry, and aquaculture diets. Demand in the European animal feed sector, particularly for piglet and aquafeed in countries like Denmark, is driven by the search for sustainable protein alternatives to fishmeal.
- Nutraceuticals:The nutraceuticals segment incorporates spent yeast into human dietary supplements, capitalizing on its B-vitamin content and immune-modulating beta-glucans. Expansion in this area is notable in Western European markets such as France and Italy, where consumer health trends favor natural ingredients.
- Bakeries:Bakeries use specific strains of live yeast for leavening, but spent yeast can be incorporated as a flavor enhancer or nutritional additive in certain baked goods.
- Distilleries:Distilleries primarily use fresh yeast for fermentation, but spent yeast can be a by-product or sometimes repurposed in minor flavoring applications for specific spirits.
The largest market share is held by Animal Feed, while Nutraceuticals represents the fastest-growing trajectory.
Application:
The application segment delineates the functional roles brewers spent yeast fulfills, ranging from bulk nutritional enhancement to specialized taste modification. Each application commands a different value proposition and processing requirement.
- Fortification:This application leverages the high protein, amino acid, and B-vitamin content of spent yeast to enrich the nutritional profile of feed and food products. It is critical in functional animal feed formulations across the Nordics, where producers seek to boost immunity and gut health.
- Flavoring:Spent yeast extracts are processed to create umami-rich flavorings and savory notes, enhancing the palatability of food products and pet foods. This application sees increasing adoption in processed food manufacturing in countries like the UK and Germany, driven by natural ingredient trends.
- Baking:While live yeast performs leavening, spent yeast can be integrated into certain baking recipes to add nutritional value or a distinct flavor profile.
- Fermentation:This application typically refers to the primary use of fresh yeast, but spent yeast can be a substrate for secondary fermentation processes in specific industrial biotechnology uses.
Fortification commands significant value, with Flavoring showing strong growth potential.
Distribution Channel:
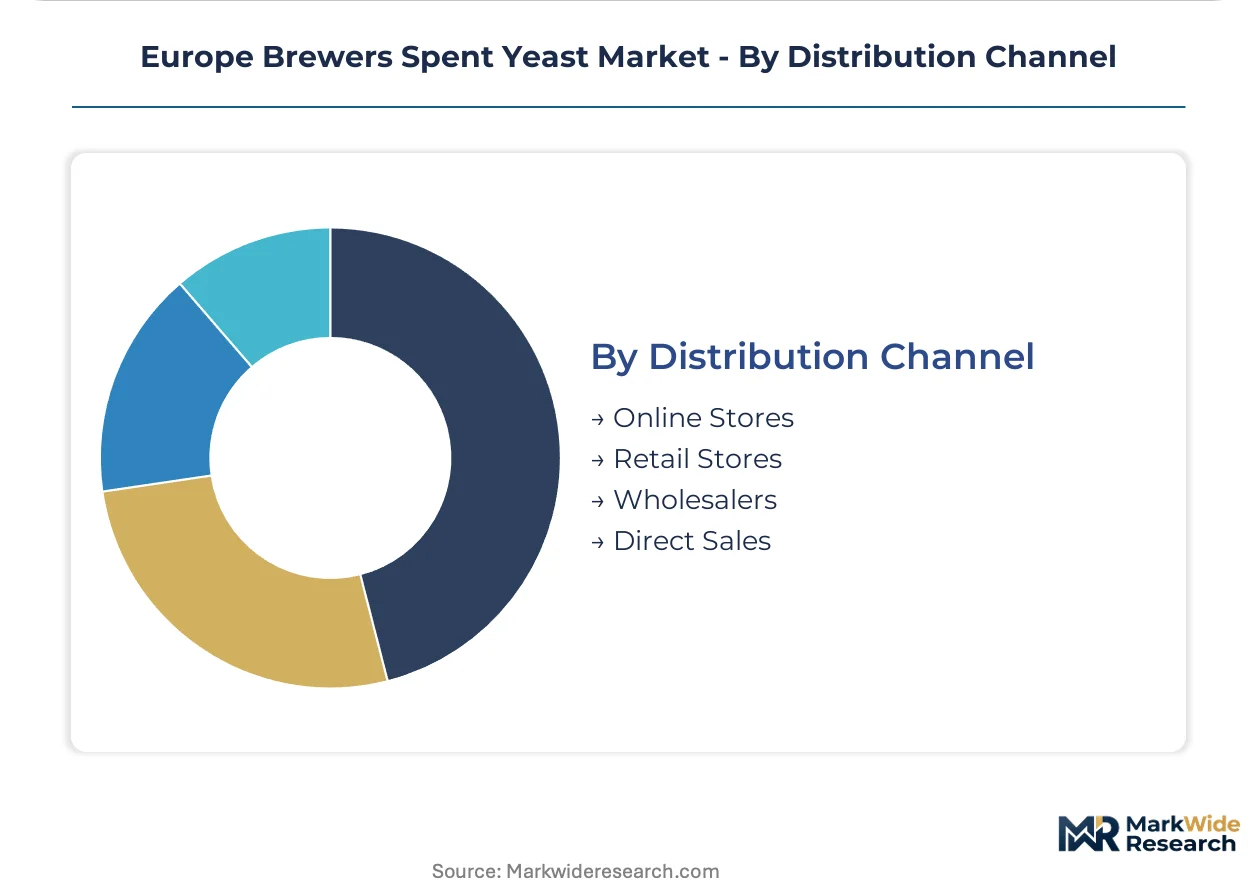
The distribution channel segment illustrates the pathways through which brewers spent yeast products reach their diverse end-users, reflecting varying scales and directness of supply. These channels range from large-volume intermediaries to direct producer-consumer relationships.
- Wholesalers:Wholesalers act as intermediaries, purchasing large volumes of processed spent yeast from producers and distributing them to various industrial clients, particularly feed mills and food manufacturers. This channel is crucial for efficient supply chain management across major European markets like Spain and Italy.
- Direct Sales:Direct sales involve producers selling spent yeast products directly to large-scale end-users, such as major animal feed corporations or nutraceutical companies. This channel facilitates customized product specifications and long-term contractual relationships in countries like Germany.
- Online Stores:Online platforms primarily cater to smaller-volume buyers or specialized niche markets seeking specific yeast products for home use or small-scale applications.
- Retail Stores:Retail stores offer limited quantities of spent yeast, typically in dried form, for consumers interested in dietary supplements or specialized baking ingredients.
Wholesalers manage the bulk of transactions, while Direct Sales offers specialized relationship management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European market for brewers spent yeast benefits from a policy-driven incentive zone established by the EU's Circular Economy Action Plan. This framework reframes brewery co-products as strategic assets for sustainable protein supply chains. Such initiatives accelerate investment in processing infrastructure across the continent.
Germany
Demand for brewers spent yeast is high due to its dense concentration of breweries and advanced feed manufacturing. The EU Green Deal encourages upcycling of food industry by-products within the country. Bavaria, a major brewing region, sees efficient collection and processing systems supporting large-scale feed producers.
Netherlands
Logistical efficiency drives the market for dry yeast products in the Netherlands, particularly for large-scale animal feed operations. EFSA standards for feed materials ensure product safety and traceability for Dutch processors. The port of Rotterdam acts as a key distribution hub, linking processed yeast to international feed markets.
Denmark
Aquaculture and piglet feed producers in Denmark seek sustainable protein sources like brewers spent yeast. The EU's Farm to Fork strategy directly incentivizes the use of such ingredients in Danish animal nutrition. Research centers in Jutland focus on advanced feed formulations incorporating functional yeast additives.
France
Nutraceuticals and human dietary supplements drive increasing demand for brewers spent yeast in France. The country's national food safety agency ensures compliance with stringent regulations for food-grade yeast applications. Paris and Lyon are centers for food innovation, where yeast extracts are developed for natural flavoring.
Poland
Expanding collection and processing infrastructure represents a significant growth opportunity for brewers spent yeast in Poland. The EU's cohesion policy supports regional development, including investments in sustainable agricultural practices. Brewery-rich regions like Greater Poland are becoming hubs for raw yeast aggregation and initial processing.
Europe Brewers Spent Yeast Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the European brewers spent yeast market. The market structure exhibits a tiered consolidation, where large agribusiness firms leverage extensive networks while specialized yeast producers innovate in niche applications. Strategic archetypes include global ingredient suppliers, regional processors, and technology-driven extract manufacturers. Competitive moves often involve capacity expansion and strategic partnerships to secure raw material supply.
Among the global agribusiness firms, Cargill, Incorporated and ADM exemplify scale-driven operations, integrating brewers spent yeast into their extensive animal nutrition portfolios. These companies anchor broad distribution networks connecting breweries with large-scale feed producers across Europe. Conversely, Leiber GmbH, a German-based specialist, occupies a position focused on deep specialization in brewers' yeast for animal nutrition and food applications, representing a pure-play approach within the market.
| Leading Market Players |
|---|
| Associated British Food plc |
| Lesaffre |
| Alltech |
| Leiber GmbH |
| Cargill, Incorporated |
| AngelYeast Co., Ltd. |
| Lallemand Inc. |
| Nutreco N.V. |
| ADM |
| Others |
Cost & Logistics Intelligence
The European protein commodity index, reflecting prices of soy meal and fishmeal, cascades into the pricing tiers for brewers spent yeast, influencing its competitive position as a sustainable alternative.
Pricing Analysis
Premium pricing for brewers spent yeast with short lead times reflects immediate demand from feed manufacturers, while spot inventory often receives discounts. Contract-based long-term offtake agreements dominate transactions for processed dry yeast. Price differentiation stems from the product's quality grade, specifically protein content and amino acid profile, and the certification level, such as EFSA compliance for animal feed. Pricing softness stems from the availability of alternative plant-based proteins. Animal feed manufacturers, particularly large-scale compounders, exhibit the highest price sensitivity, while nutraceutical companies are less price-sensitive due to higher-value applications.
Supply Chain Analysis
Reverse logistics for liquid yeast collection from breweries, involving specialized tankers and rapid processing, presents a significant cost component. Supply concentration for raw spent yeast centers on Germany, the Netherlands, and Poland, reflecting dense brewing activity. The market depends on consistent beer production volumes as its primary raw material input. Supply chain risk arises from the inherent inconsistency of brewery output, leading to seasonal fluctuations. Distribution runs through a dual model, with wholesalers handling bulk processed products and direct sales supporting specialized, high-volume end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European brewers spent yeast market is a cost-of-compliance story, with EFSA regulations creating a significant barrier-to-entry moat for compliant processors.
For Market Incumbents:Anticipate continued pressure from alternative protein sources by investing in advanced processing technologies like enzymatic hydrolysis. Deepen backward integration into brewery collection networks across Eastern Europe to secure raw material supply. This move counters potential supply chain disruptions from fluctuating beer production. Focus R&D on developing higher-value functional ingredients for specialized animal nutrition segments to mitigate commodity pricing pressure.
For New Entrants and Emerging Players:Online B2B marketplaces offer a direct route to connect smaller breweries with regional processors, bypassing traditional wholesaler channels. Target the nutraceuticals segment in Western European markets like France and Italy, which offers higher margins and values product differentiation. Focus on developing niche, certified organic or non-GMO spent yeast products. A go-to-market angle emphasizing traceability and sustainability credentials can differentiate new offerings.
For Investors and Strategic Acquirers:Distressed-cycle entries favor regional processors with established collection infrastructure in brewery-dense geographies like Germany. The long-term viability of brewers spent yeast is strong, driven by the EU's circular economy mandates and sustainable protein demand. Acquisition targets should possess robust EFSA compliance records and diversified product portfolios beyond bulk animal feed. Practitioners should monitor the development of novel fermentation technologies for alternative protein production as a signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Enzymatic Hydrolysis Capacity | Unlocks higher-value yeast extracts for functional feed and food applications. |
| Acquire Regional Collection Networks | Secures consistent raw material supply from smaller, geographically dispersed breweries. |
| Invest in Food-Grade Certification | Opens access to the higher-margin human nutraceuticals and food flavoring markets. |
| Form Strategic Partnerships with Breweries | Ensures stable, long-term spent yeast supply and optimizes logistics for collection. |
| Develop Beta-Glucan Extraction Technologies | Creates premium immune-modulating ingredients for functional feed and human supplements. |
Research Approach
Multi-period observation of brewers spent yeast pricing and supply volumes anchored the trend analysis, supplemented by interviews with brewery operations managers, animal feed formulators, nutraceutical product developers, and logistics coordinators. Secondary validation drew from EFSA reports, Eurostat agricultural data, brewing industry association publications, and national food safety agency documents. This approach ensured bottom-up and top-down triangulation of market dynamics.
The input-output matrix framing guided the quantitative modeling, projecting market growth across the analysis window. Segmentation dimensions modeled included product type, end-user, application, distribution channel, and regional policy environment. Compound annual growth rates were derived through a regression analysis of historical data and forward-looking projections based on identified growth catalysts. Key forecast inputs included projected beer production volumes and animal feed consumption trends.
The model holds under current EU regulatory frameworks and prevailing economic conditions; deviation in brewing output or shifts in alternative protein development would shift the forecast. Forecasts reflect assumptions about sustained demand for sustainable protein sources and ongoing investment in processing infrastructure. Practitioners should monitor policy changes regarding food waste upcycling and significant technological advancements in protein alternatives for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Textured Milk Protein Market
Ingredients
Plant Based Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Banana Flour Market
Ingredients
Rice Starch Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Specialty Feed Additives Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Cocoa Market
Ingredients
Global Distillers Grains Market