
 Tomato Concentrate Market | 2026-2036
Tomato Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Tomato Concentrate Market Analytics
EU F-Gas Regulation limits on fluorinated greenhouse gases is expanding compliance costs for thermal concentration facilities across European processing hubs. COFCO Tunhe Tomato Co. leverages its Xinjiang tomato base to dominate bulk paste supply into Central Asian and Middle Eastern channels. The Morning Star Company sustains one of North America's largest tomato processing footprints through vertically integrated field-to-facility operations. Sugal Group anchors southern European supply with specialized aseptic packaging capabilities for food service clients.
Tomato concentrate denotes tomato solids reduced through evaporation to 24-36% soluble solids for paste, or lower concentrations for puree and sauce applications, with hot-break or cold-break processing determining final viscosity and color retention for industrial formulation. Paste commands the largest volume pool across product types due to its ubiquity in downstream sauce and soup manufacturing, while pouch packaging within the packaging type dimension is gaining fastest in retail channels driven by convenience and portion-control preferences. The dried segment occupies a premium niche serving ingredient-intensive snack and seasoning applications with higher per-unit margins than bulk paste.
FDA standards for acidified foods and USDA grading protocols govern safety and quality thresholds in the United States, while EFSA maximum residue limits for pesticides shape agricultural input choices across European supply chains. BIS certification requirements in India and GB standards in China add compliance layers for exporters targeting those domestic markets. Stakeholders must monitor how evolving national pesticide maximum residue limits and carbon border adjustment mechanisms reshape sourcing economics and facility location decisions.
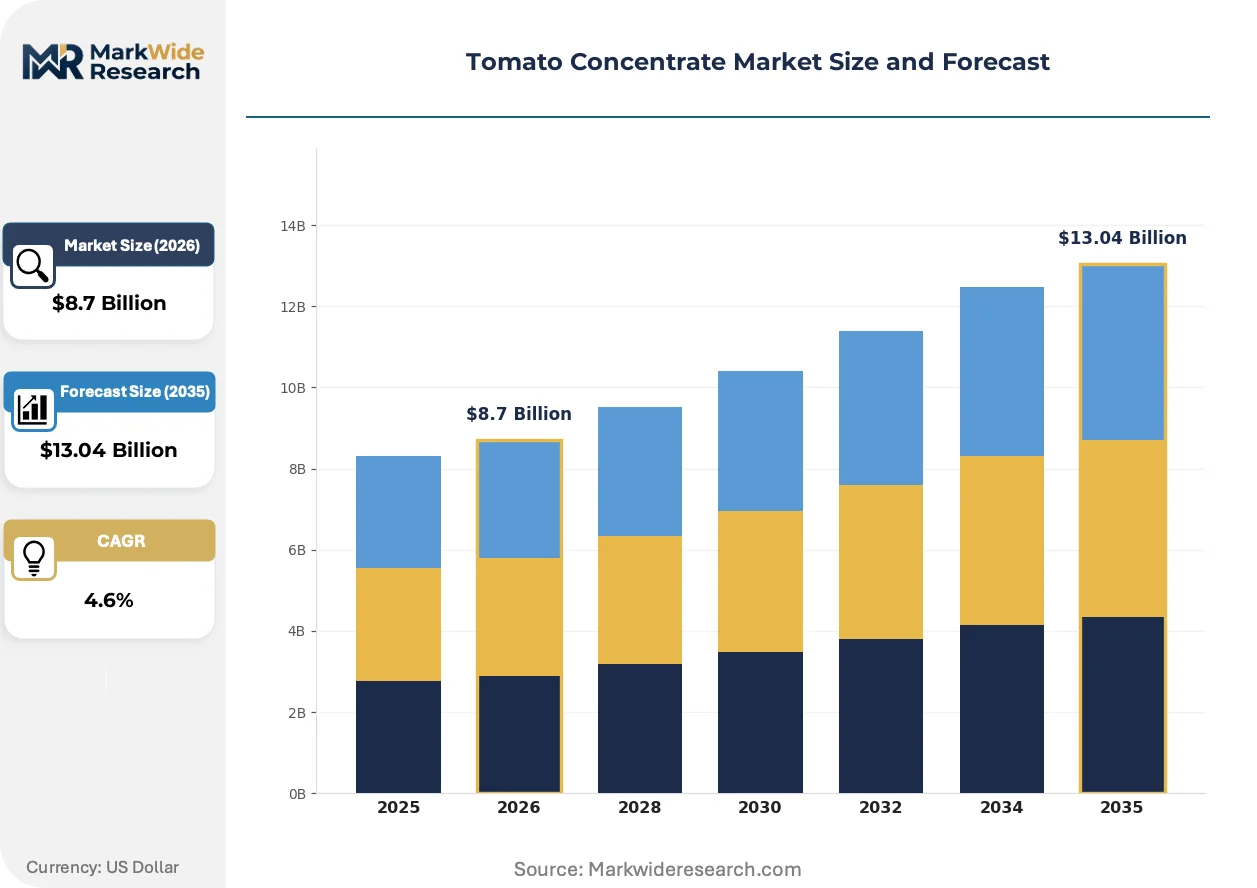
Market Dynamics
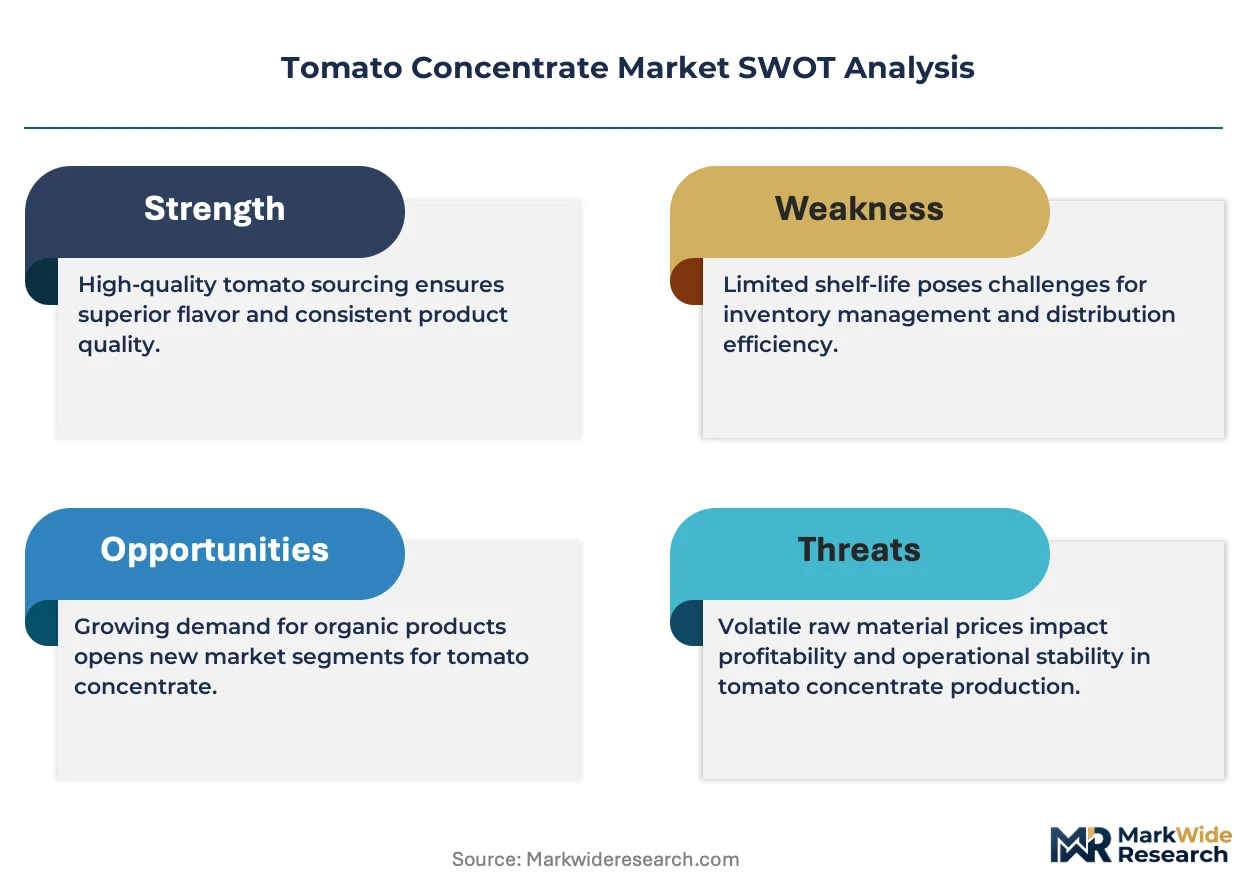
EU F-Gas Regulation compliance costs are compressing margins across European thermal concentration facilities while pushing capital allocation toward mechanical vapor recompression and membrane filtration systems.
Growth Catalysts
- Ready meals procurement surge:Food processing buyers in the ready meals category are scaling paste and sauce format procurement to meet convenience food demand.
- REACH compliance premium:ECHA chemical safety standards create differentiated positioning for processors with certified clean-label supply chains.
- California-Italy belt concentration:Processing gravity in California's Central Valley and Italy's Emilia-Romagna cluster drives economies of scale and technical knowledge spillovers.
Market Restraints
- Natural gas price volatility:Thermal concentration facilities face margin compression from input energy cost swings, particularly in European hubs.
- Xinjiang supply concentration:COFCO Tunhe's dominance of Central Asian bulk paste channels creates single-source vulnerability for regional buyers.
- Viscosity ceiling in cold-break processing:Technical limitations on solids retention constrain formulation flexibility for premium sauce applications.
Strategic Opportunities
- India BIS certification pathway:Exporters meeting BIS standards gain first-mover access to domestic food manufacturing growth.
- Pouch packaging retail penetration:Convenience and portion-control preferences in European retail channels favor flexible format expansion.
- Membrane-thermal hybrid convergence:Integration of reverse osmosis pre-concentration with mechanical vapor recompression cuts energy intensity.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in hybrid concentration system design and commissioning remains concentrated among legacy equipment suppliers.
- Legacy aseptic line retrofit costs:Food service clients demanding specialized pouch formats force capex-heavy packaging line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Concentrate Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paste, Puree, Sauce, Dried End User: Food Service, Retail, Food Processing, Restaurants Packaging Type: Tetra Pak, Glass Jar, Pouch, Can Application: Soups, Sauces, Ready Meals, Snacks |
| Companies Covered | Ingomar Packing Co., Neil Jones Food Company, The Morning Star Company, Xinjiang Guannong Tomato Products Co. Ltd., CONESA Group, COFCO Tunhe Tomato Co., Ltd., Los Gatos Tomato Products, Sugal Group, Xinjiang Chalkis Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Concentrate Market Evolving Landscape
Active innovation in the tomato concentrate sector centers on energy system redesign, regulatory compliance architecture, and packaging format diversification to capture shifting buyer preferences across industrial and retail channels.
Mechanical vapor recompression technology is modularizing thermal concentration infrastructure. Ready meals manufacturers and sauce blenders are adopting skid-mounted MVR units at pilot scale before facility-wide deployment. This modular approach is compressing capital commitment timelines and allowing processors to phase compliance investments alongside EU F-Gas Regulation deadlines.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition roadmaps across Italian and Spanish processing hubs. Facilities running hydrofluorocarbon-based cooling systems face retrofit or replacement decisions by 2030. The dried segment, with its premium positioning and lower volume throughput, is absorbing compliance costs through price premiums while bulk paste operations pursue technology substitution.
Food service procurement is consolidating around aseptic pouch specifications with extended ambient stability. Restaurant chains and institutional buyers in Italy and California are specifying single-serve and batch-size formats that reduce waste and labor. This specification shift is displacing traditional drum and bag-in-box contracts in contract manufacturing negotiations.
Tomato Concentrate Market Segmentation
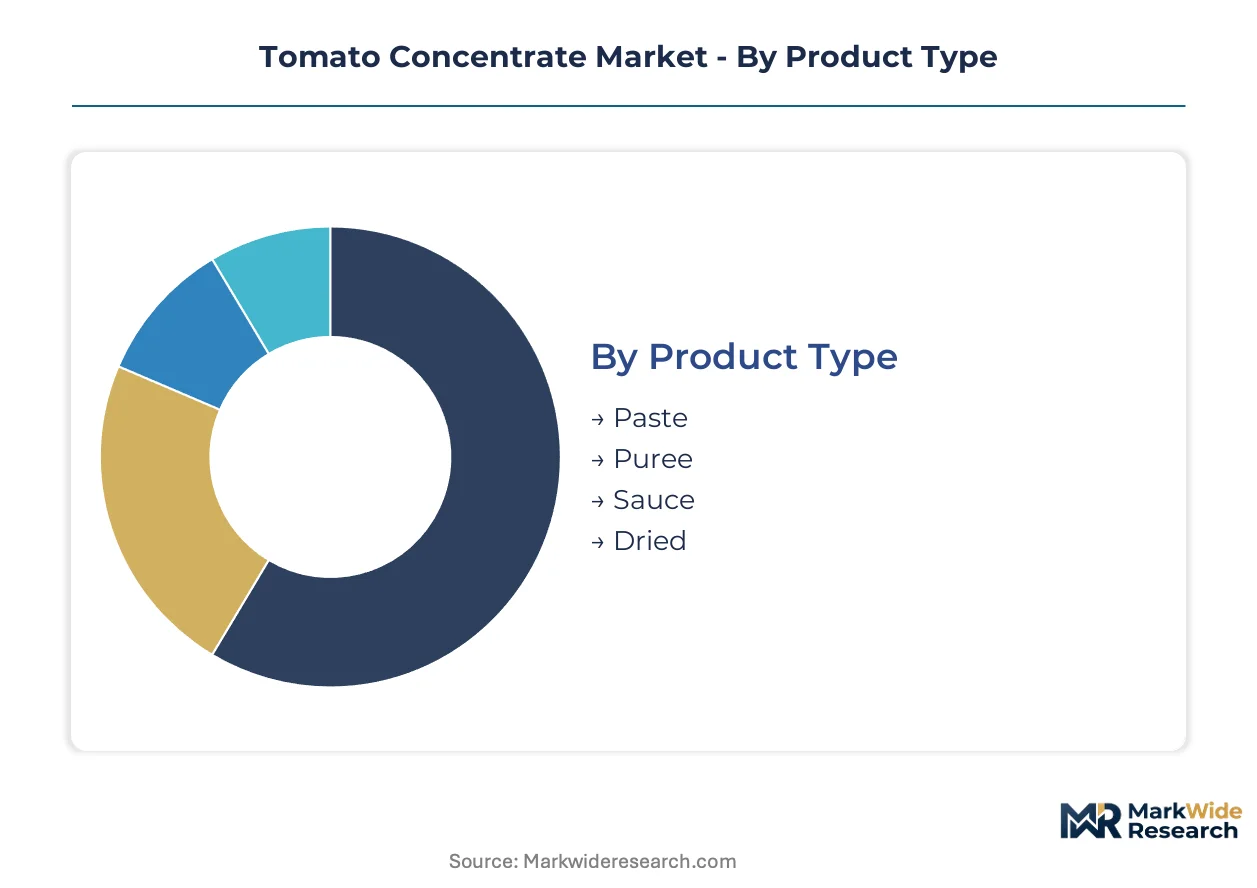
Segmentation in tomato concentrate reveals how capital intensity and regulatory exposure concentrate returns across distinct processing tiers. Buyers in food manufacturing, food service, and retail channels demand specification precision that fragments supply chain economics by product format and packaging technology.
Product Type:
Capital intensity peaks in paste production due to evaporator infrastructure and thermal energy systems, while dried formats command premium equipment for moisture removal without heat degradation.
- Paste:Tomato solids concentrated to 24-36% through hot-break or cold-break evaporation. Demand concentrates in California's Central Valley and Italy's Emilia-Romagna cluster where COFCO Tunhe and Morning Star operate integrated field-to-facility networks. Food processing buyers for downstream sauce manufacturing absorb the largest volume flows.
- Dried:Low-moisture concentrate produced through spray-drying or drum-drying for seasoning and snack applications. European processors leverage this segment to absorb EU F-Gas Regulation compliance costs through price premiums that institutional buyers accept for formulation stability.
- Puree:Lower solids concentration than paste, typically 8-24%, serving soup bases and beverage applications.
- Sauce:Pre-formulated concentrate with added seasonings, reducing downstream processing steps for ready meals manufacturers.
Most installed capacity flows through Paste. Expansion is steepest in Dried.
End User:
Customer type determines margin structure, with food service contracts favoring long-term volume commitments and retail channels demanding packaging innovation for shelf differentiation.
- Food Processing:Industrial buyers purchasing paste and puree in bulk for sauce, soup, and ready meals manufacturing. Procurement concentrates among ready meals manufacturers scaling paste format purchasing to meet convenience food demand across European and North American production facilities.
- Food Service:Restaurant chains and institutional buyers specifying aseptic pouch formats with extended ambient stability. Italian and California-based operators are displacing traditional drum contracts with single-serve and batch-size specifications that reduce kitchen labor and waste.
- Retail:Supermarket and hypermarket channels driving pouch packaging adoption for convenience and portion control.
- Restaurants:Independent operators and smaller chains purchasing through distributors with lower volume thresholds than institutional food service.
Food Processing commands the largest revenue pool. Food Service is climbing the fastest on packaging specification shifts.
Packaging Type:
Technology investment separates aseptic stability systems from commodity containment, with flexible formats requiring specialized line retrofits that constrain supplier switching.
- Pouch:Flexible aseptic packaging gaining share in European retail channels driven by convenience and portion-control preferences. Sugal Group anchors southern European supply with specialized aseptic capabilities for food service clients demanding ambient-stable formats.
- Tetra Pak:Aseptic carton systems for retail paste and puree with established recycling infrastructure in European markets.
- Glass Jar:Premium retail positioning for sauce formats with visual quality appeal and reusability credentials.
- Can:Traditional metal containment for industrial paste with established logistics but declining share in retail-facing applications.
Tetra Pak retains the largest installed base. Pouch is gaining share fastest on food service specification migration.
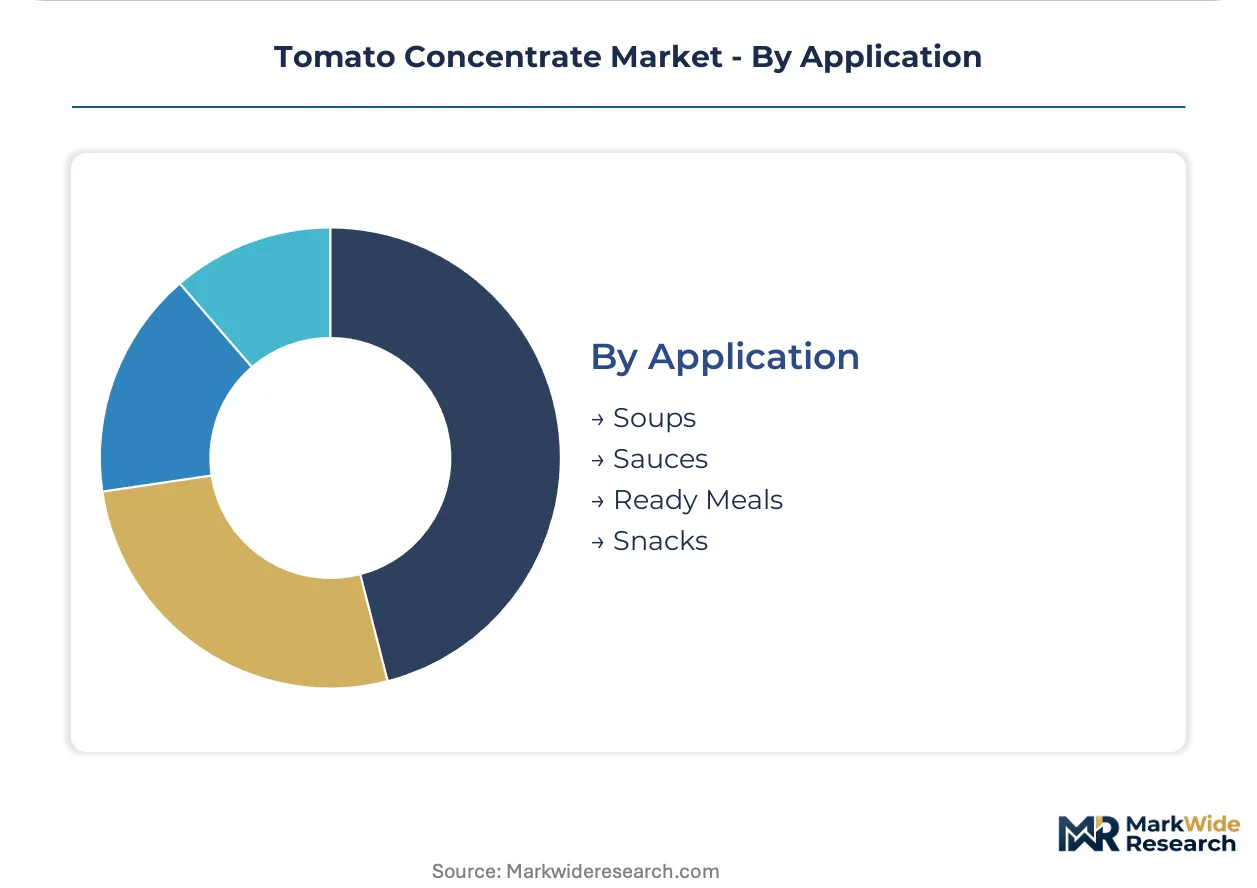
Application:
End-use formulation requirements determine viscosity specifications and color retention standards that cascade back to hot-break versus cold-break processing decisions.
- Ready Meals:Prepared food manufacturers scaling paste and sauce procurement to meet convenience demand. Procurement from California and Italian processing clusters provides formulation consistency for multinational ready meals brands.
- Sauces:Ketchup, pasta sauce, and condiment manufacturing requiring precise solids content and viscosity control. Cold-break processing limitations on solids retention constrain premium sauce formulation flexibility.
- Soups:Commercial and retail soup bases utilizing puree and lower-concentration formats.
- Snacks:Seasoning and flavoring applications for the dried segment's premium niche with higher per-unit margins than bulk paste.
Sauces absorb the largest volume share. Ready Meals shows the steepest expansion trajectory on convenience food demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing expertise concentrates in the Mediterranean basin and California's Central Valley, where multi-generational tomato cultivation knowledge anchors industrial-scale concentration operations. These talent pools sustain the technical standards that downstream food manufacturers demand.
United States
Ready meals manufacturers in the Midwest and Southeast are scaling paste procurement to meet convenience food demand. FDA acidified foods standards and USDA grading protocols govern safety thresholds for domestic and export-bound production. California's Central Valley tomato belt hosts vertically integrated field-to-facility networks that supply North American sauce and soup manufacturing.
Italy
Food service buyers across southern Europe are specifying aseptic pouch formats with extended ambient stability. EU F-Gas Regulation phase-down schedules force refrigerant transition decisions by 2030 across Italian processing hubs. Emilia-Romagna's processing cluster drives economies of scale and technical knowledge spillovers for paste and puree production.
China
Bulk paste demand from Central Asian and Middle Eastern channels concentrates procurement through Xinjiang-based operations. GB standards and SAMR oversight add compliance layers for exporters targeting domestic Chinese markets. COFCO Tunhe leverages its Xinjiang tomato base to dominate regional supply into cross-border trade corridors.
Spain
European retail channels are adopting pouch packaging for convenience and portion-control preferences. ECHA REACH compliance creates differentiated positioning for processors with certified clean-label supply chains. Southern Spanish processing facilities absorb EU F-Gas Regulation costs through technology substitution toward mechanical vapor recompression systems.
India
Domestic food manufacturing growth is opening procurement pathways for exporters meeting BIS certification requirements. FSSAI standards and DGFT trade protocols shape import and export transaction structures. Maharashtra and Gujarat processing investments are expanding to capture rising sauce and ready meals formulation demand.
Tomato Concentrate Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct processing tiers. The vendor base separates between integrated field-to-facility operators and specialized packaging-focused processors. Three archetypes dominate: vertically integrated agricultural processors with captive raw material supply, technology-specialized equipment and packaging providers, and regional bulk commodity traders. Competitive moves concentrate on capacity expansion in high-growth corridors and strategic partnerships to secure aseptic packaging line retrofits for food service specifications.
Within the integrated processing tier, COFCO Tunhe and The Morning Star Company exemplify contrasting geographic anchoring strategies—one leveraging Xinjiang agricultural concentration for Central Asian bulk supply, the other sustaining North American footprint through California Central Valley integration. Sugal Group occupies a position among southern European specialists with aseptic capabilities. These three represent the archetype spectrum from commodity-scale bulk paste to premium food service packaging.
| Leading Market Players |
|---|
| Ingomar Packing Co. |
| Neil Jones Food Company |
| The Morning Star Company |
| Xinjiang Guannong Tomato Products Co. Ltd. |
| CONESA Group |
| COFCO Tunhe Tomato Co., Ltd. |
| Los Gatos Tomato Products |
| Sugal Group |
| Xinjiang Chalkis Company Ltd. |
| Others |
Value Network & Pricing Analysis
Natural gas input costs cascade through thermal concentration economics, compressing margins at European paste facilities while rewarding mechanical vapor recompression adopters with tiered pricing power against conventional evaporator operators. California's Central Valley and Italy's Emilia-Romagna processors translate captive tomato supply into contract premiums that Xinjiang-based bulk exporters cannot match on viscosity specifications.
Pricing Analysis
Unbundled paste pricing separates aseptic pouch premiums from drum-contained commodity tiers, with food service buyers absorbing format-specific premiums for labor reduction. Price differentiation rests on hot-break versus cold-break processing certification and EU F-Gas Regulation compliance status. Margins are tightening due to refrigerant retrofit deadlines across Italian and Spanish hubs. Ready meals manufacturers exhibit highest price sensitivity, while dried segment snack seasoning buyers accept formulation stability premiums.
Supply Chain Analysis
Single-source vulnerability sits with COFCO Tunhe's Xinjiang concentration for Central Asian bulk paste procurement. Geographic supply concentration draws from Italy, California, and China's Xinjiang corridor. Raw material dependencies center on processing tomato varietals, natural gas for thermal evaporation, and hydrofluorocarbon refrigerants. Tariff exposure looms for cross-border paste flows into Middle Eastern channels. Distribution runs through aseptic packaging specialists for food service, bulk drum logistics for industrial sauce manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pouch packaging specifications and EU F-Gas compliance certification separate premium processors from commodity bulk operators. Food service procurement shifts toward single-serve ambient-stable formats reward aseptic capability investments over evaporator scale.
For Market Incumbents: Anticipate refrigerant transition deadlines by phasing mechanical vapor recompression deployment ahead of EU F-Gas Regulation phase-down milestones. Defend margin position through backward integration into Xinjiang or California tomato supply bases. Channel control via food service pouch specification anchoring protects against drum-format price erosion.
For New Entrants and Emerging Players: EU F-Gas Regulation in Italy and Spain opens a window for modular MVR equipment providers to capture retrofit demand from legacy thermal facilities. Target India's BIS certification pathway for domestic food manufacturing growth. Pursue membrane-thermal hybrid technology licensing as go-to-market angle against incumbent evaporator suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where aseptic packaging line retrofit costs exceed standalone processor cash generation capacity. Five-to-ten year viability favors processors with demonstrated REACH compliance and food service contract anchoring. Acquisition target archetype: southern European specialists with pouch capability and refrigerated distribution relationships. Signal to watch is refrigerant retrofit capex announcements across Italian processing hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Deployment | EU F-Gas Regulation compliance cuts energy intensity for Italian paste processors. |
| Aseptic Pouch Line Retrofit | Food service specification shifts in California and Italy displace drum contracts. |
| Backward Integration into Xinjiang Supply | Captive tomato base secures Central Asian bulk paste channel dominance. |
| BIS Certification Investment | First-mover access to India's domestic sauce and ready meals manufacturing growth. |
| Membrane-Thermal Hybrid Licensing | Reverse osmosis pre-concentration reduces evaporator load for energy-conscious buyers. |
Research Methodology
Multiple input streams — primary interviews with tomato processing plant managers, food service procurement directors, and aseptic packaging equipment specialists; secondary validation through FDA acidified foods filings, USDA grading protocols, EFSA pesticide residue databases, and customs trade flows — were reconciled through bottom-up facility capacity modeling and top-down demand segmentation triangulation.
Data-stream reconciliation across product type, packaging technology, end-user channel, and regional regulatory cluster dimensions generated volume and value trajectories over the projection horizon. CAGRs were derived from facility-level throughput assumptions, energy cost scenario modeling, and food service contract migration patterns. Industry-specific forecast inputs included EU F-Gas Regulation phase-down schedules and ready meals manufacturing capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price volatility and Xinjiang supply disruption scenarios. Forecasts reflect documented assumptions about refrigerant transition timelines and pouch packaging adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Ingredients Market
Ingredients
Kilned Malt Market
Ingredients
Jojoba Oil Market
Ingredients
Oak Extract Market
Ingredients
North America Vegetable Oils Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Food Amino Acids Market
Ingredients
Astragalus Root Extract Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
North America Agar Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Lupin Flour Market
Ingredients
North America Milk Protein Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Middle East and Africa Lipids Market