
 Konjac Root Fiber Market | 2026-2036
Konjac Root Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Konjac Root Fiber Market Analytics
Chinese konjac root processing is consolidating around Hubei province's integrated milling and extraction facilities. Shimizu Chemical leverages its Japanese pharmaceutical-grade purification technology to command premium positioning in konjac capsules. Hubei Yizhi Konjac Biotechnology Co., Ltd. anchors domestic noodle and flour output through captive farm contracts across the Dabie Mountains. FMC Corporation competes in North American gelling-agent applications with food-stabilizer formulations derived from refined konjac glucomannan.
Konjac root fiber comprises a water-soluble polysaccharide called glucomannan, which can absorb up to fifty times its weight in water and forms thermo-irreversible gels under alkaline conditions; manufacturers extract this from Amorphophallus konjac tubers through wet-milling, precipitation, and drying stages for use as a viscosity modifier, bulking agent, and low-calorie food matrix. Konjac flour occupies the largest volume share among product types due to its ubiquity in Asian noodle production and Western gluten-free baking, while konjac capsules represent the fastest-expanding margin pool as pharmaceutical manufacturers seek plant-based alternatives to gelatin shells. The weight management application segment leads value growth as glucomannan's satiety-inducing properties attract formulation interest from dietary supplement brands.
China's SAMR enforces GB standards for konjac food additives, while Japan's MHLW via PMDA oversight governs konjac-derived pharmaceutical excipients; these frameworks elevate compliance costs for exporters but simultaneously filter out low-purity suppliers. The EU's EFSA novel food assessments and REACH chemical registration requirements for processed konjac derivatives create additional entry barriers for Asian manufacturers seeking European market access. Stakeholders must monitor evolving glucomannan purity thresholds across regulatory jurisdictions to align capital allocation with compliant capacity expansion.
Market Dynamics
China's MIIT food-grade purity standards are compressing margins for low-grade konjac processors while rewarding pharmaceutical-grade refiners with premium positioning. This regulatory bifurcation is accelerating consolidation around Hubei province's integrated extraction clusters and Japanese JIS-certified facilities.
Growth Catalysts
- Weight Management Formulations:Glucomannan's satiety-inducing properties are pulling dietary supplement brands into high-margin capsule production. EFSA novel food assessments are validating health claims for European market entry.
- GB Standards Harmonization:China's SAMR unified additive codes are reducing inter-provincial trade friction for konjac flour distributors. Standardized testing protocols cut supplier qualification cycles.
- Alkaline Gel Thermostability:Konjac's thermo-irreversible gel formation under alkaline conditions is displacing carrageenan in retort-pouch applications. Food manufacturers value the clean-label positioning.
Market Restraints
- Raw Material Geographic Concentration:Amorphophallus konjac tuber cultivation clusters in Hubei and Shaanxi provinces create monsoon-dependent supply risk. Single-region dependency exposes processors to climate volatility.
- REACH Registration Burden:ECHA chemical registration requirements for processed konjac derivatives impose six-figure compliance costs on Asian exporters. Small-scale mills lack capital for European market access.
- Gelatin Price Competition:Bovine and porcine gelatin shells retain cost advantage in pharmaceutical encapsulation. Plant-based alternatives face 40-60% raw material cost premiums.
Strategic Opportunities
- Clean-Label Bakery Substitution:Western gluten-free baking applications remain underpenetrated for konjac flour. Specialty millers can capture premium positioning against xanthan gum blends.
- Pharmaceutical Excipient Certification:Japan's PMDA oversight of konjac-derived excipients creates pathway for pharma-grade margin expansion. Dual certification with US FDA unlocks trans-Pacific supply contracts.
- Wet-Milling Automation Convergence:Integration of membrane filtration with precision drying is modularizing extraction economics. Mid-scale processors can achieve pharmaceutical purity without captive farming.
Industry Challenges
- Alkaline Processing Expertise Gap:Thermo-irreversible gel chemistry requires specialized chemical engineering talent. Universities in producing regions lack dedicated food polymer programs.
- Dual Certification Timeline Compression:Simultaneous pursuit of JIS pharmaceutical and GB food-grade standards extends validation cycles. Capital remains deployed in regulatory limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Konjac Root Fiber Market |
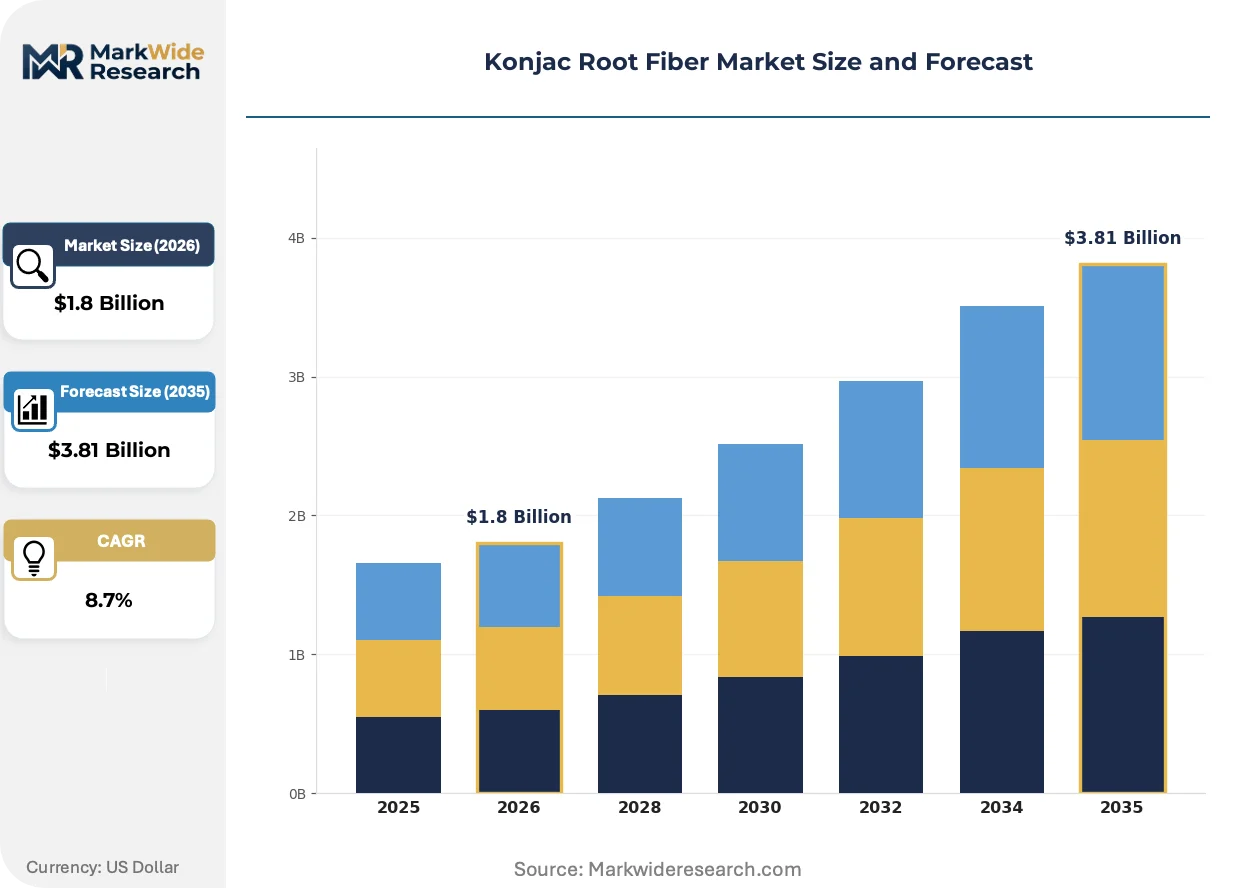
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Konjac Flour, Konjac Noodles, Konjac Gel, Konjac Capsules End User: Food Industry, Pharmaceutical Manufacturing, Cosmetics Sector, Dietary Supplements Application: Thickening Agent, Weight Management, Health Supplements, Culinary Use Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Food Shops |
| Companies Covered | Shimizu Chemical, Hubei Yizhi Konjac Biotechnology Co., Ltd., FMC Corporation, Shanghai Brilliant Gum Co., Ltd., Shaanxi Jintai Konjac Industrial Development Co., Ltd., Kowa, Gino Biotech, NOW Foods, Hubei Konson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Konjac Root Fiber Market Evolving Landscape
Extraction technology maturation and regulatory divergence are fragmenting competitive positioning between commodity flour suppliers and pharmaceutical-grade refiners. Three developments are reshaping capability requirements.
Membrane filtration systems paired with spray-drying precision are modularizing konjac glucomannan purification economics. Pharmaceutical manufacturers in Japan and South Korea are adopting these systems to secure PMDA-compliant excipient supply. The technology is compressing minimum efficient scale for pharma-grade production, enabling mid-cap entrants to challenge integrated agricultural processors.
EFSA's evolving novel food assessment protocols for konjac-derived ingredients are tightening dossier requirements for European market access. Manufacturers must now submit comprehensive toxicological data and processing method disclosures. Asian exporters with existing REACH registrations are accelerating purity upgrades to preempt regulatory exclusion.
Ingredient buyers in dietary supplements are consolidating supplier relationships around vertically integrated processors with captive organic certification. Direct farm partnerships are displacing spot-market tuber procurement. This concentration is most visible in North American contract manufacturing, where brands demand single-source traceability for clean-label positioning.
Konjac Root Fiber Market Segmentation
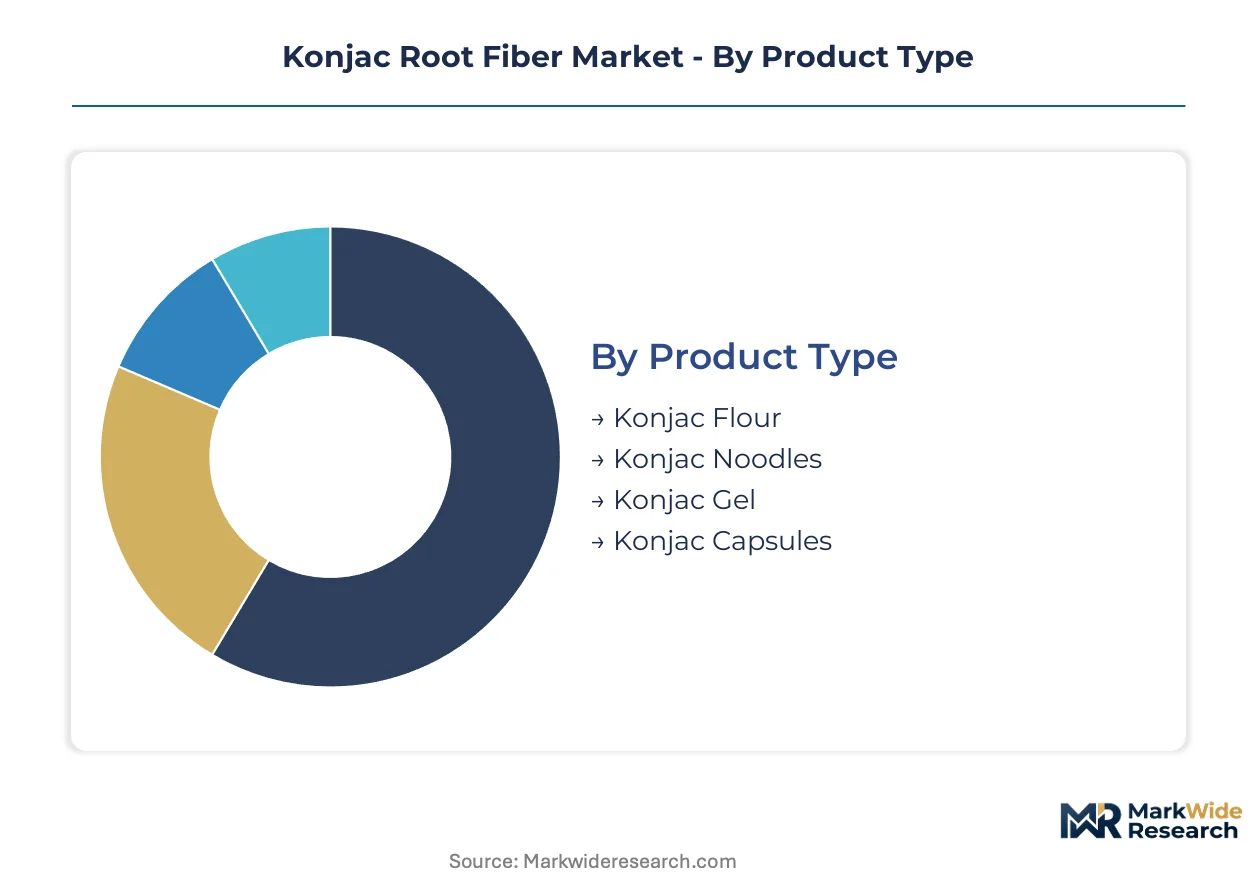
Konjac root fiber segments diverge sharply by purity threshold and end-use specification. Food-grade flour commands volume scale while pharmaceutical-grade capsules capture margin premiums. Understanding these tiered demand pools reveals where capital allocation yields asymmetric returns.
Product Type:
Hubei province's integrated extraction clusters supply divergent purity grades across product categories. Wet-milling automation is compressing minimum efficient scale for premium segments.
- Konjac Flour:The dominant volume category comprises milled Amorphophallus konjac tubers with 40-60% glucomannan content. China's SAMR GB standards govern additive-grade flour for noodle production in Hubei and Shaanxi processing hubs. Climate volatility in these provinces creates raw material supply risk.
- Konjac Capsules:Pharmaceutical-grade shells demand 90%+ glucomannan purity with PMDA-compliant excipient certification. Japanese and South Korean manufacturers pay premium pricing for plant-based gelatin alternatives. EFSA novel food assessments are tightening European entry requirements.
- Konjac Noodles:Shirataki-style products utilize lower-purity flour for calorie-reduced Asian cuisine.
- Konjac Gel:Thermo-irreversible alkaline gels displace carrageenan in retort-pouch clean-label applications.
Today's leader: Konjac Flour. Tomorrow's challenger: Konjac Capsules.
End User:
Customer type determines specification stringency and contract structure. Pharmaceutical buyers impose batch-level traceability that food manufacturers rarely require.
- Food Industry:Noodle manufacturers and gluten-free bakeries constitute the foundational demand base. Hubei Yizhi Konjac Biotechnology anchors domestic supply through captive Dabie Mountains farm contracts. Standardized GB testing protocols are reducing supplier qualification friction.
- Dietary Supplements:Weight management brands formulate glucomannan capsules for satiety positioning. North American contract manufacturers demand single-source organic traceability. Direct farm partnerships are displacing spot-market tuber procurement.
- Pharmaceutical Manufacturing:Excipient-grade supply requires dual JIS and FDA certification.
- Cosmetics Sector:Skincare applications utilize konjac sponge formats with lower purity tolerance.
Food Industry absorbs the tonnage. Dietary Supplements capture the margin expansion.
Application:
Functional properties—viscosity, gelation, and satiety induction—map directly to application value capture. Thermostability under alkaline conditions creates technical moats in specific use cases.
- Weight Management:Glucomannan's water-absorption capacity triggers gastric satiety signaling. Supplement brands in North America and Europe are expanding capsule SKU portfolios. EFSA health claim validations are accelerating European market entry.
- Thickening Agent:Konjac displaces xanthan gum and carrageenan in clean-label formulations. Retort-pouch food manufacturers value thermo-irreversible gel stability. Alkaline processing expertise limits viable supplier pools.
- Health Supplements:General wellness positioning requires lower purity thresholds than pharmaceutical excipients.
- Culinary Use:Traditional Asian cooking applications prioritize texture modification over purity metrics.
Weight Management commands the steepest expansion trajectory. Thickening Agent defends the installed base.
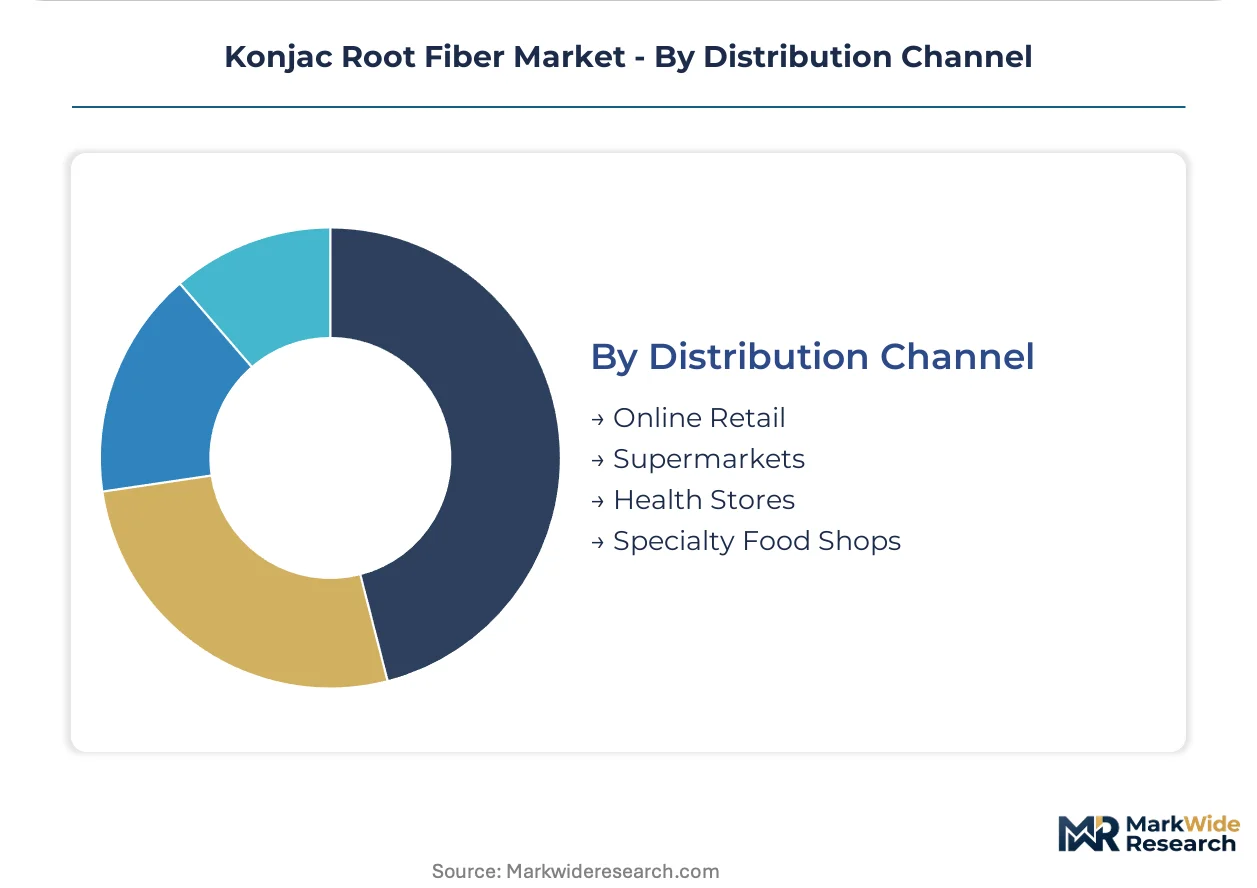
Distribution Channel:
Channel selection reflects buyer sophistication and purchase frequency. Direct procurement dominates industrial volumes while retail fragmentation serves consumer segments.
- Online Retail:Direct-to-consumer supplement brands leverage e-commerce for clean-label konjac capsule distribution. Amazon and specialized wellness platforms are consolidating North American supplement sales. Digital traceability tools satisfy organic certification display requirements.
- Supermarkets:Mass-market konjac noodles and flour reach household buyers through Asian grocery chains. Hubei-based processors maintain direct relationships with retail procurement teams. Private-label penetration remains limited by purity standardization gaps.
- Health Stores:Specialty retailers curate premium supplement assortments with third-party certification.
- Specialty Food Shops:Gourmet and gluten-free boutiques source artisanal konjac flour blends.
Supermarkets move the volume. Online Retail scales the premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands raw material dominance through Hubei and Shaanxi cultivation clusters, while Japan's pharmaceutical-grade refiners capture margin premiums through JIS-certified excipient production. Regulatory divergence between MIIT food-grade standards and PMDA pharmaceutical frameworks creates tiered market access conditions across Asia-Pacific.
China
Hubei province's integrated milling facilities supply global noodle manufacturers with GB-standard konjac flour. SAMR unified additive codes streamline inter-provincial distribution for domestic food processors. The Dabie Mountains farm belt anchors captive raw material contracts for vertically integrated extractors.
Japan
PMDA oversight of konjac-derived pharmaceutical excipients drives premium pricing for capsule-grade glucomannan. METI industrial policy supports precision extraction technology adoption among domestic refiners. Osaka-based chemical specialists leverage JIS quality frameworks to supply South Korean and Taiwanese pharma manufacturers.
United States
FDA dietary supplement regulations attract North American brands formulating glucomannan capsules for weight management positioning. USDA organic certification requirements shape procurement patterns among contract manufacturers. California and New York Metro wellness markets drive direct-to-consumer distribution through specialized e-commerce platforms.
Germany
EFSA novel food assessments determine market entry viability for konjac-derived ingredients across EU member states. ECHA REACH registration requirements impose compliance cost barriers on Asian exporters seeking European chemical-grade applications. Bavaria's food technology cluster hosts pilot-scale extraction research for clean-label bakery applications.
South Korea
MFDS pharmaceutical regulations align with Japanese PMDA standards for excipient-grade konjac imports. Seoul Capital Area dietary supplement manufacturers source high-purity glucomannan for domestic capsule production. Busan-Ulsan chemical processing hubs evaluate membrane filtration adoption for in-house pharmaceutical-grade refining.
Konjac Root Fiber Market Competitive Landscape
Hubei-based agricultural processors anchor one tier; Japanese pharmaceutical specialists hold premium positioning through certification arbitrage. Market structure bifurcates between volume-driven flour suppliers serving Asian food manufacturers and purity-focused refiners capturing pharmaceutical margins. Three archetypes dominate: integrated farm-to-flour operators, JIS-certified excipient specialists, and North American supplement distributors. Capacity expansion in membrane filtration technology and backward integration into captive farming represent the primary competitive vectors.
Within the integrated agricultural tier, Hubei Yizhi Konjac Biotechnology Co., Ltd. and Shaanxi Jintai Konjac Industrial Development Co., Ltd. exemplify Chinese processors leveraging provincial raw material concentration. Shimizu Chemical occupies a position among Japanese pharmaceutical-grade refiners commanding excipient premiums through JIS compliance. FMC Corporation represents North American chemical industry participation in food-stabilizer applications.
| Leading Market Players |
|---|
| Shimizu Chemical |
| Hubei Yizhi Konjac Biotechnology Co., Ltd. |
| FMC Corporation |
| Shanghai Brilliant Gum Co., Ltd. |
| Shaanxi Jintai Konjac Industrial Development Co., Ltd. |
| Kowa |
| Gino Biotech |
| NOW Foods |
| Hubei Konson |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap processors in Hubei province anchor upstream supply discipline through captive Dabie Mountains farm contracts, translating raw material control into pricing power against spot-market dependent competitors while GB-standard compliance costs filter out low-grade entrants.
Pricing Analysis
Capacity additions in Hubei province are reshaping price floors for food-grade konjac flour as wet-milling automation compresses minimum efficient scale. Three-tier pricing structure across pharmaceutical-grade, food-additive, and feed-grade levels separates PMDA-certified excipients commanding premium positioning from commodity noodle flour facing cost compression. Pricing pressure stems from REACH registration burdens blocking Asian millers from European chemical-grade applications. Food manufacturers exhibit highest price sensitivity due to thin margins in Asian noodle production, while pharmaceutical buyers absorb premiums for JIS-compliant capsule supply.
Supply Chain Analysis
Direct-to-pharma channels handle high-purity excipient demand from Japanese and South Korean manufacturers, while bulk distributors serve Asian food processors. Geographic concentration centers on China, Japan, and South Korea as the dominant production and refinement triangle. Raw material supply draws from Amorphophallus konjac tuber cultivation, membrane filtration equipment, and alkaline processing chemicals. Single-region dependency on Hubei and Shaanxi provinces creates monsoon-exposed supply vulnerability. Distribution runs through integrated agricultural processors with backward farm control for traceability-demanding supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA novel food assessments and PMDA excipient certifications are accelerating demand bifurcation between commodity and premium tiers.
For Market Incumbents: Hedge against gelatin price competition by securing dual JIS-FDA pharmaceutical certification before capital deployment in regulatory limbo extends validation cycles. Deepen upstream control over Dabie Mountains farm belts to defend organic traceability positioning against North American contract manufacturers consolidating supplier relationships. Membrane filtration technology adoption represents the critical capability lever for margin defense. For New Entrants and Emerging Players: Membrane filtration convergence offers entry wedge for mid-scale processors seeking pharmaceutical purity without captive farming infrastructure. Target Western gluten-free baking applications where konjac flour remains underpenetrated against xanthan gum blends. Pursue clean-label bakery positioning through specialty miller partnerships as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity flour suppliers facing GB-standard compliance cost compression while pharmaceutical-grade refiners command scarcity premiums. Five-to-ten year viability favors processors with dual certification pathways and membrane filtration capability. Watch EFSA purity threshold upgrades as the signal indicating European market access inflection for Asian exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Adoption | PMDA-compliant excipient production becomes achievable for mid-scale Hubei processors without agricultural integration. |
| Dual JIS-FDA Certification Investment | Trans-Pacific pharmaceutical supply contracts unlock for Japanese refiners serving South Korean capsule manufacturers. |
| Backward Farm Integration | Captive Dabie Mountains contracts satisfy North American organic traceability demands from supplement brands. |
| REACH Registration Completion | European chemical-grade market access opens for Asian mills previously blocked by six-figure compliance costs. |
| Clean-Label Bakery Partnership | Western gluten-free applications capture premium positioning against xanthan gum through specialized konjac flour blends. |
Research Methodology
Multiple input streams — primary interviews with extraction plant managers, procurement leads at dietary supplement contract manufacturers, and distribution channel partners; secondary validation through SAMR GB standard filings, Japanese PMDA excipient registrations, and customs trade data — were reconciled through bottom-up capacity modeling and top-down demand triangulation across the analysis window.
Historical volume trajectories were cross-referenced against panel input from industry participants to derive expansion rates across product type, end user, application, and distribution channel segmentation dimensions. Glucomannan purity thresholds and regulatory certification timelines served as industry-specific forecast inputs throughout the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel food assessment rulings and climate volatility in Hubei cultivation zones. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Wheat Gluten Market
Ingredients
Lentils Flour Market
Ingredients
Lipids Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Caramel Malt Market
Ingredients
Yeast Derivatives Market
Ingredients
Bouillon Cubes Market
Ingredients
Organic Starch Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
United States Gelatin Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Salad Oil Market
Ingredients
Konjac Flour Market
Ingredients
Europe Vanilla Beans and Extract Market