
 Homeopathic Medicine Market | 2026-2036
Homeopathic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Homeopathic Medicine Market Outlook
Market Context
Pharmaceutical-grade dilution standards is rotating the Homeopathic Medicine Market toward higher purity tiers. Boiron leverages its Lyon manufacturing complex to sustain European distribution density. Dr. Willmar Schwabe GmbH anchors German market presence through specialized tincture production. Weleda differentiates via biodynamic sourcing protocols that command premium positioning.
Technical Definition and Segment Structure
Homeopathic medicine employs serial dilution and succussion of natural substances—typically plant, mineral, or animal-derived—at potencies ranging from mother tinctures to 30C and beyond, to stimulate self-healing responses without pharmacological toxicity. Liquids and tablets occupy the largest volume pools, though granules represent the fastest-growing format due to pediatric palatability advantages. Pain Management applications generate concentrated margin pools, while Mental Health segments attract premium pricing through practitioner-channel exclusivity.
Regulatory Environment
The European Medicines Agency enforces Good Manufacturing Practice for homeopathic products under Directive 2001/83/EC, while the FDA regulates these medicines as drugs under the Federal Food, Drug, and Cosmetic Act with distinct compliance pathways. India's Central Drugs Standard Control Organization mandates Ayush certification for domestic manufacture, creating layered market access requirements. Stakeholders must monitor evolving pharmacovigilance obligations as regulators tighten post-market surveillance frameworks.
Market Dynamics
Pharmaceutical-grade dilution standards are rotating the Homeopathic Medicine Market toward higher purity tiers, forcing manufacturers to reconfigure production workflows around serial succussion protocols and third-party assay verification.
Growth Catalysts
- Pediatric wellness prioritization:Households with children under twelve are expanding homeopathic medicine cabinets, particularly for fever management and sleep support applications.
- EU Green Deal compliance:REACH-aligned sourcing mandates are accelerating biodynamic cultivation partnerships across Central European supplier networks.
- Practitioner-channel expansion:Naturopathic clinics in Germany and France are integrating homeopathic protocols into chronic pain management workflows.
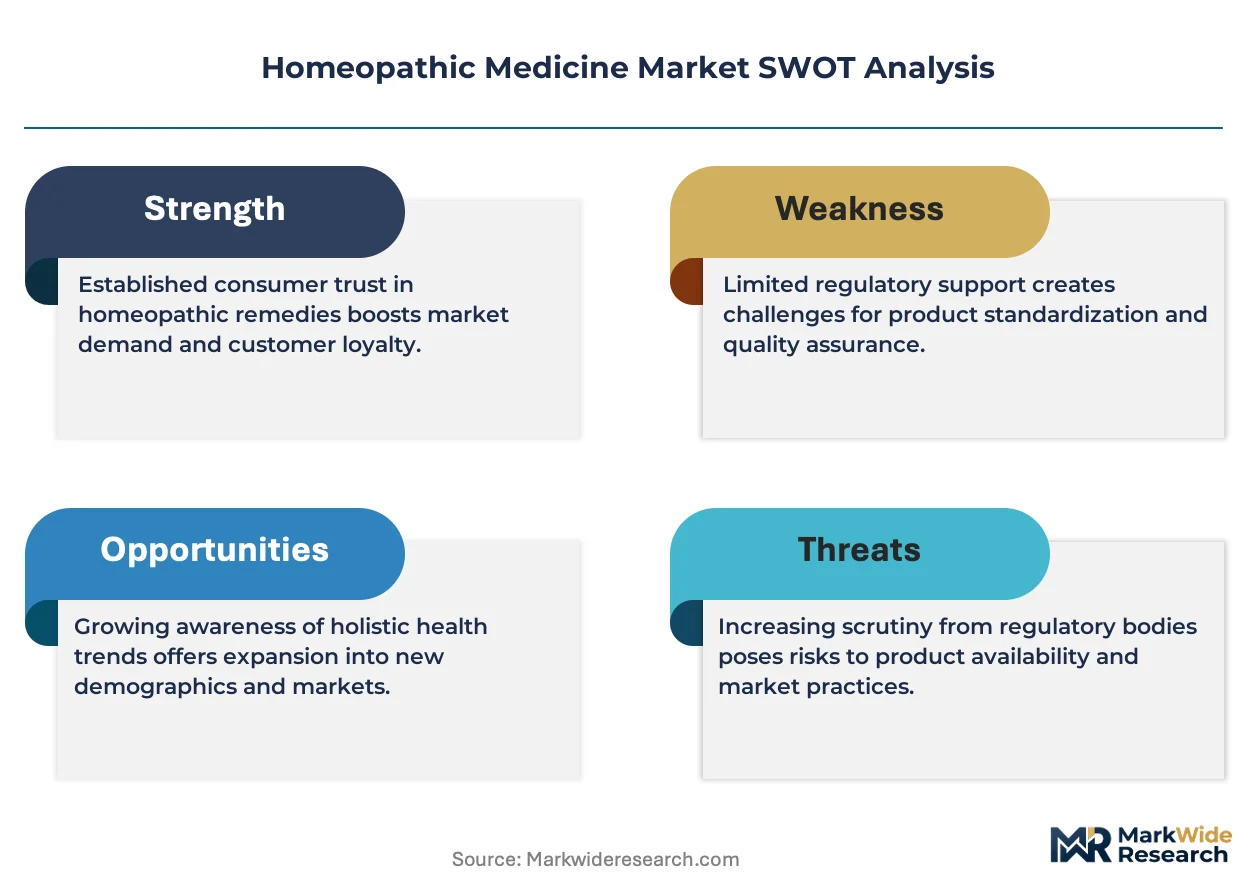
Market Restraints
- Ethanol supply volatility:Mother tincture production depends on pharmaceutical-grade ethanol, where input costs fluctuate with biofuel policy shifts.
- Lactose excipient concentration:Tablet manufacturing relies on a narrow supplier base concentrated in the Netherlands and northern Germany.
- Clinical evidence thresholds:EMA pharmacovigilance requirements impose documentation burdens that small-scale manufacturers struggle to satisfy.
Strategic Opportunities
- Rural India penetration:Ayush-certified distribution networks remain underdeveloped in Madhya Pradesh and Bihar states.
- Mental health application expansion:Anxiety and stress formulations command premium positioning through practitioner exclusivity arrangements.
- Direct-to-patient digital channels:Telehealth-integrated prescribing platforms are opening subscription-based revenue streams.
Industry Challenges
- Trained pharmacist scarcity:Serial dilution and succussion protocols require specialized compounding skills that vocational programs are not producing at sufficient scale.
- Multi-jurisdiction labeling complexity:Products crossing German-French-Swiss borders must reconcile divergent potency notation systems and patient information requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeopathic Medicine Market |
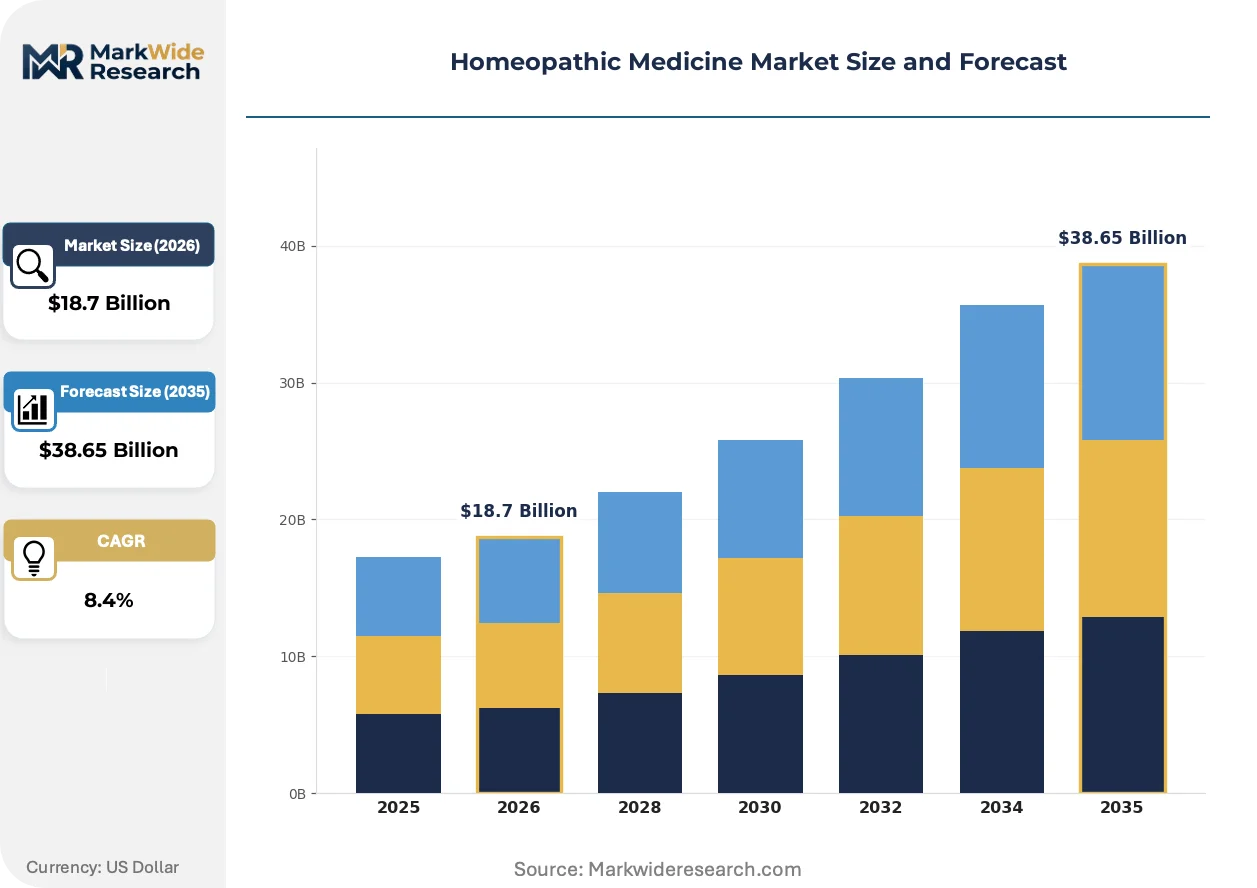
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquids, Tablets, Granules, Ointments End User: Households, Clinics, Pharmacies, Wellness Centers Application: Allergy Relief, Digestive Disorders, Pain Management, Mental Health Delivery Mode: Oral, Topical, Injectable, Sublingual |
| Companies Covered | Boiron, Biologische Heilmittel Heel GmbH, A Nelson & Co Ltd, SBL Pvt. Ltd., Homeocan, Dr. Willmar Schwabe GmbH, Hyland's, Hahnemann Laboratories, Weleda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeopathic Medicine Market Strategic Shifts
Granule-based delivery formats are reshaping formulation priorities, while regulatory digitization and prescriber education platforms are reconfiguring how products reach end-users.
Nanoparticle detection methods are supplanting traditional spectroscopic assays for verifying homeopathic dilution levels. German manufacturers are adopting these techniques to satisfy EMA documentation requirements. The shift is compressing quality-control timelines from weeks to days while raising capital barriers for smaller producers.
REACH substance restriction amendments are forcing reformulation of certain mineral-based mother tinctures. The ECHA evaluation process is disqualifying several traditionally used compounds from new product registrations. German and French manufacturers are responding by accelerating plant-derived substitute development in their Lyon and Karlsruhe facilities.
Subscription-based replenishment models are displacing pharmacy counter purchasing for chronic-condition formulations. Practitioner networks in Bavaria and Baden-Württemberg are piloting automated refill systems tied to telehealth follow-ups. This pattern is most visible in pain management and allergy segments where dosing regimens extend across multiple months.
Homeopathic Medicine Market Segmentation
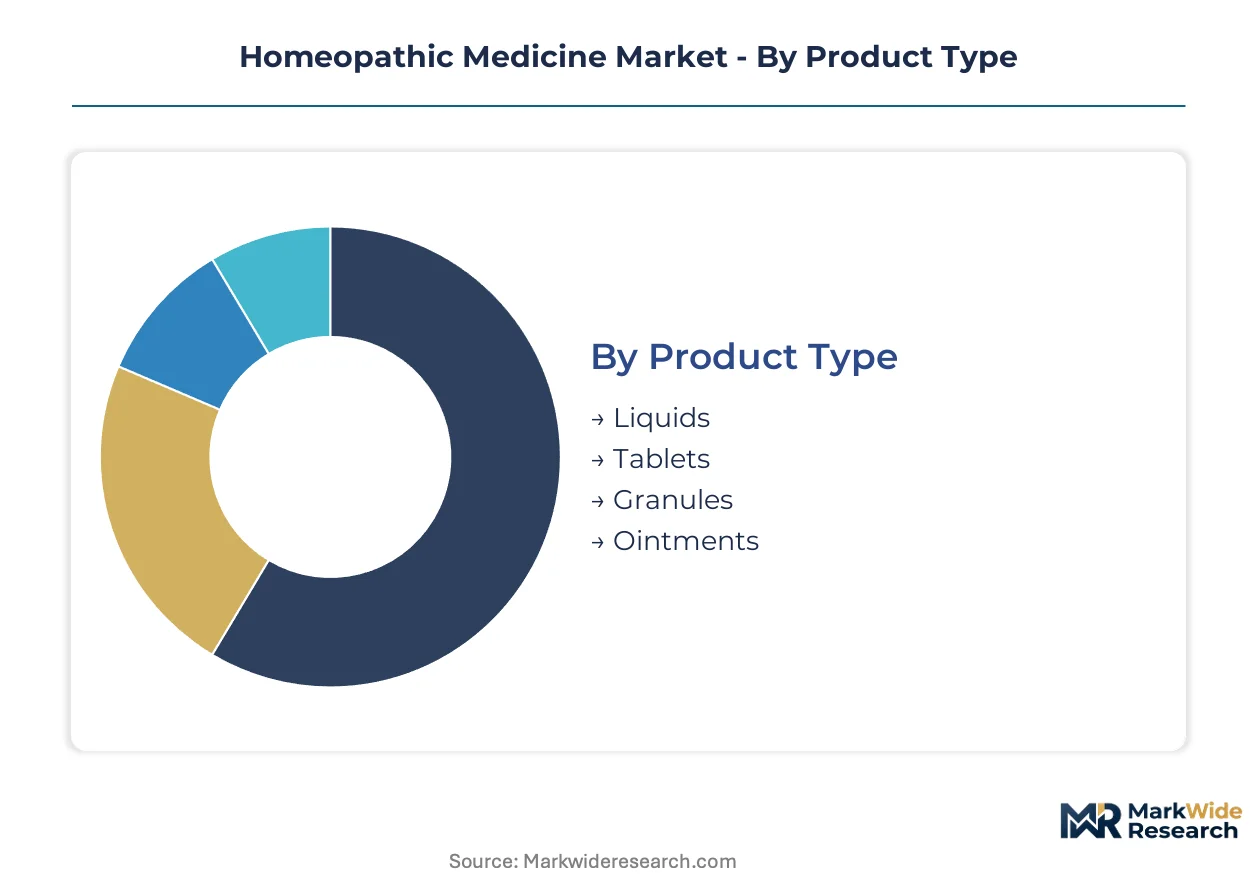
Homeopathic medicine segmentation reveals distinct substitution dynamics across delivery formats and patient access points. Product type and end-user channel configurations determine competitive vulnerability to conventional pharmaceutical alternatives.
Product Type:
Substitution pressure from over-the-counter synthetics is most acute in tablet formats, while liquid preparations retain stronger practitioner loyalty through dosing flexibility.
- Liquids:Mother tinctures and potentized dilutions in ethanol or water bases allow precise dose titration for pediatric and geriatric populations. Demand concentrates in German naturopathic clinics where practitioners customize succussion protocols for chronic conditions.
- Tablets:Lactose-based compressed forms with standardized potencies suit pharmacy self-selection. Household penetration in France and Belgium faces erosion from private-label analgesics with comparable price positioning.
- Granules:Sucrose or lactose carriers impregnated with liquid dilutions offer pediatric palatability advantages in sugar-sensitive formulations.
- Ointments:Topical preparations combining homeopathic tinctures with herbal extracts serve dermatological applications in Swiss and Austrian pharmacy channels.
Liquids anchor the volume base while granules gain share at the steepest rate.
End User:
Margin capture varies sharply across patient access points, with direct clinical relationships supporting premium pricing versus commoditized retail transactions.
- Households:Direct-to-consumer purchases for acute self-limiting conditions—fever, minor injuries, seasonal allergies—drive replenishment frequency. German households with children under twelve maintain the deepest medicine cabinets.
- Clinics:Naturopathic and integrative medicine practices in Bavaria and Baden-Württemberg prescribe chronic-condition protocols with scheduled follow-up visits.
- Pharmacies:French and Belgian pharmacy counters represent the primary point of first contact for symptom-driven purchases without prior consultation.
- Wellness Centers:Spa and preventive health facilities in Austria and Switzerland incorporate homeopathic consultations into holistic programming.
Clinics command the highest per-patient revenue while households generate the broadest volume throughput.
Application:
Clinical evidence requirements and reimbursement status fragment addressable market size across therapeutic categories.
- Pain Management:Arnica and Rhus tox formulations for musculoskeletal complaints attract the most consistent practitioner prescribing in German sports medicine and physiotherapy networks.
- Mental Health:Anxiety and sleep disorder protocols—Gelsemium, Ignatia, Coffea cruda—command exclusivity premiums through limited pharmacy distribution tied to prescriber relationships.
- Allergy Relief:Seasonal rhinitis preparations face direct competition from second-generation antihistamines with faster onset claims.
- Digestive Disorders:Nux vomica and Lycopodium protocols for functional dyspepsia compete with proton pump inhibitor accessibility.
Pain management anchors the volume base while mental health applications expand most quickly through practitioner channel deepening.
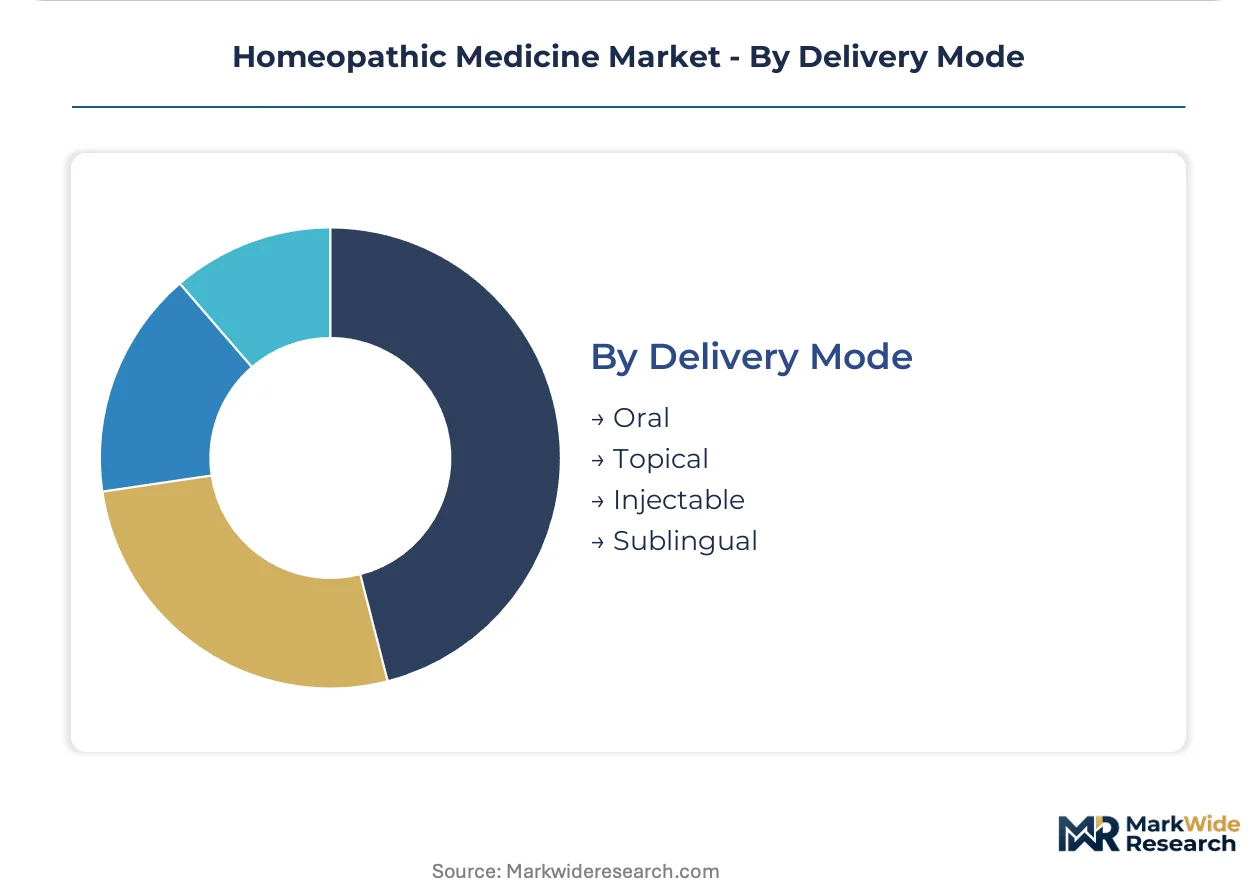
Delivery Mode:
Patient compliance and onset expectations shape format selection, with convenience trade-offs against perceived efficacy.
- Oral:Drops, tablets, and granules administered by mouth constitute the standard delivery pathway for systemic conditions across all European markets.
- Topical:Creams, gels, and ointments applied to skin or mucous membranes serve localized conditions with reduced systemic exposure concerns.
- Sublingual:Rapid buccal absorption of granules or liquids appeals to patients seeking faster symptom relief without gastrointestinal transit.
- Injectable:Subcutaneous or intramuscular administration of homeopathic preparations persists in select German and Swiss clinical settings despite regulatory scrutiny.
Oral delivery anchors the volume base while sublingual formats climb the fastest through pediatric and geriatric compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German homeopathic exports flow primarily into French and Swiss pharmacy networks, with Lyon and Basel serving as the dominant redistribution hubs for continental European supply.
Germany
Naturopathic clinic density in Bavaria and Baden-Württemberg sustains practitioner-channel demand for chronic pain protocols. The Federal Institute for Drugs and Medical Devices enforces pharmacovigilance documentation under the German Medicines Act. Karlsruhe hosts Dr. Willmar Schwabe GmbH's specialized tincture production complex serving domestic and export markets.
France
Pharmacy counter self-selection drives volume for acute-condition tablets and granules in Paris and Lyon metropolitan areas. ANSM oversees homeopathic registration under the French Public Health Code with distinct OTC classification pathways. Boiron's Lyon manufacturing complex anchors European distribution density through automated succussion lines.
Switzerland
Wellness center integration in Zurich and Geneva generates premium positioning for biodynamic-sourced formulations. Swissmedic mandates GMP compliance for all imported homeopathic preparations with batch-specific assay requirements. Basel clusters pharmaceutical logistics specialists handling cross-border distribution into German and Austrian markets.
India
Ayush-certified manufacturing in Madhya Pradesh and Bihar states targets rural household penetration for fever management applications. CDSCO mandates dual certification for export-oriented producers seeking European market access. Mumbai serves as the primary consolidation point for SBL Pvt. Ltd. distribution across domestic pharmacy networks.
United States
Direct-to-consumer digital channels in California and New York Metro expand subscription-based replenishment for pediatric sleep support formulations. FDA regulates homeopathic medicines as drugs under the Federal Food, Drug, and Cosmetic Act with distinct compliance pathways from conventional pharmaceuticals. Hyland's maintains West Coast distribution infrastructure serving naturopathic practitioner networks.
Homeopathic Medicine Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and channel access dimensions. The vendor base concentrates around three tiers: multinational pharmaceutical-grade producers, regional tincture specialists, and biodynamic sourcing purists. Strategic archetypes include succussion-technology licensors, practitioner-network orchestrators, and direct-to-patient platform operators. Capacity expansion in Lyon and Karlsruhe facilities parallels M&A activity targeting Indian Ayush-certified manufacturers.
Within the European multinational tier, Boiron and Dr. Willmar Schwabe GmbH exemplify divergent scale strategies. Boiron anchors volume production through automated Lyon facilities serving pharmacy chains across France, Belgium, and Switzerland. Dr. Willmar Schwabe GmbH occupies a specialized position in Karlsruhe focused on practitioner-channel tincture protocols with customized potency configurations. Both represent the consolidation pressure facing smaller German and French competitors lacking capital for EMA-mandated nanoparticle detection equipment.
| Leading Market Players |
|---|
| Boiron |
| Biologische Heilmittel Heel GmbH |
| A Nelson & Co Ltd |
| SBL Pvt. Ltd. |
| Homeocan |
| Dr. Willmar Schwabe GmbH |
| Hyland's |
| Hahnemann Laboratories |
| Weleda |
| Others |
Value Chain & Pricing Dynamics
Plant-derived substitute development for REACH-restricted mineral tinctures is simultaneously relocating active ingredient sourcing toward Central European biodynamic farms and compressing margin structures for legacy mineral-based formulations. This substitution dynamic concentrates procurement power with certified organic suppliers in Germany and France while forcing manufacturers to absorb higher input costs or surrender price competitiveness.
Pricing Analysis
Next-generation nanoparticle verification technology commands premium positioning against legacy spectroscopic assay protocols, while mother tincture pricing stratifies across pharmaceutical-grade ethanol purity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and practitioner-channel exclusivity arrangements. Pricing pressure stems from ethanol supply volatility tied to biofuel policy shifts in major producing regions. Household purchasers through pharmacy counters exhibit highest price sensitivity, while clinic-based chronic-condition protocols support lowest sensitivity through subscription bundling.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is elevating inbound logistics costs for pharmaceutical-grade ethanol shipments from Brazilian and US Gulf suppliers. Active ingredient concentration rests on Germany, France, and India as the dominant manufacturing geographies, with mother tincture production drawing from specialized cultivators in the Netherlands and northern Germany. Single-source vulnerability permeates lactose excipient supply given narrow supplier concentration. Distribution runs through Lyon and Karlsruhe as continental European redistribution hubs serving pharmacy networks across multiple jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as pediatric wellness demand diversifies beyond legacy tablet formats toward granule and liquid preparations with customized palatability profiles.
For Market Incumbents: Secure EMA-compliant nanoparticle detection capacity at Karlsruhe and Lyon facilities before smaller competitors exhaust financing options. Consolidate practitioner-channel relationships through exclusive chronic-condition protocol licensing. Counter subscription-based entrant threats by integrating automated refill systems with existing clinic networks. For New Entrants and Emerging Players: Telehealth-integrated prescribing platforms represent the most penetrable service-layer gap where incumbents under-serve rural Indian households and direct-to-patient segments. Target Ayush-certified distribution in Madhya Pradesh and Bihar with fever management formulations. Pursue partnership-based market entry with established logistics specialists rather than greenfield manufacturing investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European succussion-technology licensors seeking exit liquidity amid capital equipment upgrade cycles. Five-to-ten year viability hinges on regulatory digitization compliance rather than clinical evidence generation. Monitor EMA pharmacovigilance documentation burden intensity as inflection indicator for smaller manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoparticle Detection Adoption | German manufacturers deploy EMA-compliant verification to compress quality-control timelines from weeks to days. |
| Biodynamic Cultivation Partnerships | REACH-aligned sourcing mandates accelerate supplier network reconfiguration across Central European organic farms. |
| Subscription-Based Replenishment Models | Bavarian practitioner networks pilot automated refill systems tied to telehealth follow-up protocols. |
| Ayush-Certified Manufacturing Scale-Up | Indian producers expand Madhya Pradesh and Bihar capacity for rural household fever management penetration. |
| Practitioner-Channel Exclusivity Arrangements | Mental health formulations command premium positioning through limited pharmacy distribution tied to prescriber relationships. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EMA regulatory filings, CDSCO Ayush certification records, and REACH substance restriction amendments. Interviews with naturopathic clinic directors, pharmaceutical procurement managers at Boiron and Dr. Willmar Schwabe GmbH, biodynamic cultivation cooperative leaders, and pharmacy chain category buyers informed demand-side calibration. Bottom-up volume estimates from product-level potency configurations triangulate against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include delivery format, end-user channel, therapeutic application, and regional regulatory cluster across the analysis window. CAGRs derive from trend extrapolation of pediatric wellness adoption curves, practitioner-channel expansion rates, and digital subscription penetration patterns. Industry-specific forecast inputs incorporate ethanol price volatility indices and EMA documentation burden trajectory assumptions.
Underlying assumptions cover sustained REACH enforcement intensity and stable biofuel policy frameworks, with deviation risk concentrated in pharmacovigilance requirement tightening and lactose excipient supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Cold Laser Therapy Market