
 Homeopathic Veterinary Medicines Market | 2026-2036
Homeopathic Veterinary Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
Homeopathic Veterinary Medicines Market Outlook
HPUS certification compliance is rotating as the primary gatekeeper for manufacturer credibility in this sector. Boiron Laboratories leverages its established pharmacopeial expertise to sustain quality benchmarks across European and North American supply chains. Guna SPA anchors its portfolio in injectable and oral homeopathic preparations for large-animal veterinary use. Freemans Homeopathy Pharmacy competes through specialized compounding capabilities that serve independent veterinary practitioners.
Homeopathic veterinary medicines are ultradilute preparations—typically 6X to 30C potencies—derived from botanical, mineral, or zoological sources, prepared through sequential dilution and succussion to yield formulations containing negligible molecular concentrations of original substance; their commercial purpose centers on stimulating endogenous healing responses in animals without pharmacological toxicity or residue concerns. Liquid formulations dominate volume due to ease of administration across species, while tablets command premium positioning in companion animal channels where owner compliance drives repeat purchase behavior. Preventive care applications are expanding fastest as livestock producers seek residue-free alternatives ahead of export certification requirements.
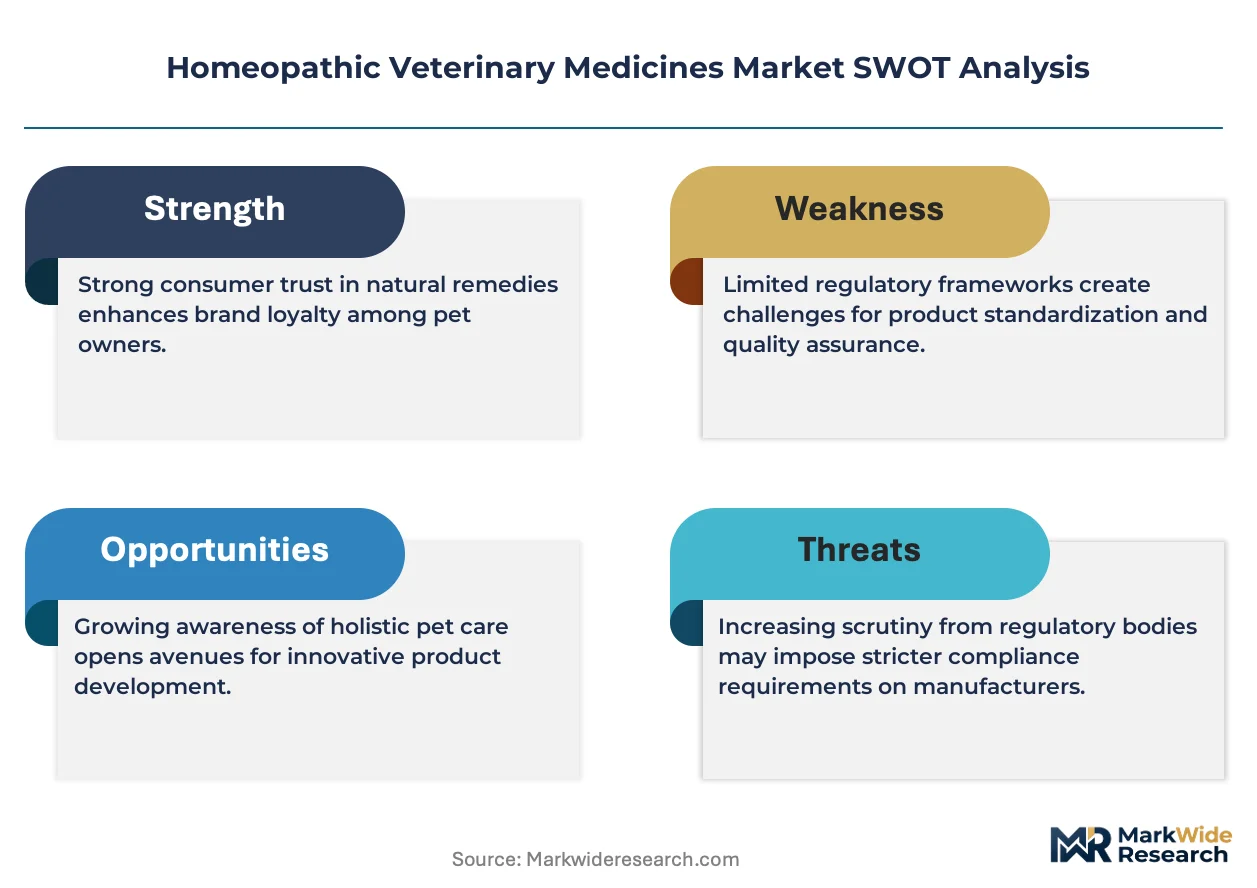
The FDA Center for Veterinary Medicine maintains oversight of homeopathic product labeling and manufacturing claims, while the EMA's Committee for Veterinary Medicinal Products evaluates borderline homeopathic registrations under divergent national interpretations across EU member states. India's CDSCO and the country's national pharmaceutical regulator are developing Ayurveda-Homeopathy convergence guidelines that could reshape export eligibility for domestic manufacturers. Stakeholders must monitor how evolving pharmacovigilance reporting obligations for "natural" veterinary products will alter liability exposure and insurance requirements.
Market Dynamics
The EU Green Deal and REACH frameworks are tightening scrutiny of synthetic veterinary actives, redirecting formulation interest toward plant-derived and mineral-based alternatives and reshaping competitive positioning across Western European supply chains.
Growth Catalysts
- Companion animal insurance coverage:Pet insurance policies in Germany and France increasingly reimburse complementary veterinary therapies, expanding addressable demand for homeopathic protocols in clinical settings.
- Residue-free export certification:Livestock producers facing EU and Middle Eastern import standards are adopting preventive homeopathic regimens to eliminate pharmaceutical residues from meat and dairy supply chains.
- HPUS pharmacopeial alignment:Manufacturers achieving Homeopathic Pharmacopoeia of the United States certification gain preferred supplier status with North American veterinary distributors and institutional buyers.
Market Restraints
- Raw material sourcing volatility:Botanical source materials including Arnica montana and Calendula officinalis face harvest fluctuations and climate-dependent yield variations in Eastern European cultivation zones.
- Regulatory fragmentation:EMA's Committee for Veterinary Medicinal Products evaluates borderline homeopathic registrations under divergent national interpretations across EU member states, creating compliance complexity.
- Scientific efficacy skepticism:Veterinary schools and mainstream practitioner associations in the United States maintain institutional resistance to ultradilute preparations lacking conventional pharmacological evidence bases.
Strategic Opportunities
- India's regulatory convergence:CDSCO development of Ayurveda-Homeopathy integration guidelines could unlock export eligibility for domestic manufacturers targeting Commonwealth veterinary markets.
- Injectable large-animal formats:Cattle and equine operations seeking alternatives to antibiotic growth promoters represent underpenetrated demand for parenteral homeopathic preparations in Brazilian and Australian beef sectors.
- Direct-to-practitioner digital channels:Specialized compounding pharmacies are bypassing traditional distribution tiers through veterinary telemedicine platforms and subscription replenishment models.
Industry Challenges
- Pharmacovigilance reporting obligations:Evolving adverse event documentation requirements for natural veterinary products are expanding liability exposure and professional indemnity insurance costs for manufacturers.
- Succussion equipment standardization:Mechanical potentization devices lack unified calibration protocols, creating batch-to-batch variability risks that complicate GMP compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeopathic Veterinary Medicines Market |
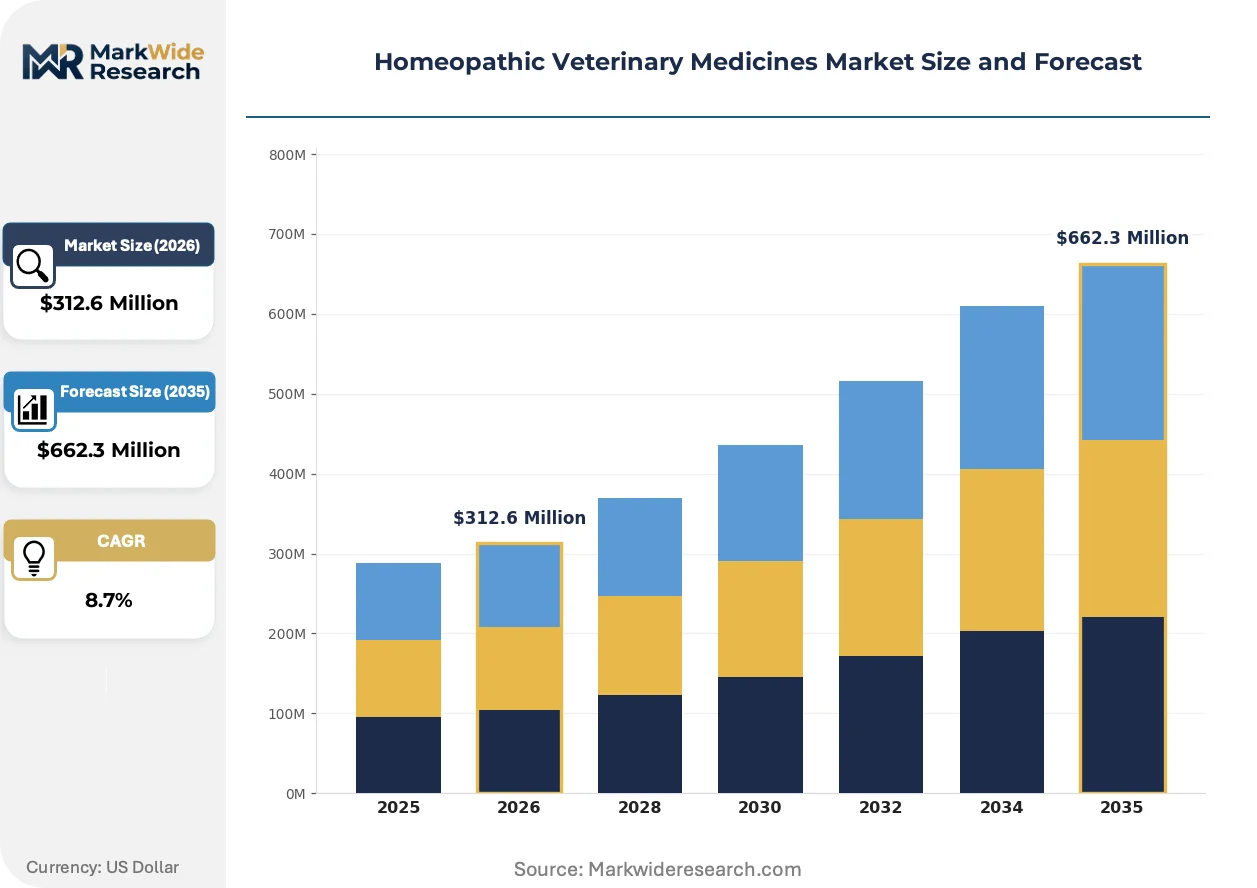
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Formulations, Tablets, Powders, Topicals Animal Type: Canines, Felines, Equines, Livestock Application: Preventive Care, Acute Conditions, Chronic Conditions, Supportive Therapy Distribution Channel: Veterinary Clinics, Online Retail, Pet Shops, Pharmacies |
| Companies Covered | Freemans Homeopathy Pharmacy, Guna SPA, Boiron Laboratories, Hivet, Helios Homeopathy Ltd., animalEo, Goel Vet Pharma, Omida AG, Dorwest Herbs Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeopathic Veterinary Medicines Market Strategic Shifts
Sequential dilution automation and potency verification technologies are transforming quality assurance protocols, while regulatory bifurcation between jurisdictions accelerates formulation specialization.
Automated succussion systems with integrated torque sensors and cycle counters are decomposing manual preparation methods that dominated artisanal homeopathic manufacturing. Large-scale veterinary compounders in Germany and Switzerland are retrofitting production lines with programmable dilution stations that reduce operator-dependent variability. This mechanization is compressing cost structures for 30C and 200C potencies previously requiring labor-intensive hand-succussion.
REACH authorization requirements for synthetic veterinary actives are forcing reformulation investments across European livestock pharmaceutical portfolios. Manufacturers are redirecting R&D expenditure toward mineral-derived and botanical source materials that bypass substance-of-very-high-concern classifications. Injectable homeopathic preparations for dairy cattle mastitis protocols are experiencing accelerated registration timelines in France and the Netherlands as authorities prioritize residue-reduction alternatives.
Veterinary procurement committees at integrated livestock operations are consolidating supplier relationships around single-source homeopathic formulators capable of batch-level traceability documentation. Independent practitioners and smaller companion animal clinics are losing access to institutional pricing tiers as volume concentrates with vertically integrated protein producers. This bifurcation is most pronounced in Denmark and the Netherlands, where cooperative veterinary purchasing organizations dominate ruminant health expenditure.
Homeopathic Veterinary Medicines Market Segmentation
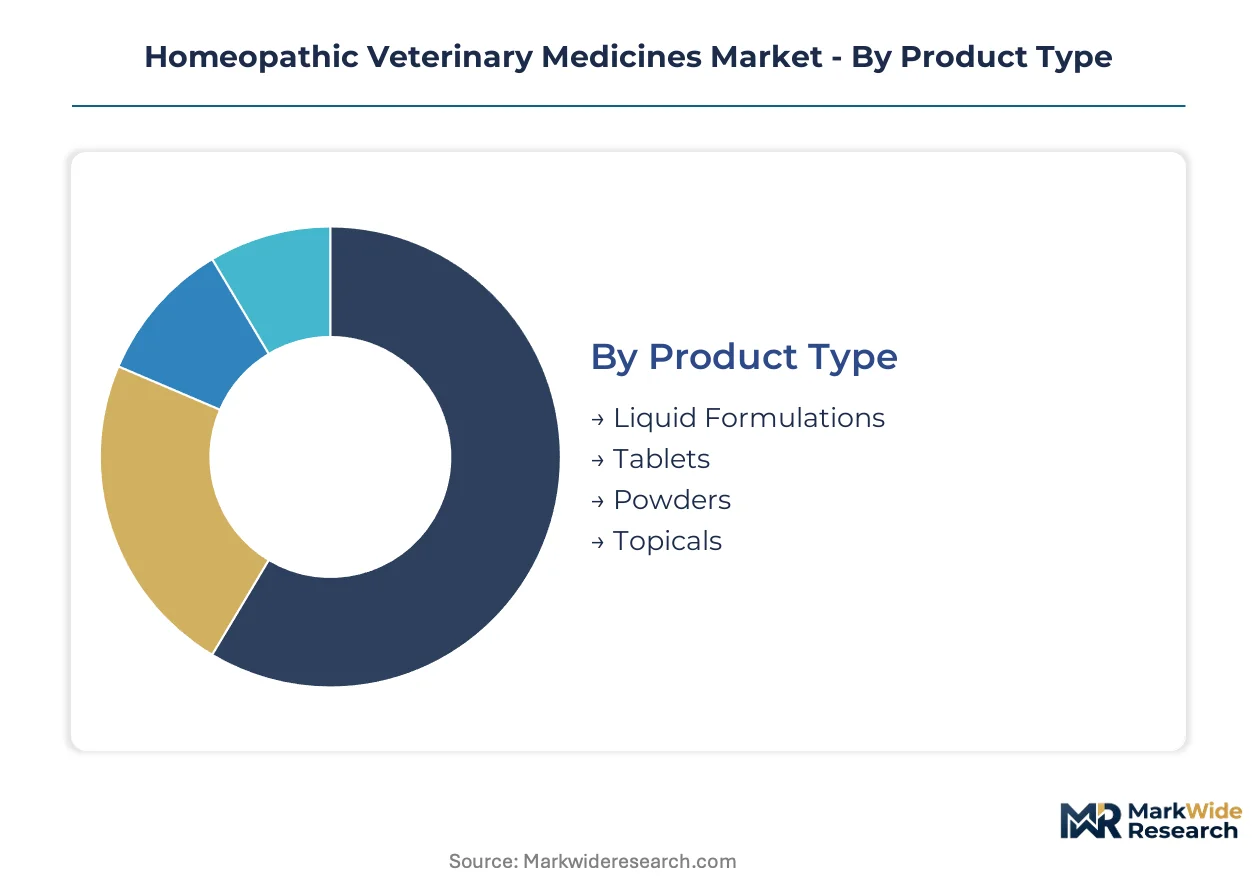
Segmentation in homeopathic veterinary medicines reveals how formulation physics, species physiology, and channel economics create distinct competitive arenas. Each dimension carries unique regulatory checkpoints and margin structures that determine manufacturer positioning.
Product Type:
EMA's Committee for Veterinary Medicinal Products applies divergent stability testing requirements to liquid versus solid dosage forms, creating compliance cost tiers that reshape competitive entry.
- Liquid Formulations:Aqueous or hydroalcoholic solutions at 6X to 30C potencies enable precise dose titration across species weights. Demand concentrates in German livestock cooperatives where automated water medicators integrate homeopathic protocols into dairy herd management.
- Tablets:Lactose or sucrose-based compressed units at 6X to 12X potencies suit companion animal compliance. French and German pet insurance reimbursement policies drive repeat purchase behavior in metropolitan veterinary clinics.
- Powders:Bulk mineral and botanical preparations for feed-topdressing applications in equine and livestock operations. Brazilian feed mills source these for residue-free export certification.
- Topicals:Cream and ointment bases containing ultradilute Arnica or Calendula for dermatological and musculoskeletal applications. Australian equine trainers favor these for pre-competition protocols.
Established volume favors liquid formulations; emerging adoption favors tablets.
Animal Type:
Species-specific pharmacokinetics and regulatory residue thresholds generate divergent formulation investment priorities across manufacturer portfolios.
- Canines:Companion dogs drive tablet and liquid demand in urban veterinary markets. German and French clinics lead protocol adoption where insurance coverage reduces owner cost sensitivity.
- Felines:Palatability challenges favor highly diluted liquid preparations with minimal alcohol content. Specialized compounding pharmacies serve this segment through veterinary telemedicine channels.
- Equines:Large-animal injectable and oral formats for performance and reproductive health. Australian and Brazilian racing authorities increasingly permit homeopathic alternatives to conventional pharmaceuticals.
- Livestock:Cattle, swine, and poultry operations seeking residue-free certification for EU and Middle Eastern export markets. Preventive mastitis and respiratory protocols dominate procurement in Dutch dairy cooperatives.
Companion animal channels sustain margin premiums; livestock volumes drive manufacturing scale.
Application:
Clinical outcome documentation requirements vary sharply between preventive and therapeutic indications, influencing veterinary practitioner liability exposure.
- Preventive Care:Herd-level prophylactic regimens administered through feed or water systems. Livestock producers in Denmark and the Netherlands adopt these ahead of export certification audits.
- Acute Conditions:Trauma, infection, and post-surgical protocols requiring rapid symptom modulation. German emergency veterinary clinics integrate these into multimodal pain management.
- Chronic Conditions:Long-term musculoskeletal, dermatological, and metabolic support in geriatric companion animals. French pet insurance policies increasingly cover extended homeopathic treatment courses.
- Supportive Therapy:Adjunctive use alongside conventional pharmaceuticals to reduce drug burden. Swiss veterinary teaching hospitals document these protocols for pharmacovigilance databases.
Preventive applications gain share fastest in livestock; chronic protocols deepen penetration in companion animal markets.
Distribution Channel:
Channel economics reflect the veterinary profession's institutional resistance and the rise of direct-to-practitioner digital procurement.
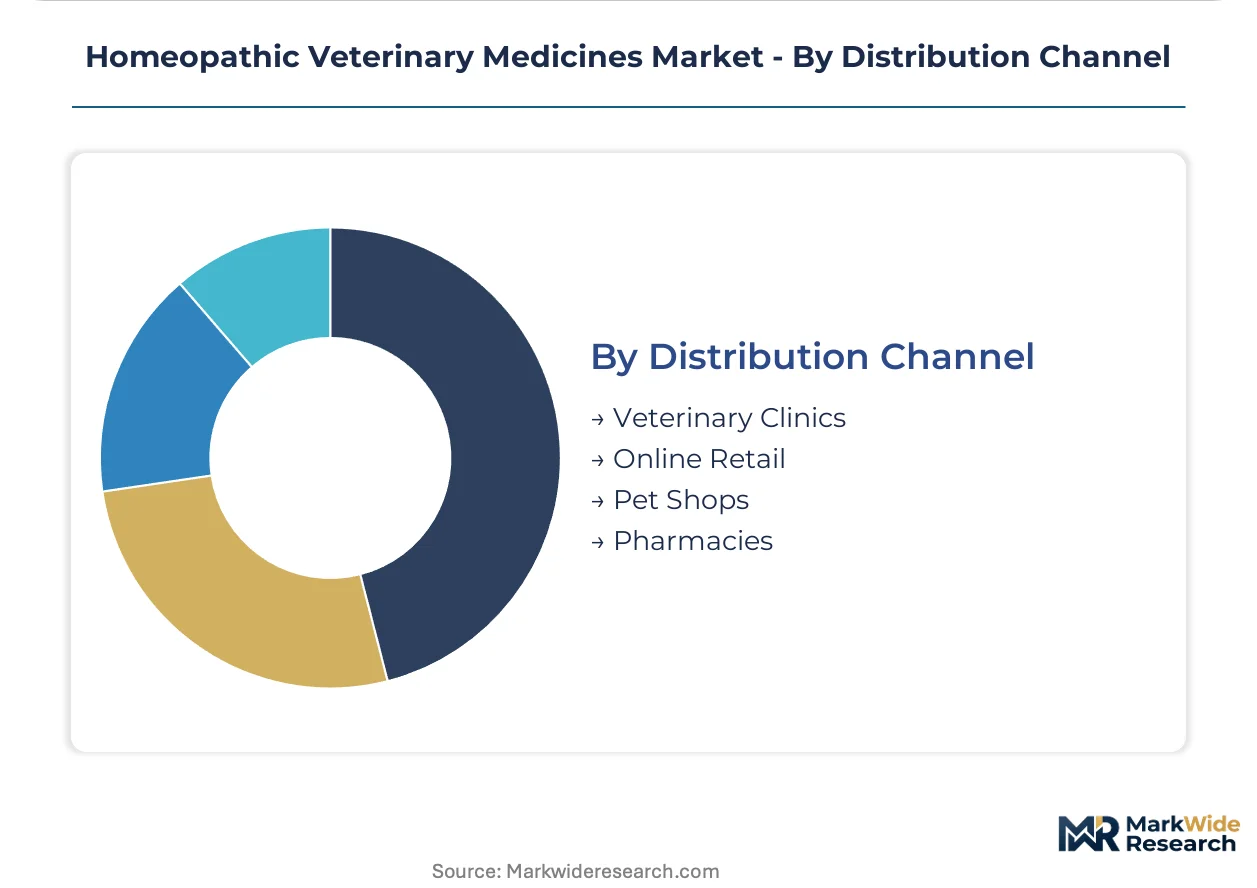
- Veterinary Clinics:Primary point of prescription and protocol design in regulated markets. German and French clinic chains consolidate purchasing through cooperative buying organizations.
- Online Retail:Direct-to-consumer platforms for over-the-counter companion animal products. Regulatory ambiguity around veterinary telemedicine limits expansion in jurisdictions with strict prescription requirements.
- Pet Shops:Mass-market outlets for low-potency nutritional supplements with homeopathic positioning. Italian and Spanish markets show highest channel penetration for these products.
- Pharmacies:Community and hospital pharmacies with homeopathic licensure, particularly in Belgium and Switzerland. Pharmacist counseling requirements create service differentiation.
Clinic channels defend professional authority; digital platforms erode traditional distribution tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal clinics in Germany and France anchor procurement volume for homeopathic veterinary protocols, while livestock cooperatives in the Netherlands and Denmark drive preventive regimen adoption ahead of export certification audits.
Germany
Pet insurance policies reimburse complementary veterinary therapies, expanding addressable demand for homeopathic treatment protocols in metropolitan companion animal clinics. The EU Green Deal framework tightens scrutiny of synthetic veterinary actives, redirecting formulation interest toward plant-derived alternatives. Bavarian livestock cooperatives integrate automated water medicators with homeopathic herd health management systems.
France
Metropolitan veterinary clinic chains consolidate purchasing through cooperative buying organizations for tablet and liquid formulations. ANSM evaluates borderline homeopathic registrations under national interpretations that diverge from EMA harmonization efforts. The Lyon-Grenoble corridor hosts specialized compounding pharmacies serving independent veterinary practitioners.
Netherlands
Dairy cooperatives adopt preventive mastitis protocols to eliminate pharmaceutical residues ahead of EU and Middle Eastern export certification requirements. REACH authorization timelines for conventional veterinary actives accelerate reformulation investments toward mineral-derived alternatives. The Randstad region concentrates veterinary procurement committees at integrated livestock operations.
Switzerland
Swissmedic maintains distinct pharmacovigilance reporting obligations for natural veterinary products, expanding liability exposure documentation requirements for manufacturers. Community and hospital pharmacies with homeopathic licensure create service differentiation through pharmacist counseling mandates. The Basel-Zurich corridor anchors batch-level traceability documentation standards.
India
CDSCO development of Ayurveda-Homeopathy integration guidelines reshapes export eligibility for domestic manufacturers targeting Commonwealth veterinary markets. The national pharmaceutical regulator converges traditional medicine frameworks with veterinary product registration pathways. Maharashtra and Gujarat host manufacturing clusters supplying botanical source materials for ultradilute preparations.
Homeopathic Veterinary Medicines Market Competitive Environment
Player mix skews toward established pharmacopeial specialists and regional compounding pharmacies rather than diversified pharmaceutical conglomerates. Market structure fragments across certification tiers, with HPUS-aligned manufacturers commanding preferred supplier status in North American distribution channels. Two strategic archetypes dominate: large-scale compounders with automated succussion capabilities and specialized pharmacies serving independent practitioners through direct digital channels. Competitive moves concentrate on portfolio diversification into injectable large-animal formats and geographic expansion through veterinary telemedicine platform partnerships.
Within the pharmacopeial specialist tier, Boiron Laboratories and Guna SPA occupy positions reflecting established quality benchmark capabilities across European supply chains. Freemans Homeopathy Pharmacy exemplifies the specialized compounding archetype, serving independent veterinary practitioners through capabilities that bypass traditional distribution tiers. These three entities represent the concentration of manufacturing credibility and direct-to-practitioner channel access within the sector.
| Leading Market Players |
|---|
| Freemans Homeopathy Pharmacy |
| Guna SPA |
| Boiron Laboratories |
| Hivet |
| Helios Homeopathy Ltd. |
| animalEo |
| Goel Vet Pharma |
| Omida AG |
| Dorwest Herbs Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Bavarian livestock cooperatives and German compounders lock in multi-year supply access for Arnica montana and Calendula officinalis while fixing price visibility against harvest yield volatility. These contracts bundle raw material procurement with automated succussion capacity reservations, transferring climate risk to suppliers in exchange for volume commitments.
Pricing Analysis
Cost-plus contracts with botanical indexation dominate procurement between Eastern European cultivators and German manufacturers, passing through harvest volatility as quarterly price adjustments. Three-tier pricing structure across HPUS-certified premium, GMP-standard, and unlicensed economy tiers reflects certification investment recovery timelines. Pricing pressure stems from REACH-driven reformulation demand as livestock producers seek residue-free alternatives ahead of export audits. Small companion animal clinics exhibit highest price sensitivity, while integrated Dutch dairy cooperatives absorb premiums for batch-level traceability documentation.
Supply Chain Analysis
Container availability constraints on Baltic-Black Sea trade lanes inflate inbound logistics costs for Bulgarian and Romanian botanical harvests reaching German processing facilities. Supply concentrates in Germany, Switzerland, and India, with Maharashtra cultivation clusters feeding ultradilute preparation lines. Raw material dependencies include Arnica montana rhizomes, Calendula officinalis flowers, and mineral tinctures sourced from specific geologic deposits. Single-source vulnerability runs through Eastern European wildcrafting cooperatives lacking cultivation insurance. Distribution runs through veterinary clinic cooperative buying organizations in metropolitan France and Germany, bypassing traditional pharmaceutical wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to EU Green Deal implementation timelines, as REACH authorization waves force sequential reformulation investments across livestock pharmaceutical portfolios.
For Market Incumbents: Fortify HPUS certification moats through backward integration into Eastern European cultivation zones, securing Arnica and Calendula supply against climate volatility. Deepen automated succussion capacity in Bavaria and Baden-Württemberg to capture livestock cooperative consolidation. Defensive priority centers on injectable large-animal format registrations ahead of Brazilian and Australian antibiotic reduction mandates. For New Entrants and Emerging Players: Veterinary telemedicine platform integration represents the most penetrable service-layer gap, as incumbents under-serve independent practitioners through traditional distribution hierarchies. Target French and German companion animal clinics seeking direct-to-practitioner compounding relationships. White-space exists in feline-specific palatable liquid formulations with minimal alcohol content. Go-to-market leverage centers on subscription replenishment models bypassing cooperative buying organizations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized compounding pharmacies with veterinary telemedicine platform integration, as subscription protocols generate predictable replenishment cycles. Long-term viability frames around regulatory convergence in India and Commonwealth export eligibility expansion. Acquisition focus centers on mid-scale compounders with HPUS alignment and automated potency verification capabilities. Signal to monitor: CDSCO Ayurveda-Homeopathy integration guideline finalization as demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| HPUS Certification Investment | Unlocks preferred supplier status with North American veterinary distributors and institutional buyers. |
| Backward Integration into Cultivation | Secures Arnica montana and Calendula officinalis supply against Eastern European harvest volatility. |
| Injectable Large-Animal Format Development | Captures Brazilian and Australian beef sector demand for antibiotic growth promoter alternatives. |
| Veterinary Telemedicine Platform Partnership | Enables direct-to-practitioner digital channels bypassing traditional distribution tiers. |
| Automated Succussion Capacity Expansion | Reduces batch-to-batch variability risks and compresses cost structures for 30C and 200C potencies. |
Study Parameters
The analysis maps liquid formulations, tablets, powders, and topicals, each validated through veterinary procurement managers, compounding pharmacy operators, regulatory affairs specialists at HPUS-aligned manufacturers, and livestock cooperative health directors. Primary interviews combined with secondary validation against EMA Committee for Veterinary Medicinal Products registration databases, FDA Center for Veterinary Medicine labeling guidance, CDSCO draft convergence guidelines, and EU Green Deal implementation tracking. Bottom-up segment sizing triangulated against top-down market envelope checks.
Consistency checks validated volume and value outputs against external benchmarks including pharmacopeial certification registries, veterinary distributor procurement data, and livestock export certification statistics. Segmentation dimensions modeled encompass product type, animal species, application indication, and distribution channel across the projection horizon. CAGRs derived from fitted growth curves incorporating HPUS certification expansion rates, pet insurance reimbursement policy adoption, and REACH authorization timeline impacts on reformulation investment.
Forecasts assume regulatory continuity in EMA, FDA, and CDSCO frameworks; material policy shifts would require re-modeling. Specific risk factors include pharmacovigilance reporting obligation expansion for natural veterinary products and divergent national interpretations of borderline homeopathic registrations across EU member states. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Mastitis Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Healthcare Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Veterinary Point-Of-Care Diagnostics Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Milking Salve Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
Clonorchiasis Market
Veterinary
Foot and Mouth Disease (FMD) Vaccine Market
Veterinary
Veterinary in Vitro Fertilization Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Global Animal Sedative Market