
 Flower Essences Market | 2026-2036
Flower Essences Market Size, Share, and Industry Trends Forecast 2026-2036
Flower Essences Market Insights
Multi-source botanical procurement is decoupling from the traditional single-territory harvesting models that long defined this industry. Nelsons leverages its British manufacturing heritage to sustain quality consistency across European retail channels. Australian Bush Flower Essences anchors the Southern Hemisphere supply base through direct relationships with indigenous flora collectors. Living Essences of Australia competes on formulation depth, offering one of the largest single-country catalogues worldwide.
Flower essences constitute aqueous preparations produced via sun-steeping or boiling of fresh blossoms in spring water, with the resulting liquid preserved in brandy or glycerin and diluted to stock or dosage strength for therapeutic use. Blended Essence formulations currently occupy the widest margin pool as practitioners prefer customized combinations over single-flower preparations for complex emotional presentations. Online Retail channels are displacing specialty stores as the dominant route to individual consumers, though Wellness Centers remain the critical trust-building touchpoint for first-time buyers encountering flower therapy.
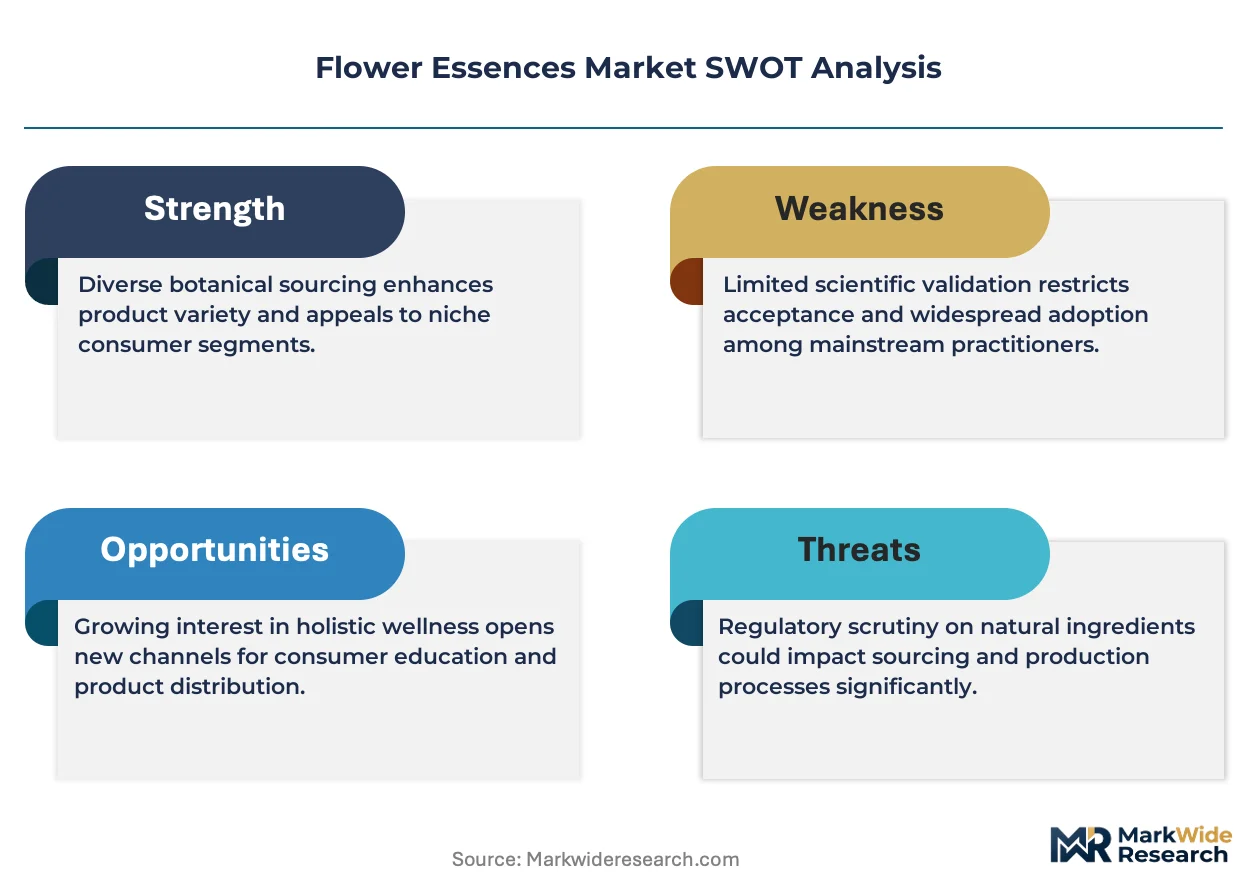
FDA oversight of dietary supplements in the United States limits disease-related claims, while the EU's REACH framework governs botanical extraction residues entering European commerce. Australia's Therapeutic Goods Administration classifies certain flower essence products as listed medicines, creating a compliance gradient that shapes export feasibility. Stakeholders must monitor how evolving pharmacovigilance requirements for traditional medicines affect labeling freedoms and practitioner education investments across their priority markets.
Market Dynamics
EU Green Deal botanical sourcing mandates are forcing manufacturers to abandon wild-harvesting networks in favor of certified cultivation partnerships, restructuring upstream supply economics across the entire preparation category.
Growth Catalysts
- REACH residue thresholds:ECHA guidelines on botanical extraction contaminants are accelerating investment in closed-loop water purification systems at European production facilities.
- Wellness center channel expansion:Holistic therapy clinics in Germany, the United Kingdom, and Australia now stock flower essences as standard therapeutic inventory, creating predictable institutional demand.
- Sun-steeping automation:Precision solar exposure chambers are standardizing potency variance that previously plagued artisanal batch production.
Market Restraints
- Wild-harvest supply concentration:Australian indigenous flora collectors control access to premium bush flower species, creating single-territory bottlenecks.
- Brandy preservation cost volatility:Spirit excise duties in key manufacturing jurisdictions directly compress margin on glycerin-alternative formulations.
- FDA disease-claim prohibitions:United States dietary supplement oversight blocks emotional-therapeutic positioning that drives practitioner adoption elsewhere.
Strategic Opportunities
- TGA listed-medicine pathway:Australia's Therapeutic Goods Administration offers regulatory precedent for exportable therapeutic classification in comparable jurisdictions.
- Online retail channel primacy:Direct-to-consumer platforms are displacing specialty stores as the dominant route for individual purchasers seeking dosage-strength products.
- Blended formulation customization:Practitioner preference for multi-flower combinations over single-essence preparations opens margin expansion in compounding services.
Industry Challenges
- Pharmacovigilance reporting systems:Evolving adverse-event documentation requirements for traditional medicines demand new investments in practitioner education infrastructure.
- Batch-to-batch solar variability:Sun-steeping remains resistant to full mechanization, complicating scale-up without potency drift.
- Cross-border labeling harmonization:Divergent stock-versus-dosage strength definitions between EU member states create compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flower Essences Market |
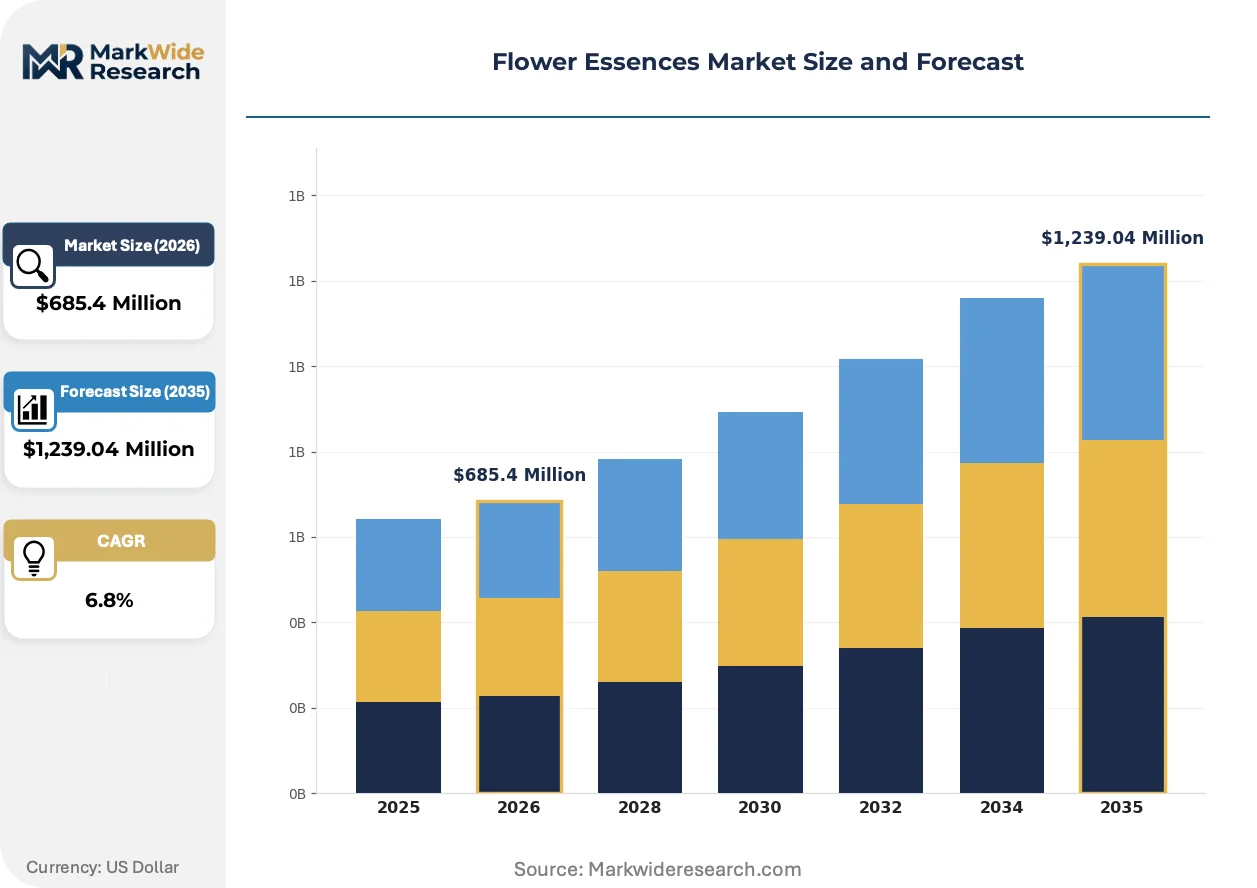
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Essence, Blended Essence, Spray Essence, Cream Essence Application: Emotional Healing, Stress Relief, Sleep Aid, Mood Enhancement Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wellness Centers End User: Individuals, Practitioners, Therapists, Wellness Enthusiasts |
| Companies Covered | Nelsons, Flower Essence Services, Australian Bush Flower Essences, Living Essences of Australia, Himalayan Flower Enhancers, Desert Alchemy, Spirit-in-Nature Essences, Tree Frog Farm, Bach Flower Remedies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flower Essences Market Trends and Innovations
Formulation science and distribution infrastructure are converging to transform how aqueous blossom preparations reach therapeutic end-users, with digitization and regulatory transparency as the dominant vectors.
Spectral analysis tools for vibrational field detection are entering quality-control protocols at advanced manufacturing facilities. European blenders are adopting these devices to verify energetic consistency across solar-steeped batches. This metrology layer is unifying artisanal credibility with industrial reproducibility, compressing the traditional quality-assurance timeline from weeks to hours.
EU Green Deal due-diligence requirements now mandate chain-of-custody documentation for all wild-harvested plant material entering European commerce. Manufacturers must demonstrate sustainable collection practices through third-party botanical certification. Australian exporters face the steepest compliance gradient, as their native species command premium positioning precisely because of wild provenance.
Practitioner procurement is consolidating around subscription-based replenishment models that guarantee formulation continuity for chronic emotional presentations. Wellness centers in Germany and the United Kingdom are negotiating direct supply agreements that bypass traditional wholesale tiers. This channel compression is most visible in Australia's domestic market, where clinic networks have captured majority volume from retail apothecaries.
Flower Essences Market Segmentation
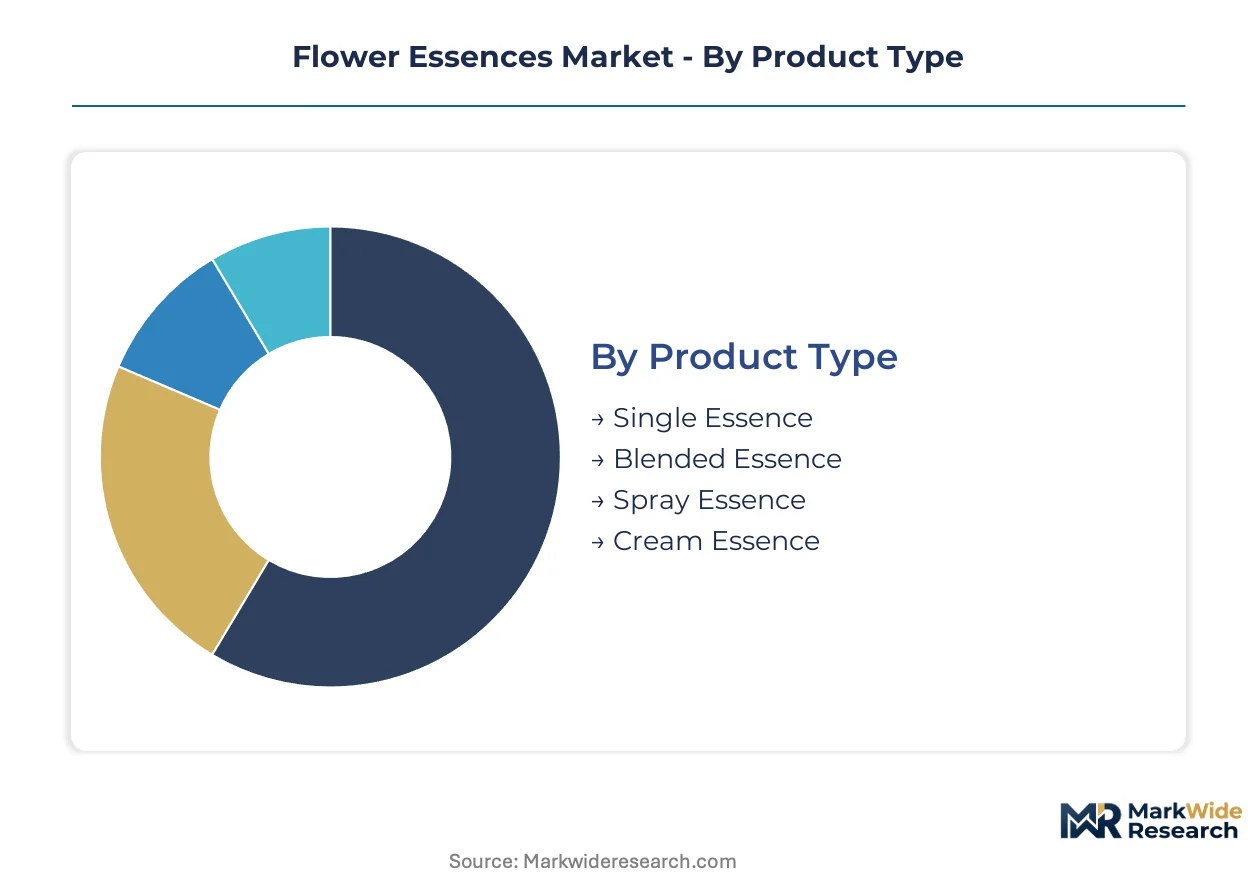
Flower essences fragment across formulation complexity, therapeutic intent, and procurement channel. Each axis carries distinct margin profiles and regulatory exposure that manufacturers must navigate simultaneously.
Product Type:
Formulation architecture determines preservation method, dosage protocol, and practitioner customization latitude.
- Single Essence:Individual flower preparations preserved in brandy or glycerin at stock concentration. Demand concentrates among German and Australian practitioners seeking precise energetic targeting for complex emotional presentations.
- Blended Essence:Multi-flower combinations diluted to dosage strength for immediate therapeutic application. Wellness centers in the United Kingdom and Australia prefer these for client retention through subscription replenishment models.
- Spray Essence:Misting formulations combining aqueous essences with essential oil carriers for environmental and topical application.
- Cream Essence:Emulsion-based delivery systems integrating flower essences into topical bases for somatic integration protocols.
Blended Essence leads on scale; Spray Essence leads on momentum.
Application:
Therapeutic positioning shapes regulatory classification and permissible marketing claims across jurisdictions.
- Emotional Healing:Core therapeutic category addressing grief, trauma, and life transitions through Bach and Australian bush flower protocols. Practitioners in Germany and the United Kingdom drive institutional procurement for clinical integration.
- Stress Relief:Acute anxiety management formulations targeting cortisol regulation narratives. Australian TGA listed-medicine pathway enables stronger positioning here than FDA-regulated US channels permit.
- Sleep Aid:Nocturnal application protocols combining flower essences with melatonin-adjacent positioning in European wellness retail.
- Mood Enhancement:General wellbeing maintenance category facing strictest claim limitations under US dietary supplement oversight.
Emotional Healing dominates practitioner protocols; Stress Relief expands most quickly through pharmacy channel access.
Distribution Channel:
Channel selection determines margin capture, consumer education burden, and regulatory documentation requirements.
- Online Retail:Direct-to-consumer platforms displacing traditional apothecaries for dosage-strength purchases. German and Australian consumers demonstrate highest digital procurement rates for repeat replenishment.
- Specialty Stores:Remaining strong in United Kingdom high streets where tactile product evaluation supports first-time trial.
- Pharmacies:Growing presence in German and Australian chains where TGA or national pharmacy recognition enables shelf placement alongside conventional OTC categories.
- Wellness Centers:Critical trust-building touchpoint for initial flower therapy exposure, with German clinic networks capturing majority domestic volume from retail channels.
Online Retail commands volume growth; Wellness Centers sustain premium positioning through practitioner endorsement.
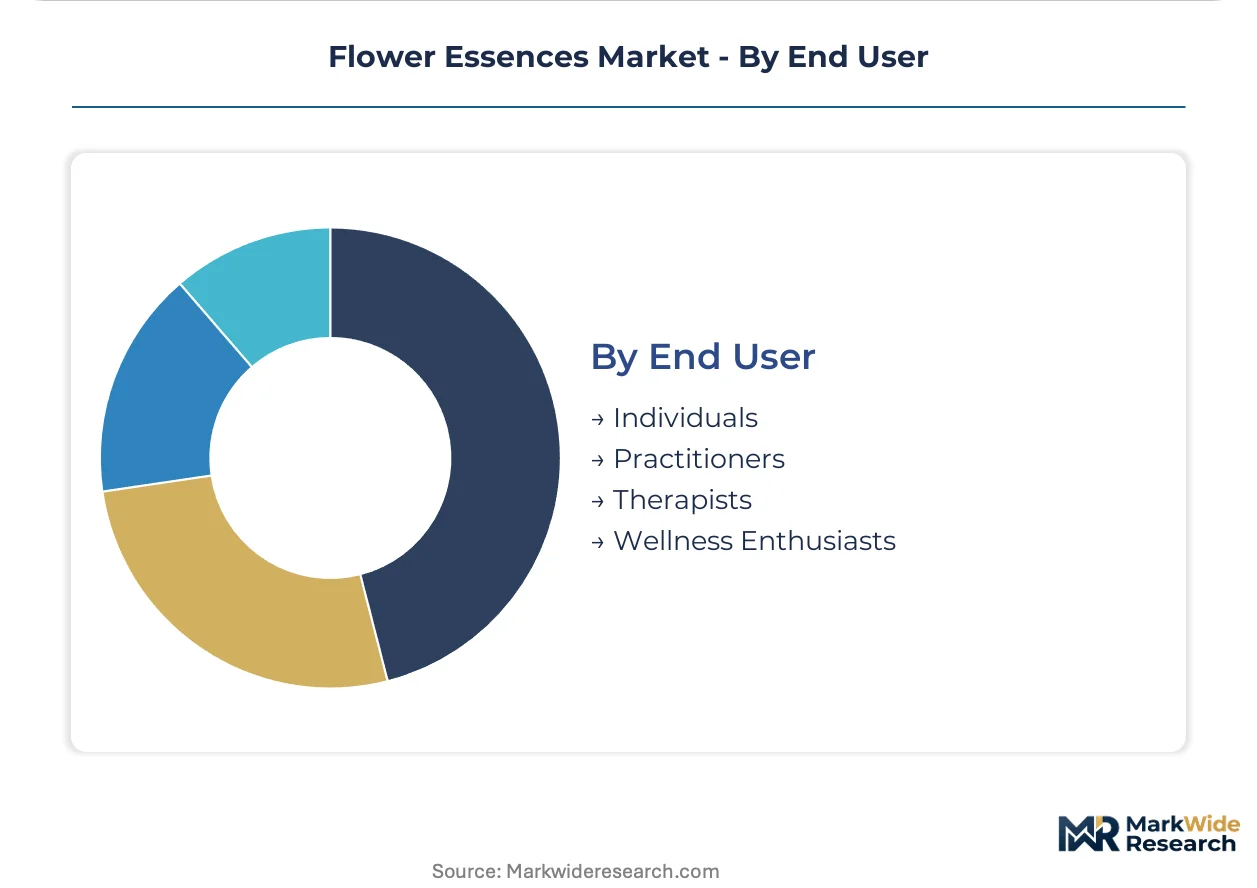
End User:
User sophistication determines formulation preference, price tolerance, and information requirements.
- Individuals:Self-directed consumers purchasing dosage-strength products for personal emotional maintenance. Australian and German markets show highest self-prescribing rates among educated wellness segments.
- Practitioners:Professional flower essence therapists requiring stock-strength inventories for client-specific compounding. United Kingdom and Australia host the densest practitioner networks.
- Therapists:Allied health professionals integrating essences into broader holistic protocols including counseling and bodywork.
- Wellness Enthusiasts:Early-adopter segment driving trial of novel formats including spray and cream essences through specialty retail.
Practitioners anchor professional-grade demand; Individuals represent the steepest expansion trajectory through digital channel maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian wild-harvest networks anchor the industry's upstream supply base, while German wellness infrastructure and United Kingdom practitioner density shape downstream demand patterns across the analysis window.
United States
Practitioner adoption concentrates in coastal wellness corridors from California to New York, though FDA dietary supplement oversight blocks emotional-therapeutic claims that drive clinical integration elsewhere. State-level hemp and botanical regulations create compliance fragmentation between jurisdictions. Los Angeles and New York Metro host the densest alternative therapy clinic networks for flower essence protocols.
Germany
Wellness center channel expansion generates predictable institutional procurement volumes unmatched elsewhere in Europe. EU Green Deal botanical sourcing mandates are forcing German distributors to abandon unverified wild-harvest suppliers. Berlin and Munich clinic networks have captured majority domestic volume from traditional retail apothecaries through direct supply agreements.
United Kingdom
High street specialty stores sustain tactile product evaluation for first-time trial despite online channel displacement elsewhere. Nelsons leverages British manufacturing heritage to sustain quality consistency across European retail channels. London practitioner networks drive the densest professional-grade demand for stock-strength compounding inventories.
Australia
Native bush flower species command premium positioning through wild provenance that TGA listed-medicine classification reinforces for export credibility. Indigenous flora collectors control access to premium species, creating single-territory supply bottlenecks. Sydney and Melbourne wellness centers anchor domestic demand while Queensland harvesting networks supply raw botanical material.
France
Pharmacy channel presence is expanding through national chains where ANSM recognition enables shelf placement alongside conventional OTC categories. REACH residue thresholds from ECHA guidelines are accelerating investment in closed-loop water purification at French formulation facilities. Paris clinic networks are negotiating subscription-based replenishment models that bypass traditional wholesale tiers.
Flower Essences Market Competitive Landscape
Global majors compete with regional champions across formulation depth and wild-harvest access, producing a tiered structure where heritage British manufacturers, Australian bush flower specialists, and North American therapeutic blenders occupy distinct competitive positions. Strategic archetypes include vertically integrated wild-harvest controllers, practitioner-direct subscription platforms, and multi-territory retail distributors. Capacity expansion in precision solar exposure chambers and certified cultivation partnerships represent the dominant competitive moves as EU Green Deal compliance reshapes upstream economics.
Within the heritage manufacturer tier, Nelsons and Bach Flower Remedies exemplify British-formulation credibility that sustains European retail penetration. Australian Bush Flower Essences and Living Essences of Australia occupy positions anchored by Southern Hemisphere wild-harvest access and TGA regulatory precedent. Flower Essence Services represents the North American practitioner-direct archetype, while Himalayan Flower Enhancers and Desert Alchemy exemplify geographically specialized collectors competing on indigenous species provenance.
| Leading Market Players |
|---|
| Nelsons |
| Flower Essence Services |
| Australian Bush Flower Essences |
| Living Essences of Australia |
| Himalayan Flower Enhancers |
| Desert Alchemy |
| Spirit-in-Nature Essences |
| Tree Frog Farm |
| Bach Flower Remedies |
| Others |
Pricing and Supply Chain Analysis
Spirit excise duty indices in the United Kingdom and Australia cascade directly through manufacturing cost structures, compressing margins on brandy-preserved formulations while elevating glycerin-alternative premiums across dosage-strength retail tiers.
Pricing Analysis
Input-cost pass-through from wild-harvest licensing fees and organic certification premiums stratifies pricing across premium, standard, and economy tiers. Price differentiation rests on TGA listed-medicine status and EU Green Deal botanical provenance documentation. Pricing pressure stems from REACH compliance investments at European formulation facilities. Individual consumers through online retail channels exhibit highest price sensitivity, while German wellness centers absorb premiums for practitioner-grade stock concentrations.
Supply Chain Analysis
Freight cost volatility on temperature-controlled shipments from Queensland harvesting networks to European compounding facilities is reshaping inventory positioning strategies. Supply concentrates in Australia, the United Kingdom, and Germany, with raw material dependencies on indigenous bush flower species, spring water sourcing, and pharmaceutical-grade ethanol. Single-territory bottlenecks around Australian wild-harvest access create structural vulnerability. Distribution runs through direct-to-clinic subscription models that bypass wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where practitioner preference for certified provenance and TGA-listed formulations is elevating specification requirements above commodity positioning.
For Market Incumbents: Cement wild-harvest access through exclusive partnerships with Queensland indigenous flora collectors before EU Green Deal certification mandates fully phase out unverified sourcing. Deepen backward integration into certified cultivation partnerships to offset supply concentration risk. Prioritize closed-loop water purification capacity additions at British and German manufacturing sites to sustain REACH compliance without margin erosion from third-party testing. For New Entrants and Emerging Players: Launch via practitioner-direct subscription platforms targeting United States coastal wellness corridors where FDA claim restrictions have suppressed incumbent penetration. Exploit white space in spray and cream essence formats where Australian and German early adopters demonstrate format-switching willingness. Target pharmacy channel placement in France and Germany where ANSM and national recognition protocols enable shelf adjacency to conventional OTC categories. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated Australian operators combining TGA regulatory precedent with captive wild-harvest networks. Long-term viability favors acquisition targets with certified cultivation partnerships already operational rather than pure wild-harvest dependence. Monitor EU Green Deal implementation timelines as the inflection signal for supply economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Cultivation Partnerships | EU Green Deal compliance eliminates wild-harvest dependency while securing botanical provenance documentation for premium positioning. |
| Precision Solar Exposure Chamber Deployment | Standardization of sun-steeping potency variance enables scale-up without artisanal batch drift that previously limited production volume. |
| TGA Listed-Medicine Pathway Investment | Therapeutic classification precedent creates exportable regulatory credibility for pharmacy channel access in comparable jurisdictions. |
| Direct-to-Clinic Subscription Platform Launch | Bypassing wholesale tiers captures margin compression from wellness center procurement consolidation in Germany and Australia. |
| Spectral Analysis Quality Control Integration | Vibrational field detection compresses quality assurance timelines from weeks to hours at advanced manufacturing facilities. |
Research Methodology
Bottom-up practitioner and wellness center demand modeling reconciled against top-down botanical supply and formulation capacity tracking forms the analytical core of this study. Primary interviews with flower essence therapists, clinic procurement managers, indigenous flora collectors, and European regulatory compliance officers combined with secondary validation from TGA listed-medicine registers, EU REACH documentation databases, and Australian wild-harvest certification records. Triangulation across these sources ensures cross-verification of stock-to-dosage strength volume flows and channel-specific pricing structures.
Historical trendline analysis of Bach and Australian bush flower protocol adoption rates informed projection frameworks across the analysis window. Segmentation modeling incorporated formulation type, therapeutic application, distribution channel, and end-user sophistication dimensions. CAGRs derive from compounding annual growth assumptions anchored to wellness center channel expansion trajectories and online retail penetration curves. Industry-specific inputs include EU Green Deal implementation pace and TGA pharmacovigilance reporting system evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regulatory harmonization or sustained spirit excise duty escalation. Forecasts reflect assumptions about wild-harvest supply continuity and practitioner education infrastructure investment levels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
US Aromatherapy Market