
 Global Complementary and Alternative Medicines Market | 2026-2036
Global Complementary and Alternative Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Complementary and Alternative Medicines Market Foresight
Subscription-based herbal supplement replenishment is decoupling product ownership from one-time purchasing in the complementary and alternative medicines space. Dabur India Ltd. leverages its vertically integrated Ayurveda supply chain spanning raw herb procurement to finished goods. Himalaya Global Holdings Ltd. anchors its competitive position through pharmaceutical-grade botanical extraction standards. Weleda AG differentiates via biodynamic cultivation certifications that command premium positioning in European pharmacy channels.
Complementary and alternative medicines encompass botanical extracts, homeopathic dilutions, traditional system formulations, and mind-body interventions administered outside conventional allopathic protocols, typically requiring standardization of marker compounds or potency indices for batch consistency. The primary commercial purpose centers on preventive health maintenance, chronic condition adjunct therapy, and wellness optimization across non-clinical and integrative care settings. Herbal supplements occupy the largest revenue pool among product type segments, while traditional Chinese medicine concentrates its fastest growth in Asia-Pacific export markets. Direct sales channels retain margin advantages through practitioner-patient relationships, though online pharmacies are capturing volume from convenience-oriented individual consumers.
FDA dietary supplement regulations, EFSA health claim substantiation requirements, and India's AYUSH ministry quality standards collectively shape ingredient sourcing transparency and cross-border market access for botanical products. The EU Traditional Herbal Medicinal Products Directive creates registration pathways that favor established European manufacturers while imposing compliance costs on new entrants. Stakeholders must monitor evolving pharmacovigilance obligations for herbal products as regulators tighten adverse event reporting thresholds.
Market Dynamics
Subscription-based replenishment models are restructuring cash flow patterns across botanical supply chains, decoupling traditional one-time purchase economics from recurring revenue streams and forcing manufacturers to reconfigure inventory planning around patient adherence data rather than wholesale order cycles.
Growth Catalysts
- India's AYUSH Ministry quality standards:Mandatory GMP certification for Ayurveda exporters is consolidating manufacturing capacity around Kerala and Karnataka, accelerating formalization of previously fragmented herbal processing.
- Wellness center expansion:Service menu diversification into acupuncture and herbal protocols across Germany, Japan, and Brazil is creating institutional demand channels for standardized botanical extracts.
- Pharmaceutical-grade extraction:Adoption of marker compound standardization by integrative medicine clinics is displacing artisanal procurement with batch-consistent supply agreements.
Market Restraints
- Wild herb supply volatility:Climate-sensitive harvests of ashwagandha root and ginseng rhizome concentrate input cost risk with Indian and Korean agricultural cooperatives.
- EFSA health claim substantiation:The European regulator's randomized trial requirements for botanical efficacy claims impose multi-year validation timelines that freeze new product introductions.
- Synthetic nootropics substitution:Lab-derived cognitive enhancers from pharmaceutical manufacturers compete directly with traditional adaptogenic formulations on price and dosing precision.
Strategic Opportunities
- Brazilian regulatory tailwind:ANVISA's simplified registration pathway for traditional herbal products reduces market entry barriers for South American botanical exporters.
- Biometric-integrated adherence tracking:Wearable device convergence with personalized herbal protocols enables outcome-linked subscription pricing in preventive health segments.
- Direct-to-practitioner telehealth channels:Virtual consultation platforms bypass pharmacy distribution markups for licensed naturopaths and traditional medicine practitioners.
Industry Challenges
- Phytochemical analytical talent scarcity:Chromatography and mass spectrometry expertise for marker compound verification remains concentrated with contract research organizations, constraining in-house quality control scaling.
- Cross-border pharmacovigilance compliance:Divergent adverse event reporting thresholds between FDA, EMA, and India's CDSCO force parallel surveillance system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Complementary and Alternative Medicines Market |
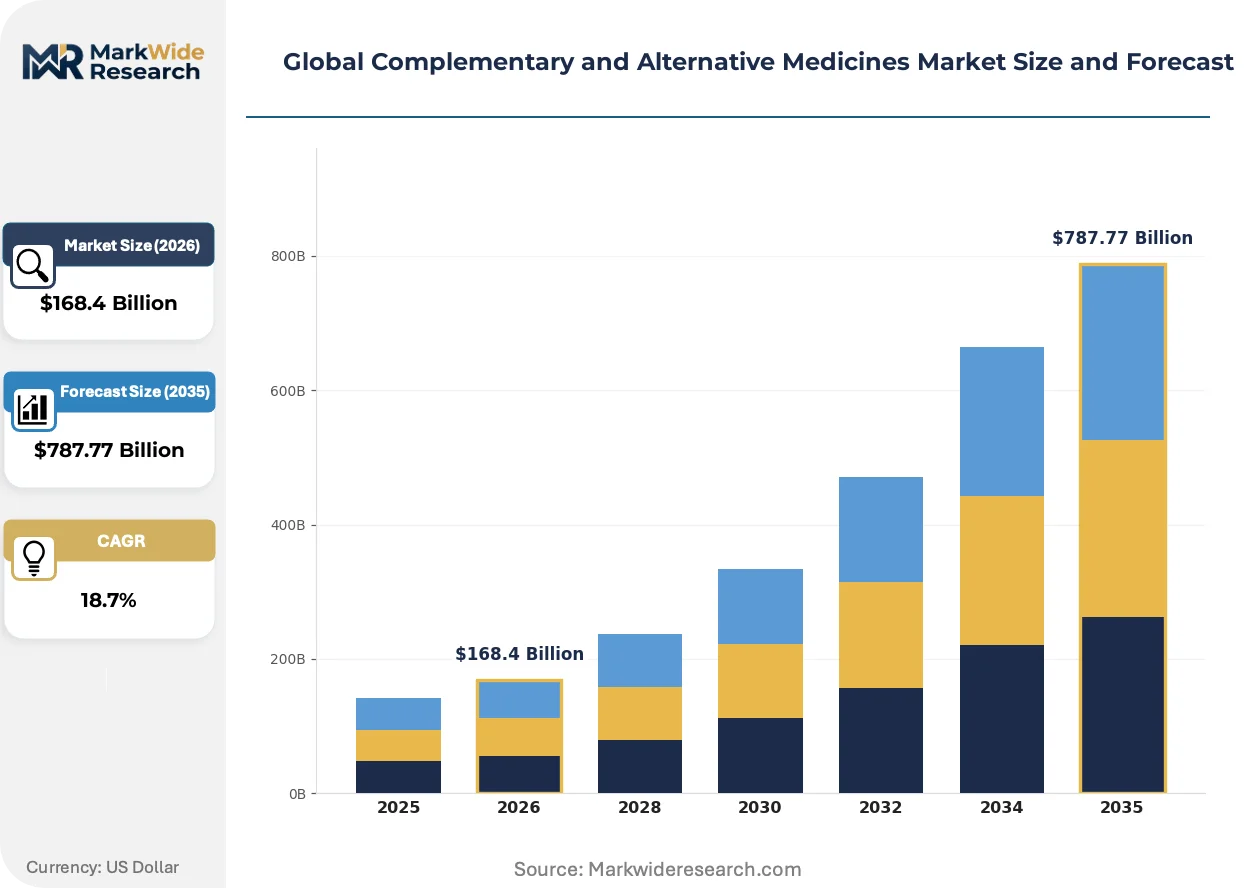
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $787.77 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Homeopathy, Traditional Chinese Medicine, Ayurveda, Naturopathy, Aromatherapy Application: Stress Management, Pain Relief, Digestive Health, Immune Support, Respiratory Care, Sleep Disorders End User: Wellness Centers, Individual Consumers, Fitness Facilities, Massage Therapists, Rehabilitation Centers, Health Spas Distribution Channel: Online Pharmacies, Specialty Retail Stores, Direct Sales, Drug Stores, Health Food Stores, Wellness Clinics |
| Companies Covered | Himalaya Global Holdings Ltd., Dabur India Ltd., Herb Pharm, Nature's Bounty, Weleda AG, Nordic Nutraceuticals, Boiron USA, ARKOPHARMA Laboratories Company Limited, Pure Encapsulations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Complementary and Alternative Medicines Market Shifts & Advancements
Digital therapeutics integration and biodynamic certification hierarchies are bifurcating competitive positioning, separating technology-enabled personalized protocols from premium positioning through cultivation transparency and soil-to-shelf traceability systems.
DNA barcoding for botanical identity verification is overtaking morphological and organoleptic testing at raw material intake. Large-scale Ayurveda and TCM manufacturers in India and China are adopting genomic authentication to combat adulteration with cheaper substitutes. This technology is compressing quality assurance timelines from weeks to hours while raising capital requirements for laboratory infrastructure.
The EU Traditional Herbal Medicinal Products Directive is forcing concentration of regulatory affairs capabilities among established European manufacturers. Smaller exporters from Asia-Pacific and Latin American markets face compliance cost barriers that favor partnership or acquisition routes over independent registration. German and French pharmacy channels are responding by consolidating supplier bases around fewer, fully certified vendors.
Practitioner-patient relationship models are displacing retail pharmacy as the primary channel for chronic condition adjunct therapy. Licensed acupuncturists and naturopaths in Australia, Canada, and Switzerland are capturing margin through direct dispensing arrangements. This shift is most visible in oncology support and pain management verticals where clinical supervision drives protocol adherence.
Global Complementary and Alternative Medicines Market Segmentation
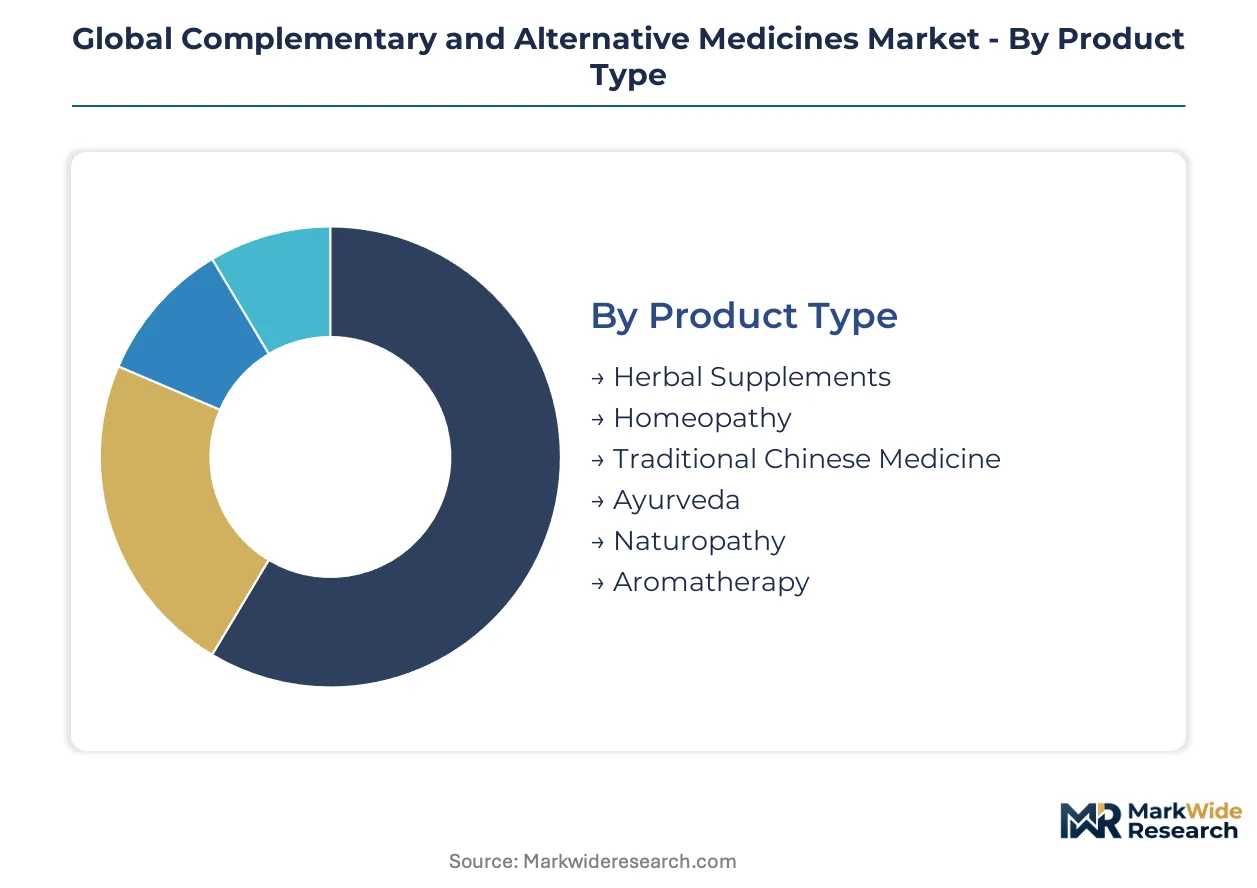
Segmentation in complementary and alternative medicines reveals how purchasing decisions diverge between preventive wellness seekers and chronic condition managers. Product form, application intent, and channel access each reshape margin structures and loyalty patterns across this fragmented supply base.
Product Type:
Buyers differentiate by standardization requirements and regulatory familiarity rather than efficacy claims alone.
- Herbal Supplements:Standardized botanical extracts with verified marker compound concentrations dominate pharmacy shelf space. Demand concentrates in India's Kerala and Karnataka manufacturing clusters where AYUSH Ministry GMP certification consolidates formerly fragmented processing capacity.
- Traditional Chinese Medicine:Multi-herb formulations requiring decoction or granule preparation retain strong practitioner-channel dependence. Export demand from Asia-Pacific markets accelerates as wellness centers in Germany and Japan expand acupuncture-integrated service menus.
- Homeopathy:Potency-dilution preparations face EFSA health claim substantiation barriers in European markets.
- Ayurveda:Dosha-specific protocols from Indian manufacturers leverage vertically integrated herb procurement.
- Naturopathy:Protocol-driven interventions bundle botanical, nutritional, and lifestyle components.
- Aromatherapy:Essential oil applications concentrate in health spa and massage therapy channels.
Volume sits with Herbal Supplements; growth tilts toward Traditional Chinese Medicine.
Application:
Condition-specific positioning determines whether products reach clinical adjunct or lifestyle wellness price tiers.
- Stress Management:Adaptogenic formulations targeting cortisol modulation attract subscription-based replenishment models. Wellness centers in Brazil and Japan deploy these protocols as core service differentiators.
- Pain Relief:Topical botanical preparations and acupuncture adjuncts compete with pharmaceutical analgesics on safety perception. Licensed naturopaths in Australia and Switzerland capture margin through direct dispensing arrangements.
- Digestive Health:Probiotic-herb combinations face FDA dietary supplement disclosure tightening.
- Immune Support:Seasonal demand spikes strain wild herb supply chains for echinacea and andrographis.
- Respiratory Care:Traditional formulations gain traction where conventional antibiotic stewardship limits options.
- Sleep Disorders:Melatonin-herb hybrids compete with synthetic nootropics on dosing precision.
Revenue concentrates in Stress Management; Pain Relief climbs the fastest.
End User:
Institutional procurement scales through protocol adherence requirements that individual purchasing cannot replicate.
- Wellness Centers:Facility-based consumption of standardized extracts and acupuncture supplies operates on service-menu integration. Expansion across Germany, Japan, and Brazil creates institutional demand channels with batch-consistency requirements.
- Individual Consumers:Direct-to-patient subscription models decouple ownership from one-time purchasing. Online pharmacies capture volume through convenience-oriented replenishment.
- Fitness Facilities:Recovery-focused botanical protocols target post-exercise inflammation modulation.
- Massage Therapists:Topical aromatherapy and liniment procurement depends on professional licensing status.
- Rehabilitation Centers:Adjunct pain management protocols require clinical supervision documentation.
- Health Spas:Premium positioning through biodynamic certification commands European pharmacy channel access.
Wellness Centers anchor volume; Individual Consumers gain share fastest.
Distribution Channel:
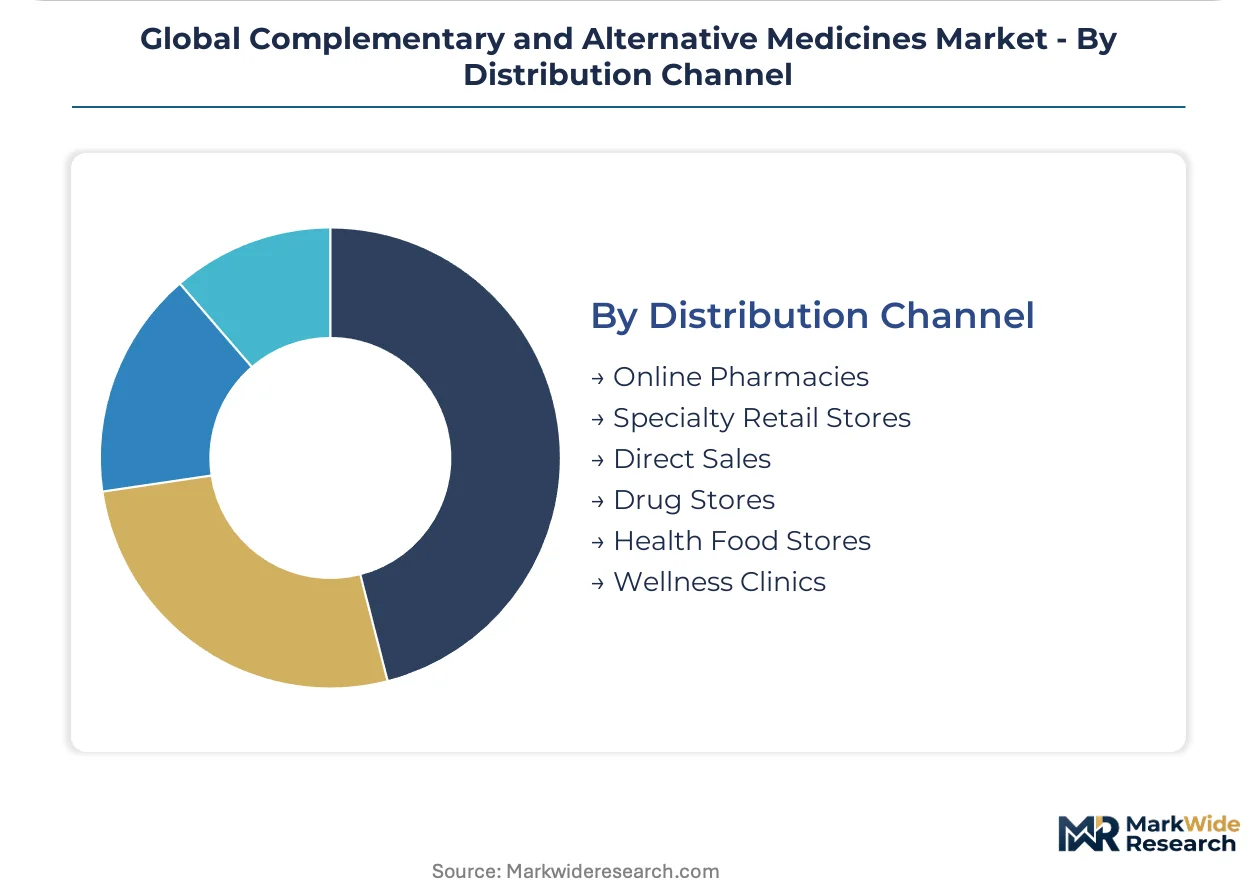
Channel selection determines margin retention versus reach trade-offs, with practitioner relationships preserving price integrity.
- Direct Sales:Licensed practitioner-patient relationships bypass pharmacy markups through in-clinic dispensing. Virtual consultation platforms now extend this model to telehealth-integrated naturopaths.
- Online Pharmacies:Convenience-driven individual purchasing captures volume from subscription-based replenishment adoption.
- Specialty Retail Stores:Staff-trained environments support complex multi-herb protocol explanation.
- Drug Stores:Mass-market herbal supplements compete on shelf placement and price promotion.
- Health Food Stores:Certified organic and biodynamic positioning targets premium segments.
- Wellness Clinics:Integrated service-and-product bundling locks in patient adherence data.
Direct Sales retains margin leadership; Online Pharmacies expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala and Karnataka manufacturing clusters anchor India's AYUSH-certified Ayurveda production, while wellness center expansion across Germany, Japan, and Brazil redistributes demand geography. Regulatory divergence between FDA disclosure mandates and EFSA substantiation requirements fragments market access protocols. DNA barcoding adoption concentrates laboratory infrastructure investment in Indian and Chinese processing hubs.
United States
FDA dietary supplement enforcement tightening drives ingredient disclosure investments among domestic formulators. The agency's evolving adverse event reporting thresholds force parallel pharmacovigilance system upgrades. Direct-to-practitioner telehealth channels bypass traditional pharmacy distribution in oncology support verticals.
Germany
Biodynamic certification hierarchies command premium positioning in pharmacy channels serving preventive health seekers. The EU Traditional Herbal Medicinal Products Directive consolidates supplier bases around fully certified vendors. Wellness centers in Bavaria and Baden-Württemberg expand acupuncture-integrated service menus.
India
AYUSH Ministry mandatory GMP certification consolidates Ayurveda manufacturing around Kerala and Karnataka clusters. CDSCO quality standards accelerate formalization of previously fragmented herbal processing capacity. Dabur India Ltd. leverages vertically integrated supply chains spanning raw herb procurement to finished goods.
Japan
PMDA regulatory frameworks govern traditional Kampo medicine integration with conventional care protocols. METI standards support wellness center service diversification into herbal and acupuncture offerings. Manufacturing investment concentrates in Kansai and Chubu regions serving domestic and export markets.
Brazil
ANVISA simplified registration pathways reduce market entry barriers for South American botanical exporters. Wellness center expansion in São Paulo and Rio de Janeiro creates institutional demand channels for standardized extracts. Climate-sensitive harvests of native species concentrate input cost risk with agricultural cooperatives.
Global Complementary and Alternative Medicines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across complementary and alternative medicines, with integrated Ayurveda manufacturers facing specialized botanical extractors. The vendor base stratifies between pharmaceutical-grade standardization specialists and artisanal heritage brands. Three archetypes dominate: vertically integrated herb-to-shelf operators, pharmaceutical-grade extraction specialists, and biodynamic cultivation certifiers. M&A activity concentrates regulatory affairs capabilities among established players, while strategic partnerships bridge compliance cost barriers for Asia-Pacific exporters.
Within the heritage Ayurveda tier, Dabur India Ltd. and Himalaya Global Holdings Ltd. exemplify vertically integrated supply chain control. Weleda AG anchors the European biodynamic positioning vector. These three entities represent divergent competitive moats: captive raw material sourcing, pharmaceutical-grade extraction standards, and cultivation transparency certification respectively.
| Leading Market Players |
|---|
| Himalaya Global Holdings Ltd. |
| Dabur India Ltd. |
| Herb Pharm |
| Nature's Bounty |
| Weleda AG |
| Nordic Nutraceuticals |
| Boiron USA |
| ARKOPHARMA Laboratories Company Limited |
| Pure Encapsulations |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification tiers bifurcate the complementary and alternative medicines landscape, with biodynamic and GMP-certified products commanding 40-60% premiums over artisanal equivalents while concentrating procurement power among Kerala and Karnataka manufacturing clusters. This tier divergence manifests in supply chain configurations where premium-positioned players captive-source raw herbs through agricultural cooperatives, whereas commodity-tier competitors remain exposed to spot-market volatility for wild-harvested ashwagandha and ginseng.
Pricing Analysis
Margin tightening in commodity herbal supplements reflects wild herb supply volatility and synthetic nootropic substitution pressure from pharmaceutical manufacturers. Three-tier pricing structure across pharmaceutical-grade, certified-organic, and conventional levels segments buyer archetypes, with wellness centers and licensed practitioners exhibiting lowest price sensitivity due to protocol adherence requirements. Cost-down pressure on economy-tier extracts accelerates because climate-sensitive harvests concentrate input cost risk with Indian and Korean agricultural cooperatives.
Supply Chain Analysis
Direct-to-practitioner channels handle institutional demand from wellness centers and integrative medicine clinics, bypassing pharmacy distribution markups. Geographic supply concentration centers on India, China, and Brazil, with raw material dependencies spanning ashwagandha root, ginseng rhizome, and native South American botanicals. Single-source vulnerability from wild-harvested inputs creates supply chain risk, particularly for adaptogenic formulations where cultivation cycles span multiple years.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DNA barcoding authentication is displacing legacy morphological testing across botanical supply chains, compressing quality assurance timelines while raising capital barriers for laboratory infrastructure investment.
For Market Incumbents: Acquire chromatography and mass spectrometry capabilities to anchor in-house marker compound verification, reducing reliance on contract research organizations for batch consistency documentation. Consolidate regulatory affairs capabilities ahead of tightening FDA adverse event reporting thresholds and EFSA health claim substantiation requirements. Defensive positioning requires backward integration into biodynamic cultivation certifications that command premium pharmacy channel access in Germany and France. For New Entrants and Emerging Players: Licensed telehealth practitioners represent the most penetrable channel partner type for bypassing established pharmacy distribution networks. Target Brazilian wellness center expansion through ANVISA's simplified registration pathway for traditional herbal products, leveraging climate-advantaged native species cultivation. White-space concentration appears in biometric-integrated adherence tracking for subscription-based preventive health protocols. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical-grade extraction specialists seeking regulatory affairs capabilities and geographic manufacturing footprints. Long-term viability favors vertically integrated Ayurveda operators with captive herb procurement and AYUSH-certified processing capacity. The signal to watch is CDSCO enforcement intensity for adverse event reporting, which would accelerate consolidation among sub-scale manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| DNA Barcoding Infrastructure Investment | Genomic authentication compresses quality assurance timelines from weeks to hours for Indian and Chinese manufacturers. |
| Biodynamic Cultivation Certification | Soil-to-shelf traceability commands premium positioning in German and French pharmacy channels. |
| Direct-to-Practitioner Telehealth Platform | Virtual consultation channels bypass pharmacy markups for licensed naturopaths and acupuncturists. |
| AYUSH GMP Certification Acquisition | Mandatory standards consolidate manufacturing capacity around Kerala and Karnataka clusters. |
| Subscription-Based Replenishment Model | Recurring revenue streams reconfigure inventory planning around patient adherence data. |
Research Methodology
Trade databases, regulatory filings, and customs records formed the secondary backbone for supply chain mapping and competitive positioning analysis. Primary interviews with Ayurveda manufacturing executives, AYUSH compliance officers, wellness center procurement directors, and chromatography laboratory managers validated secondary findings. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, application intent, and distribution channel dimensions.
Historical trendline analysis of botanical extract pricing, certification adoption rates, and channel migration patterns informed the projection framework. Segmentation dimensions modeled include standardization tier, end-use setting, practitioner licensing status, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating wellness center expansion trajectories and DNA barcoding penetration rates.
Caveats apply where FDA enforcement intensity, EFSA substantiation timeline extensions, or climate-induced wild herb harvest failures could materially shift the outlook. Forecasts reflect assumptions regarding AYUSH certification consolidation pace and telehealth platform regulatory clarity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Aromatherapy Market