
 Medicine Cabinets Market | 2026-2036
Medicine Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Medicine Cabinets Market Analysis
Aftermarket service revenue for cabinet refurbishment and hardware replacement is rewriting profit dynamics across the value chain. Kohler leverages its captive distribution network to sustain premium positioning in the wall-mounted segment. Robern specializes in mirrored technology integration to differentiate its portfolio in the luxury channel. Bradley Corp. anchors its presence through institutional specification dominance in healthcare and commercial facilities.
Medicine cabinets are enclosed storage fixtures, typically wall-mounted or recessed, featuring mirrored doors, adjustable shelving, and moisture-resistant construction using engineered wood, aluminum, or tempered glass to protect pharmaceuticals and toiletries from humidity and contamination. Wall-mounted configurations lead volume due to retrofit compatibility across aging housing stock, while metal construction captures expanding share as durability standards tighten in commercial installations. The compact storage capacity tier serves fastest-growing demand from urban micro-unit residential development, whereas extra-large formats occupy mature replacement cycles in suburban single-family homes.
EPA guidelines on indoor air quality and material emissions shape product specifications for engineered wood substrates, while OSHA requirements in commercial healthcare settings mandate corrosion-resistant hardware and shatterproof mirror assemblies. The EU Green Deal and associated Ecodesign frameworks are forcing material transparency disclosures across imported cabinetry. Stakeholders must monitor evolving compliance thresholds for recycled content mandates and chemical restriction lists that will determine supplier qualification and market access trajectories.
Market Dynamics
Residential bathroom renovation cycles are compressing replacement timelines while REACH and RoHS compliance in Europe forces material substitutions across metal and glass supply chains, reshaping procurement priorities for manufacturers and distributors alike.
Growth Catalysts
- Wall-mounted retrofit compatibility:Aging housing stock in the United States requires minimal-invasive installation solutions, driving specification of surface-mounted units over recessed alternatives in renovation corridors.
- REACH material transparency mandates:European Ecodesign frameworks under the EU Green Deal compel engineered wood substrate disclosures, qualifying suppliers who document recycled content and chemical compliance.
- Healthcare corrosion standards:OSHA requirements for commercial healthcare settings mandate shatterproof mirror assemblies and moisture-resistant hardware, institutionalizing premium metal construction in hospital and clinic procurement.
Market Restraints
- Aluminum price volatility:Raw material input costs for metal-framed cabinets fluctuate with energy-intensive smelting economics, compressing margin stability for mid-tier manufacturers.
- Glass supply concentration:Tempered mirror production clusters in specific manufacturing corridors, exposing lead time risks from single-source dependencies for tempered glass components.
- Engineered wood emission thresholds:EPA indoor air quality guidelines restrict formaldehyde and VOC content in substrate materials, disqualifying legacy suppliers lacking certified panel sourcing.
Strategic Opportunities
- Urban micro-unit development:Compact storage capacity tiers address space-constrained residential construction in metropolitan United States corridors, capturing fastest-growing volume from studio and one-bedroom unit specifications.
- Aftermarket service unbundling:Cabinet refurbishment and hardware replacement revenue streams separate from original equipment sales, creating recurring revenue models for installation and maintenance networks.
- Mirrored technology convergence:Integration of LED lighting, anti-fog systems, and Bluetooth connectivity into medicine cabinet doors commands premium positioning in luxury residential channels.
Industry Challenges
- Certification timeline compression:Multi-jurisdictional compliance testing for EPA emissions, OSHA healthcare standards, and EU chemical restrictions extends product launch cycles and strains R&D resource allocation.
- Skill gap in moisture-sealing installation:Proper vapor barrier integration and humidity-resistant mounting require specialized contractor training, limiting qualified installer availability in fragmented construction labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicine Cabinets Market |
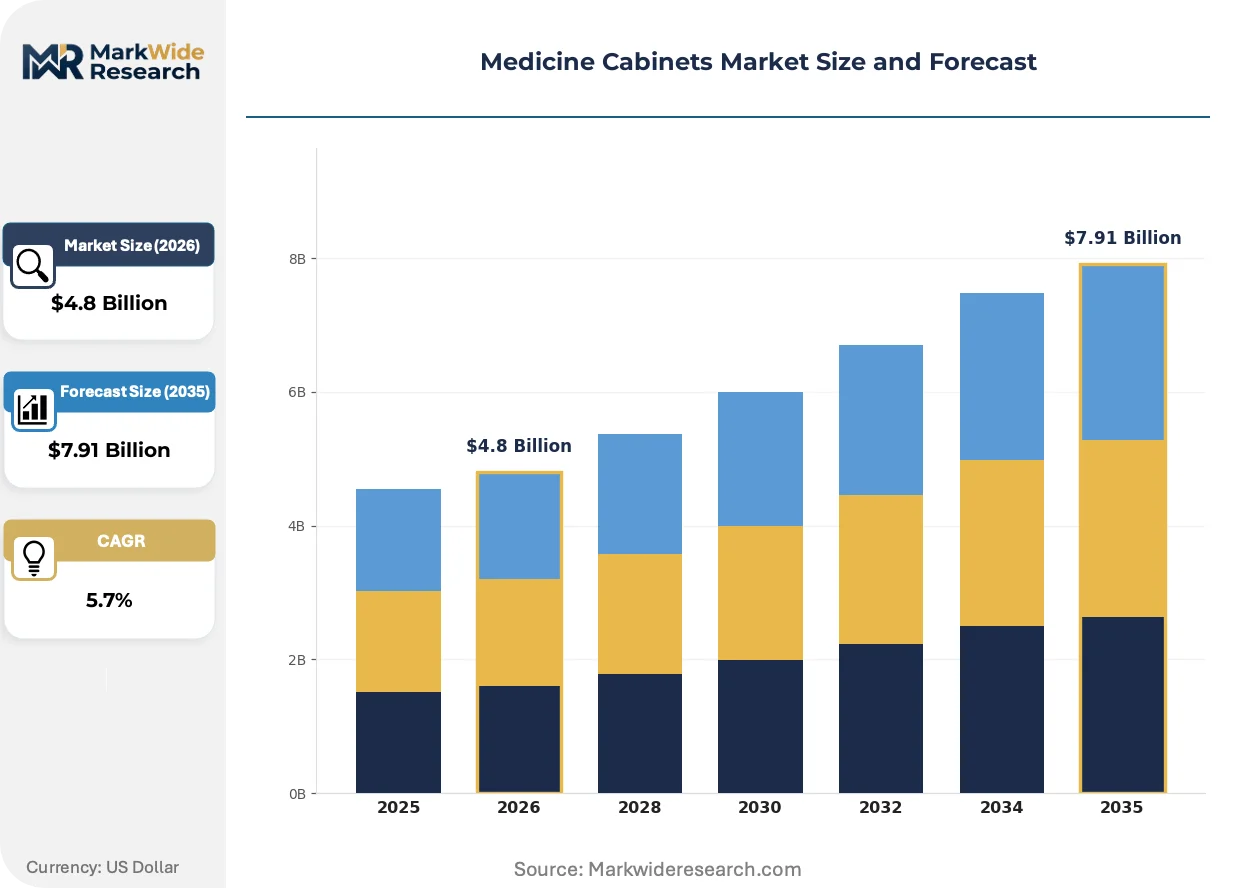
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted, Freestanding, Corner, Under-sink Material: Wood, Metal, Glass, Plastic Storage Capacity: Compact, Medium, Large, Extra-large Design Style: Modern, Traditional, Rustic, Minimalist |
| Companies Covered | Kohler, Robern, Bradley Corp., Afina Corporation, Duravit, Ketcham Medicine Cabinets, Foremost Medicine Cabinet, American Specialties, Inc., Casta Cabinetry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicine Cabinets Market Emerging Trajectories
Active innovation in medicine cabinets centers on material science convergence, regulatory compliance automation, and channel restructuring that separates hardware sales from installation services.
Aluminum-frame construction with integrated LED edge lighting is hybridizing traditional storage functionality with ambient bathroom illumination. Luxury residential developers in metropolitan renovation corridors specify these units at accelerating rates. The technology is compressing demand for standalone vanity lighting fixtures while elevating cabinet positioning from utilitarian storage to design centerpiece.
EU Green Deal Ecodesign frameworks are forcing material passport documentation across imported cabinetry supply chains. Manufacturers must now trace engineered wood substrates, aluminum alloys, and mirror coatings through certified chain-of-custody systems. European importers and specification architects are responding by qualifying only suppliers with third-party verified recycled content and restricted substance compliance.
Buyer concentration among national home improvement retailers is consolidating procurement leverage and compressing supplier margins. Independent distributors and direct-to-contractor channels are losing share to centralized purchasing platforms that bundle cabinet specifications with installation services. This pattern is most visible in United States suburban single-family replacement cycles, where big-box retailers coordinate turnkey bathroom renovation packages.
Medicine Cabinets Market Segmentation
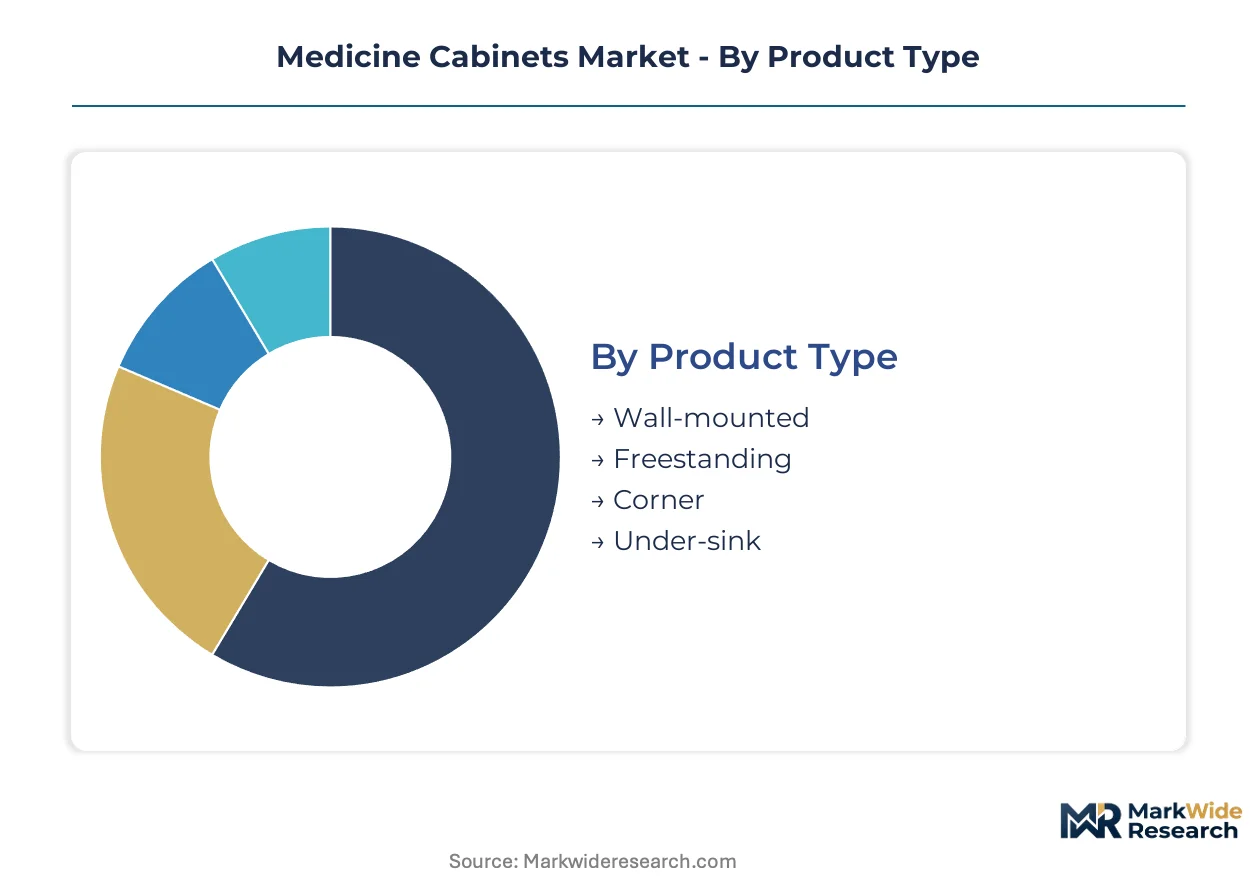
Medicine cabinet segmentation reveals distinct procurement patterns across installation constraints, material durability requirements, and spatial economics. Each dimension carries specific regulatory and channel implications that reshape supplier qualification and margin structures.
Product Type:
Mature retrofit solutions dominate volume while emerging configurations capture specification-driven replacement cycles.
- Wall-mounted:Surface-mounted aluminum or steel frames attach directly to finished walls without cavity modification. Aging housing stock across United States metropolitan renovation corridors drives specification, as contractors minimize invasive structural work in bathroom retrofits.
- Freestanding:Floor-based units with integrated legs or pedestal bases serve rental properties and temporary installations where wall penetration is restricted. Demand concentrates in multi-family housing developments with lease-turnover maintenance protocols.
- Corner:Triangular profiles maximize storage in spatially constrained powder rooms and guest bathrooms.
- Under-sink:Base-cabinet integrations conceal plumbing while providing auxiliary pharmaceutical storage.
Wall-mounted configurations handle the majority of throughput; compact urban units are expanding most quickly on specification share.
Material:
Cost tier stratification separates premium metal construction from economy plastic alternatives, with mid-market wood substrates facing emission compliance pressures.
- Metal:Aluminum and stainless steel frames with powder-coated or brushed finishes deliver corrosion resistance for humidity-intensive environments. OSHA healthcare facility mandates institutionalize metal construction in hospital and clinic procurement across commercial channels.
- Wood:Engineered substrates with moisture-resistant laminates or veneers occupy mid-market residential renovation specifications. EPA formaldehyde emission thresholds disqualify uncertified panel suppliers from big-box retail distribution.
- Glass:Tempered mirror assemblies with moisture-sealed backing dominate door construction.
- Plastic:Injection-molded ABS or polypropylene cabinets serve budget-conscious multi-unit developers and institutional bulk procurement.
Metal construction commands premium positioning; plastic alternatives are climbing the fastest in volume from cost-sensitive development segments.
Storage Capacity:
Customer type divergence separates space-constrained urban dwellers from suburban homeowners with expansive bathroom footprints.
- Compact:Single-shelf or narrow-profile units under 18 inches width address studio and micro-unit residential construction. Metropolitan United States corridors with high-density zoning drive steepest expansion trajectory for this tier.
- Medium:Standard 24-30 inch widths with two adjustable shelves serve typical suburban single-family bathroom replacement cycles.
- Large:Double-door or extended-width configurations accommodate family pharmaceutical storage and shared bathroom layouts.
- Extra-large:Custom or built-in units exceeding 36 inches width occupy luxury residential and hospitality specification channels.
Medium capacity maintains replacement-cycle dominance; compact formats are gaining share fastest from urban densification trends.
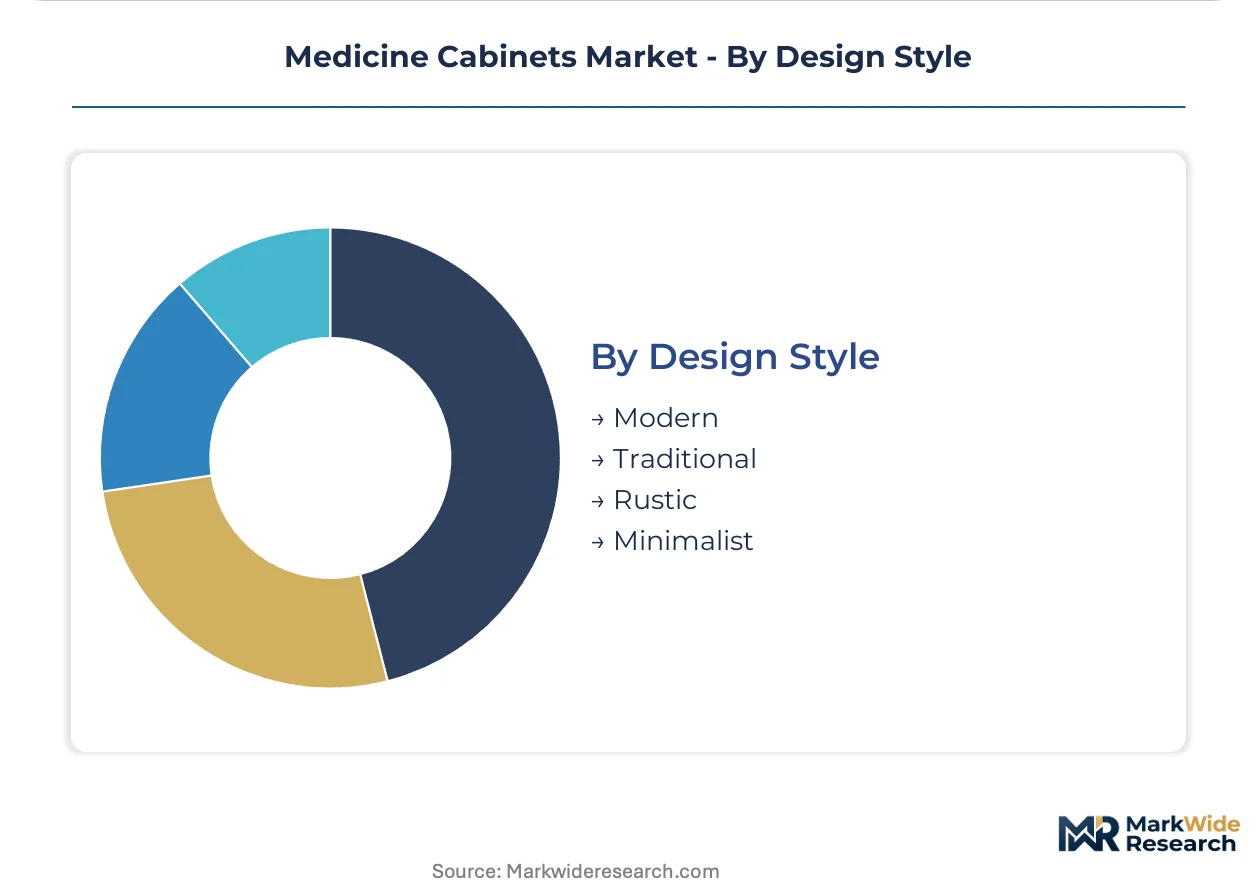
Design Style:
Geography and channel concentration shape aesthetic specification, with modern and minimalist profiles accelerating in coastal metropolitan markets.
- Modern:Clean lines, frameless mirrors, and integrated LED edge lighting align with contemporary bathroom renovations. Luxury residential developers in United States coastal corridors specify these units at accelerating rates for design-center positioning.
- Traditional:Raised-panel doors, decorative hardware, and ornamental framing serve established suburban housing stock with classical architectural continuity.
- Rustic:Distressed wood finishes and vintage-inspired hardware capture vacation property and farmhouse-style renovation segments.
- Minimalist:Handle-less profiles with concealed hinges and recessed pulls address ultra-contemporary architectural specifications.
Traditional styling retains volume leadership in replacement markets; modern profiles show the steepest specification climb in new luxury construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting corridors and tempered glass manufacturing clusters concentrate supply-side capacity across three continents. Demand dispersion follows metropolitan renovation cycles in aging housing stock and healthcare infrastructure buildouts.
United States
Metropolitan renovation corridors in the Northeast and Midwest drive wall-mounted retrofit specifications as contractors minimize invasive structural work. OSHA healthcare facility mandates institutionalize corrosion-resistant metal construction in hospital procurement. The Southeast Sun Belt corridor accelerates compact cabinet specifications for high-density urban micro-unit developments.
Germany
REACH compliance documentation and Ecodesign framework requirements under the EU Green Deal force engineered wood substrate transparency across imported cabinetry. The country's national building regulator enforces stringent indoor air quality thresholds for formaldehyde emissions. Industrial clusters in North Rhine-Westphalia concentrate metal fabrication capacity serving commercial healthcare specifications.
China
Raw material input volatility in energy-intensive aluminum smelting shapes export pricing dynamics for metal-framed cabinet components. The Ministry of Ecology and Environment enforces dual carbon goals that tighten smelter operating permits. Manufacturing corridors in Guangdong Province dominate tempered mirror assembly production for global supply chains.
Japan
Compact residential footprints in metropolitan Tokyo and Osaka prefectures drive specification of narrow-profile storage units under 18 inches width. METI building efficiency standards mandate moisture-resistant construction in humid climate zones. Industrial clusters in the Chubu region around Nagoya concentrate precision metal finishing for premium residential channels.
India
Rapid urbanization in Maharashtra and Karnataka states expands multi-unit residential construction with cost-sensitive plastic cabinet procurement. The Bureau of Indian Standards enforces emerging certification requirements for building material emissions. Manufacturing corridors in Gujarat state develop engineered wood substrate capacity targeting mid-market export segments.
Medicine Cabinets Market Vendor Landscape
Full-line bathroom fixture conglomerates and specialized mirrored-storage specialists split the market between scale-driven distribution and technology-differentiated positioning. Three archetypes dominate: captive distribution networks leveraging retail channel control, specification-driven specialists anchoring institutional healthcare procurement, and integrated design houses bundling cabinetry with full bathroom suites. Competitive moves center on backward integration into aluminum extrusion capacity and technology licensing for LED-integrated mirror systems.
Among North American fixture conglomerates, Kohler Co. and Bradley Corp. exemplify divergent strategic archetypes. Kohler anchors premium residential positioning through captive distribution network control. Bradley Corp. occupies institutional specification dominance in healthcare and commercial facility channels. Within the specialized mirrored-storage tier, Robern represents technology convergence strategies integrating ambient lighting and connectivity features. European design houses including Duravit and Afina Corporation sit within the integrated bathroom-suite bundling archetype, leveraging cross-product specification pull-through.
| Leading Market Players |
|---|
| Kohler |
| Robern |
| Bradley Corp. |
| Afina Corporation |
| Duravit |
| Ketcham Medicine Cabinets |
| Foremost Medicine Cabinet |
| American Specialties, Inc. |
| Casta Cabinetry |
| Others |
Supply Flow & Price Mechanics
Aluminum price volatility from energy-intensive smelting economics determines both pricing tier spreads and supply chain shape across metal-framed cabinet production. Input cost fluctuations compress margin stability for mid-tier manufacturers while forcing premium suppliers toward backward integration into captive extrusion capacity.
Pricing Analysis
REACH and RoHS compliance dictates the pricing tier structure across European import channels. Three-tier pricing structure across premium, standard, and economy levels separates certified metal construction with full material passports from uncertified engineered wood substrates and injection-molded plastic alternatives. Price differentiation hinges on emission certification grade and corrosion-resistance hardware specifications. Pricing pressure stems from aluminum smelting cost volatility, compressing margins for non-integrated manufacturers. Multi-unit developers exhibit highest price sensitivity, while luxury residential channels absorb premium positioning for LED-integrated and anti-fog mirror systems.
Supply Chain Analysis
Extended payment terms from big-box retailers strain supplier working capital across distribution networks. Manufacturing concentrates in China, Germany, and the United States, with Guangdong Province dominating tempered mirror assembly and North Rhine-Westphalia anchoring metal fabrication for healthcare specifications. Raw material inputs draw from aluminum smelting corridors, engineered wood panel producers, and tempered glass manufacturers. Single-source vulnerability in tempered mirror production exposes lead time risks from concentrated manufacturing clusters. Distribution runs through national home improvement retailers consolidating procurement leverage, with independent distributors losing share to centralized purchasing platforms bundling installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as metropolitan renovation cycles and healthcare infrastructure buildouts generate specification niches underserved by full-line conglomerates. Channel restructuring toward turnkey service bundling separates hardware sales from installation revenue, opening vertical specialization paths.
For Market Incumbents: Pre-empt margin compression from aluminum volatility by securing captive extrusion capacity in domestic smelting corridors. Defensive consolidation should target specialized mirrored-storage technology portfolios to block LED-integrated system convergence by emerging competitors. Certification investment in REACH documentation and OSHA healthcare compliance institutionalizes specification dominance in institutional procurement channels.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka multi-unit residential corridors offer underpenetrated cost-sensitive procurement segments with limited incumbent specialization. White-space targets include compact storage tiers for urban micro-unit development and aftermarket refurbishment services unbundled from original equipment sales. Direct-to-contractor channel positioning bypasses big-box retail consolidation, capturing installation-margin capture in fragmented labor markets.
For Investors and Strategic Acquirers: EU Green Deal Ecodesign framework implementation reshapes the acquisition landscape toward suppliers with verified material passport systems and recycled content documentation. Long-term viability favors mid-cap specialists with backward integration into aluminum extrusion and certified engineered wood substrate sourcing. The signal to watch is REACH compliance timeline acceleration, which would disqualify legacy suppliers lacking third-party certification infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive smelting capacity insulates margin stability from energy price volatility. |
| Material Passport Certification Investment | Third-party verified documentation qualifies suppliers for EU Green Deal procurement. |
| Aftermarket Service Network Expansion | Recurring refurbishment revenue separates from cyclical new construction demand. |
| LED-Integrated Mirror Technology Licensing | Ambient lighting convergence commands premium positioning in luxury residential channels. |
| Direct-to-Contractor Channel Development | Bypasses big-box retail consolidation capturing installation-margin in fragmented markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and hospital procurement databases. Primary interviews engaged product managers at fixture conglomerates, specification architects at healthcare facility design firms, procurement officers at national home improvement retailers, and installation contractors in metropolitan renovation corridors. Secondary validation drew from EPA emission compliance records, OSHA healthcare facility standards documentation, EU Ecodesign framework publications, and aluminum smelting industry reports. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Forecast inputs include residential renovation cycle velocity, healthcare infrastructure capital expenditure patterns, and urban densification zoning approvals across metropolitan corridors. Modeled dimensions span installation type, material construction, storage capacity tier, design style, and end-use channel. CAGRs derive from segment-level volume trajectories weighted by price realization trends. Industry-specific inputs incorporate REACH compliance cost pass-through assumptions and tempered glass supply concentration risk adjustments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese aluminum extruders or accelerated EU chemical restriction timelines would shift outcomes. Macroeconomic deviation in construction activity, regulatory threshold tightening, or LED-integrated system technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Medical Commodes Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Medical Bed Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Global Smart Hospital Bed Market