
 Non-Wearable Sleep Tracker Market | 2026-2036
Non-Wearable Sleep Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Wearable Sleep Tracker Market Intelligence
The transition from basic piezoelectric sensors to sophisticated radar and infrared components is rebalancing product cost structures and performance capabilities. Koninklijke Philips leverages its deep clinical expertise for devices aimed at healthcare institutions. In the consumer space, Eight Sleep specializes in smart bed technologies with integrated tracking, while Withings differentiates with products that connect to a wider home health ecosystem.
A non-wearable sleep tracker is a device that monitors sleep patterns without direct physical contact with the user. These systems utilize radar or infrared technology to detect micromovements, heart rate, and respiration from a distance. Smart beds and dedicated sleep monitors are the primary product forms, with the former commanding a premium. While households remain the largest end-user segment, applications in healthcare institutions for remote health monitoring represent the fastest-growing area.
Medical-grade devices require clearance from bodies like the US FDA and adherence to Europe's MDR, mandating clinical validation for any health claims. Consumer-focused products face general electronics safety rules, such as CE marking in the EU and FCC regulations in the United States. The strategic decision of whether to pursue medical device classification or remain in the wellness category dictates a company's development roadmap and market access.
Market Dynamics
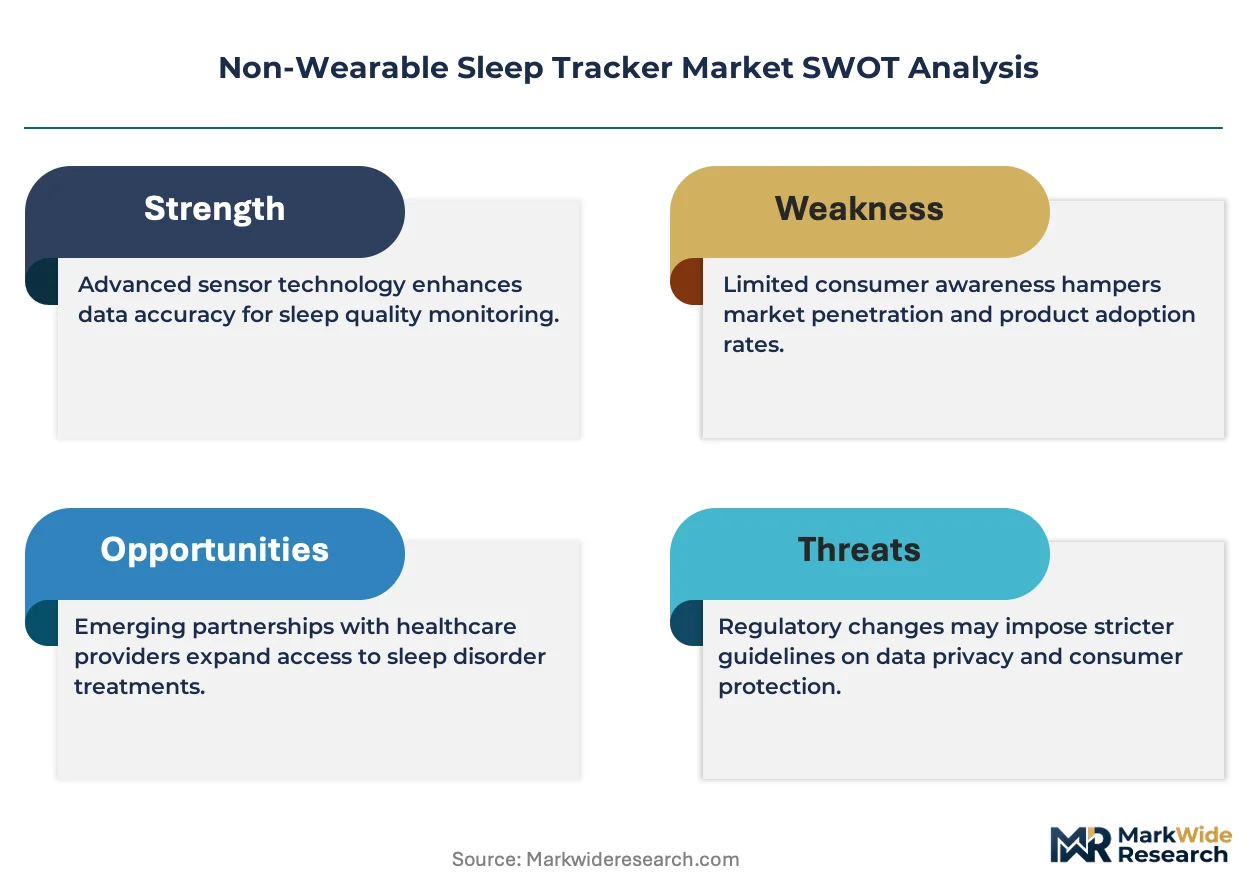
The central force shaping the market is the technological divergence between consumer wellness products and medical-grade devices. This split is driven by the shift to advanced radar and infrared sensors, which redefines cost structures and performance expectations for each segment.
Growth Catalysts
- Remote Patient Monitoring:Demand from US healthcare institutions is rising, driven by a focus on preventative care and continuous observation.
- Advanced Sensor Technology:Radar system integration enables contactless vital sign tracking, a key innovation attracting consumer and clinical users.
- Insurance Reimbursement:Growing acceptance of remote monitoring data by payors creates financial incentives for healthcare providers to adopt these devices.
Market Restraints
- Component Costs:The high price of medical-grade radar and infrared components limits affordability in the consumer segment.
- Regulatory Hurdles:Stringent validation requirements for medical devices under the FDA and Europe's MDR create significant barriers to entry.
- Data Accuracy Concerns:User skepticism about the precision of contactless measurements, especially in multi-person settings, restrains adoption.
Strategic Opportunities
- Specialized Healthcare:Expansion into elder care and post-operative recovery units offers opportunities for continuous, non-intrusive monitoring.
- Ecosystem Integration:Converging sleep data with smart home systems for automated environmental adjustments creates enhanced user value.
- Geographic Expansion:Targeting digitally advanced markets with aging populations, like Japan and South Korea, provides new growth avenues.
Industry Challenges
- Data Security and Privacy:Ensuring compliance with regulations like GDPR and HIPAA is a critical challenge due to the sensitive health data collected by devices.
- System Interoperability:Integrating tracker data with disparate Electronic Health Record (EHR) systems in hospitals remains a major technical and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Wearable Sleep Tracker Market |
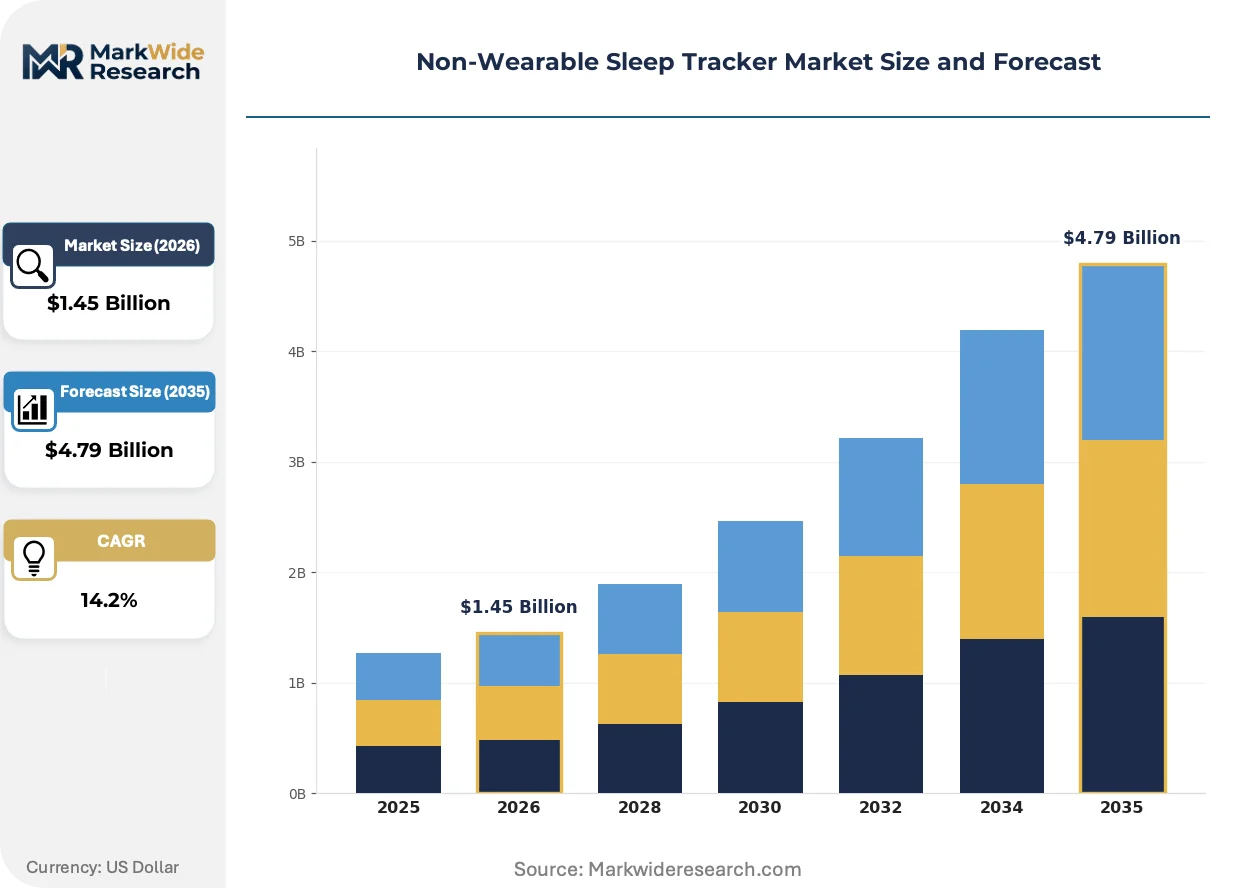
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $4.79 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bed, Sleep Monitor, Non-Invasive Sensor, Tracking Device Technology: Infrared, Radar, Audio Analysis, Vibration Sensor End User: Households, Healthcare Institutions, Sleep Clinics, Fitness Centers Application: Sleep Quality Assessment, Health Monitoring, Sleep Disorder Detection, Lifestyle Tracking |
| Companies Covered | Simmons Bedding Company, Sleep Number Corporation, Apple, Xiaomi, Koninklijke Philips, ResMed, Emfit, Eight Sleep, Withings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Wearable Sleep Tracker Market Strategic Shifts & Innovations
The market's evolution is defined by a bifurcation into clinical-grade medical instruments and consumer-oriented wellness products. This divergence influences everything from technology choices and regulatory pathways to go-to-market strategies for manufacturers in each segment.
Multi-sensor fusion combines radar for micromovements with thermal imaging for body temperature, offering a more complete sleep profile. Healthcare institutions are adopting these systems for monitoring patients in non-critical care settings. This combination of data streams is electrifying the diagnostic potential of non-wearable devices, moving them closer to clinical-grade polysomnography.
Europe's Medical Device Regulation (MDR) imposes stricter rules for clinical evidence and post-market surveillance on devices making health claims. This regulation forces a clear choice for manufacturers between investing in validation for medical classification or remaining in the wellness category. Devices aimed at the European healthcare market are most affected, facing longer development cycles.
Consumers are increasingly buying sleep trackers as part of a bundled smart bed or an integrated home health system. This shift favors companies providing complete ecosystem solutions, disrupting the market for standalone monitors. The bundling trend is most visible in the North American consumer market, fueled by a preference for integrated smart home technology.
Non-Wearable Sleep Tracker Market Segmentation
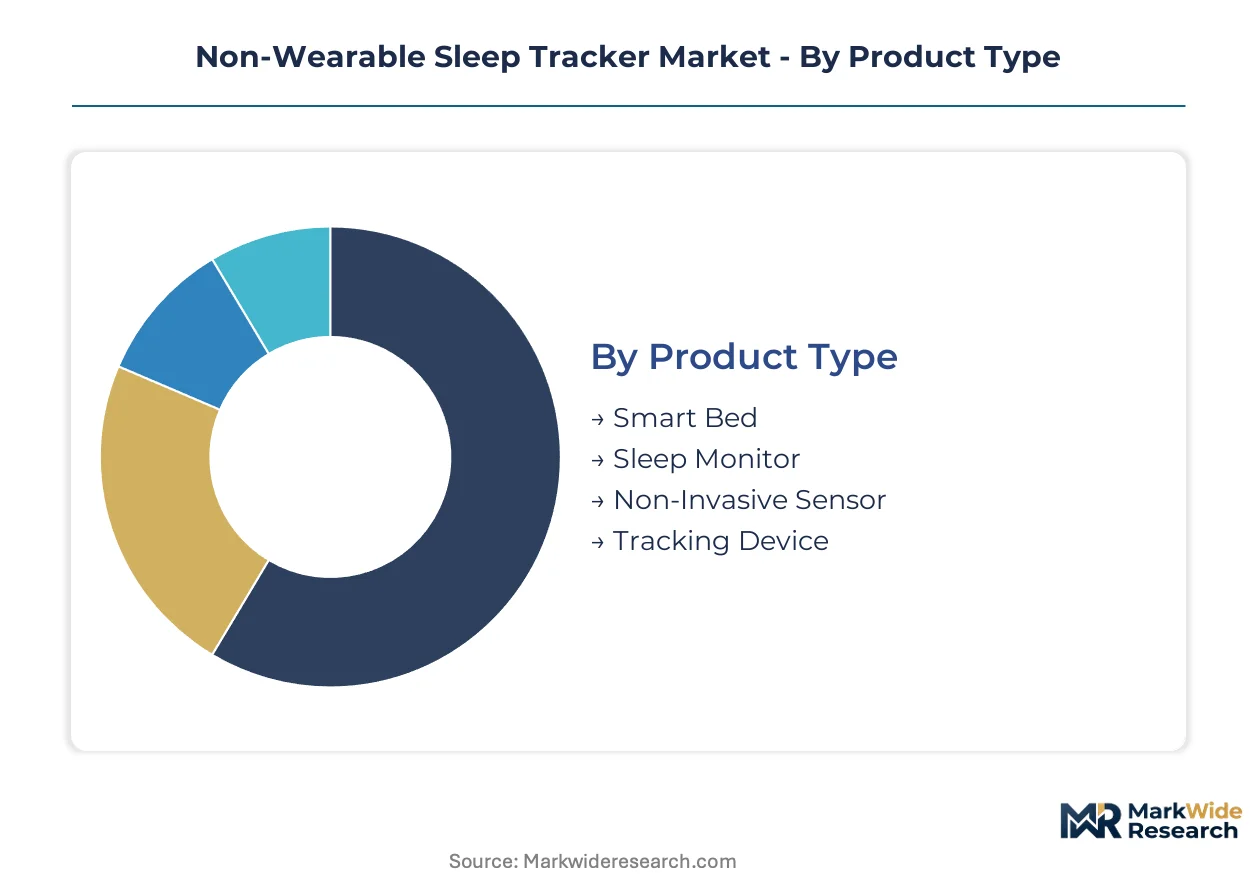
The non-wearable sleep tracker market segments into distinct categories based on product design, underlying technology, target users, and primary applications. Understanding these divisions is crucial for manufacturers to tailor development and market strategies effectively.
Product Type:
The market's product offerings are defined by their core design and integration capabilities.
- Smart Bed:These integrated systems embed sleep tracking technology directly into the mattress or bed frame, providing seamless data collection. Demand concentrates in the North American consumer market, driven by a preference for integrated smart home technology.
- Sleep Monitor:Dedicated devices that are placed near the bed, utilizing radar or infrared technology to track sleep patterns without direct contact. Households remain a significant end-user, while healthcare institutions increasingly adopt these for patient monitoring.
- Non-Invasive Sensor:These sensors are typically placed under a mattress or sheet, detecting micromovements and vital signs without user interaction.
- Tracking Device:A broad category encompassing various non-wearable gadgets designed for general sleep pattern observation, often integrated into larger wellness ecosystems.
Smart Bed leads on scale; Sleep Monitor leads on momentum.
Technology:
The cost structure of non-wearable sleep trackers varies significantly based on the underlying sensor technology.
- Radar:This technology employs radio waves to detect micromovements, heart rate, and respiration from a distance, offering contactless vital sign tracking. US healthcare institutions are increasingly adopting radar systems for preventative care and continuous observation.
- Infrared:Infrared sensors detect body temperature, presence, and heat signatures, contributing to a comprehensive sleep profile when combined with other sensors. Multi-sensor fusion incorporating infrared is gaining traction in clinical-grade applications.
- Audio Analysis:These systems monitor sleep sounds such as snoring, sleep talking, and breathing patterns to infer sleep quality and potential disturbances.
- Vibration Sensor:Simple sensors that detect bed movement and restlessness, often used for basic sleep stage detection in entry-level devices.
Radar technology currently dominates adoption while Infrared technology offers complementary data streams.
End User:
The primary application areas for non-wearable sleep trackers reflect diverse user needs and operational environments.
- Households:Consumers purchase these devices for personal wellness, sleep quality improvement, and integration into smart home systems. The North American consumer market shows strong demand for integrated home health solutions.
- Healthcare Institutions:Hospitals and clinics deploy non-wearable trackers for remote patient monitoring, continuous observation in non-critical settings, and post-operative recovery. Demand from US healthcare institutions is rising due to preventative care initiatives.
- Sleep Clinics:Specialized medical facilities use these devices as supplementary tools for sleep diagnostics and patient assessment.
- Fitness Centers:These establishments integrate sleep tracking into broader wellness and performance optimization programs for their members.
Households represent the largest user base, with Healthcare Institutions expanding most quickly.
Application:
Volume demand for non-wearable sleep trackers is driven by specific use cases across consumer and clinical settings.
- Health Monitoring:Continuous tracking of vital signs like heart rate and respiration for remote patient observation and early detection of health anomalies. Insurance reimbursement for remote monitoring data creates financial incentives for healthcare providers in the United States.
- Sleep Quality Assessment:Devices measure sleep duration, sleep stages, and efficiency to provide users with insights into their overall sleep health and patterns. The consumer segment drives demand for these general wellness applications, often as part of integrated smart home systems.
- Sleep Disorder Detection:These applications focus on identifying patterns indicative of conditions like sleep apnea or insomnia, often requiring clinical validation for medical claims.
- Lifestyle Tracking:Integration with broader wellness platforms to correlate sleep data with activity levels, diet, and other lifestyle factors for holistic health management.
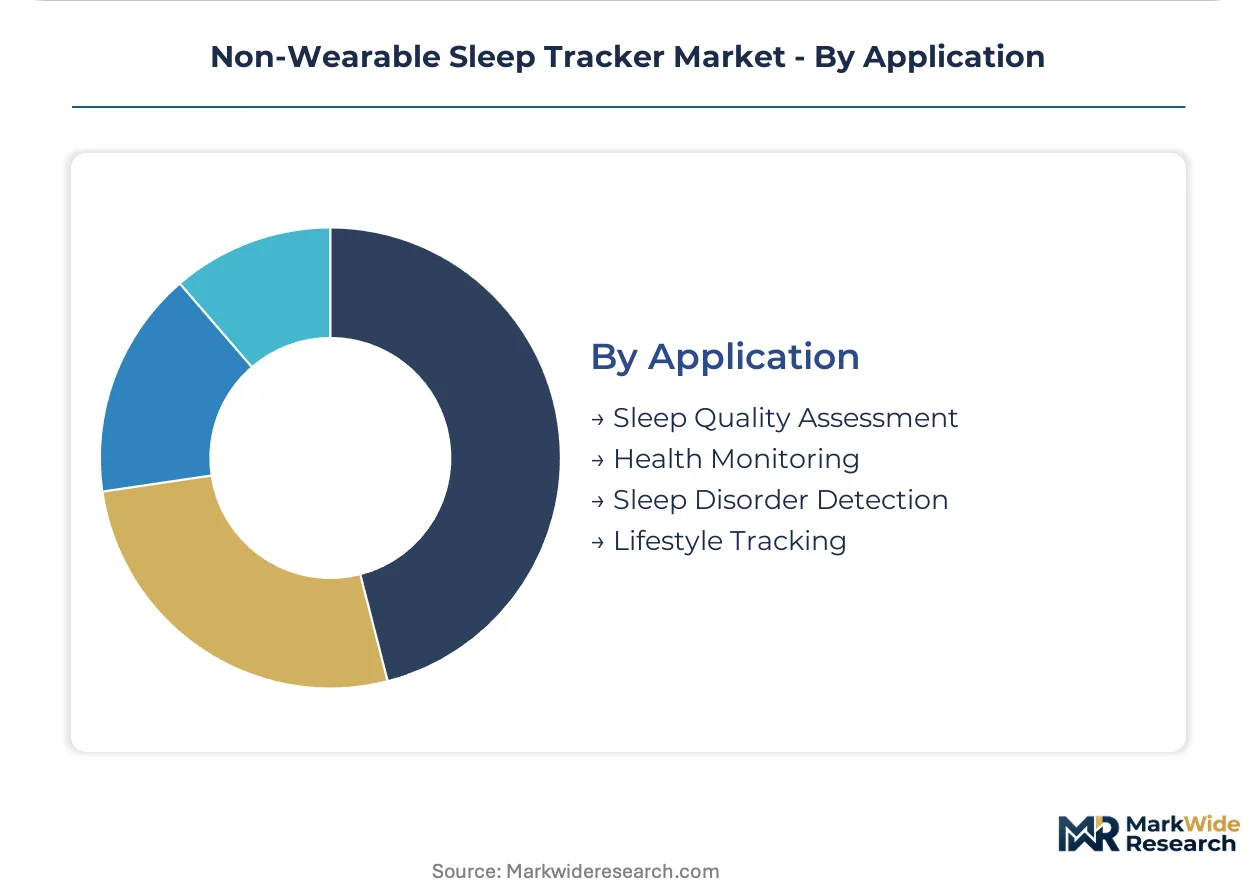
Health Monitoring holds significant clinical relevance, while Sleep Quality Assessment drives broad consumer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's tech hub, notably Silicon Valley, drives substantial innovation in non-wearable sleep tracker development. Preventative healthcare and remote patient monitoring initiatives in the United States create robust demand for advanced devices. This region attracts significant investment for health technology startups and established medical device manufacturers.
United States
Demand from US healthcare institutions for remote patient monitoring continues to rise, especially for continuous observation. The US FDA clearance process for medical-grade devices ensures stringent validation and safety standards. Silicon Valley and Boston's biotech corridor are key centers for research and commercialization of advanced sleep monitoring solutions.
Japan
Japan's aging population and high digital literacy fuel demand for non-wearable home health monitoring systems. The Ministry of Economy, Trade and Industry (METI) supports health-tech innovation and data integration initiatives. Tokyo's research institutions are actively advancing multi-sensor fusion technologies for comprehensive sleep analysis.
Germany
Germany places a strong emphasis on clinical validation and medical device quality under Europe's Medical Device Regulation (MDR). Healthcare providers increasingly integrate non-wearable solutions for non-intrusive patient care in various settings. Munich's medical technology cluster fosters significant collaboration between industry and academic research.
China
China's large consumer base and rising health consciousness stimulate demand for wellness-oriented sleep trackers and smart home integration. The National Medical Products Administration (NMPA) guides the market for medical devices making health claims. Shenzhen's robust electronics manufacturing ecosystem provides a strong base for production and innovation.
South Korea
South Korea exhibits high adoption rates for smart home technologies, and a rapidly aging society increases demand for remote health monitoring. The Ministry of Food and Drug Safety (MFDS) regulates product safety and efficacy for devices with health claims. Seoul's tech companies are developing integrated home health ecosystems that incorporate sleep tracking.
Non-Wearable Sleep Tracker Market Key Industry Players
Strategic partnerships dominate the current landscape, as companies seek to expand their technological capabilities and market reach. The market structure bifurcates between highly regulated medical device manufacturers and agile consumer wellness brands. Key strategic archetypes include clinical-grade specialists, consumer-focused smart bed providers, and broader home health ecosystem integrators. Technology licensing and geographic expansion into digitally advanced markets represent dominant competitive moves.
Within the clinical-grade medical device tier, Koninklijke Philips leverages its extensive clinical expertise to develop solutions for healthcare institutions. Eight Sleep exemplifies the consumer-focused smart bed segment, specializing in integrated sleep tracking technologies. Withings occupies a position as a consumer wellness brand that differentiates through its connection to a wider home health ecosystem.
| Leading Market Players |
|---|
| Simmons Bedding Company |
| Sleep Number Corporation |
| Apple |
| Xiaomi |
| Koninklijke Philips |
| ResMed |
| Emfit |
| Eight Sleep |
| Withings |
| Others |
Cost & Logistics Intelligence
US healthcare institutions' increasing demand for continuous patient monitoring shapes value-based pricing models for medical-grade non-wearable sleep trackers. Consumer preferences for integrated smart home systems drive bundled pricing for wellness products.
Pricing Analysis
Component cost pass-through significantly impacts pricing for non-wearable sleep trackers. Value-based pricing dominates the medical-grade segment, driven by FDA/MDR certification and integrated data analytics platforms. Price differentiation also stems from advanced radar technology and established brand premium for clinical devices. Pricing softness affects the consumer segment due to intense competition and high component costs, making households more price-sensitive than healthcare institutions.
Supply Chain Analysis
Single-source vulnerability sits with specialized sensor manufacturers, particularly for medical-grade radar and infrared components. Component production concentrates in China for general electronics, while advanced sensor R&D and manufacturing occur in the United States and parts of Europe. The market depends on a steady supply of radar modules, infrared sensors, and microcontrollers. Geopolitical tensions and component shortages represent a structural risk. Distribution runs through specialized medical device distributors for healthcare institutions and broad retail/e-commerce channels for consumer products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-wearable sleep tracker market is transitioning into a late-cycle quality story. Demand is shifting towards premium specifications, particularly for devices offering multi-sensor fusion and clinical-grade accuracy.
For Market Incumbents: To counter stringent regulatory hurdles, established incumbents must invest heavily in clinical validation for medical device classification. Deepen vertical integration into advanced sensor manufacturing to mitigate component cost volatility. Expand R&D efforts into multi-sensor fusion technologies to enhance data accuracy and diagnostic potential. Control distribution channels within healthcare institutions through strategic partnerships and long-term contracts.
For New Entrants and Emerging Players: Elder care facilities represent an underserved buyer archetype for non-wearable sleep trackers, seeking non-intrusive monitoring solutions. Target small clinics and remote patient monitoring programs with cost-effective, clinically validated devices. Develop specialized software companions for data interpretation, offering a unique value proposition. Focus go-to-market strategies on direct sales to healthcare providers, emphasizing ease of integration with existing EHR systems.
For Investors and Strategic Acquirers: Large medical device conglomerates are the most active acquirers in this space, seeking to expand their remote patient monitoring portfolios. The long-term viability favors companies with strong intellectual property in sensor technology and robust regulatory clearances. Identify acquisition targets with proven clinical validation and established integration capabilities with Electronic Health Record systems. The signal to watch is the increasing insurance reimbursement for remote monitoring data, indicating market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Secures FDA/MDR clearance, expanding access to regulated healthcare markets. |
| Multi-Sensor Fusion R&D | Enhances diagnostic accuracy, moving devices closer to clinical-grade polysomnography. |
| EHR System Integration | Improves data flow for healthcare providers, streamlining remote patient monitoring. |
| Geographic Expansion (Japan/South Korea) | Capitalizes on aging populations and high digital literacy for new growth. |
| Smart Home Ecosystem Partnership | Bundles sleep trackers with integrated systems, increasing consumer value. |
Research Approach
Bottom-up end-user modeling for households and healthcare institutions, reconciled against top-down sensor manufacturer tracking, forms the analytical core. This approach combines primary interviews with clinicians, hospital procurement managers, smart home integrators, and sensor R&D directors. Secondary validation draws from FDA filings, Europe's MDR guidance, smart home technology reports, and customs data. This triangulation ensures robust market sizing and trend identification.
Historical trendline analysis informs the projection of market trajectories across the analysis window. The framework models segmentation dimensions including product type, underlying technology, end-user categories, and application areas, alongside regulatory classification. Compound annual growth rates are derived from a weighted average of historical performance and future market drivers. Key forecast inputs include sensor technology advancements and evolving insurance reimbursement policies for remote monitoring.
Underlying measurement precision varies by segment; medical-grade devices carry tighter precision than consumer wellness products. Forecasts reflect assumptions regarding regulatory changes, rapid technological shifts, and data privacy concerns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market