
 Emphysema Treatment Market | 2026-2036
Emphysema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Emphysema Treatment Market Analysis
Hospital systems are reorganizing their procurement of emphysema therapies, shifting volume toward integrated delivery networks that negotiate formulary placement directly with manufacturers. GlaxoSmithKline plc dominates the bronchodilator segment through its established respiratory franchise. AstraZeneca leverages biologics development capabilities to differentiate in severe emphysema subsets. Boehringer Ingelheim International GmbH anchors the European hospital channel with its inhaled corticosteroid portfolio.
Emphysema treatment encompasses pharmacological and non-pharmacological interventions targeting alveolar wall destruction, with bronchodilators typically formulated as metered-dose inhalers delivering measured doses of beta-agonists or anticholinergics to improve expiratory airflow. The primary purpose is to reduce dyspnea, prevent acute exacerbations, and preserve functional lung capacity in patients with confirmed airflow limitation. Bronchodilators command the largest revenue pool among product types due to chronic daily use patterns, while oxygen therapy generates the highest per-patient margins despite smaller patient volumes. Inhalation delivery mode leads prescription volume globally, though home care settings are expanding as a distribution channel as payors push for reduced hospital readmission costs.
The FDA maintains stringent bioequivalence requirements for generic inhaled therapies, creating barriers to substitution that protect branded pricing power. The EPA regulates propellants in pressurized inhalers, driving formulation transitions that alter manufacturing costs and supply chain configurations. The Centers for Medicare & Medicaid Services sets reimbursement thresholds for long-term oxygen therapy and pulmonary rehabilitation that directly shape provider adoption decisions. Stakeholders must monitor how evolving FDA guidance on complex generic inhalers and CMS bundled payment models for chronic respiratory conditions will reshape competitive dynamics and investment priorities across the treatment landscape.
Market Dynamics
Hospital procurement consolidation is restructuring how emphysema therapies reach patients, with integrated delivery networks extracting volume commitments from manufacturers in exchange for formulary access and long-term supply contracts.
Growth Catalysts
- CMS bundled payments for chronic respiratory conditions:Medicare reimbursement models reward coordinated care, incentivizing health systems to invest in comprehensive COPD management programs that standardize therapy selection.
- Home care oxygen delivery infrastructure:Durable medical equipment suppliers have expanded remote monitoring capabilities, enabling earlier hospital discharge and sustained therapy adherence outside acute settings.
- Biologics pipeline expansion:Severe emphysema subsets with eosinophilic inflammation profiles are attracting targeted monoclonal antibody development, creating new addressable patient populations.
Market Restraints
- Propellant transition costs:EPA regulations phasing out hydrofluoroalkane propellants force reformulation of pressurized metered-dose inhalers, raising manufacturing complexity and capital requirements.
- FDA bioequivalence barriers:Complex generic inhaler approval standards protect branded pricing power while limiting price competition in the largest product category.
- Long-term oxygen therapy reimbursement compression:CMS competitive bidding programs have compressed per-patient margins for stationary and portable oxygen equipment suppliers.
Strategic Opportunities
- India's respiratory diagnostics gap:Underdiagnosis of COPD in rural populations creates latent demand for screening programs that would expand the treated patient pool.
- Telehealth-integrated pulmonary rehabilitation:Remote patient monitoring platforms enable CMS-reimbursable rehabilitation programs without facility-based infrastructure.
- Japan's aging smoker cohort:METI healthcare spending priorities align with emphysema intervention, given the country's high prevalence among males born 1945-1960.
Industry Challenges
- Inhaler technique training workforce:Pharmacists and respiratory therapists require specialized certification to demonstrate proper device use, creating bottlenecks in patient onboarding.
- Legacy oxygen concentrator fleet compatibility:Home care providers face capital-intensive upgrades as newer portable devices use incompatible power and cannula interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emphysema Treatment Market |
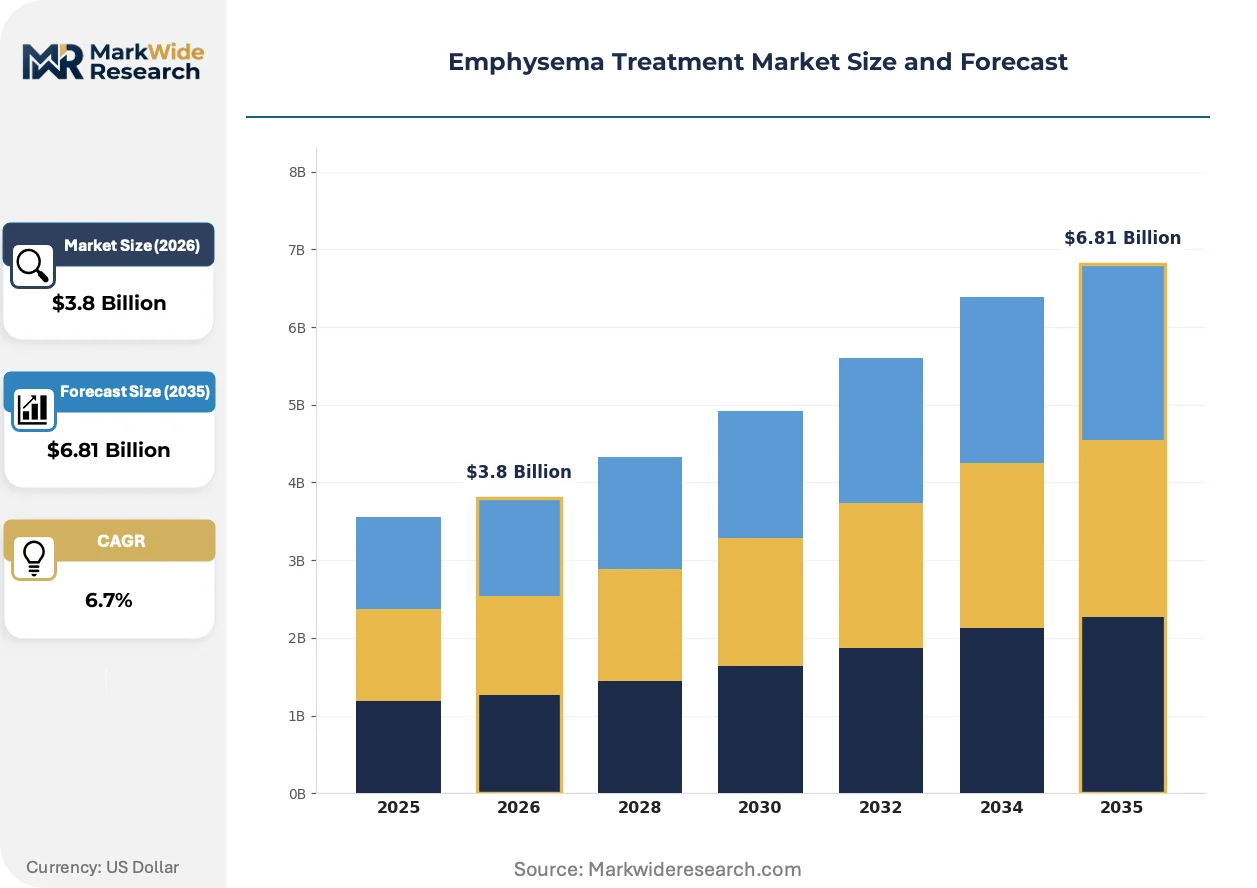
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Antidepressants, Oxygen Therapy Delivery Mode: Inhalation, Oral, Injectable, Transdermal End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Therapy Area: Respiratory Diseases, Chronic Lung Conditions, Smoking Cessation, Pulmonary Rehabilitation |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca, Boehringer Ingelheim International GmbH, Novartis AG, Viatris Inc., Teva Pharmaceutical Industries Ltd., Verona Pharma, Pfizer Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emphysema Treatment Market Emerging Trajectories
Digital respiratory medicine is converging with traditional pharmaceutical delivery, creating new data streams that reshape how adherence is measured and how payors evaluate therapy effectiveness.
Smart inhalers with embedded sensors are miniaturizing to the point of cost parity with conventional devices. Pulmonology clinics in the United States and Germany are piloting Bluetooth-enabled bronchodilators that transmit usage timestamps to electronic health records. This connectivity is miniaturizing the gap between prescribed and actual dosing, enabling intervention before exacerbation.
EMA's Medical Device Regulation is tightening clinical evidence requirements for combination products, forcing inhaler manufacturers to generate device-specific safety data beyond drug bioequivalence. European notified bodies have extended review timelines for connected inhaler submissions. Manufacturers are responding by segregating regulatory filings, pursuing drug approval first and device clearance second.
Integrated delivery networks are consolidating oxygen therapy procurement under single-source contracts that bundle equipment, maintenance, and respiratory therapist home visits. Durable medical equipment dealers are losing direct hospital relationships as IDNs centralize vendor management. This concentration is most visible in the United States, where Medicare Advantage plans in Florida and Texas have pioneered total-cost-of-care contracts for chronic respiratory patients.
Emphysema Treatment Market Segmentation
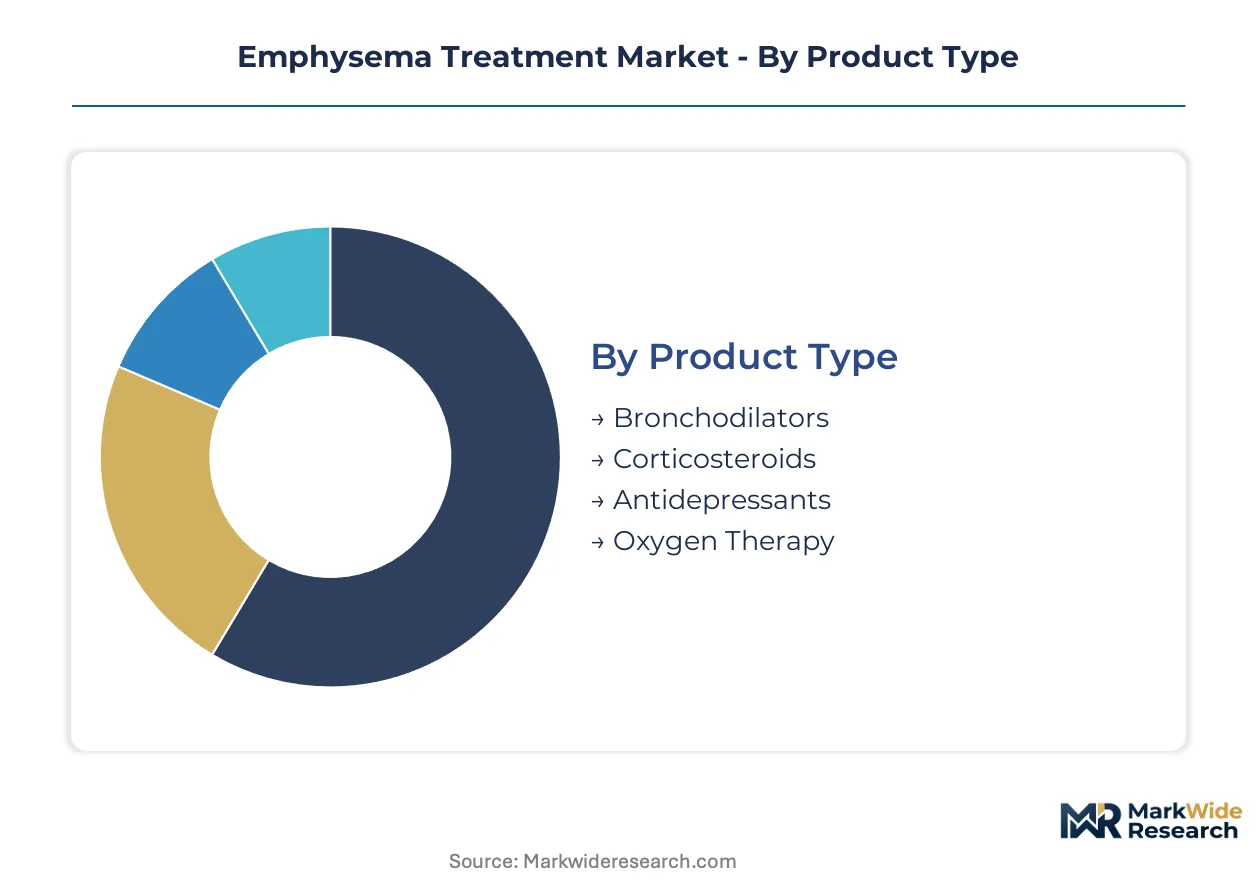
Segmentation in emphysema treatment reveals how clinical workflows, reimbursement structures, and patient acuity distribute demand across product formats and care settings. Manufacturers configure their portfolios around these fault lines to capture volume where procurement authority concentrates.
Product Type:
Substitution pressure runs highest among pharmacological segments where generic entrants and device alternatives erode branded positioning, while oxygen therapy maintains structural insulation through durable equipment bundling.
- Bronchodilators:Formulated as metered-dose inhalers or dry-powder devices delivering beta-agonists or anticholinergics to improve expiratory airflow. Hospital formularies in the United States and Germany concentrate procurement of these therapies where integrated delivery networks negotiate long-term supply contracts for chronic daily use populations.
- Oxygen Therapy:Comprises stationary concentrators, portable liquid systems, and compressed gas cylinders for hypoxemic patients. Medicare reimbursement thresholds in the United States create predictable payment streams that sustain durable medical equipment supplier margins despite competitive bidding compression on per-patient rates.
- Corticosteroids:Inhaled or systemic anti-inflammatory agents targeting airway hyperresponsiveness in exacerbation-prone patients.
- Antidepressants:Selective serotonin reuptake inhibitors and tricyclic compounds addressing anxiety-depression comorbidities that amplify dyspnea perception and reduce therapy adherence.
Bronchodilators anchors the volume base while Oxygen Therapy gains share at the steepest rate as home care infrastructure expands and payors push for reduced hospital readmission costs.
Delivery Mode:
Cost tier differentiation separates capital-intensive inhalation devices from commoditized oral formulations, with reimbursement coding determining which modalities providers prioritize in formulary design.
- Inhalation:Pressurized metered-dose inhalers, dry-powder inhalers, and nebulized solutions delivering medication directly to lung parenchyma. EPA propellant regulations in the United States and EMA Medical Device Regulation in Europe are forcing reformulation investments that alter manufacturing cost structures for device-drug combinations.
- Oral:Systemic corticosteroids, phosphodiesterase-4 inhibitors, and mucolytic agents for patients with poor inhaler technique or severe airflow limitation. Demand concentrates in emerging markets where device penetration lags and pharmacy dispensing favors pill-based regimens with simpler cold-chain requirements.
- Injectable:Biologic monoclonal antibodies targeting eosinophilic inflammation pathways in severe emphysema subsets.
- Transdermal:Nicotine replacement patches supporting smoking cessation in newly diagnosed patients.
Inhalation commands the prescription volume base while Injectable modalities expand most quickly as biologics pipelines advance through clinical development.
End User:
Customer type fragmentation reflects how care migration from acute facilities to community settings is redistributing procurement authority and altering therapy mix.
- Hospitals:Acute care facilities managing exacerbations through emergency department presentation and inpatient admission. United States hospital systems are consolidating vendor relationships under integrated delivery network structures that extract volume commitments from manufacturers in exchange for formulary placement.
- Home Care:Durable medical equipment suppliers and visiting nurse services delivering oxygen therapy and remote patient monitoring. Medicare Advantage plans in Florida and Texas have pioneered total-cost-of-care contracts that bundle equipment, maintenance, and respiratory therapist visits for chronic respiratory patients.
- Clinics:Outpatient pulmonology practices managing stable disease through periodic assessment and prescription renewal.
- Rehabilitation Centers:Facility-based and telehealth-integrated programs delivering CMS-reimbursable pulmonary rehabilitation.
Hospitals anchors the volume base while Home Care gains share fastest as remote monitoring platforms enable earlier discharge and sustained therapy adherence outside acute settings.
Therapy Area:
Maturity gradients separate well-established respiratory disease management from emerging smoking cessation and rehabilitation segments where evidence generation and reimbursement coding remain in development.
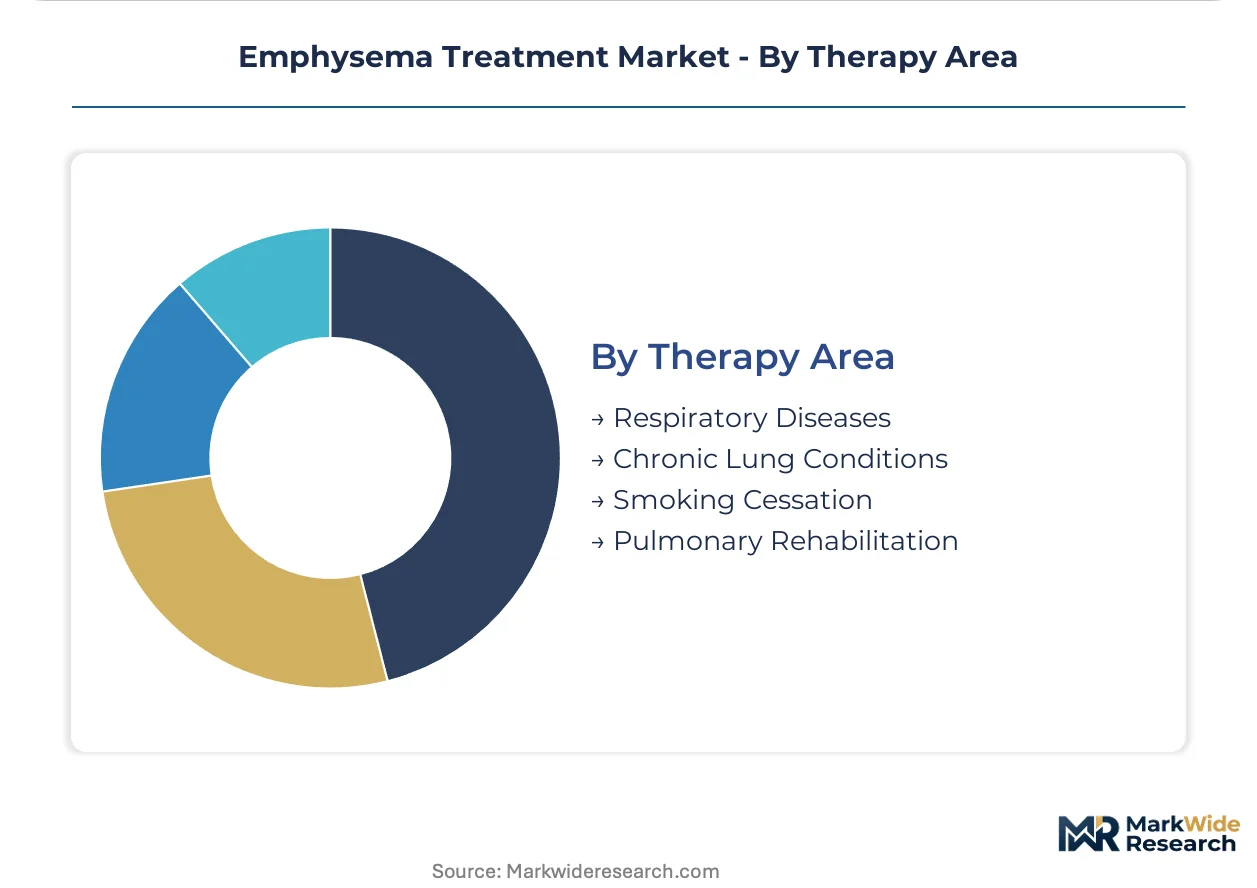
- Respiratory Diseases:Core emphysema and chronic obstructive pulmonary disease management encompassing bronchodilation, anti-inflammatory therapy, and exacerbation prevention. Pulmonology departments in United States hospital systems are expanding their COPD management programs as CMS bundled payment models reward coordinated care.
- Pulmonary Rehabilitation:Exercise training, nutritional intervention, and psychosocial support to preserve functional capacity. Telehealth-integrated platforms are enabling CMS-reimbursable rehabilitation programs without facility-based infrastructure, expanding addressable patient populations in rural geographies.
- Chronic Lung Conditions:Overlapping asthma-COPD overlap syndrome and bronchiectasis requiring differentiated therapeutic approaches.
- Smoking Cessation:Pharmacologic and behavioral interventions targeting the primary preventable cause of emphysema progression.
Respiratory Diseases anchors the volume base while Pulmonary Rehabilitation gains share at the steepest rate as reimbursement coding solidifies for remote delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exporters supply bronchodilator formulations to hospital systems across Central and Eastern Europe, while United States-based durable medical equipment manufacturers ship portable oxygen concentrators to aging populations in Latin America and Southeast Asia.
United States
Medicare Advantage plans in Florida and Texas bundle chronic respiratory care, driving integrated delivery network consolidation. The FDA maintains stringent bioequivalence requirements for generic inhaled therapies that protect branded pricing power. Hospital systems in the Southeast and Southwest are reorganizing procurement under single-source oxygen therapy contracts that include remote monitoring infrastructure.
Germany
Pulmonology clinics in Bavaria and North Rhine-Westphalia pilot Bluetooth-enabled bronchodilators transmitting usage data to electronic health records. The EMA's Medical Device Regulation forces manufacturers to generate device-specific safety data beyond drug bioequivalence. Manufacturing clusters around Frankfurt and Munich concentrate pressurized metered-dose inhaler production serving hospital channels across the European Union.
Japan
Males born between 1945 and 1960 carry elevated emphysema prevalence, aligning METI healthcare spending priorities with respiratory intervention programs. The PMDA accelerates review timelines for combination products addressing severe COPD subsets. Medical device distributors in Osaka and Nagoya are expanding home oxygen delivery fleets to serve aging rural populations in Kyushu and Tohoku.
India
Rural underdiagnosis of COPD creates latent demand for screening programs that would expand the treated patient pool in Maharashtra and Gujarat. The CDSCO streamlines approval pathways for complex generic inhalers to improve domestic access. Pharmaceutical manufacturing in Hyderabad and Ahmedabad supplies metered-dose inhalers to hospital systems across South Asia and Sub-Saharan Africa.
United Kingdom
Integrated care systems in England consolidate respiratory therapy procurement under regional formularies that extract volume commitments from manufacturers. NICE technology appraisals determine reimbursement eligibility for biologic therapies in severe emphysema subsets. Research clusters in Cambridge and Oxford advance digital respiratory medicine platforms integrating smart inhaler data with primary care workflows.
Emphysema Treatment Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established respiratory franchises, creating a tiered structure where scale-driven manufacturers negotiate directly with integrated delivery networks while mid-cap specialists pursue biologic differentiation in severe disease subsets. Two strategic archetypes dominate: bronchodilator portfolio incumbents leveraging chronic daily use patterns, and biologics developers targeting eosinophilic inflammation pathways. Competitive moves concentrate on formulary placement extraction through long-term supply contracts and regulatory segmentation to delay generic substitution.
Among diversified pharmaceutical conglomerates, GlaxoSmithKline plc and AstraZeneca occupy positions exemplifying the bronchodilator-incumbent archetype, while Boehringer Ingelheim International GmbH anchors the European hospital channel specialization. These three represent distinct geographic and regulatory positioning strategies within the consolidated upper tier.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca |
| Boehringer Ingelheim International GmbH |
| Novartis AG |
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Verona Pharma |
| Pfizer Inc. |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Hydrofluoroalkane propellant replacement by dry-powder and soft-mist alternatives is redrawing manufacturing footprints from United States and European Union sites toward India and China facilities, compressing margins on legacy pressurized metered-dose inhalers while creating pricing premiums for reformulated device-drug combinations that satisfy EPA and EMA environmental mandates.
Pricing Analysis
Current-generation smart inhalers with embedded sensors command substantial premiums over prior-generation mechanical devices, while next-generation connected-drug combinations are entering pilot pricing in Germany and Japan. Three-tier pricing structure across premium connected devices, standard dry-powder inhalers, and economy nebulized solutions reflects FDA certification tiers and after-sales service bundling. Cost compression in the standard tier is intensifying because Indian and Chinese manufacturers are securing CDSCO and NMPA approvals for complex generic bronchodilators. Hospital procurement managers at integrated delivery networks demonstrate highest price sensitivity, while home care oxygen therapy patients show lowest sensitivity due to Medicare reimbursement insulation.
Supply Chain Analysis
Strategic stockpiling of hydrofluoroalkane propellants and specialized cannula materials dominates inventory strategy as manufacturers buffer against EPA phase-out deadlines and single-source API dependencies. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with device assembly clustering in Germany, United States, and Japan. Finished inhaler supply draws from hydrofluoroalkane propellants sourced through limited qualified suppliers, specialized plastics for device housings, and lithium-ion cells for portable oxygen concentrators. Single-source vulnerability in propellant supply creates structural exposure to regulatory restriction timelines. Distribution runs through hospital-system integrated delivery networks in the United States, hospital pharmacies in Germany, and durable medical equipment dealers serving home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized workforce certification in inhaler technique training and connected device data analytics represents the critical capability gap constraining market expansion, with qualified respiratory therapists and pharmacists concentrated in United States and Western European urban centers while rural India and Southeast Asia face acute shortages.
For Market Incumbents: Compound formulary lock-in through long-term oxygen therapy bundling contracts that incorporate remote monitoring infrastructure and respiratory therapist home visits, while accelerating backward integration into propellant chemistry to offset EPA-mandated reformulation costs and protect margin structures against Indian generic inhaler entrants securing FDA complex generic pathways. For New Entrants and Emerging Players: CDSCO fast-track certification for dry-powder inhaler devices targeting Maharashtra and Gujarat rural screening programs represents the most penetrable entry vector, with telehealth-integrated pulmonary rehabilitation platforms offering a direct-to-patient go-to-market angle that bypasses hospital procurement consolidation and captures Medicare Advantage bundled payment flows in Florida and Texas. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biologics developers with eosinophilic inflammation targeting capabilities over bronchodilator portfolio incumbents facing generic substitution pressure. Long-term viability across the projection horizon rests on monoclonal antibody pipeline depth and digital respiratory medicine data platform integration. The acquisition target archetype combines late-stage biologic assets with connected inhaler device capabilities. The signal to watch is FDA guidance publication on complex generic inhaler bioequivalence standards that would accelerate or delay substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Complex Generic Inhaler Submission | Accelerates market entry for Indian and Chinese manufacturers seeking United States hospital formulary placement. |
| Telehealth-Integrated Rehabilitation Platform | Enables CMS-reimbursable pulmonary rehabilitation delivery without facility-based infrastructure investment. |
| Propellant Chemistry Backward Integration | Secures supply continuity for pressurized metered-dose inhalers through EPA hydrofluoroalkane transition period. |
| Hospital System Partnership Agreement | Extracts volume commitments from integrated delivery networks for chronic daily use bronchodilator populations. |
| Biologics Pipeline Diversification | Targets severe emphysema subsets with eosinophilic inflammation profiles and differentiated reimbursement coding. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with pulmonology department heads, hospital procurement managers, durable medical equipment supplier executives, and CMS reimbursement specialists; and secondary validation against FDA 510(k) filings, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, and Medicare claims databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-verified segment sizing across the analysis window.
Across the modeling period, the analytical framework projected value and volume through treatment line stratification, delivery mode differentiation, end-user channel migration, and regional regulatory cluster segmentation. CAGRs derived from historical Medicare spending patterns, hospital admission trend analysis, and biologics pipeline advancement rates. Forecast inputs incorporated EPA propellant phase-out timelines, CMS competitive bidding program evolution, and CDSCO regulatory pathway streamlining.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability, EPA regulatory timeline adherence, or biologics clinical trial success rates would require recalibration. Forecasts reflect documented assumptions regarding patient diagnosis expansion, generic substitution velocity, and connected device adoption curves. Revision becomes warranted when FDA complex generic guidance publication or CMS bundled payment model expansion crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Pneumoconiosis Treatment Market