
 Sleep Aid Devices Market | 2026-2036
Sleep Aid Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Aid Devices Market Outlook
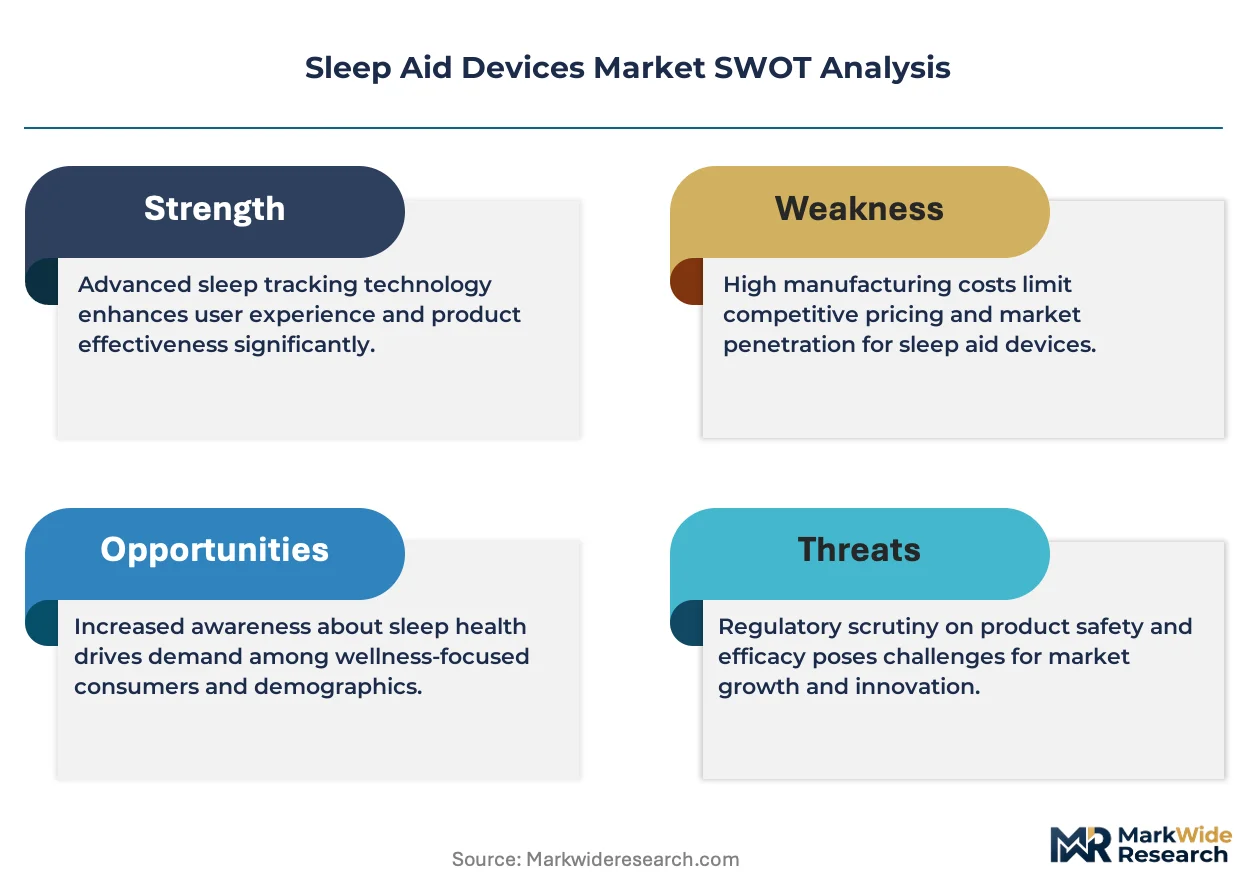
Modular bundling of sleep tracking hardware with subscription-based coaching apps is rebalancing how consumers evaluate total cost of ownership against standalone device purchases. ResMed leverages its clinical channel relationships to sustain recurring revenue from connected CPAP ecosystems. Apple Inc. competes through health platform integration that anchors sleep data within broader biometric dashboards. Oura Health Oy differentiates via ring-form-factor specialization that occupies a premium wearable niche with minimal sleep disruption.
Sleep aid devices encompass instruments designed to monitor, induce, or improve sleep quality through mechanical, electronic, or acoustic mechanisms, typically operating at frequencies below 20 kHz for sound-based interventions and incorporating triaxial accelerometers for motion-based sleep staging. Their primary commercial purpose is to deliver measurable sleep metrics to consumers and clinicians for diagnostic support or behavioral modification. Wearable devices dominate value capture due to sensor miniaturization and continuous data streams, while sound machines represent a mature segment with compressed margins and limited connectivity. Smart sensors within wearable and pillow categories represent the fastest-expanding technology dimension as manufacturers integrate photoplethysmography and temperature sensing for multi-parameter sleep architecture analysis.
The FDA regulates sleep aid software exceeding diagnostic thresholds as Software as a Medical Device under 21 CFR 820 quality system requirements, while the EU MDR and CE marking framework impose clinical evidence standards for apps claiming therapeutic benefit. Japan's PMDA maintains distinct approval pathways for household sleep monitors versus clinical-grade polysomnography equipment, creating segmented market access conditions. Stakeholders must monitor evolving regulatory distinctions between wellness and medical claims across jurisdictions to avoid compliance-driven market exclusion.
Market Dynamics
Reimbursement frameworks for sleep diagnostics are tightening clinical evidence requirements while simultaneously expanding coverage for remote patient monitoring, forcing manufacturers to revalidate software algorithms under medical-grade standards.
Growth Catalysts
- Aging demographics in Japan and Germany:Population cohorts over 65 are driving demand for home-based sleep apnea screening, expanding the addressable household base for connected monitoring devices.
- FDA Software as a Medical Device pathway:Clearance frameworks under 21 CFR 820 are creating definitional clarity for algorithm-based sleep staging, enabling premium pricing for clinically validated wearables.
- Photoplethysmography miniaturization:Optical sensor integration into ring and earbud form factors is enabling continuous blood oxygen and heart rate variability capture without polysomnography lab infrastructure.
Market Restraints
- Semiconductor supply concentration:Triaxial accelerometer and PPG chip fabrication clusters in Taiwan create vulnerability to geopolitical disruption and allocation rationing.
- EU MDR clinical evidence burden:Class IIa medical device designation for sleep therapeutic apps requires prospective studies, extending time-to-market by 18-24 months.
- Sound machine margin compression:Mature acoustic hardware without connectivity features faces substitution from smartphone applications and smart speaker integrations.
Strategic Opportunities
- Employer wellness programs in the United States:Self-insured corporations are adding sleep coaching subscriptions to benefits packages, creating B2B procurement channels distinct from retail.
- Japan PMDA household monitor pathway:Distinct approval track for non-clinical sleep trackers enables faster market entry for wellness-positioned devices before medical-grade escalation.
- AI-driven sleep coaching convergence:Large language model integration with longitudinal biometric data is enabling personalized intervention recommendations previously requiring human sleep specialists.
Industry Challenges
- Algorithm validation talent scarcity:Clinical sleep medicine expertise combined with machine learning engineering remains concentrated in academic medical centers, constraining R&D scaling.
- Legacy CPAP integration complexity:Proprietary data protocols from established respiratory device manufacturers create friction for third-party sleep tracker interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Aid Devices Market |
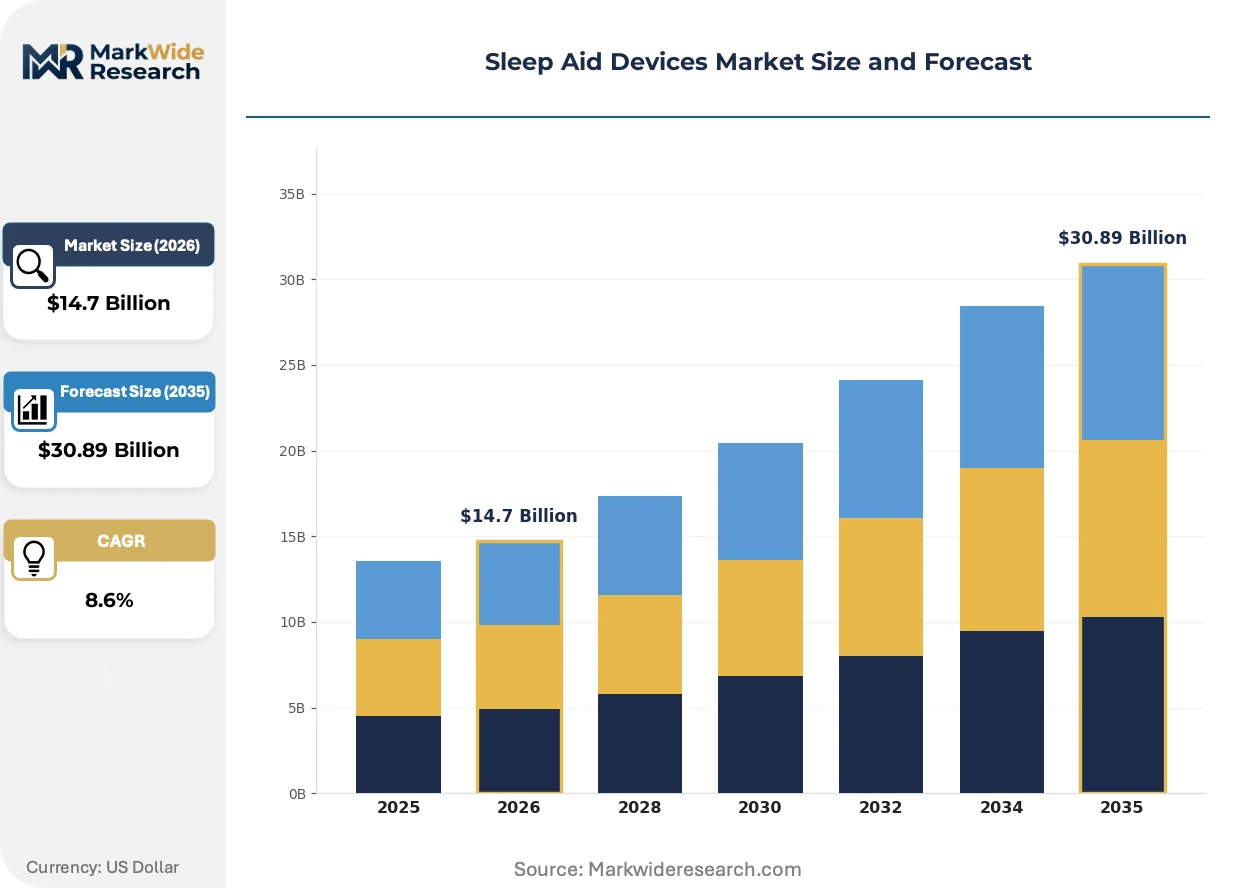
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Pillows, Sleep Masks, Sound Machines Technology: Bluetooth, Smart Sensors, White Noise, Sleep Tracking End User: Adults, Children, Seniors, Sleep Clinics Application: Insomnia Management, Relaxation, Travel, Therapy |
| Companies Covered | Koninklijke Philips N.V., ResMed, Apple Inc., Fitbit (Google LLC), Eight Sleep, Garmin Ltd., Oura Health Oy, Xiaomi, Sleep Number, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Aid Devices Market Strategic Shifts
Multi-parameter sensor fusion is displacing single-modality sleep tracking, while regulatory bifurcation between wellness and medical claims is forcing platform architects to design for dual-path certification from inception.
Photoplethysmography is consolidating market share across wearable categories as manufacturers embed SpO2 and pulse arrival time sensing into rings, watches, and earbuds. Sleep clinics are adopting these sensors for home diagnostic extensions, replacing intermittent oximetry with continuous nocturnal monitoring. The technology is consolidating previously fragmented sleep staging methodologies into unified optical platforms, compressing demand for dedicated actigraphy hardware.
The EU MDR and CE marking framework under 2017/745 is elevating clinical evidence requirements for apps claiming therapeutic benefit beyond pure monitoring. Software manufacturers must now submit prospective validation studies for algorithm-based sleep improvement interventions. Wearable vendors with EU market exposure are responding by establishing notified body relationships earlier in development cycles and bifurcating product lines into wellness and medical tiers.
Subscription bundling is restructuring consumer lifetime value calculations as hardware margins compress and recurring revenue from coaching platforms becomes the dominant profit pool. Direct-to-consumer brands are displacing retail pharmacy distribution for initial device acquisition, though sleep specialist referral remains critical for medical-grade escalation. The United States exhibits the most pronounced channel shift, where employer benefits administration platforms are emerging as volume aggregators distinct from traditional medical device procurement.
Sleep Aid Devices Market Segmentation
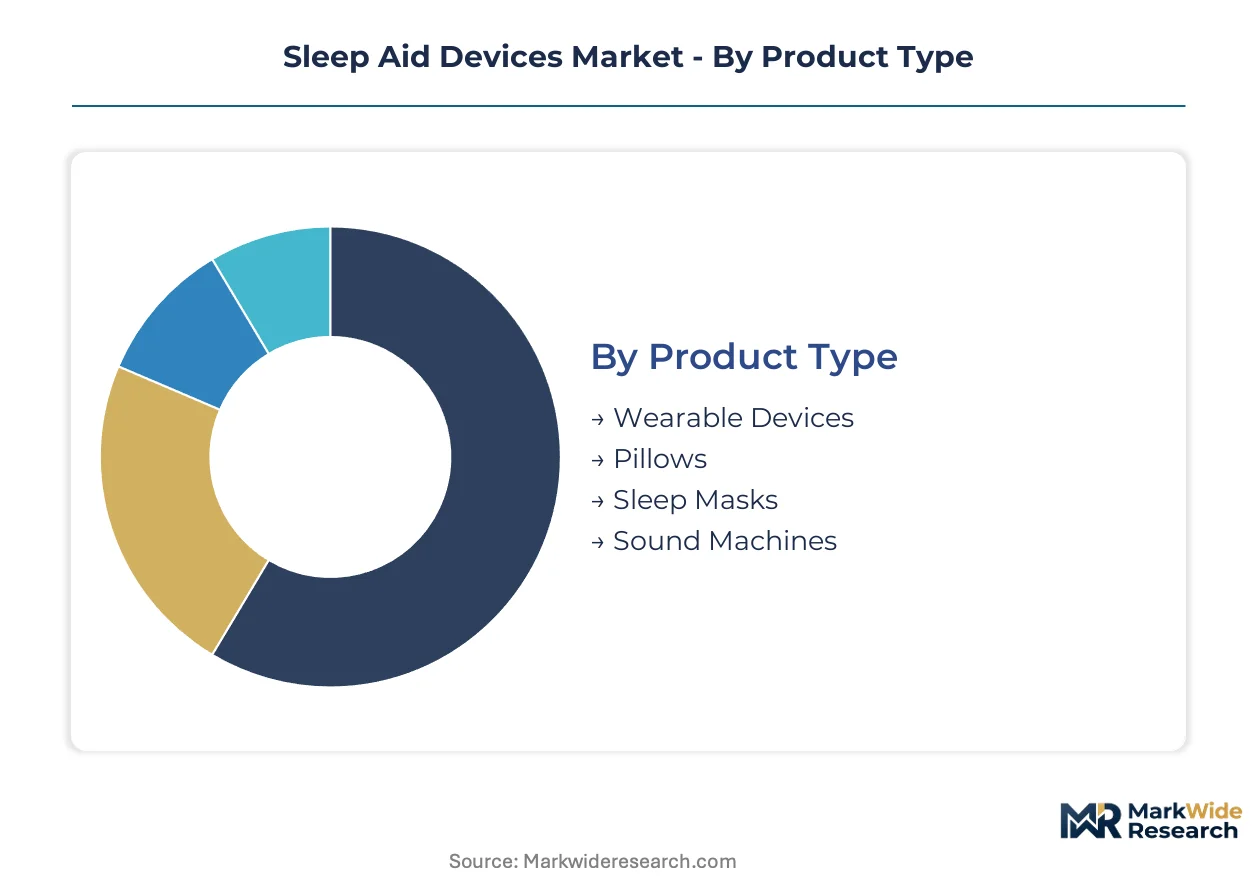
Product form factor and sensor modality determine reimbursement eligibility and distribution channel selection across the sleep aid devices landscape. Manufacturers must align technical specifications with regulatory classification thresholds to access clinical procurement budgets versus consumer retail channels.
Product Type:
Triaxial accelerometer miniaturization and photoplethysmography integration have redefined which physical form factors can deliver medical-grade sleep architecture data.
- Wearable Devices:Ring, wristband, and earbud configurations incorporate continuous SpO2 and heart rate variability monitoring through optical sensors. Sleep clinics in the United States and Germany are deploying these for home diagnostic extensions, replacing intermittent lab-based polysomnography. FDA Software as a Medical Device clearances under 21 CFR 820 enable premium positioning for clinically validated units.
- Pillows:Embedded pressure sensors and temperature arrays capture head movement patterns and micro-arousals without skin contact. Japanese households over-index on this category due to cultural preferences for non-intrusive monitoring during sleep.
- Sleep Masks:Lightweight遮光 designs with integrated EEG electrodes or light therapy LEDs target travel and shift-work applications. Demand concentrates in urban professional demographics seeking jet lag mitigation.
- Sound Machines:Acoustic hardware generating white, pink, or brown noise frequencies below 20 kHz for sleep induction. Margin compression from smartphone app substitution has limited connectivity investment in this mature category.
Wearable Devices leads on scale; Smart Sensors within wearables leads on momentum.
Technology:
Wireless protocol selection and algorithm sophistication separate wellness-positioned devices from reimbursable medical equipment.
- Smart Sensors:Multi-parameter fusion of PPG, accelerometry, and temperature sensing enables sleep stage classification without polysomnography lab infrastructure. EU MDR clinical evidence requirements under 2017/745 are forcing manufacturers to submit prospective validation studies for algorithm-based therapeutic claims.
- Bluetooth:Low-energy connectivity protocols synchronize biometric streams with smartphone applications and electronic health record systems. Data transmission security requirements under HIPAA in the United States and GDPR in Europe constrain firmware architecture decisions.
- White Noise:Acoustic generation through analog circuits or digital signal processing for sleep onset facilitation. Technology differentiation is minimal; competition centers on speaker quality and programmable sound libraries.
- Sleep Tracking:Algorithmic interpretation of motion and physiological signals to generate sleep efficiency scores and architecture summaries. Integration with large language models is enabling personalized coaching recommendations previously requiring human sleep specialist intervention.
Bluetooth leads on installed base; Smart Sensors leads on reimbursement expansion.
End User:
Age-related sleep disorder prevalence and care setting economics determine device specification requirements and pricing tolerance.
- Seniors:Home-based sleep apnea screening demand from cohorts over 65 in Japan and Germany is expanding the addressable household base for connected monitoring with fall detection and emergency alert integration.
- Adults:Employer wellness program enrollment in the United States is creating B2B procurement channels for subscription-bundled sleep coaching platforms distinct from retail pharmacy distribution.
- Sleep Clinics:Clinical-grade polysomnography equipment procurement requires FDA or CE marking under medical device frameworks, with remote patient monitoring reimbursement expansion accelerating adoption of home diagnostic extensions.
- Children:Pediatric sleep tracking faces heightened data privacy scrutiny under COPPA in the United States and equivalent frameworks elsewhere, limiting continuous monitoring deployment in school-age populations.
Seniors leads on volume growth; Sleep Clinics leads on price realization.
Application:
Clinical indication severity determines regulatory pathway selection and channel strategy for sleep intervention positioning.
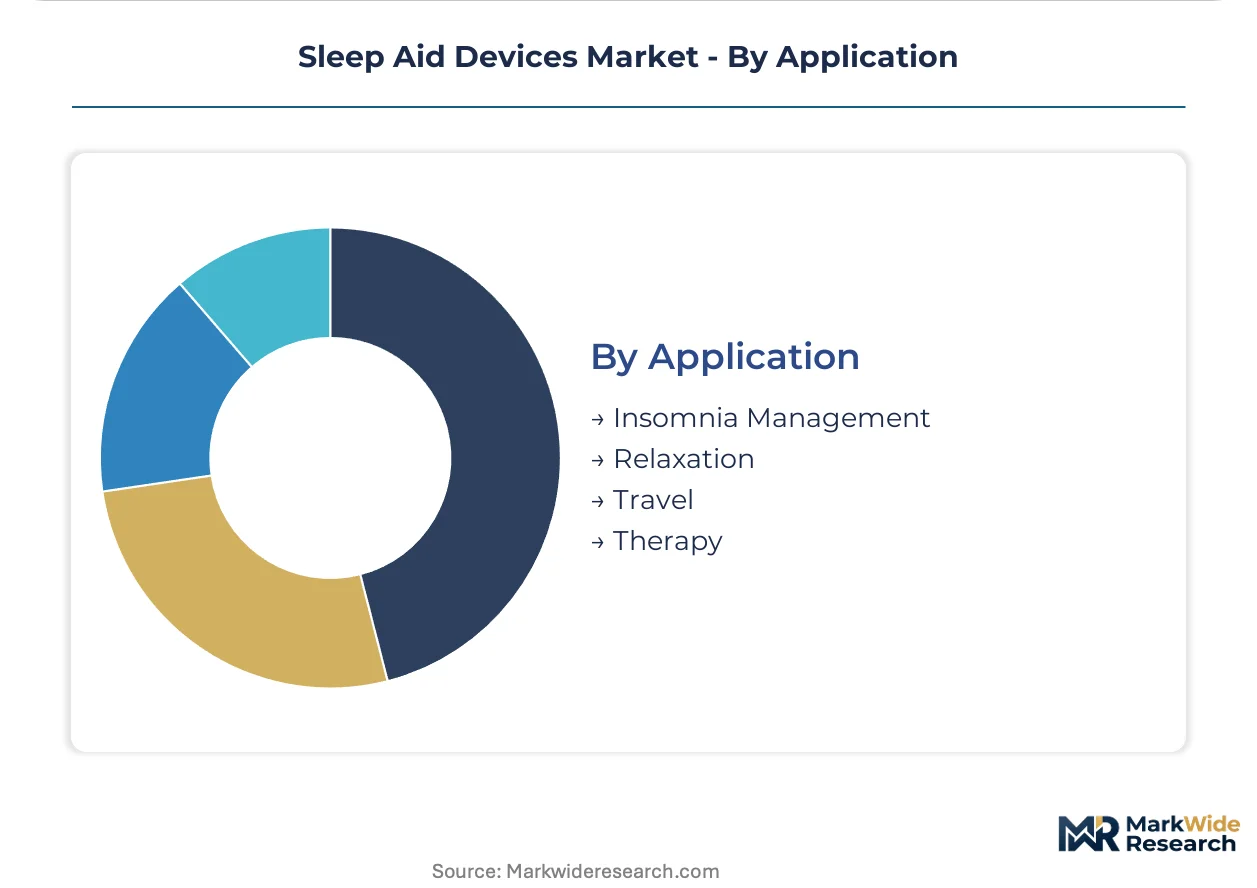
- Insomnia Management:Cognitive behavioral therapy for insomnia (CBT-I) delivery through mobile applications combined with wearable sleep restriction monitoring. FDA breakthrough device designation pathways are accelerating clearance for digital therapeutic platforms.
- Therapy:Continuous positive airway pressure (CPAP) adjuvant monitoring and compliance tracking through connected ecosystems. ResMed and Philips Respironics maintain proprietary data protocols that create integration friction for third-party tracker interoperability.
- Relaxation:Stress reduction through guided breathing and biofeedback applications with lower regulatory barriers than diagnostic or therapeutic claims. Wellness positioning enables faster market entry under Japan PMDA household monitor pathways.
- Travel:Portable form factors targeting jet lag mitigation and unfamiliar sleep environment adaptation. Seasonal demand concentration creates inventory management challenges for direct-to-consumer brands.
Insomnia Management leads on addressable population; Therapy leads on reimbursement attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sleep aid device manufacturing traces its clinical roots to Stanford University's sleep medicine program, where polysomnography standardization in the 1970s established technical protocols later commercialized by Silicon Valley and Minneapolis-based respiratory equipment firms. This academic-industrial lineage concentrated early production expertise in the United States before diffusion to German precision engineering clusters and Japanese consumer electronics hubs.
United States
Employer wellness program procurement and self-insured corporate benefits administration are accelerating B2B channel development for subscription-bundled sleep coaching platforms. FDA Software as a Medical Device clearances under 21 CFR 820 create definitional clarity for algorithm-based sleep staging, enabling premium pricing for clinically validated wearables. The San Francisco Bay Area hosts concentrated digital health venture activity, while Minneapolis anchors legacy respiratory device manufacturing expertise.
Germany
Aging demographics among cohorts over 65 are expanding home-based sleep apnea screening demand and connected monitoring device adoption. EU MDR clinical evidence requirements under 2017/745 impose prospective study obligations for therapeutic sleep applications, extending time-to-market by 18-24 months. Baden-Württemberg's medical technology corridor concentrates wearable sensor development and notified body relationships for CE marking compliance.
Japan
Cultural preferences for non-intrusive monitoring during sleep drive household adoption of pillow-embedded pressure sensors and temperature arrays. PMDA maintains distinct approval pathways for household sleep monitors versus clinical-grade polysomnography equipment, enabling faster market entry for wellness-positioned devices. Tokyo-Osaka industrial corridors host consumer electronics manufacturers integrating photoplethysmography into ring and earbud form factors.
China
Domestic manufacturing scale for triaxial accelerometers and photoplethysmography chips supports cost-competitive wearable production for export markets. NMPA regulatory frameworks are evolving to distinguish wellness claims from medical device classifications for sleep-tracking software. Shenzhen's electronics manufacturing ecosystem concentrates optical sensor assembly and Bluetooth connectivity module production.
United Kingdom
NHS remote patient monitoring reimbursement expansion is accelerating procurement of home diagnostic extensions for sleep clinic referrals. GDPR data transmission security requirements constrain firmware architecture decisions for biometric stream synchronization with smartphone applications. London's digital health venture cluster anchors software development for cognitive behavioral therapy integration with wearable sleep restriction monitoring.
Sleep Aid Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory certification intensity, with FDA-cleared medical devices commanding pricing multiples over wellness-positioned consumer electronics. The vendor base stratifies into three tiers: clinical-grade respiratory equipment manufacturers with proprietary data ecosystems, consumer technology platforms integrating sleep data within broader biometric dashboards, and specialized wearable form-factor innovators occupying premium niches. Dominant competitive moves include strategic partnerships with employer benefits administration platforms and portfolio diversification into subscription-based coaching software.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and ResMed occupy positions exemplifying clinical-channel-dependent revenue models, while Apple Inc. represents the platform-integration archetype anchoring sleep metrics within ecosystem-wide health dashboards. Oura Health Oy sits within the specialization tier, its ring-form-factor design occupying a premium wearable niche with minimal sleep disruption characteristics.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| ResMed |
| Apple Inc. |
| Fitbit (Google LLC) |
| Eight Sleep |
| Garmin Ltd. |
| Oura Health Oy |
| Xiaomi |
| Sleep Number |
| Others |
Value Chain & Pricing Dynamics
Photoplethysmography chip spot prices in Taiwan's semiconductor foundries cascade through three distinct pricing tiers as optical sensor miniaturization separates FDA-cleared medical wearables from wellness-positioned consumer electronics.
Pricing Analysis
Subscription-hardware hybrid models now dominate revenue architecture across the sleep aid devices landscape. Certification grade under FDA 21 CFR 820 and EU MDR CE marking tiers creates the primary price differentiation driver, with clinically validated units commanding multiples over wellness-positioned alternatives. Cost compression in the sound machine category intensifies because smartphone app substitution eliminates connectivity investment returns. Employer wellness programs in the United States exhibit the lowest price sensitivity, while direct-to-consumer retail channels face acute margin pressure from promotional discounting.
Supply Chain Analysis
Dual-sourcing requirements for triaxial accelerometer and PPG chip procurement mandate multi-supplier qualification across Taiwan, South Korea, and China manufacturing clusters. Raw material dependencies center on silicon wafers, optical sensor substrates, and lithium-polymer battery cells. Single-source vulnerability concentrates in Taiwan's foundry capacity for advanced node sensor fabrication. Distribution runs through direct-to-consumer e-commerce platforms, employer benefits administration systems, and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleep aid devices market functions as a regulatory compounder where FDA Software as a Medical Device pathway clarity and EU MDR clinical evidence requirements are accelerating demand for certified platforms over unvalidated wellness alternatives.
For Market Incumbents: Deploy backward integration into optical sensor design to secure supply continuity against Taiwan foundry allocation rationing. Fortify proprietary data protocol moats around CPAP ecosystems to block third-party tracker interoperability threats. Escalate CE marking investment ahead of EU MDR 2017/745 enforcement deadlines to maintain premium positioning. For New Entrants and Emerging Players: Employer benefits administration platforms represent the most penetrable channel for subscription-bundled sleep coaching platforms. Target Japan's PMDA household monitor pathway for faster market entry before medical-grade escalation. Pursue white-space in pediatric sleep tracking under COPPA-compliant data architectures. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wearable form-factor innovators possessing ring or earbud miniaturization expertise and existing FDA 510(k) clearances. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Watch for AI-driven sleep coaching convergence with large language models as the inflection signal. Deviation in FDA enforcement posture toward wellness-claiming apps would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Enables premium pricing through 21 CFR 820 quality system validation. |
| CE Marking Pathway under EU MDR | Unlocks clinical procurement budgets across German and UK hospital systems. |
| Hospital System Partnership | Secures sleep clinic referral channels for home diagnostic extensions. |
| Software Companion Development | Creates recurring revenue from CBT-I coaching platform subscriptions. |
| Reimbursement Strategy | Aligns with CMS remote patient monitoring expansion for connected monitoring. |
Study Parameters
Direct dialogue with sleep clinic medical directors, biomedical engineers at hospital purchasing committees, GPO contracts managers, and digital health CTOs grounded the qualitative foundation, cross-validated against FDA 510(k) filings, EU MDR notified body submissions, CMS reimbursement databases, and SEC 10-K disclosures from publicly traded device manufacturers. Bottom-up unit economics triangulated with top-down epidemiological prevalence modeling.
Segment-level value outputs across the analysis window reflect product form factor, sensor modality, regulatory classification tier, and end-user channel selection. CAGRs derive from installed base penetration curves, replacement cycle assumptions, and subscription attach rate trajectories. Forecast inputs incorporate photoplethysmography miniaturization roadmaps and evolving reimbursement framework coverage decisions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement discretion toward wellness-claiming algorithms and Taiwan semiconductor supply continuity. Deviation in EU MDR notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Parasomnia Treatment Market