
 Europe Insomnia Market | 2026-2036
Europe Insomnia Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insomnia Market Insights
The EU Medical Device Regulation is shifting the cost-of-entry calculus for digital sleep therapeutics and connected diagnostic platforms seeking CE marking. Idorsia Pharmaceuticals leverages its European regulatory heritage to anchor clinical trial networks across Switzerland and EU member states. Takeda Pharmaceutical sustains manufacturing scale for orexin antagonist formulations through its Vienna-based operations. Neurim Pharmaceuticals competes on melatonin receptor agonist specialization, particularly within pediatric and geriatric labeling.
Insomnia constitutes a chronic sleep-wake disorder characterized by persistent difficulty initiating or maintaining sleep despite adequate opportunity, with diagnostic criteria requiring symptom duration exceeding three months and measurable daytime impairment. The condition demands interventions that modulate GABAergic, orexinergic, or melatoninergic pathways to restore circadian architecture and sleep continuity. Prescription medications currently dominate value generation, though cognitive behavioral therapy captures disproportionate policy attention as health technology assessments in France and the Netherlands expand reimbursement for structured non-pharmacological programs. Oral administration routes maintain volume leadership, yet transdermal and sublingual formats attract formulation investment where rapid onset or bypassing first-pass metabolism offers clinical differentiation.
EMA centralized marketing authorization procedures, national health technology assessment bodies in Germany and France, and the EU AI Act collectively shape product development timelines, evidence requirements, and market access pathways for insomnia interventions. EMA pharmacovigilance obligations now extend to real-world data collection for hypnotic safety profiles, while the EU AI Act imposes conformity burdens on algorithmic sleep diagnostics. Stakeholders must monitor how HTA convergence across France, Germany, and England redefines evidence thresholds for novel mechanisms entering European reimbursement negotiations.
Market Dynamics
EMA pharmacovigilance obligations now mandate real-world data collection for hypnotic safety profiles, compressing development timelines and elevating evidence requirements for market authorization across EU member states.
Growth Catalysts
- Germany's reimbursement clarity:The Federal Joint Committee (G-BA) has expanded coverage for structured cognitive behavioral therapy programs, pulling demand toward non-pharmacological interventions.
- EU Medical Device Regulation:CE marking pathways for digital therapeutics are formalizing, enabling algorithmic sleep diagnostics to enter commercial distribution.
- Aging demographics:Population cohorts over 65 exhibit elevated insomnia prevalence, concentrating prescription volume and clinical service demand across Northern European health systems.
Market Restraints
- Active pharmaceutical ingredient concentration:Orexin antagonist synthesis depends on specialized contract manufacturers concentrated in Switzerland and the Netherlands, creating supply vulnerability.
- EU AI Act conformity burdens:Algorithmic sleep diagnostics face mandatory third-party assessment, extending time-to-market for connected diagnostic platforms.
- Generic hypnotic substitution:Zolpidem and zopiclone formulations face pricing compression from mature generic portfolios, eroding branded prescription value.
Strategic Opportunities
- France's HTA expansion:The National Authority for Health (HAS) is broadening reimbursement for digital therapeutics, creating access pathways for connected cognitive behavioral therapy platforms.
- Pediatric labeling:Melatonin receptor agonist specialization for adolescent insomnia remains underdeveloped, offering formulation differentiation.
- Transdermal delivery convergence:Microneedle patch technology combined with chronopharmacology enables circadian-timed drug release, bypassing first-pass metabolism.
Industry Challenges
- Real-world evidence generation:EMA pharmacovigilance obligations require post-market surveillance infrastructure that mid-cap developers lack, forcing partnership with contract research organizations.
- Legacy system integration:Sleep clinic adoption of algorithmic diagnostics requires interoperability with existing electronic health record architectures, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insomnia Market |
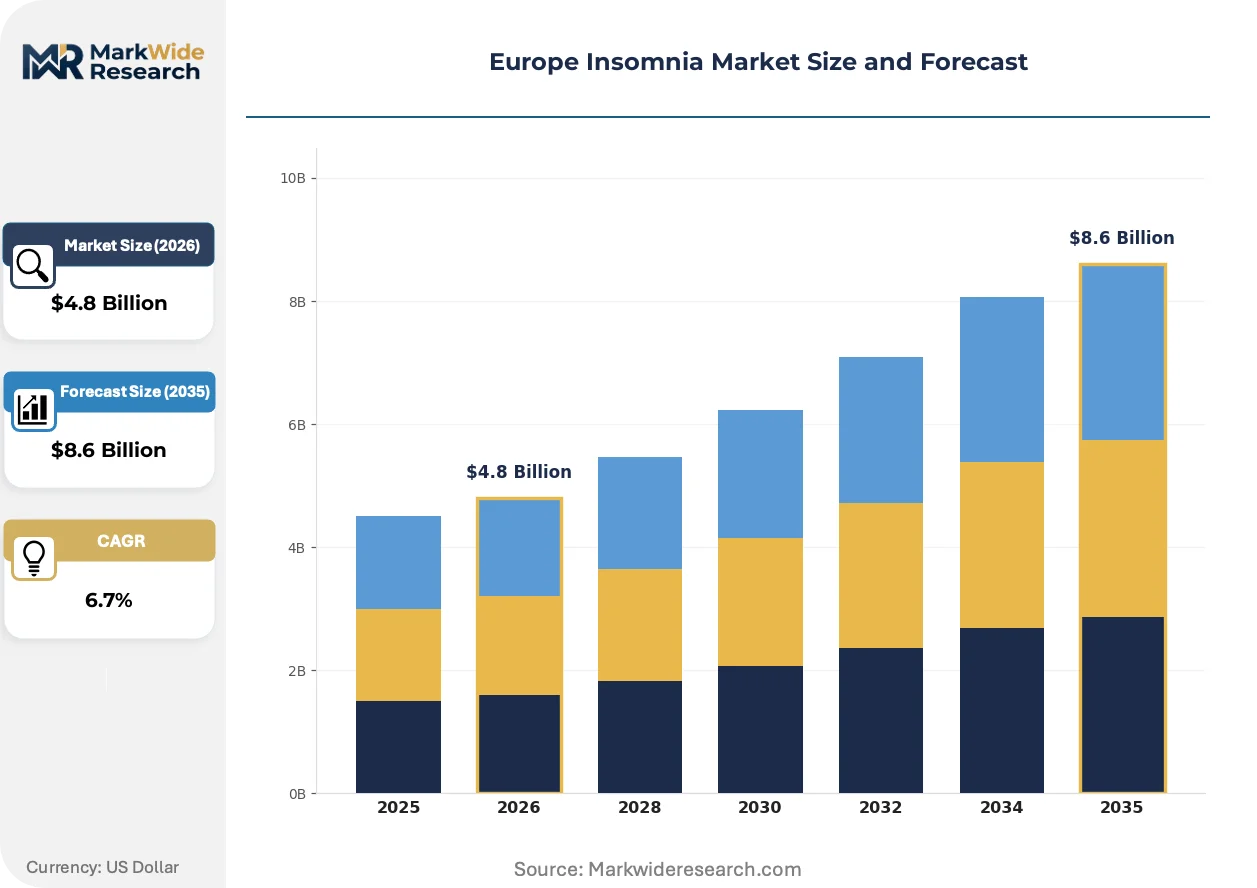
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Prescription Medications, Over-the-Counter Drugs, Cognitive Behavioral Therapy, Herbal Remedies Patient Demographics: Adults, Elderly, Adolescents, Children Administration Route: Oral, Injectable, Sublingual, Transdermal Formulation: Tablets, Capsules, Liquid Form, Sprays |
| Companies Covered | Takeda Pharmaceutical, Eisai, Sanofi, Neurim Pharmaceuticals, Idorsia Pharmaceuticals, Pfizer, Teva Pharmaceutical Industries, Astellas Pharma, Merck & Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insomnia Market Trends and Innovations
Digital sleep therapeutics are migrating from wellness applications toward regulated medical device status, while formulation science pursues chronopharmacological precision to match drug release with circadian phase.
Dual orexin receptor antagonists are electrifying insomnia pharmacotherapy by targeting wake-promoting pathways rather than sedative mechanisms. Sleep clinics in Germany and the Netherlands are adopting these agents for patients with residual daytime impairment from GABAergic hypnotics. The technology is electrifying competitive positioning by enabling next-day functional performance claims that differentiate from legacy benzodiazepine-receptor agonists.
EMA centralized marketing authorization procedures now incorporate health technology assessment convergence requirements, forcing sponsors to design pan-European evidence generation strategies from Phase II onward. This regulatory architecture compresses the window for national pricing negotiations and elevates the importance of Germany's early benefit assessment as a benchmark for subsequent markets. France, England, and the Netherlands are synchronizing their evidence expectations, reducing regulatory arbitrage opportunities.
Procurement patterns in hospital sleep centers are rotating toward bundled payment models that combine diagnostic polysomnography with therapeutic intervention. This displacement of fee-for-service reimbursement is compressing vendor margins while rewarding platforms that integrate hardware, software, and clinical workflow. The Netherlands and Belgium exhibit the most advanced adoption of these outcome-oriented contracts, with hospital groups consolidating vendor relationships to three preferred suppliers per region.
Europe Insomnia Market Segmentation
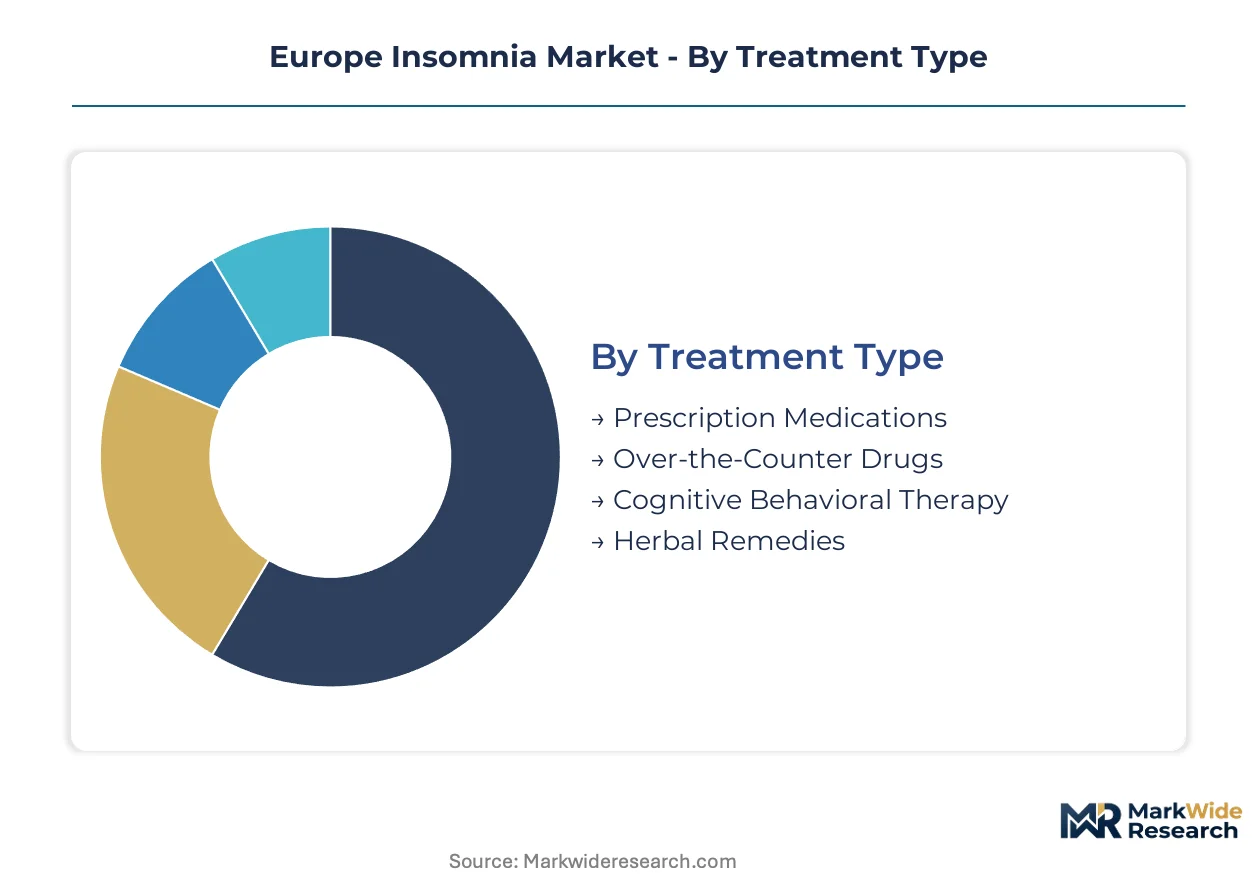
Insomnia interventions in Europe fragment across regulatory pathways that determine reimbursement access and commercial viability. EMA marketing authorization, CE marking under MDR, and national HTA evaluations create divergent cost-of-entry profiles across treatment modalities.
Treatment Type:
EMA centralized procedures and national reimbursement catalogs impose distinct evidence burdens on pharmacological versus non-pharmacological segments.
- Prescription Medications:Dual orexin receptor antagonists and melatonin receptor agonists require centralized EMA authorization with post-market pharmacovigilance obligations. Germany's G-BA early benefit assessment sets pricing benchmarks across EU member states, concentrating commercial investment in agents demonstrating next-day functional performance.
- Cognitive Behavioral Therapy:Structured programs face heterogeneous reimbursement status, with France's HAS and Netherlands' Zorginstituut expanding coverage for digital delivery platforms. Germany's statutory health insurance now reimburses therapist-guided and app-based protocols, pulling volume toward non-pharmacological channels.
- Over-the-Counter Drugs:Antihistamine formulations and low-dose melatonin navigate national pharmacy regulations without prescription requirements.
- Herbal Remedies:Valerian root and passionflower extracts fall under food supplement directives in most EU jurisdictions, bypassing pharmaceutical authorization.
Prescription medications sit at the top of the volume ranking, with cognitive behavioral therapy climbing the fastest.
Patient Demographics:
Age-stratified prevalence patterns concentrate clinical trial design and commercial targeting within specific European health systems.
- Elderly:Population cohorts over 65 exhibit elevated chronic insomnia prevalence across Northern European systems. Polypharmacy interactions and fall risk drive demand for non-GABAergic mechanisms in Germany and the Netherlands.
- Adults:Working-age patients with sleep maintenance difficulties represent the core prescription volume for orexin antagonists in sleep clinics.
- Adolescents:Delayed sleep phase syndrome and academic performance concerns create pediatric labeling opportunities for melatonin agonists, with Neurim Pharmaceuticals specializing this segment.
- Children:Neurodevelopmental comorbidities concentrate demand within hospital sleep centers in France and England.
Elderly patients command the largest addressable population, with adolescents presenting the steepest expansion trajectory for specialized formulations.
Administration Route:
Formulation technology investments align with pharmacokinetic requirements and patient adherence patterns across European markets.
- Oral:Immediate-release and modified-release tablets dominate prescription volume through established manufacturing infrastructure. Vienna-based Takeda operations and Swiss contract manufacturers sustain GABAergic and orexin antagonist supply.
- Transdermal:Microneedle patches enabling circadian-timed release attract formulation investment where bypassing first-pass metabolism offers clinical differentiation.
- Sublingual:Rapid-onset zolpidem formulations address sleep initiation difficulties in hospital discharge settings.
- Injectable:Parenteral routes remain confined to perioperative and intensive care applications with limited insomnia-specific development.
Oral administration maintains volume leadership, with transdermal formats gaining share fastest through chronopharmacology convergence.
Formulation:
Manufacturing scale and patent expiration timelines shape competitive positioning across dosage form categories.
- Tablets:Compression technology and coating capabilities support high-volume production of modified-release hypnotics. Generic zolpidem and zopiclone substitution erodes branded value in this mature segment.
- Liquid Form:Pediatric and geriatric compliance applications drive demand for oral solutions with precise dosing flexibility.
- Capsules:Hard gelatin and HPMC shells enable taste masking and modified-release profiles for botanical extracts.
- Sprays:Sublingual and intranasal delivery systems target rapid onset requirements in acute insomnia presentations.
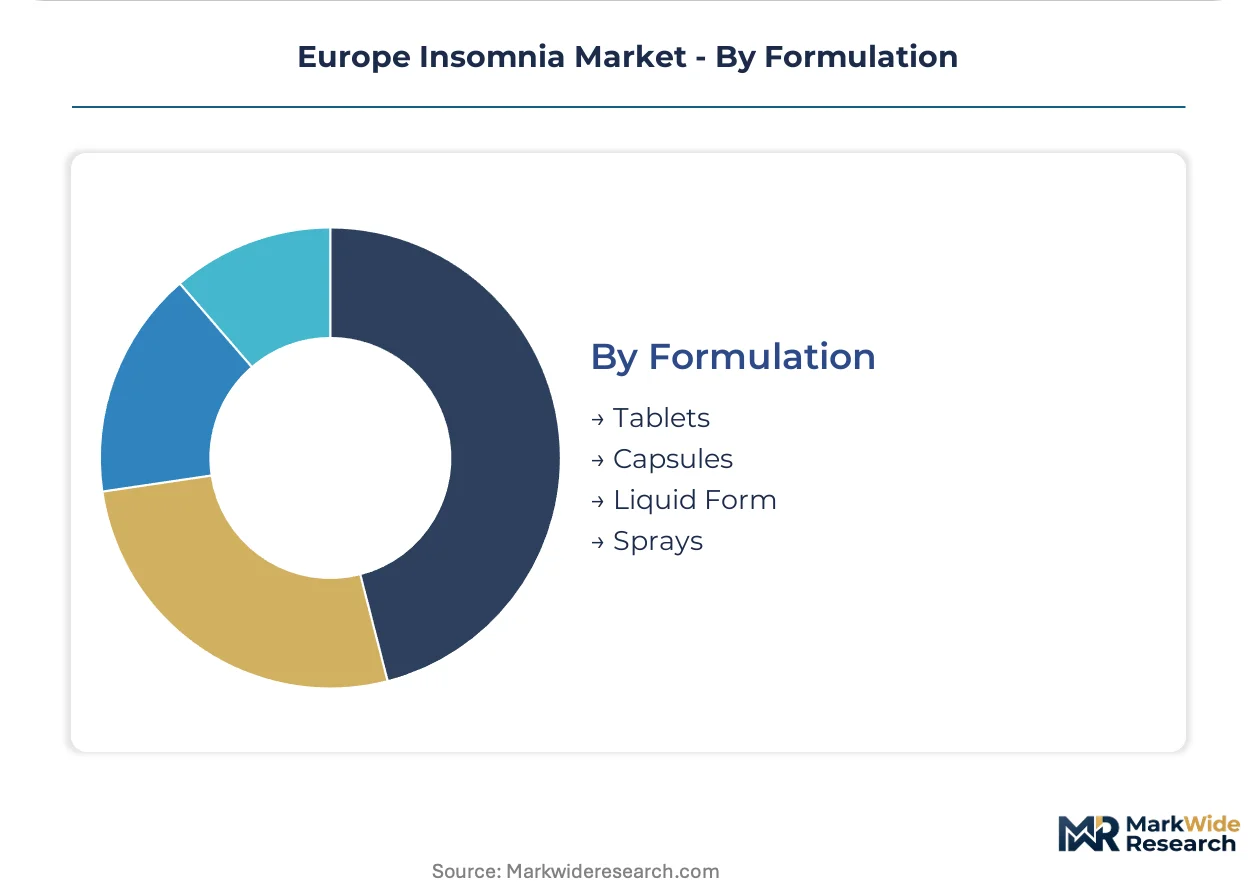
Tablets sit at the top of the volume ranking, with liquid formulations climbing the fastest through pediatric and geriatric labeling expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sleep medicine researchers and clinical trial coordinators cluster in Basel, Vienna, and Amsterdam, anchoring Europe's insomnia therapeutic development corridor. This talent concentration shapes regulatory strategy and commercial deployment across national health systems.
Germany
Aging demographics and statutory health insurance reimbursement for cognitive behavioral therapy pull demand toward non-pharmacological interventions. The Federal Joint Committee (G-BA) early benefit assessment sets pricing benchmarks that reverberate through EU member state negotiations. Berlin and Munich host the continent's densest concentration of sleep clinics adopting bundled payment models.
France
The National Authority for Health (HAS) is broadening reimbursement pathways for digital therapeutics, creating access channels for connected cognitive behavioral therapy platforms. EMA centralized marketing authorization procedures intersect with national HTA evaluations here, compressing evidence generation timelines. Paris and Lyon anchor clinical trial networks for orexin antagonist development.
United Kingdom
England's National Institute for Health and Care Excellence (NICE) synchronizes evidence expectations with continental HTA bodies, reducing regulatory arbitrage opportunities. Sleep maintenance insomnia drives prescription volume for modified-release formulations in working-age populations. London and Cambridge concentrate health technology assessment expertise and digital health venture formation.
Netherlands
Zorginstituut Nederland has expanded coverage for app-based and therapist-guided cognitive behavioral protocols, accelerating digital therapeutic adoption. Hospital groups in Amsterdam and Rotterdam are consolidating vendor relationships to three preferred suppliers per region under outcome-oriented contracts. Algorithmic sleep diagnostics face EU AI Act conformity assessment through Dutch notified bodies.
Switzerland
Swissmedic regulatory heritage anchors clinical trial infrastructure for novel hypnotic mechanisms, particularly dual orexin receptor antagonists. Contract manufacturers in Basel and Zurich concentrate specialized active pharmaceutical ingredient synthesis for orexinergic pathways. Geneva hosts pharmacovigilance coordination for real-world safety data collection mandated by EMA obligations.
Europe Insomnia Market Competitive Landscape
The competitive structure tilts toward mid-cap specialists with European regulatory heritage rather than consolidated pharmaceutical majors. Tiered positioning separates developers with centralized EMA authorization capabilities from those navigating national pharmacy regulations for over-the-counter segments. Two strategic archetypes dominate: dual orexin receptor antagonist innovators and melatonin receptor agonist pediatric specialists. Competitive moves center on health technology assessment convergence strategies and real-world evidence generation partnerships with contract research organizations.
Among Swiss-based developers, Idorsia Pharmaceuticals occupies a position exemplifying the orexin antagonist innovation archetype, while Neurim Pharmaceuticals represents the pediatric melatonin specialization vector. Takeda Pharmaceutical, with Vienna-based manufacturing operations, anchors the scale-driven end of prescription hypnotic supply. These three entities collectively illustrate how geographic regulatory heritage shapes competitive positioning across EMA centralized procedures and national reimbursement negotiations.
| Leading Market Players |
|---|
| Takeda Pharmaceutical |
| Eisai |
| Sanofi |
| Neurim Pharmaceuticals |
| Idorsia Pharmaceuticals |
| Pfizer |
| Teva Pharmaceutical Industries |
| Astellas Pharma |
| Merck & Co. |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient spot prices for orexinergic compounds cascade through European contract manufacturing networks, compressing margins at formulation stage while amplifying pricing power for Swiss and Dutch synthesis specialists serving dual orexin receptor antagonist developers.
Pricing Analysis
Bundled payment models for sleep clinic services separate diagnostic polysomnography from therapeutic intervention, creating three-tier pricing structure across premium orexin antagonists, standard GABAergic hypnotics, and economy generic zolpidem portfolios. Price differentiation hinges on next-day functional performance claims and CE marking status for connected diagnostics. Cost compression in the generic hypnotic tier intensifies because of mature substitution patterns, while hospital procurement committees in the Netherlands and Belgium exhibit lowest price sensitivity for integrated digital-therapeutic platforms.
Supply Chain Analysis
EU Medical Device Regulation local-content requirements for CE marking are reshaping sourcing decisions, pushing developers toward notified bodies in Germany, the Netherlands, and Switzerland for conformity assessment. Orexin antagonist active pharmaceutical ingredient synthesis concentrates in Basel and Zurich, while melatonin receptor agonist formulation feeds from Vienna-based operations. Single-source vulnerability characterizes specialized contract manufacturers for orexinergic pathways. Distribution runs through hospital sleep centers consolidating to three preferred suppliers per region under outcome-oriented contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Insomnia Market operates as a regulatory compounder where EMA pharmacovigilance obligations for real-world data collection now mandate post-market surveillance infrastructure, pulling capital toward developers with existing CRO partnerships and compressing timelines for mid-cap entrants lacking these capabilities.
For Market Incumbents: Hedge against generic substitution pressure by deepening backward integration into specialized orexinergic API synthesis in Switzerland, while securing preferred supplier status with Dutch hospital groups rotating toward bundled payment models. Channel control through sleep clinic EHR interoperability investments offers defensive positioning against algorithmic diagnostic entrants.
For New Entrants and Emerging Players: The price-point gap between premium orexin antagonists and economy generic hypnotics opens white-space targeting for transdermal melatonin formulations in pediatric labeling, with France's HAS reimbursement expansion offering the most penetrable geography. App-based cognitive behavioral therapy protocols in Germany's statutory health insurance system present a second entry vector through digital therapeutic CE marking pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing European regulatory heritage and centralized EMA authorization track records, particularly those with pediatric melatonin agonist pipelines or dual orexin receptor antagonist development networks. Watch for HTA convergence announcements across France, Germany, and England as inflection indicators for evidence threshold elevation and pricing benchmark synchronization.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Authorization Pathway | Early benefit assessment in Germany sets pricing benchmarks reverberating through EU member state negotiations. |
| Real-World Evidence Partnership | CRO alliances satisfy EMA pharmacovigilance obligations for post-market hypnotic safety surveillance. |
| CE Marking for Digital Therapeutics | Algorithmic sleep diagnostics gain commercial distribution under formalized EU Medical Device Regulation pathways. |
| Pediatric Labeling Expansion | Melatonin receptor agonist specialization addresses underdeveloped adolescent insomnia segments with formulation differentiation. |
| Transdermal Delivery Investment | Microneedle patch technology enables circadian-timed drug release bypassing first-pass metabolism constraints. |
Research Methodology
Multiple input streams — regulatory filing databases, health technology assessment documentation, and pharmaceutical procurement records — were reconciled against primary interviews with drug development executives, formulary directors at German statutory health insurers, sleep clinic medical directors in the Netherlands, and EMA regulatory affairs specialists. Secondary validation drew from EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, HAS and G-BA reimbursement determinations, and EU MDR notified body registers. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Historical prescription trends were cross-referenced against panel input from payer access specialists and hospital procurement managers to construct the analytical framework across the projection horizon. Segmentation dimensions modeled encompass treatment modality, administration route, patient demographic cohort, and national regulatory cluster. CAGRs were derived from volume trajectory analysis incorporating aging demographic projections, reimbursement policy shifts, and formulation technology adoption curves.
The model assumes a particular technology adoption path for dual orexin receptor antagonists; alternative pathways for GABAergic hypnotic persistence would alter the outlook. Forecasts reflect assumptions regarding HTA convergence timing and digital therapeutic reimbursement expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Insomnia Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Asia Pacific Insomnia Market