
 Global Wearable Sleep Trackers Market | 2026-2036
Global Wearable Sleep Trackers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Sleep Trackers Market Foresight
Subscription-based sleep coaching and software-defined analytics layers is broadening what wearable sleep tracker vendors monetize beyond hardware. Apple Inc. leverages its health ecosystem integration to sustain recurring engagement through sleep trend dashboards. Oura Health Oy anchors its revenue model on membership tiers that unlock advanced readiness metrics and personalized guidance. Garmin Ltd competes through specialized aviation and military-grade sleep recovery tools that extend its core athlete positioning.
Wearable sleep trackers are wrist-worn, finger-worn, or head-mounted sensor systems that capture photoplethysmography signals, accelerometer-derived movement patterns, and peripheral temperature fluctuations to estimate sleep architecture and recovery status. These devices serve commercial purposes spanning consumer wellness optimization, remote patient monitoring for sleep disorders, and athletic load management. Smartwatch and ring form factors dominate unit economics due to all-day wearability that generates continuous longitudinal datasets, while electroencephalography-enabled headbands command premium positioning in clinical study and research institution deployments where hypnogram accuracy determines protocol validity. Home monitoring and corporate wellness programs represent the expanding usage scenario frontier as employers seek quantified return on wellness investments.
The FDA in the United States scrutinizes sleep apnea detection algorithms under software-as-medical-device pathways, compelling vendors to validate clinical claims or recategorize consumer-facing features. The EU AI Act and MDR in Europe impose conformity requirements on algorithmic health scoring that affects market access timelines for AI-enhanced sleep stage classification. Stakeholders must monitor how regulatory divergence between FDA predicate device routes and EU notified body expectations fragments development roadmaps and certification budgets.
Market Dynamics
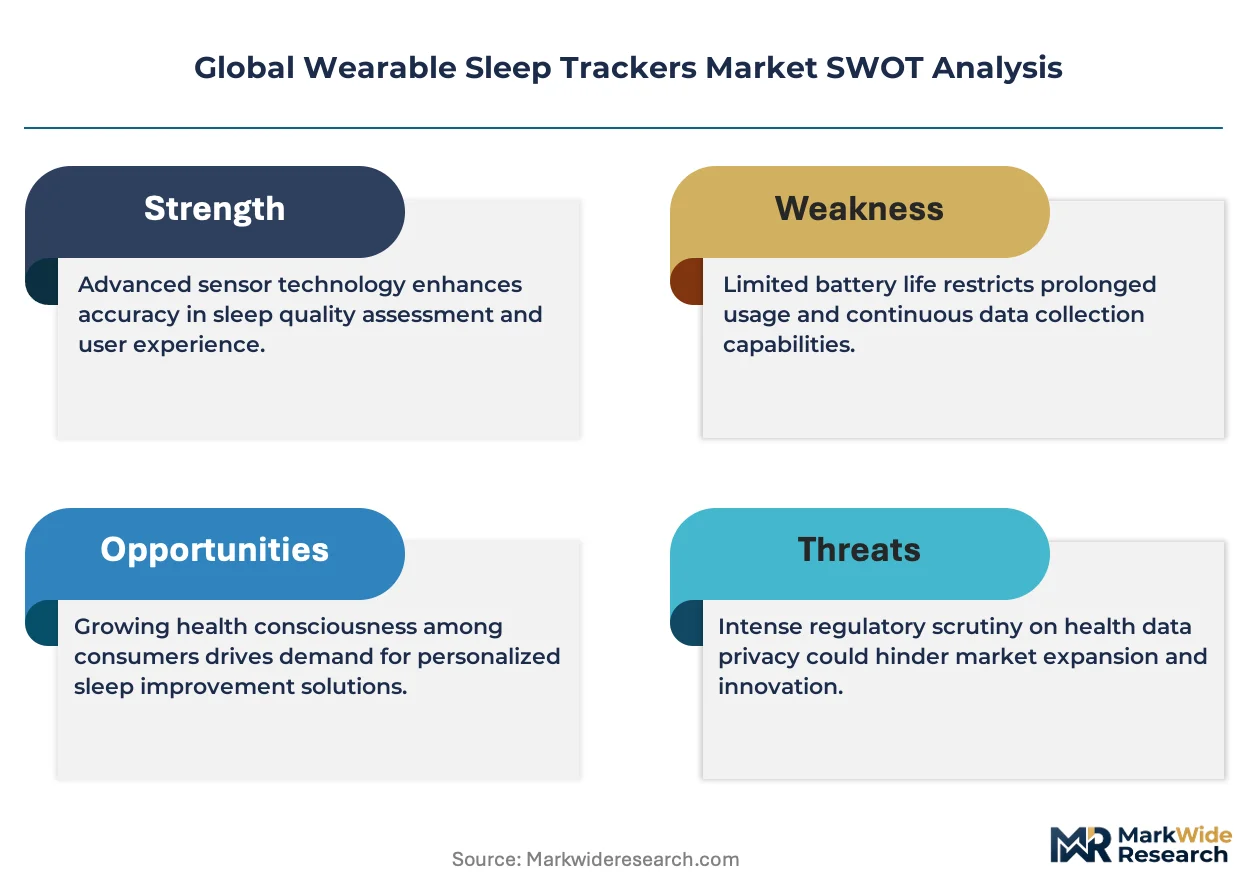
Software-as-medical-device reclassification pressure from the FDA is forcing hardware vendors to rebuild compliance architectures around algorithm validation, splitting development roadmaps between consumer wellness and clinical-grade product lines.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States now quantify sleep metrics as part of occupational health programs, generating institutional procurement contracts that bypass consumer retail channels.
- EU AI Act conformity pathways:Algorithmic health scoring frameworks in Europe create first-mover advantages for vendors that pre-certify machine learning sleep stage classification models.
- Photoplethysmography miniaturization:Advances in optical sensor integration enable ring and earbud form factors that capture continuous cardiovascular data without wrist-worn bulk.
Market Restraints
- Clinical validation costs:Polysomnography correlation studies required for FDA 510(k) clearance of sleep apnea detection features consume 18-24 month development cycles.
- Component concentration in Shenzhen:Discrete optical sensors and low-power microcontrollers flow through a narrow corridor of Guangdong Province contract manufacturers.
- Substitute service models:Telehealth platforms offering physician-interpreted home sleep tests compete directly on diagnostic accuracy claims.
Strategic Opportunities
- India's PLI scheme for wearables:Production-linked incentives for electronics manufacturing attract assembly capacity outside China, reducing tariff exposure for export markets.
- Remote patient monitoring reimbursement:CMS billing codes in the United States now cover sleep disorder management via connected devices, opening B2B2C hospital system partnerships.
- Generative AI coaching convergence:Large language models layered atop biometric streams enable hyper-personalized sleep intervention protocols that differentiate subscription tiers.
Industry Challenges
- Biomedical algorithm talent scarcity:Cross-functional teams combining signal processing, sleep medicine, and regulatory science command premium compensation in Boston and San Francisco labor markets.
- Multi-jurisdiction certification timelines:Parallel FDA, CE marking, and NMPA submissions for the same hardware platform fragment engineering resources across documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Sleep Trackers Market |
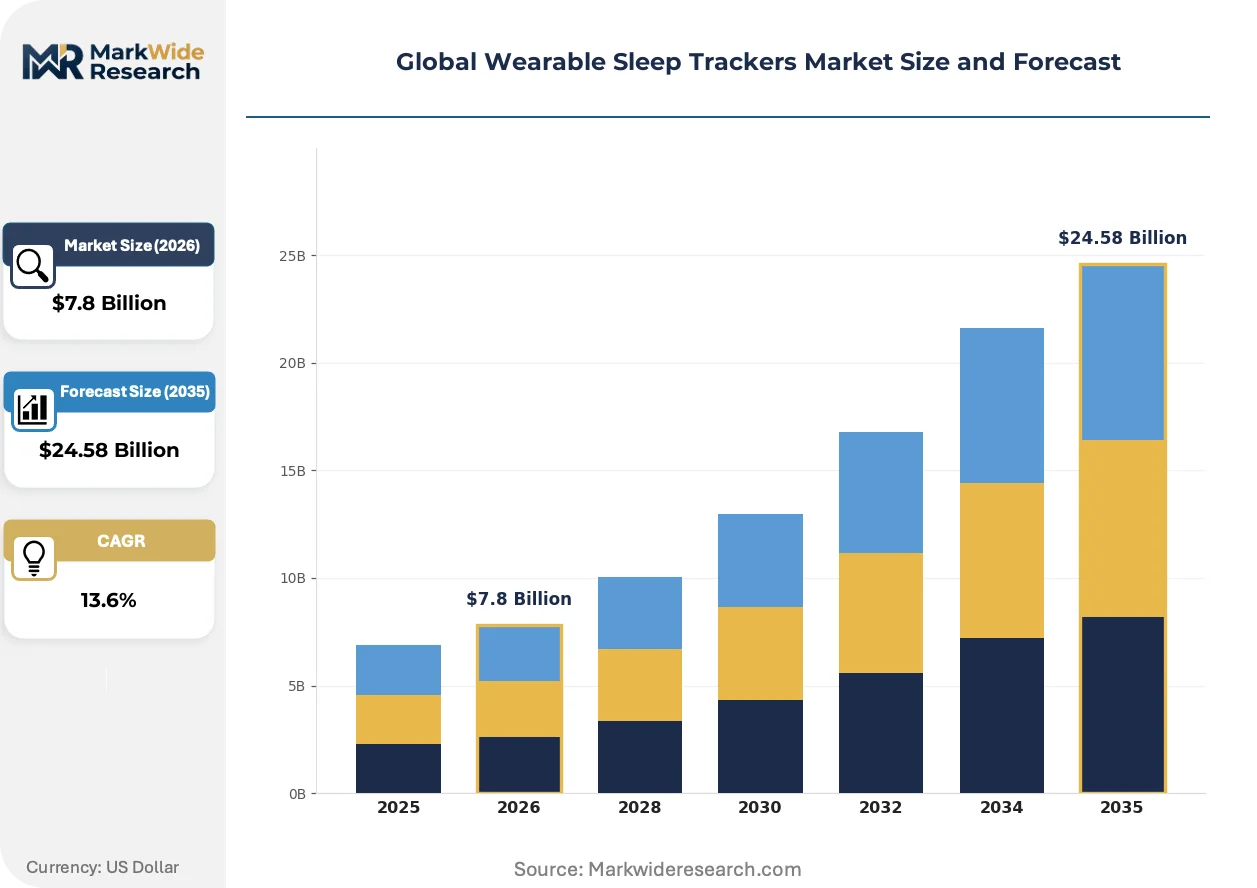
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatch, Fitness Band, Ring, Headband, Clip-on Tracker, Eyewear Technology: Photoplethysmography, Accelerometer, Electroencephalography, Ballistocardiography, Temperature Sensor, Pulse Oximetry Usage Scenario: Home Monitoring, Clinical Study, Sports Performance, Stress Management, Pediatric Tracking, Elderly Care Customer Type: Individual Consumers, Sleep Clinics, Research Institutions, Wellness Centers, Corporate Wellness Programs, Athlete Support Services |
| Companies Covered | Fitbit, Apple Inc., Garmin Ltd, ResMed, Huawei Device Co., Ltd, Oura Health Oy, Withings, Fossil Inc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Sleep Trackers Market Shifts & Advancements
Algorithmic personalization is compressing the gap between raw sensor output and actionable health guidance, shifting competitive advantage from hardware specifications to software-defined user retention mechanics.
Multi-modal sensor fusion is electrifying the accuracy of sleep architecture estimation. Devices now combine photoplethysmography, 3-axis accelerometry, and skin temperature thermistors to disambiguate wake from REM states. Sleep disorder clinics in Germany and the Netherlands are adopting these consumer-grade streams for longitudinal patient monitoring. The technology is electrifying clinical research workflows by replacing overnight laboratory stays with weeks of ambulatory data capture.
The FDA's evolving software-as-medical-device framework is bifurcating product development pathways. Sleep apnea detection algorithms now trigger premarket notification requirements if marketed with diagnostic intent. Vendors targeting the United States must maintain quality management systems under 21 CFR Part 820. Ring-form-factor specialists are responding by bifurcating SKUs: wellness-grade for direct-to-consumer, clinical-grade for healthcare channel partners.
Employer-sponsored wellness programs are consolidating purchasing decisions away from individual consumers. Fortune 500 human resource departments now negotiate enterprise licenses covering thousands of employees, extracting volume discounts unavailable in retail. This concentration is most visible in the United States, where self-insured employers bear direct medical cost risk and quantify sleep intervention ROI through reduced hypertension and diabetes claims.
Global Wearable Sleep Trackers Market Segmentation
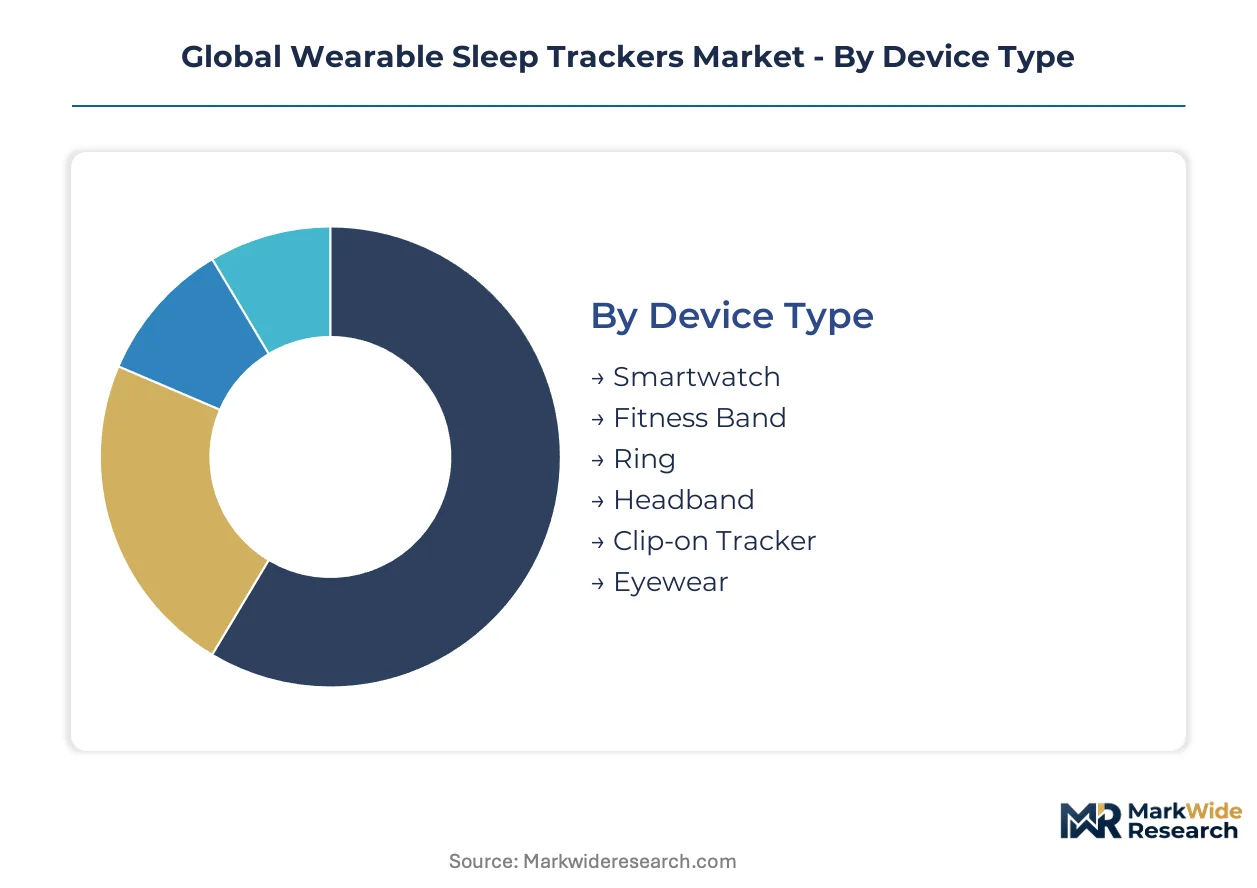
Wearable sleep tracker segmentation reveals how hardware form factors, sensor modalities, and procurement channels fragment addressable revenue pools. Understanding these divides exposes where unit economics concentrate versus where premium pricing commands sustainable margins.
Device Type:
Volume concentration favors wrist-worn formats while premium positioning clusters on discrete finger and head-mounted systems.
- Smartwatch:Multi-function wrist-worn displays integrate sleep staging with daytime health metrics, capturing the largest installed base. Corporate wellness programs in the United States standardize procurement around Apple Watch and Garmin platforms for unified fleet management.
- Ring:Titanium-encased optical sensors on the finger minimize sleep disruption while enabling continuous peripheral temperature tracking. Oura and Ultrahuman dominate direct-to-consumer premium tiers through subscription-locked advanced analytics.
- Fitness Band:Stripped-down accelerometer and PPG modules in silicone straps serve price-sensitive Asian markets with basic sleep-wake detection.
- Headband:Dry-electrode EEG arrays capture frontal cortex signals for research-grade hypnogram accuracy. Sleep labs in Germany and the Netherlands deploy these for ambulatory polysomnography substitutes.
- Clip-on Tracker:Accelerometer-only devices attach to pillowcases or mattress edges, offering entry-level sleep disruption logging without body-worn compliance.
- Eyewear:Smart frames with embedded PPG and temperature sensors remain experimental, targeting narcolepsy and REM behavior disorder monitoring in Japanese clinical trials.
Mature deployment sits with Smartwatch. Newer deployment is concentrated in Ring.
Technology:
Sensor fusion architectures now layer multiple modalities to disambiguate sleep states previously indistinguishable through single-source measurement.
- Photoplethysmography:Green and infrared LED arrays measure blood volume changes to derive heart rate variability and respiratory rate proxies. Shenzhen optical module suppliers drive 70%+ component cost reduction over five years.
- Accelerometer:3-axis MEMS devices detect movement cessation and periodic limb movements. Sports performance applications in Australia leverage this for training load-recovery balance.
- Electroencephalography:Frontal and occipital electrode configurations capture brainwave patterns for sleep stage classification. Research institutions in Switzerland require FDA 510(k)-cleared EEG headbands for protocol compliance.
- Ballistocardiography:Pressure-sensitive mattress strips detect micro-movements from cardiac ejection without body-worn sensors. Elderly care facilities in Japan deploy these for fall-risk correlation.
- Temperature Sensor:Skin thermistors track distal-proximal gradient shifts that precede sleep onset. Women's health applications exploit this for fertility window prediction.
- Pulse Oximetry:Red and infrared PPG variants estimate blood oxygen saturation for sleep apnea screening. FDA scrutiny of diagnostic claims forces wellness-grade recalibration.
Multi-sensor fusion is displacing single-modality dominance in clinical-adjacent deployments.
Usage Scenario:
Application contexts determine whether devices face consumer convenience thresholds or clinical validation requirements.
- Home Monitoring:Consumer self-tracking for sleep hygiene optimization dominates unit shipments. China's Xiaomi and Huawei ecosystem integration accelerates penetration.
- Clinical Study:Protocol-compliant data capture for pharmaceutical trials and academic research commands 10-20x hardware premiums. CROs in the United Kingdom specify CE-marked devices for EU trial sites.
- Sports Performance:Recovery scoring integrated with training management platforms. Professional cycling teams in Italy mandate Oura rings for altitude camp monitoring.
- Stress Management:HRV-guided breathing interventions during wake periods. Corporate wellness vendors in Singapore bundle these with mental health EAPs.
- Pediatric Tracking:Parental anxiety drives demand for crib-mounted and wearable infant monitors. Owlet's sock-based pulse oximetry faced FDA warning letters over diagnostic marketing.
- Elderly Care:Nursing home fall prediction and nocturnal wandering alerts. Japanese insurers subsidize deployment for dementia patient cohorts.
Reimbursement eligibility concentrates in Clinical Study. Direct-to-consumer momentum is expanding most quickly in Home Monitoring.
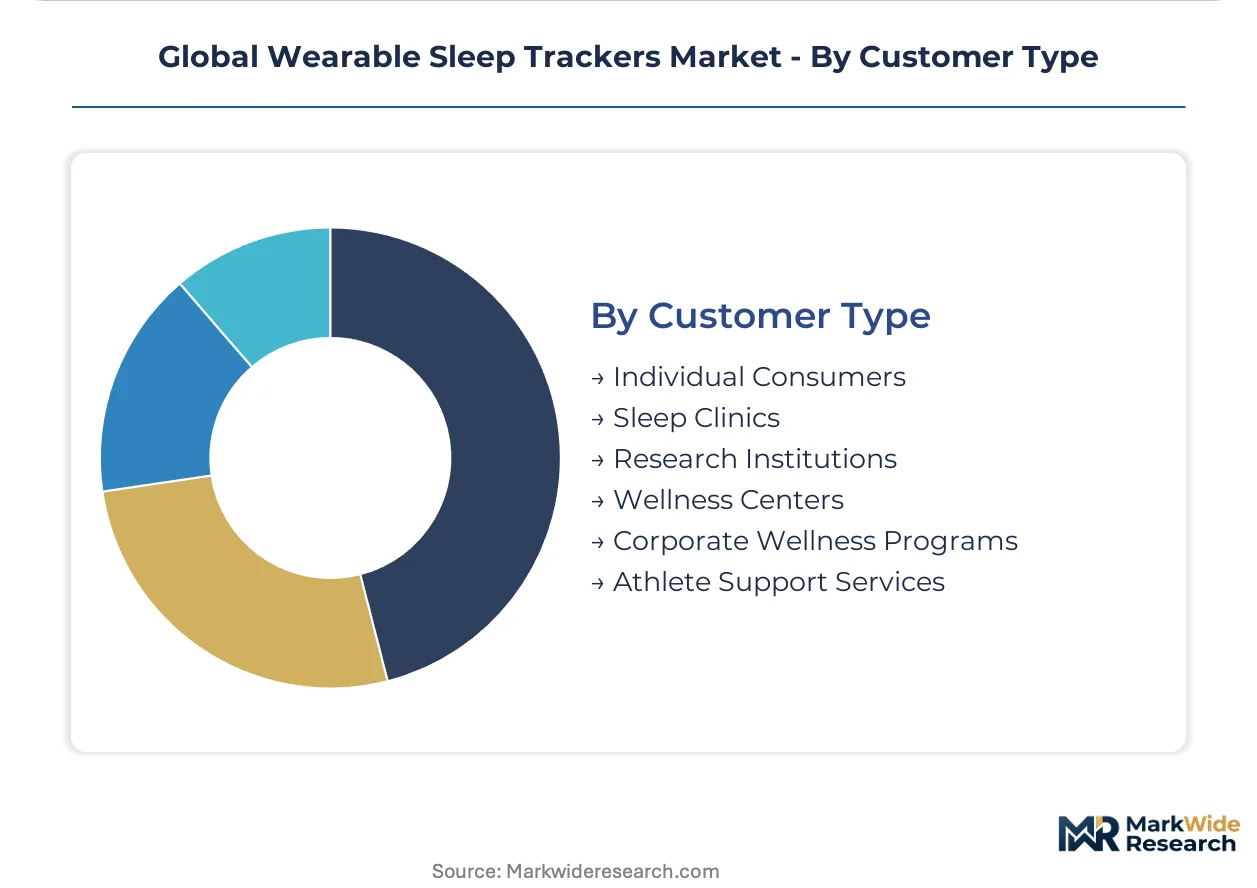
Customer Type:
Procurement authority is shifting from individual discretion to institutional purchasing departments with negotiated enterprise terms.
- Individual Consumers:Retail and direct-to-consumer channels with price elasticity driving feature-tier selection. Amazon reviews and Reddit communities shape consideration sets.
- Sleep Clinics:Physician practices prescribing take-home monitoring for sleep apnea diagnosis. ResMed and Philips dominate this channel with FDA-cleared platforms.
- Research Institutions:Academic medical centers and contract research organizations with protocol-specific accuracy requirements. Stanford Sleep Medicine Center validates consumer devices against polysomnography gold standards.
- Wellness Centers:Spas and longevity clinics bundling devices with coaching services. Dubai and Riyadh facilities source white-label rings for branded member programs.
- Corporate Wellness Programs:Self-insured employers quantifying intervention ROI through medical claims reduction. Walmart and Target have deployed fleet-scale Apple Watch programs.
- Athlete Support Services:Professional sports franchises and Olympic committees with performance optimization mandates. UK Sport mandates WHOOP for funded athlete monitoring.
Volume scale sits with Individual Consumers. Margin expansion is accelerating in Corporate Wellness Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor supplies the densest concentration of optical sensor modules and low-power microcontrollers feeding wearable sleep tracker assembly lines worldwide.
United States
Corporate wellness procurement from self-insured employers like Walmart and Target drives institutional volume. The FDA's software-as-medical-device framework forces vendors to validate sleep apnea detection algorithms or recategorize consumer features. Boston and San Francisco labor markets command premium compensation for cross-functional teams combining signal processing with regulatory science.
China
Xiaomi and Huawei ecosystem integration accelerates consumer penetration through domestic retail channels. The NMPA maintains distinct pathways for wellness-grade versus clinical-grade device registration. Guangdong Province contract manufacturers concentrate discrete optical sensor flows through a narrow corridor of Shenzhen and Dongguan facilities.
Germany
Sleep disorder clinics in Munich and Hamburg adopt consumer-grade biometric streams for longitudinal patient monitoring. The EU AI Act and MDR impose conformity requirements on algorithmic health scoring that extend market access timelines. Baden-Württemberg research institutions specify CE-marked EEG headbands for pharmaceutical trial protocol compliance.
Japan
Elderly care facilities in Tokyo and Osaka deploy ballistocardiography mattress strips for fall-risk correlation among dementia patient cohorts. METI subsidizes nursing home technology adoption through insurer-backed deployment programs. Kanto region clinical trials test smart eyewear with embedded PPG sensors for narcolepsy monitoring.
India
Production-linked incentives for electronics manufacturing attract assembly capacity outside China, reducing tariff exposure for export markets. The PLI scheme targets component localization for wearables in Tamil Nadu and Karnataka clusters. Bangalore-based wellness vendors bundle HRV-guided breathing interventions with corporate mental health EAPs.
Global Wearable Sleep Trackers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the wearable sleep tracker value chain. The market structures around three tiers: integrated health ecosystem operators, specialized form-factor innovators, and component-assembly contract manufacturers. Strategic moves concentrate on algorithmic differentiation through subscription software layers and geographic diversification of manufacturing footprints to mitigate tariff exposure.
Within the health ecosystem tier, Apple Inc. and Garmin Ltd exemplify platform-scale operators that embed sleep metrics within broader wellness dashboards. Oura Health Oy occupies a discrete position among ring-form-factor specialists that monetize through membership-locked advanced analytics. These three entities represent divergent archetypes: horizontal platform integration, vertical hardware-software specialization, and premium subscription economics.
| Leading Market Players |
|---|
| Fitbit |
| Apple Inc. |
| Garmin Ltd |
| ResMed |
| Huawei Device Co., Ltd |
| Oura Health Oy |
| Withings |
| Fossil Inc. |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Biomedical algorithm talent scarcity in Boston and San Francisco labor markets widens pricing-tier spreads between wellness-grade and clinical-grade hardware, as cross-functional teams combining signal processing with regulatory science command premium compensation that manufacturers pass through to healthcare channel partners.
Pricing Analysis
Subscription-locked advanced analytics anchor value-based pricing for ring-form-factor specialists, while per-unit transactional models dominate wrist-worn smartwatch procurement. Price differentiation rests on FDA 510(k) certification tier and enterprise volume scale, with clinical-grade SKUs commanding substantial premiums over direct-to-consumer wellness variants. Pricing pressure stems from Shenzhen optical module suppliers driving component cost compression that squeezes mid-tier fitness band margins. Individual consumers exhibit highest price sensitivity, whereas self-insured employers in corporate wellness programs demonstrate inelastic demand for fleet-standardized platforms.
Supply Chain Analysis
India's PLI scheme for wearables is reshaping sourcing patterns as production-linked incentives attract assembly capacity outside China, reducing tariff exposure for export markets. Discrete optical sensors and low-power microcontrollers flow through Guangdong Province contract manufacturers in Shenzhen and Dongguan, with ballistocardiography pressure strips and titanium ring enclosures sourced from Japanese and German precision metalworkers. Single-source vulnerability concentrates in Shenzhen optical module corridors. Distribution runs through direct-to-consumer e-commerce, enterprise procurement departments, and hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into optical sensor design and captive algorithm development teams is accelerating as vendors seek to control the software-defined analytics layers that drive subscription renewal rates and differentiate premium positioning.
For Market Incumbents: Lock in algorithmic personalization capabilities by acquiring specialized signal processing boutiques in Boston and San Francisco, insulating against biomedical talent scarcity that threatens R&D velocity. Fortify FDA 510(k) predicate device portfolios to defend against software-as-medical-device reclassification pressure that fragments development roadmaps. Deepen enterprise wellness channel control through outcome-based contracting models that quantify medical claims reduction.
For New Entrants and Emerging Players: Generative AI coaching convergence offers a technology-first wedge into the subscription analytics tier, where large language models layered atop biometric streams remain underexploited by established hardware vendors. Target India's PLI-subsidized manufacturing clusters for cost-competitive assembly, then penetrate European sleep disorder clinics seeking CE-marked ambulatory monitoring alternatives to polysomnography. Pursue white-label partnerships with Dubai and Riyadh longevity clinics bundling devices with coaching services.
For Investors and Strategic Acquirers: Re-rating potential sits with ring-form-factor specialists given CMS reimbursement code expansion for remote patient monitoring that opens B2B2C hospital system partnerships. Long-term viability hinges on software-defined revenue mix exceeding hardware transactional dependence. Target acquisition archetypes: vertical specialists with FDA-cleared sleep apnea detection algorithms and locked-in enterprise wellness contracts. Watch FDA software-as-medical-device enforcement actions as inflection indicator for compliance-cost repricing across vendor tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Validation Investment | FDA 510(k) clearance for sleep apnea detection unlocks clinical-grade pricing tiers and hospital channel access. |
| Manufacturing Footprint Diversification | Tamil Nadu and Karnataka assembly capacity reduces tariff exposure and China concentration risk. |
| Enterprise Wellness Partnership | Fortune 500 fleet contracts bypass retail price sensitivity and generate predictable recurring revenue. |
| Multi-Modal Sensor Fusion R&D | Combining PPG, accelerometry, and thermistors disambiguates REM states for research protocol compliance. |
| Subscription Tier Expansion | Membership-locked readiness metrics and personalized guidance differentiate Oura-style premium economics. |
Research Methodology
SEC filings, FDA 510(k) premarket notification databases, and CMS reimbursement code registers formed the secondary backbone, cross-referenced with trade flow data from Guangdong Province export records and enterprise wellness procurement disclosures. Primary interviews with biomedical engineers at Stanford Sleep Medicine Center, GPO contracts managers at hospital purchasing committees, and regulatory affairs leads at FDA-cleared device manufacturers validated secondary findings. Bottom-up unit shipment estimates by form factor and top-down value aggregation across subscription revenue streams were triangulated to constrain forecast variance.
Bottom-up modeling tracked smartwatch, ring, fitness band, headband, and clip-on tracker volumes through the projection horizon, with top-down cross-checks against corporate wellness program penetration rates and sleep clinic diagnostic device replacement cycles. CAGRs were derived from fitted growth curves across the analysis window, incorporating photoplethysmography miniaturization adoption curves and EU AI Act conformity timeline assumptions. Segmentation dimensions included device type, sensor modality fusion level, usage scenario, and customer procurement authority.
Several conditions sit outside the modeled scope, including NMPA registration pathway shifts in China, unforeseen FDA enforcement actions on wellness-grade diagnostic marketing claims, and commodity price volatility in optical sensor substrates. Forecasts reflect documented assumptions regarding reimbursement code stability and algorithmic health scoring regulatory convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Americas Insomnia Market