
 Global Sleep Tech Devices Market | 2026-2036
Global Sleep Tech Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sleep Tech Devices Market Foresight
China's Shenzhen manufacturing corridor is rewriting component supply dynamics for biometric sensors used in sleep monitors. ResMed Inc. leverages its vertical integration into cloud-connected CPAP ecosystems to sustain recurring revenue streams. Oura Health differentiates through ring-form-factor precision that competes with wrist-worn alternatives in recovery-tracking segments.
Sleep tech devices encompass instrumented hardware and software systems that measure physiological signals—heart rate variability below 0.1 Hz, blood oxygen saturation, and body movement patterns—to generate sleep architecture reports for clinical or consumer decision-making. Polysomnography-grade systems anchor hospital and sleep clinic procurement budgets, while actigraphy-based wearable devices capture the fastest expansion as home care users prioritize convenience over clinical fidelity. Smart mattresses occupy concentrated margin pools through subscription-anchored business models that extend customer lifetime value beyond initial hardware purchases.
FDA software-as-medical-device frameworks and EU MDR conformity requirements shape product development roadmaps by mandating clinical validation thresholds before market authorization. Japan's PMDA and South Korea's MFDS impose additional localization testing that controls entry timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as these determine whether sleep tech purchases shift from discretionary consumer spending to covered medical benefits.
Market Dynamics
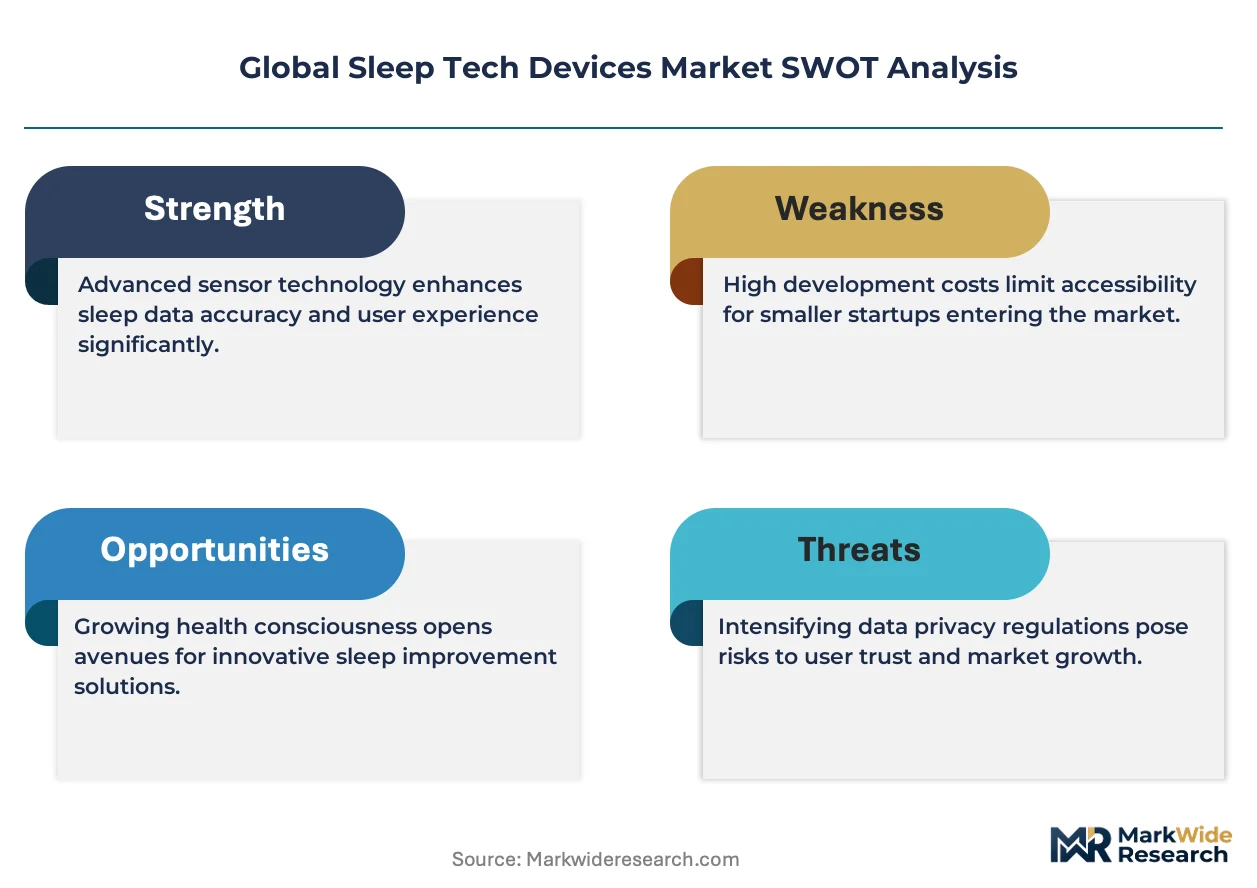
FDA software-as-medical-device pathways are compressing commercialization timelines while EU MDR conformity requirements impose clinical validation thresholds that reshape product development roadmaps across biometric sensor ecosystems.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS reimbursement codes in the United States are converting discretionary consumer purchases into covered medical benefits for home care users managing chronic conditions.
- Corporate Wellness Procurement:Employer-sponsored wellness programs are expanding bulk procurement of sleep tracking systems as workforce productivity metrics integrate recovery data.
- Cloud-Connected CPAP Ecosystems:Recurring revenue streams from subscription-anchored business models extend customer lifetime value beyond initial hardware purchases.
Market Restraints
- Biometric Sensor Supply Concentration:Shenzhen manufacturing corridor dominance creates single-point vulnerability for component sourcing across multiple device categories.
- Clinical Validation Costs:Polysomnography-grade system development requires extensive trial infrastructure that excludes smaller entrants from hospital procurement channels.
- Actigraphy Fidelity Ceiling:Wrist-worn and ring-form-factor devices face inherent physiological signal limitations that restrict clinical diagnostic acceptance.
Strategic Opportunities
- Japan PMDA Localization:Additional testing requirements for foreign manufacturers create first-mover advantage for compliant entrants in aging-population sleep clinics.
- Smart Mattress Subscriptions:Hardware-software bundles with continuous monitoring capabilities unlock recurring revenue pools in premium home care segments.
- South Korea MFDS Pathways:Streamlined digital health device approvals accelerate market entry for software-validated sleep architecture reporting tools.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, EU MDR, PMDA, and MFDS submissions require dedicated regulatory affairs capacity that strains mid-scale developers.
- Legacy System Integration:Hospital electronic health record compatibility demands consume engineering resources without direct revenue attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sleep Tech Devices Market |
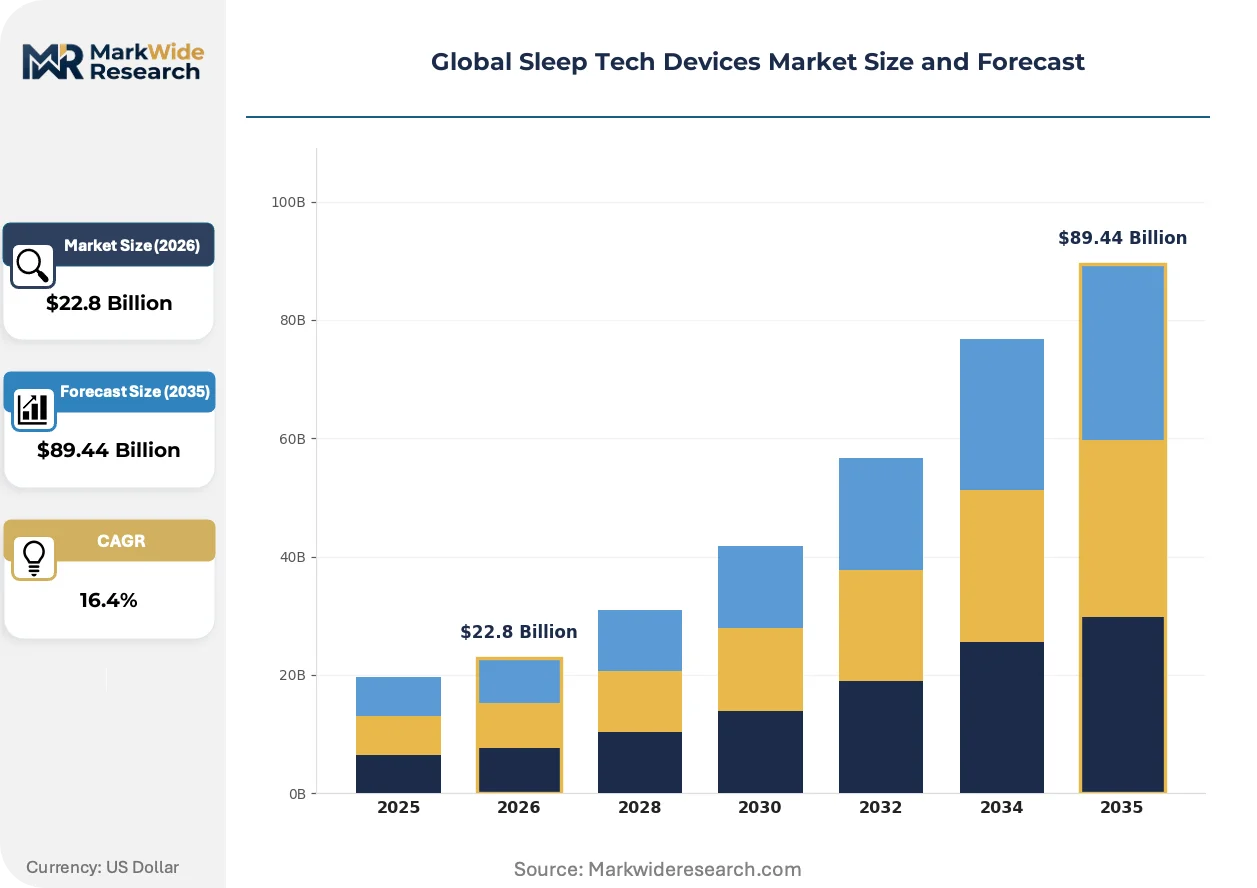
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $89.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Non-Wearable Devices, Smart Mattresses, Sleep Tracking Apps, CPAP Machines, Sound Machines Technology: Actigraphy, Polysomnography, Ballistocardiography, Electroencephalography, Pulse Oximetry, Accelerometry Application: Insomnia Management, Sleep Apnea Monitoring, Circadian Rhythm Analysis, Narcolepsy Detection, Restless Leg Syndrome, Shift Work Disorder End User: Sleep Clinics, Home Care Users, Occupational Health Providers, Wellness Centers, Research Institutions, Elderly Care Facilities |
| Companies Covered | Tempur Sealy International, Inc., Fisher & Paykel Healthcare Corporation Limited, ResMed Inc., Somnox, Inogen, Inc., Koninklijke Philips N.V., Oura Health, Ozlo Sleep, Eight Sleep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sleep Tech Devices Market Shifts & Advancements
Artificial intelligence inference at the edge is transforming raw physiological signals into actionable sleep architecture classifications without cloud dependency, reshaping competitive differentiation around data privacy and latency performance.
Photoplethysmography arrays embedded in non-wrist form factors are digitizing heart rate variability capture below 0.1 Hz for sleep staging algorithms. Home care users seeking chronic condition management tools are adopting these systems faster than clinic-grade alternatives. The technology is digitizing the boundary between consumer wellness and clinical monitoring by enabling physician-validated reports from consumer hardware.
The EU MDR software-as-medical-device framework is mandating clinical validation thresholds before CE marking authorization for sleep disorder diagnostic algorithms. Manufacturers must demonstrate equivalence to polysomnography reference standards through prospective trials. Wearable device developers targeting European home care markets are restructuring quality management systems to accommodate notified body scrutiny of algorithm change protocols.
Subscription-anchored business models are displacing perpetual license structures across smart mattress and connected bedding categories. Direct-to-consumer channels with trial periods and hardware financing are capturing buyer relationships previously held through retail intermediaries. United States home care users exhibit strongest preference for bundled monitoring-plus-coaching services that convert device data into personalized intervention protocols.
Global Sleep Tech Devices Market Segmentation
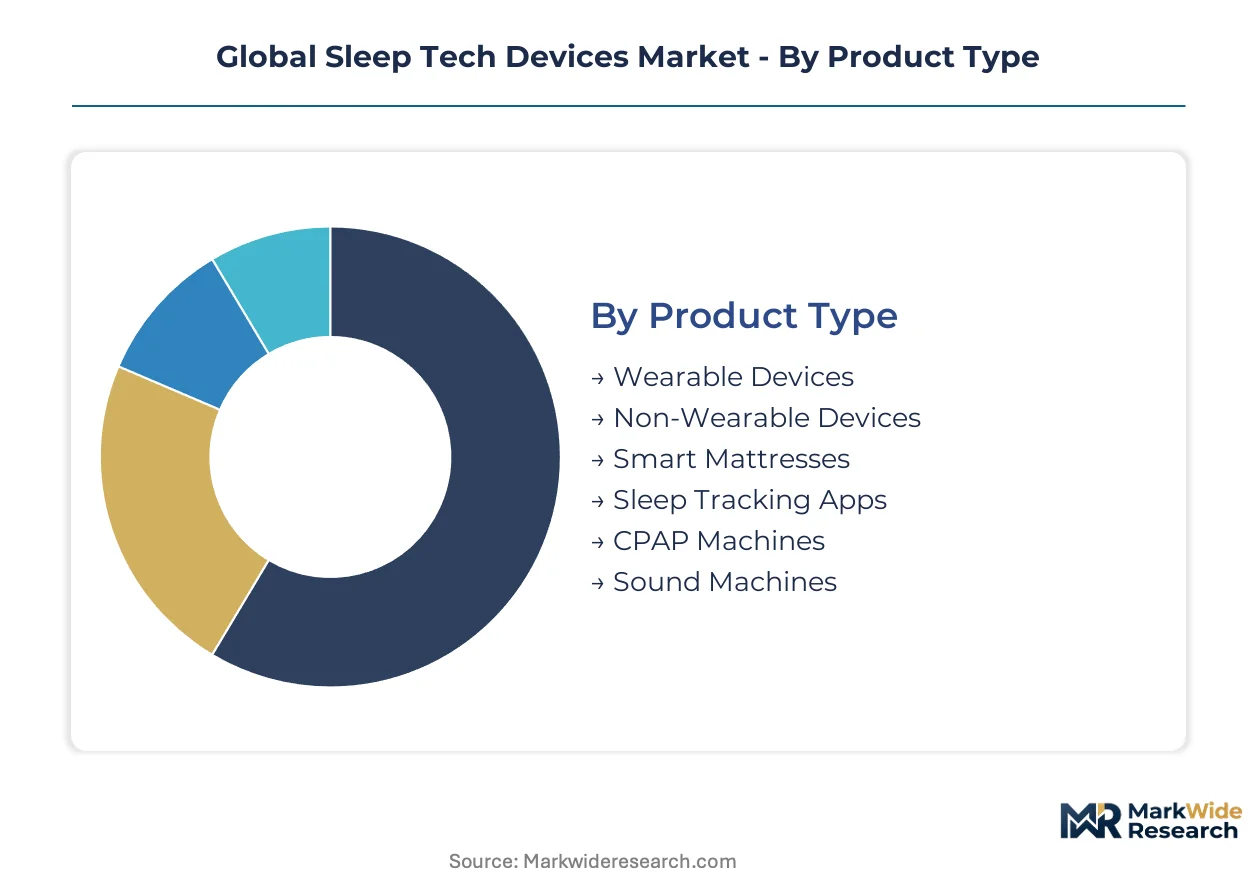
Product lifecycle velocity varies dramatically across sleep tech categories. Hardware refresh cycles compress as sensor miniaturization accelerates, while clinical-grade systems retain decade-long depreciation schedules. Understanding replacement dynamics and demand concentration across each dimension reveals where capital deployment yields disproportionate returns.
Product Type:
Wearable devices turn over fastest at 18-24 month replacement cycles, while CPAP machines and smart mattresses anchor the slowest refresh patterns at 5-7 years. This divergence shapes inventory planning and subscription revenue modeling across manufacturer portfolios.
- Wearable Devices:Wrist-worn and ring-form-factor instruments capture photoplethysmography signals for heart rate variability analysis below 0.1 Hz. United States home care users seeking chronic condition management tools drive bulk of volume through direct-to-consumer channels with trial-period financing.
- Smart Mattresses:Embedded pressure sensor arrays and ballistocardiography modules enable continuous sleep architecture monitoring without user compliance friction. Subscription-anchored business models in premium United States home care segments extend customer lifetime value through bundled coaching services.
- Non-Wearable Devices:Bedside and under-mattress sensors eliminate wearability constraints for elderly populations.
- Sleep Tracking Apps:Software-only solutions leverage smartphone accelerometry and microphone arrays for basic sleep detection.
- CPAP Machines:Cloud-connected positive airway pressure systems with integrated pulse oximetry dominate sleep apnea therapy workflows.
- Sound Machines:White noise and adaptive audio generators address environmental sleep disruption without physiological monitoring capabilities.
Wearable devices dominate installed base volume. Smart mattresses represent where expansion concentrates most steeply.
Technology:
Cost tier stratification separates hospital-procurement-grade systems from consumer-accessible alternatives. Polysomnography and electroencephalography anchor premium clinical budgets, while actigraphy and accelerometry penetrate mass-market price points.
- Actigraphy:Motion-sensing algorithms estimate sleep-wake states through accelerometer-derived movement patterns. Home care users across United States, Japan, and Germany prioritize convenience over clinical fidelity, making this the volume leader in consumer channels despite diagnostic ceiling constraints.
- Polysomnography:Multi-parameter reference standard combines electroencephalography, electrooculography, electromyography, and respiratory belt sensors for gold-standard sleep staging. Sleep clinics in the United States and hospital systems across France and Switzerland maintain procurement budgets for these systems despite capital intensity.
- Ballistocardiography:Mechanical vibration sensing detects cardiac and respiratory signals through mattress-integrated pressure transducers.
- Electroencephalography:Scalp electrode arrays capture cortical electrical activity for definitive sleep stage classification.
- Pulse Oximetry:Transmissive or reflectance photoplethysmography measures blood oxygen saturation for apnea-hypopnea indexing.
- Accelerometry:Three-axis motion detection enables basic activity classification and sleep-wake estimation at minimal component cost.
Polysomnography dominates clinical validation requirements. Actigraphy captures where volume expansion concentrates.
Application:
Customer type segmentation separates reimbursed medical indications from discretionary wellness purchases. Sleep apnea monitoring and insomnia management anchor covered benefit categories, while circadian rhythm analysis and shift work disorder remain predominantly self-pay.
- Sleep Apnea Monitoring:Diagnostic and therapeutic workflows for obstructive and central sleep apnea drive the largest reimbursed indication category. United States CMS reimbursement codes for remote patient monitoring convert hardware purchases into covered medical benefits for home care users with chronic respiratory conditions.
- Insomnia Management:Cognitive behavioral therapy integration and sleep restriction protocol digitization address the most prevalent sleep disorder diagnosis. Wellness centers in Germany and occupational health providers across Japan are expanding procurement as workforce productivity metrics incorporate sleep quality data.
- Circadian Rhythm Analysis:Core body temperature and melatonin onset tracking for phase disorder characterization.
- Narcolepsy Detection:Multiple sleep latency testing and hypocretin level correlation for rare disorder diagnosis.
- Restless Leg Syndrome:Periodic limb movement indexing through leg-worn accelerometry or EMG channels.
- Shift Work Disorder:Schedule-rotation adaptation tools for transportation and healthcare worker populations.
Sleep apnea monitoring dominates reimbursement capture. Insomnia management represents where commercial expansion concentrates.
End User:
Geography of demand concentration clusters in aging economies with reimbursement infrastructure. United States home care users and Japanese elderly care facilities exhibit strongest preference for continuous monitoring, while European sleep clinics prioritize diagnostic-grade fidelity.
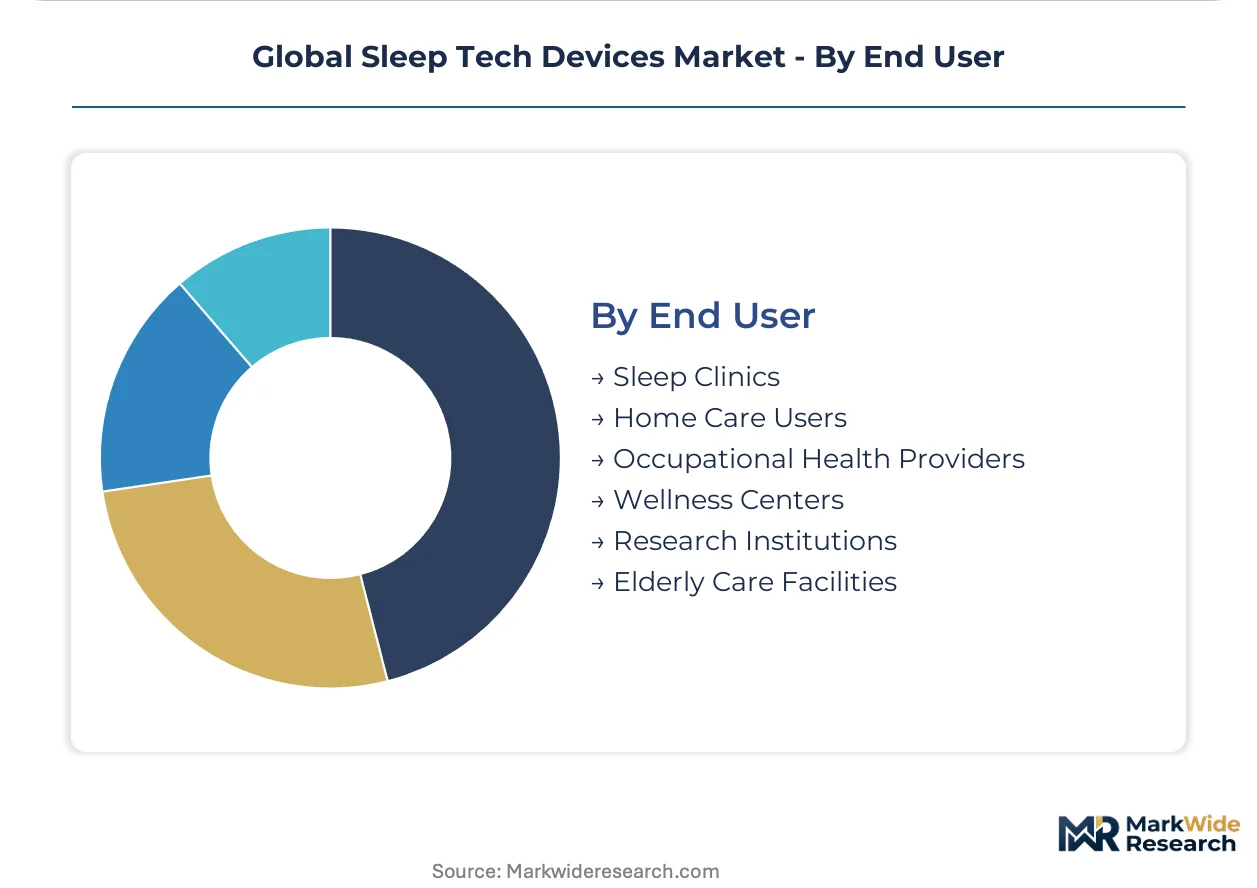
- Home Care Users:Individual consumers managing chronic conditions or optimizing wellness drive the largest addressable population. United States demand concentrates here as CMS reimbursement codes expand coverage for remote patient monitoring devices, converting discretionary purchases into medical benefits.
- Sleep Clinics:Specialized diagnostic facilities require polysomnography-grade equipment for clinical trial endpoints and insurance reimbursement. France, Switzerland, and Germany maintain dense networks of accredited sleep centers with capital equipment refresh cycles tied to EU MDR conformity timelines.
- Occupational Health Providers:Corporate wellness programs and transportation safety departments procure bulk tracking systems.
- Wellness Centers:Spas, fitness clubs, and longevity clinics offer recovery optimization as premium service add-ons.
- Research Institutions:Academic sleep laboratories and pharmaceutical trial sites require validated instrumentation for protocol compliance.
- Elderly Care Facilities:Nursing homes and assisted living operators deploy non-intrusive monitoring for fall-risk and nocturnal event detection.
Home care users dominate volume installed base. Sleep clinics anchor where premium pricing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States home care users deploy sleep tech predominantly for chronic condition management, whereas Japanese elderly care facilities prioritize non-intrusive monitoring for fall-risk detection. German sleep clinics anchor diagnostic-grade procurement budgets. Chinese manufacturing corridors supply biometric sensors across all geographies.
United States
CMS reimbursement codes for remote patient monitoring convert discretionary consumer purchases into covered medical benefits for home care users managing sleep apnea. FDA software-as-medical-device pathways compress commercialization timelines for algorithm-validated sleep architecture tools. The Minneapolis-Saint Paul corridor hosts concentrated CPAP device engineering and cloud-connected ecosystem development.
Japan
Aging-population sleep clinics drive demand for polysomnography-grade systems with localized software interfaces. PMDA imposes additional testing requirements that control entry timelines for foreign manufacturers seeking device authorization. The Kansai region around Osaka maintains dense networks of accredited sleep centers with capital equipment refresh cycles tied to regulatory conformity timelines.
Germany
Occupational health providers and corporate wellness programs expand bulk procurement of sleep tracking systems as workforce productivity metrics integrate recovery data. EU MDR conformity requirements mandate clinical validation thresholds before CE marking authorization for diagnostic algorithms. The Munich metropolitan area anchors medical device engineering clusters serving sleep clinic networks across Bavaria and Baden-Württemberg.
China
Shenzhen manufacturing corridors rewrite component supply dynamics for photoplethysmography arrays and biometric sensors used across wearable and non-wearable device categories. NMPA medical device registration requirements shape product localization strategies for foreign manufacturers. The Yangtze River Delta around Shanghai concentrates smart mattress assembly operations and subscription platform development for premium home care segments.
South Korea
Streamlined MFDS digital health device approvals accelerate market entry for software-validated sleep architecture reporting tools targeting home care users. Government-backed smart city initiatives integrate sleep monitoring into elderly care facility infrastructure. The Seoul Capital Area hosts concentrated development of ballistocardiography-embedded bedding systems for continuous nocturnal monitoring.
Global Sleep Tech Devices Market Competitive Landscape
Capability concentration sits with specialized diagnostic equipment manufacturers; scale advantage sits with diversified health technology conglomerates. The vendor base organizes into three tiers: polysomnography-grade system developers serving hospital procurement channels, consumer wearable specialists capturing direct-to-consumer volume, and smart mattress platforms anchoring subscription revenue pools. Dominant competitive moves include backward integration into cloud-connected service ecosystems and geographic expansion through regulatory pathway optimization.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and ResMed Inc. exemplify scale-driven positioning across multiple sleep tech categories. Fisher & Paykel Healthcare Corporation Limited occupies a position within the respiratory therapy specialist tier, representing focused clinical equipment development. These three anchors demonstrate how vendor origin and corporate structure map to distinct strategic archetypes in a market where regulatory compliance capacity separates sustainable participants from transient entrants.
| Leading Market Players |
|---|
| Tempur Sealy International, Inc. |
| Fisher & Paykel Healthcare Corporation Limited |
| ResMed Inc. |
| Somnox |
| Inogen, Inc. |
| Koninklijke Philips N.V. |
| Oura Health |
| Ozlo Sleep |
| Eight Sleep |
| Others |
Supply & Pricing Matrix
Overcapacity in Shenzhen photoplethysmography sensor fabs is compressing component costs while simultaneously eroding pricing power for finished-device manufacturers across all tiers, forcing suppliers to absorb margin pressure or risk volume displacement to vertically integrated rivals.
Pricing Analysis
Long-term offtake contracts dominate procurement between sleep tech OEMs and Shenzhen-based biometric sensor suppliers, locking in 12-18 month price floors that insulate against spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates polysomnography-grade systems with FDA 510(k) clearance from consumer wearables and basic sleep-tracking apps. Cost compression in the mid-tier wearable segment is intensifying because component commoditization has collapsed differentiation around heart rate variability algorithms. Home care users in the United States exhibit highest price sensitivity, while Japanese sleep clinics purchasing polysomnography systems show least elasticity due to reimbursement insulation and clinical validation requirements.
Supply Chain Analysis
Export-control regimes limiting flows of advanced photolithography equipment to Chinese semiconductor foundries have not yet constrained sleep tech sensor production, though dual-use biometric processing chips face emerging scrutiny. Component sourcing draws from China's Shenzhen corridor for PPG arrays, South Korea for MEMS accelerometers, and Taiwan for edge-AI inference chips. Ballistocardiography pressure sensors and cloud-connectivity modules represent critical single-source dependencies for smart mattress platforms. Tariff exposure runs through the Yangtze River Delta assembly hubs serving United States home care demand. Distribution runs through direct-to-consumer channels with trial-period financing, hospital procurement committees, and corporate wellness bulk purchasing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device pathways are compressing commercialization timelines from 36 months to under 18 months for algorithm-validated sleep architecture tools, creating a regulatory inflection that rewards first-movers with cleared diagnostic claims.
For Market Incumbents: Build cloud-connected ecosystem moats by integrating CPAP hardware with subscription-anchored coaching services that extend customer lifetime value beyond initial device purchases. Defend against Oura Health and Eight Sleep by accelerating backward integration into captive photoplethysmography sensor production in Shenzhen-adjacent manufacturing zones. Prioritize EU MDR notified body relationships to secure CE marking ahead of conformity assessment bottlenecks for algorithm-change protocols. For New Entrants and Emerging Players: Pursue white-space opportunities in South Korea's MFDS-streamlined digital health pathway and Japan's aging-population elderly care facilities where PMDA localization requirements have slowed foreign penetration. Target ballistocardiography-embedded smart mattresses for institutional buyers seeking non-intrusive monitoring without user compliance friction. Launch through direct-to-consumer channels with hardware financing and bundled sleep-coaching subscriptions to bypass retail margin extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart mattress platforms with subscription-anchored business models that monetize continuous monitoring data through personalized intervention protocols. Long-term viability over the five-to-ten year window favors developers with demonstrated FDA 510(k) clearance and EU MDR conformity capacity, as regulatory compliance separates sustainable participants from transient entrants. Monitor CMS reimbursement code expansions for remote patient monitoring as the signal indicating whether sleep tech purchases accelerate from discretionary consumer spending toward covered medical benefits.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates market authorization timelines for algorithm-validated sleep staging tools below traditional 510(k) pathways. |
| EU MDR Notified Body Engagement | Secures CE marking for diagnostic algorithms through prospective polysomnography equivalence trials mandated by conformity requirements. |
| Cloud-Connected Ecosystem Development | Extends ResMed-style recurring revenue streams through subscription-anchored CPAP and smart mattress service bundles. |
| Shenzhen Component Supply Agreement | Locks in photoplethysmography array pricing floors against spot-market volatility through long-term offtake contracts. |
| CMS Reimbursement Strategy | Converts discretionary United States home care purchases into covered medical benefits through remote patient monitoring code expansion. |
Research Methodology
A spread of perspectives from sleep clinic medical directors, biomedical engineers at CPAP manufacturers, GPO contracts managers, and FDA regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary interviews with corporate wellness procurement officers and smart mattress platform engineers were cross-validated against secondary sources including FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up installed base modeling and top-down spending-flow analysis were triangulated to constrain estimate variance.
Demand-supply balance dynamics across the analysis window were modeled through segmented cohort tracking of replacement cycles, reimbursement expansion scenarios, and manufacturing capacity utilization in Shenzhen sensor fabs. Segmentation dimensions included product type, sensing technology, clinical application, and end-user archetype with geographic regulatory cluster overlays. CAGRs were derived from fitted growth curves against historical adoption patterns in comparable remote patient monitoring categories. Forecast inputs incorporated FDA software-as-medical-device pathway velocity, EU MDR conformity assessment queue lengths, and CMS code expansion probabilities.
Sensitivities concentrate around reimbursement policy shifts, export-control tightening on biometric processing chips, and notified body capacity constraints for EU MDR algorithm-validation reviews. Forecasts reflect documented assumptions regarding regulatory pathway timelines and component cost trajectories. Material shifts in FDA software-as-medical-device precedent or CMS remote patient monitoring coverage determinations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Global Hypersomnia Treatment Market