
 Mobile Accessories Market | 2026-2036
Mobile Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Accessories Market Intelligence
Buyer power in the mobile accessories market is shifting from individual consumer purchases toward large, consolidated online retail platforms. Anker Innovations leverages its direct-to-consumer model to capture significant online market share. Belkin International sustains its premium positioning through strong channel partnerships with major device manufacturers and retailers like Apple. Meanwhile, Samsung Electronics integrates its accessories ecosystem deeply with its own smartphone and tablet releases.
Mobile accessories are defined as peripheral devices designed to augment the functionality, protection, or power management of smartphones and tablets. This includes products utilizing materials like silicone and polycarbonate for cases or advanced circuitry for power delivery. Protective items like cases and screen protectors constitute a high-volume, mature product category. In contrast, chargers and headphones represent segments with higher margin potential, driven by innovations in wireless charging and high-fidelity audio.
A complex regulatory environment governs market access and product design across key geographies. Compliance with the EU's CE marking and its common charger directive, FCC rules on wireless emissions in the United States, and China's GB safety standards is mandatory. Vendor success will be determined by their ability to navigate these divergent regional standards for power delivery and material recyclability to maintain a global footprint.
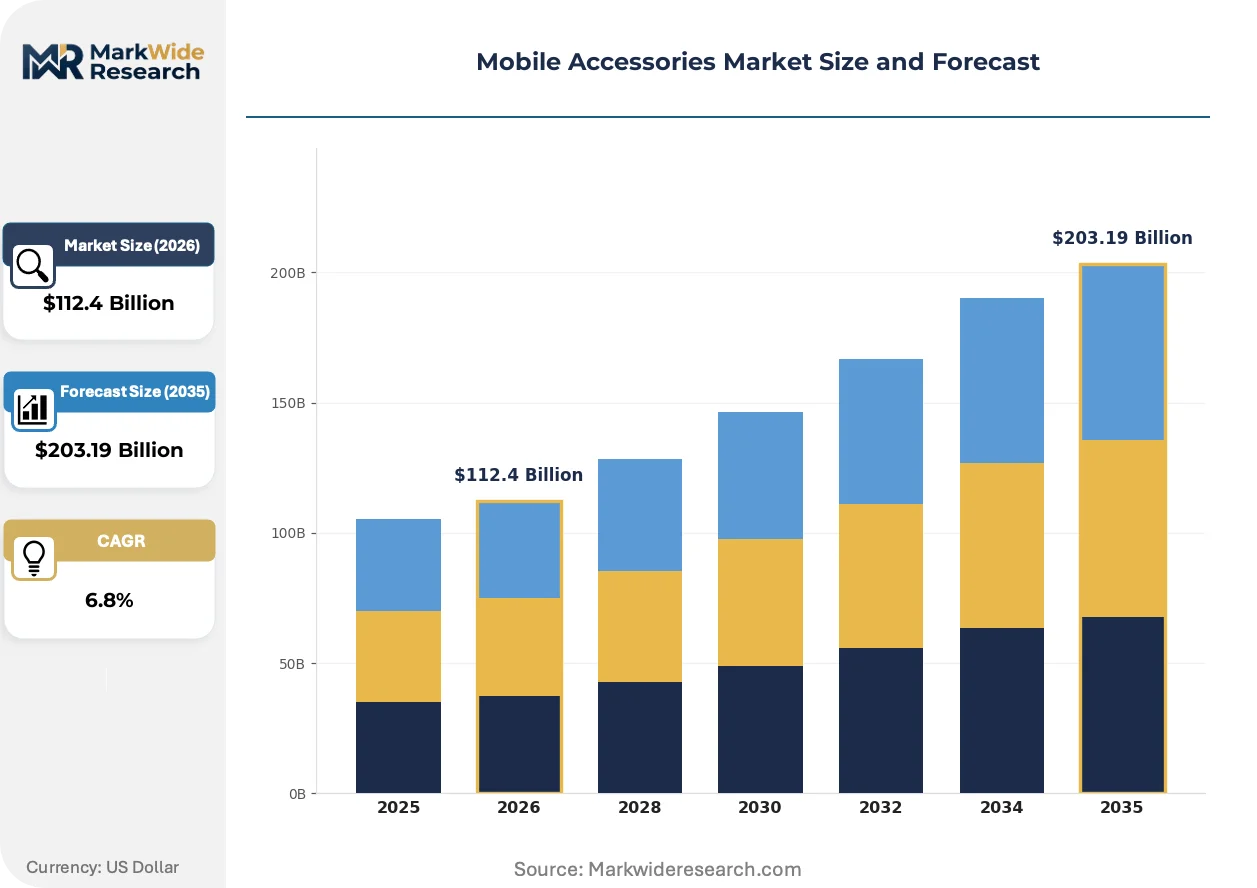
Market Dynamics
The central dynamic in the mobile accessories market is the tension between regulatory-driven hardware standardization, exemplified by the EU's USB-C mandate, and the competitive necessity for brands to differentiate through proprietary ecosystems, material innovation, and design.
Growth Catalysts
- Gallium Nitride (GaN) Technology:The adoption of GaN semiconductors in chargers enables smaller, more power-efficient designs, meeting consumer demand for faster and more portable charging solutions for multiple devices.
- Enterprise Device Programs:Corporate and government procurement of accessories for employee-issued smartphones and tablets creates a stable, high-volume demand channel for protective cases, chargers, and privacy screens.
- EU Common Charger Directive:The EU's mandate for USB-C standardizes charging ports, simplifying product development for global manufacturers and creating a predictable replacement cycle for compliant cables and power bricks.
Market Restraints
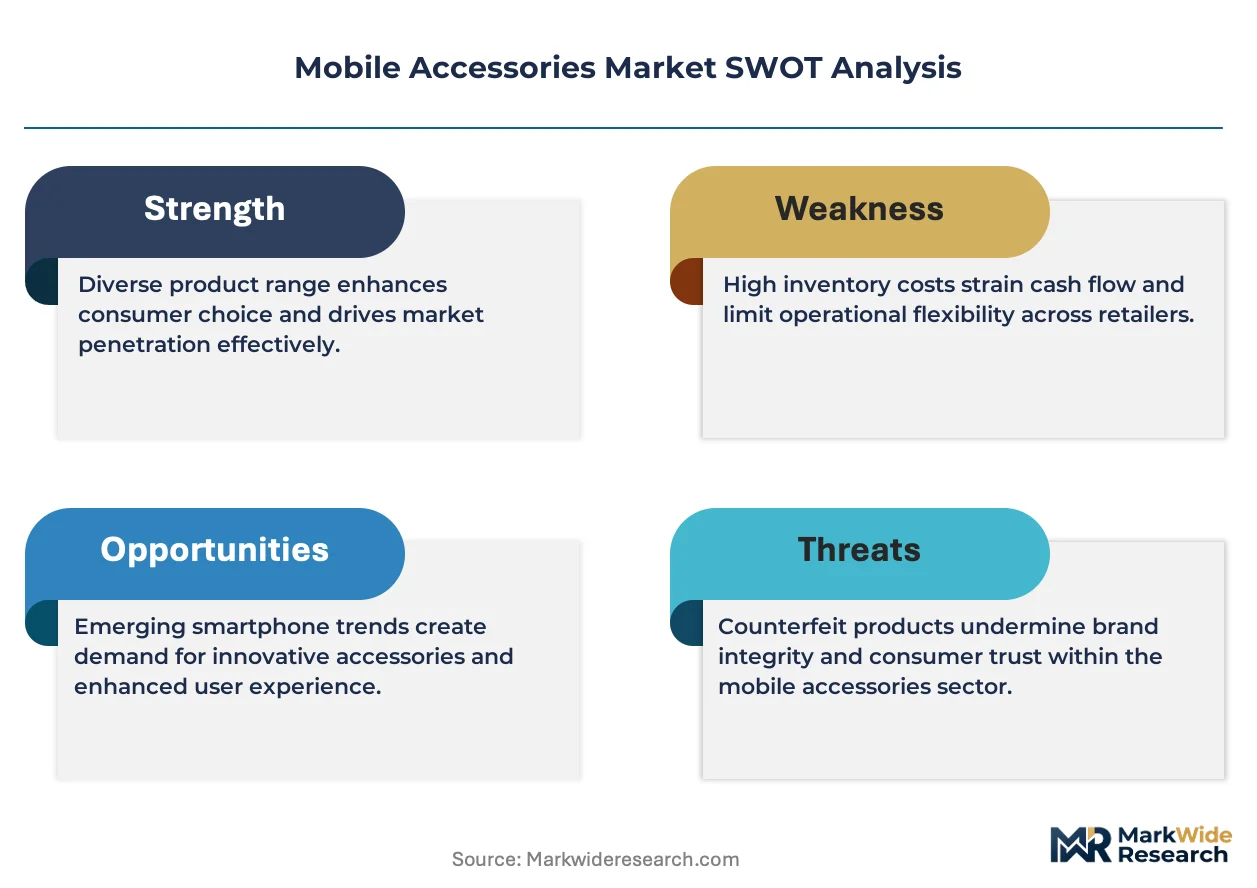
- Counterfeit Products:The proliferation of unauthorized and counterfeit accessories, particularly through online marketplaces, erodes brand value and presents safety risks, forcing legitimate vendors into price competition with inferior goods.
- Component Price Volatility:Fluctuations in the cost of raw materials like polycarbonate resins, silicone, and key semiconductor components for power management ICs create margin pressure for manufacturers.
- Divergent Global Standards:Navigating disparate regulatory requirements, such as FCC rules for wireless charging emissions in the US versus China's GB safety standards, increases compliance costs and time-to-market.
Strategic Opportunities
- High-Growth Smartphone Markets:Underpenetrated demand for premium and specialized accessories in markets like India and Southeast Asia offers significant expansion potential as smartphone ownership and disposable income rise.
- Health and Wellness Integration:The convergence of high-fidelity audio with biometric sensors in headphones and earbuds opens a new market for accessories that provide health monitoring functionalities.
- Eco-Friendly Materials:Developing and marketing products made from recycled plastics, bio-polymers, and other sustainable materials caters to a growing consumer segment willing to pay a premium for environmental responsibility.
Industry Challenges
- Rapid Compliance Cycles:Keeping pace with evolving environmental regulations, such as the EU's directives on material recyclability and e-waste, requires constant redesign and supply chain adjustments for manufacturers.
- Intellectual Property Protection:The high cost and complexity of defending design patents and trademarks against infringement on a global scale is a significant operational burden, especially for smaller innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Accessories Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Screen Protectors, Chargers, Headphones End User: Consumers, Enterprises, Educational Institutions, Retailers Material: Plastic, Silicone, Leather, Metal Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Belkin International Inc., Sony Corporation, Apple Inc., Sennheiser Electronic GmbH & Co. KG, Harman International Industries, Samsung Electronics Co. Ltd., Bose Corporation, Logitech International S.A., Anker Innovations Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Accessories Market Strategic Shifts & Innovations
Product innovation is bifurcating between advanced material science for protection and sustainability, and sophisticated electronics integration for power and audio. These advancements are occurring against a backdrop of increasing regulatory harmonization that simplifies some product categories while raising compliance barriers.
Gallium Nitride (GaN) technology provides a significant leap in power adapter efficiency and size reduction. This material is being rapidly adopted by consumers and enterprise buyers who require fast charging for laptops, tablets, and phones from a single, compact device. GaN's superior thermal performance and power density is overtaking traditional silicon-based circuitry in the premium multi-port charger segment.
Regulatory frameworks are actively standardizing hardware interfaces across the industry. The European Union's revised Radio Equipment Directive, which enforces USB-C as a common charging standard, fundamentally alters product design roadmaps for all device manufacturers selling into the EU. The power delivery and cable categories are most affected, compelling a global shift toward USB-C to maintain market access.
Consumer purchasing criteria are shifting to prioritize products with verifiable sustainability claims. This trend disrupts the market for low-cost, disposable accessories by creating a premium segment for cases and cables made from recycled plastics, bio-based materials, or with carbon-neutral certifications. This shift is most pronounced in North American and European retail channels, where eco-labeling influences brand perception.
Mobile Accessories Market Segmentation
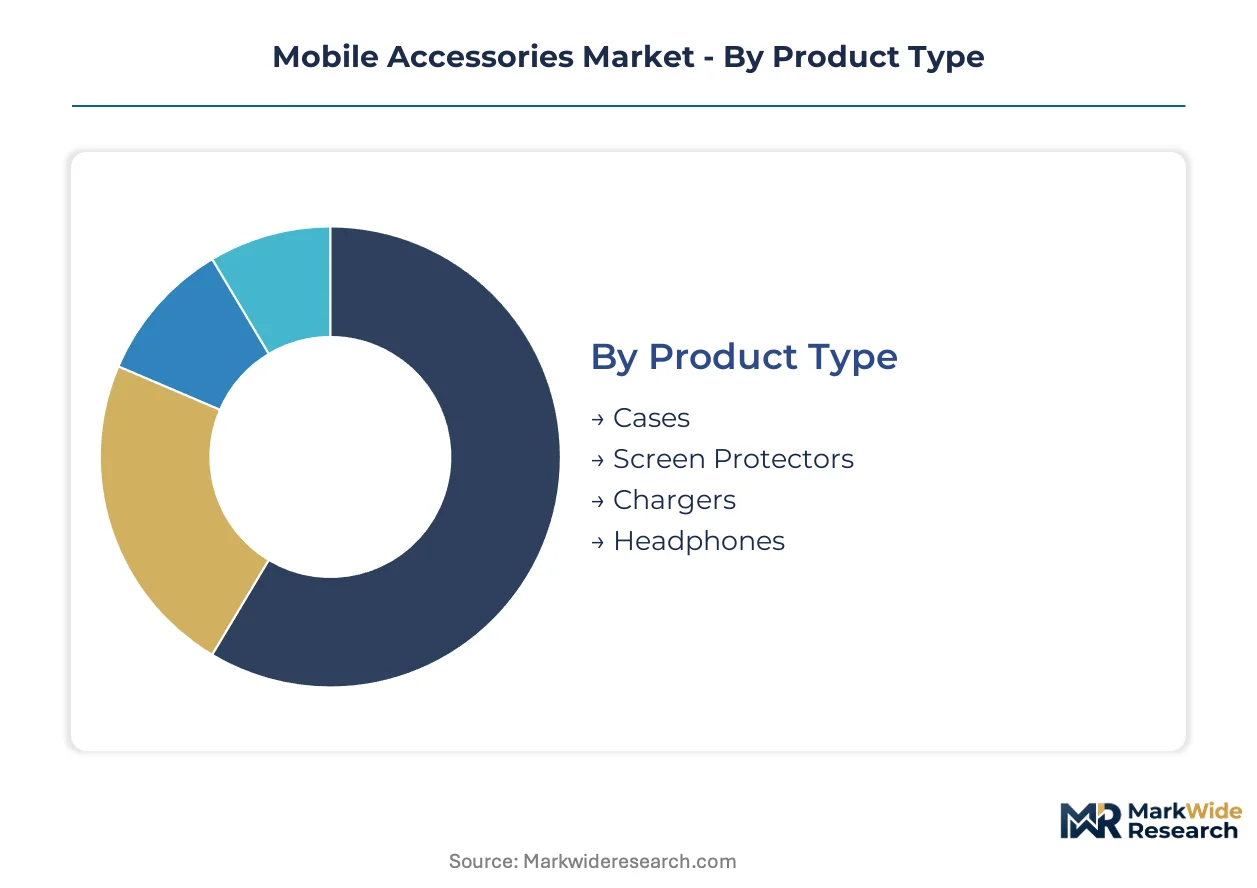
Segmentation within the mobile accessories market illuminates distinct demand patterns and competitive dynamics across various product categories and end-user groups. Understanding these segments is crucial for manufacturers and retailers to tailor product development, pricing strategies, and distribution efforts effectively. This granular view reveals where innovation is most impactful and where market saturation dictates different approaches.
Product Type:
The mobile accessories market balances product standardization with extensive customization across various product types.
- Cases:These protective enclosures, often made from silicone, polycarbonate, or TPU, provide impact absorption and scratch resistance. Demand is concentrating in high-growth smartphone markets like India, driven by the need for device longevity in active consumer environments.
- Chargers:This category includes wall adapters, car chargers, and power banks, increasingly featuring Gallium Nitride (GaN) technology for compact, efficient power delivery. Demand is concentrating within enterprise device programs, where reliable and fast charging for multiple employee-issued devices is a procurement priority.
- Screen Protectors:These transparent layers, typically made from tempered glass or plastic film, shield smartphone and tablet displays from scratches and cracks.
- Headphones:This segment encompasses wired and wireless audio devices, ranging from basic earbuds to high-fidelity over-ear models, often integrating advanced audio processing.
Leading the category by volume: Cases. Growing fastest: Chargers.
End User:
Procurement patterns for mobile accessories vary significantly among different end-user segments.
- Consumers:This segment comprises individual buyers purchasing accessories for personal use, driven by device protection, functional enhancement, and personalization. Demand is concentrating on large online retail platforms, where product variety and competitive pricing influence purchasing decisions.
- Enterprises:Corporate and government entities procure accessories in bulk for employee-issued smartphones and tablets, prioritizing durability, security, and consistent performance. Demand is concentrating in sectors adopting mobile-first work strategies, where device uptime and asset protection are critical.
- Educational Institutions:This segment includes schools and universities purchasing accessories for student and staff devices, often focusing on protective solutions and charging stations.
- Retailers:This category represents businesses that resell mobile accessories, either as standalone products or bundled with device sales, targeting broad consumer access.
The largest share belongs to Consumers, while Enterprises are expanding rapidly.
Material:
Material choices for mobile accessories reflect a tension between durability, cost, and environmental sustainability.
- Plastic:This broad category includes polycarbonate and thermoplastic polyurethane (TPU), valued for its versatility, lightweight properties, and cost-effectiveness in mass production. Demand is strong in the high-volume protective case market, where material properties allow for diverse designs and impact resistance.
- Silicone:Known for its flexibility, soft-touch finish, and shock-absorbing qualities, silicone is frequently used in protective cases and earbud components. Demand is increasing for premium cases and ergonomic audio accessories, where tactile feel and enhanced grip are valued.
- Leather:Utilized for its premium aesthetic and durability, leather is often found in higher-end cases and wallet-style phone accessories.
- Metal:Materials like aluminum and zinc alloys are employed for stands, charging docks, and structural components, offering rigidity and a premium feel.
The most prevalent material is Plastic, with Silicone showing significant innovation.
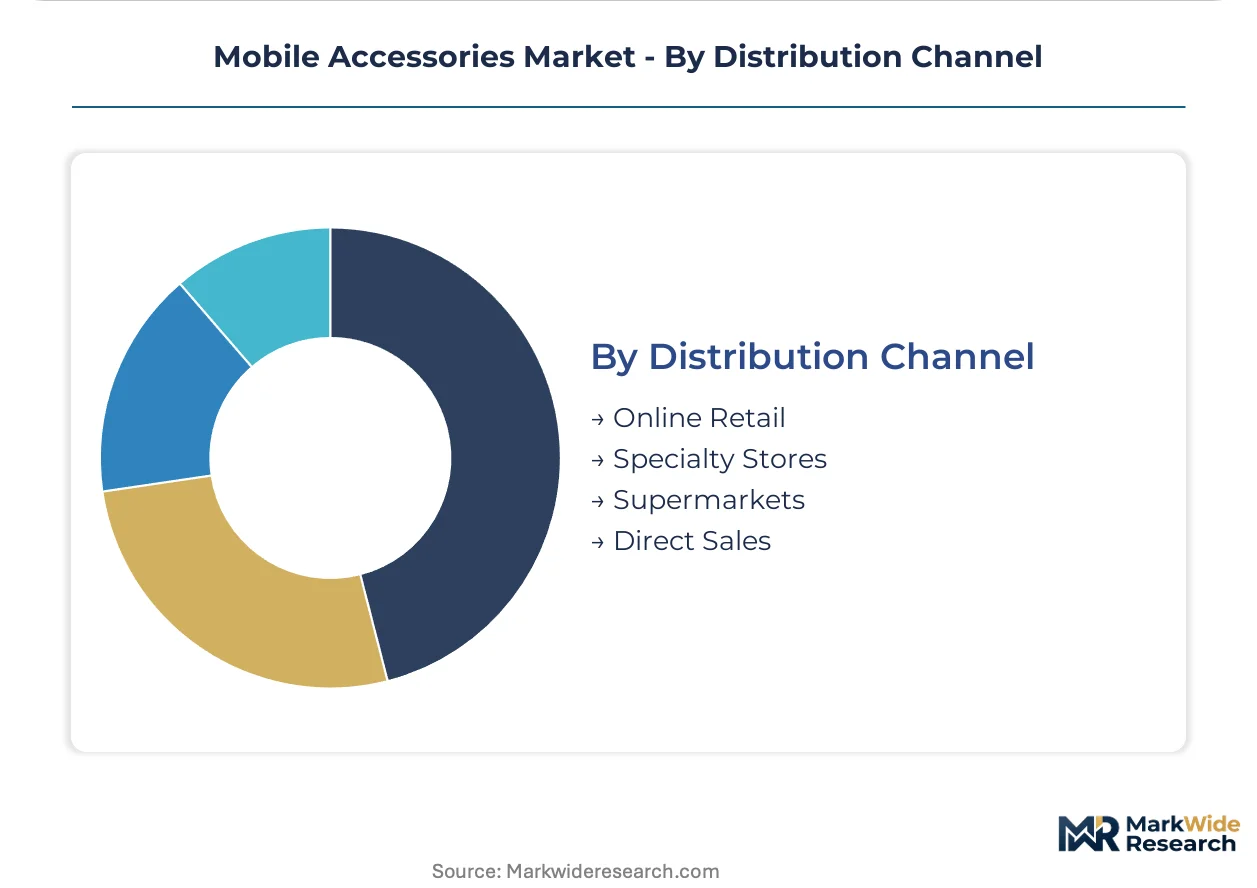
Distribution Channel:
Market access and brand control strategies dictate the prominence of various distribution channels for mobile accessories.
- Online Retail:This channel includes e-commerce giants and direct-to-consumer websites, offering extensive product catalogs and global reach. Demand is concentrated among consumers seeking convenience, competitive pricing, and user reviews before purchase.
- Specialty Stores:Dedicated electronics retailers and brand-specific outlets provide curated selections and expert advice, often catering to premium accessory segments. Demand is strong for high-margin products where customers value in-person product demonstrations and immediate availability.
- Supermarkets:Mass-market retail environments offer basic and impulse-purchase accessories, leveraging high foot traffic for broad consumer exposure.
- Direct Sales:This channel involves manufacturers selling directly to end-users, particularly enterprises, through their own sales teams or dedicated online portals.
Online Retail commands the largest reach, while Specialty Stores maintain strong premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for mobile accessories is prominent in high-growth smartphone markets, notably India, and within developed economies where enterprise adoption and regulatory standardization shape procurement. Regional dynamics are influenced by diverse consumer preferences, technological infrastructure, and varying regulatory landscapes across key geographies.
India
Demand for protective cases and chargers in India is driven by the country's rapidly expanding smartphone user base and the need for device longevity. The Bureau of Indian Standards (BIS) mandates quality and safety certifications for electronic products, ensuring a baseline for market entry. Bengaluru, a major tech hub, exhibits strong demand for advanced accessories that complement new device launches.
Germany
The German market prioritizes premium accessories and eco-friendly materials, reflecting strong consumer environmental consciousness and high disposable income. The EU's USB-C mandate, enforced through CE marking, significantly influences charger and cable design for manufacturers selling into the region. Munich's strong automotive and technology sectors create demand for sophisticated in-car charging solutions and enterprise-grade accessories.
United States
Consumer and enterprise procurement patterns define the United States mobile accessories market, with a strong emphasis on innovation in wireless charging and high-fidelity audio. FCC rules on wireless emissions govern the design and sale of many accessory types, particularly those with advanced connectivity features. Silicon Valley remains a focal point for accessory innovation, attracting R&D investment for new product categories.
China
China's vast domestic market fuels demand for a wide range of mobile accessories, from high-volume protective items to advanced power solutions. Adherence to China's GB safety standards is mandatory for all electronic accessories sold within the country, impacting product development and supply chains. Shenzhen, a global electronics manufacturing hub, drives rapid prototyping and mass production of accessories for both domestic and international brands.
Mobile Accessories Market Key Industry Players
Chinese producers anchor one tier of the mobile accessories market, focusing on high-volume manufacturing and cost efficiency, while European and North American specialists hold positions in premium segments. The market structure exhibits both fragmentation at the entry level and consolidation among established brands that have built strong ecosystems. Strategic archetypes include direct-to-consumer innovators, established brand licensors, and integrated device manufacturers. Companies primarily engage in geographic expansion and portfolio diversification to maintain market relevance.
Among direct-to-consumer innovators, Anker Innovations Limited exemplifies a strategy focused on online market share and agile product development. Belkin International Inc. occupies a position as a premium accessory brand, maintaining strong channel partnerships with major device manufacturers. Samsung Electronics Co. Ltd. sits within the integrated device manufacturer archetype, deeply embedding its accessory ecosystem with its own smartphone and tablet releases.
| Leading Market Players |
|---|
| Belkin International Inc. |
| Sony Corporation |
| Apple Inc. |
| Sennheiser Electronic GmbH & Co. KG |
| Harman International Industries |
| Samsung Electronics Co. Ltd. |
| Bose Corporation |
| Logitech International S.A. |
| Anker Innovations Limited |
| Others |
Cost & Logistics Intelligence
The European Union's USB-C mandate and material recyclability directives gate qualified supply and premium-tier pricing access for mobile accessories. These regulations compel manufacturers to invest in compliant designs, influencing both production costs and market entry strategies.
Pricing Analysis
Volume-driven segments like protective cases operate on tight per-unit transactional margins, while specialized chargers and audio accessories command higher value. Pricing stratifies across premium, standard, and economy tiers, driven by brand premium and certification level, such as CE marking or BIS standards. Pricing pressure stems from the proliferation of counterfeit products and component price volatility. Consumers exhibit high price sensitivity for basic accessories, whereas enterprise buyers prioritize consistent performance and durability, accepting higher costs.
Supply Chain Analysis
Gallium Nitride (GaN) semiconductor supply for compact chargers largely draws from East Asian manufacturers, particularly those in China and Taiwan. The supply chain for mobile accessories concentrates heavily in China, which serves as a global manufacturing hub, alongside increasing contributions from Southeast Asia. Key raw material dependencies include polycarbonate resins, silicone, and advanced semiconductor components for power management ICs. Component price volatility represents a significant structural risk across the supply chain. Distribution runs primarily through large online retail platforms, which offer broad market access and competitive pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile accessories market is a vertical-integration race, with brands pursuing in-house design and manufacturing capabilities to control quality and cost. This allows for deeper integration with device ecosystems and faster response to market changes.
For Market Incumbents: Extend existing channel partnerships with major device manufacturers to secure bundled sales opportunities. Invest in advanced material science for protective accessories to differentiate against low-cost alternatives. Focus R&D efforts on GaN technology to maintain a competitive edge in the fast-charging segment, countering margin erosion from counterfeit products.
For New Entrants and Emerging Players: Underserved enterprise buyers in emerging markets represent a significant white-space opportunity for durable and secure accessories. Target eco-conscious consumers in North American and European retail channels with verifiable sustainability claims. Leverage a direct-to-consumer online sales model to build brand identity around specialized health and wellness audio devices.
For Investors and Strategic Acquirers: The rapid adoption rate of eco-friendly materials in mass-market products is the leading indicator that sustainability is transitioning from niche to mainstream. This market demonstrates long-term viability driven by expanding smartphone penetration and regulatory standardization. Seek out vertically integrated specialists with strong intellectual property in GaN technology or bio-based materials as prime acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: GaN-powered multi-device chargers | This initiative meets consumer demand for compact, efficient charging solutions across multiple devices. |
| Green Certification Program: For accessories made from recycled plastics | This program caters to growing consumer preference for sustainable products and enhances brand perception. |
| Strategic Partnership: With major smartphone OEM for bundled accessories | This partnership secures guaranteed distribution channels and integrates accessories into new device ecosystems. |
| Direct-to-Consumer Launch: For specialized health and wellness audio devices | This launch allows for direct customer engagement and captures higher margins from niche product categories. |
| Manufacturing Footprint Expansion: In high-growth smartphone markets like India | This expansion reduces logistics costs and enables faster market response in rapidly expanding regions. |
Research Approach
Independent corroboration across industry reports, regulatory body publications, and company financial statements underwrites the qualitative findings. Primary interviews with product development leads, supply chain managers, retail buyers, and enterprise procurement officers provided essential insights. Secondary data from the EU Radio Equipment Directive, FCC filings, BIS certifications, and customs data were used for bottom-up and top-down triangulation.
The rate-of-change decomposition framework was applied to project market dynamics over the projection horizon. Segmentation dimensions modeled included product type, end-user, material, distribution channel, and regional smartphone penetration rates. Compound annual growth rates were derived from historical data analysis and projected market dynamics, incorporating key industry-specific forecast inputs like smartphone shipment volumes and regulatory compliance deadlines.
Revisions become necessary when significant shifts in technology adoption or consumer behavior materialize. Forecasts reflect assumptions about market stability and the current regulatory landscape. Geopolitical shifts affecting supply chains or new regulatory mandates could necessitate revisions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Adult Sex Dolls Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Streaming Devices Market