
 Smart Phones Market | 2026-2036
Smart Phones Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Phones Market Intelligence
Gallium nitride is consolidating its position in smartphone power management as silicon-based charging ICs face efficiency ceilings at higher wattages. Samsung leverages in-house semiconductor fabrication to control GaN adapter margins across its flagship lineup. Apple sustains premium positioning through proprietary chip design that locks performance advantages to its ecosystem. Xiaomi competes on cost-engineered GaN implementations that narrow the fast-charging gap with premium rivals.
A smartphone is a handheld computing device integrating a cellular modem, application processor, and capacitive touchscreen within a sealed chassis typically measuring 6.1 to 6.7 inches diagonally, designed for voice communication, mobile internet access, and third-party application execution. Flagship tiers command disproportionate margin pools despite representing minority volume, as camera quality and OLED display specifications drive replacement cycles. Mid-range 5G handsets represent the fastest-expanding technology segment as operators sunset legacy spectrum allocations. Gaming-oriented configurations with enhanced thermal architecture and high-refresh-rate panels occupy a defensible niche with above-average accessory attach rates.
FCC equipment authorization in the US and CE marking under the EU Radio Equipment Directive govern market access and electromagnetic compatibility testing burdens for OEMs. India's BIS compulsory registration order for lithium-ion cells and China's GB standards for charger safety are elevating compliance costs for brands without captive component certification. Stakeholders must monitor how India's PLI scheme and Vietnam's emerging electronics cluster reshape final assembly geography without assuming linear supplier migration timelines.
Market Dynamics
Enterprise mobility adoption is compressing replacement cycles for field-service and logistics workforces, while India's PLI scheme and China's MIIT dual carbon goals are forcibly rerouting component sourcing toward domestic battery and display ecosystems.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic manufacturing are drawing assembly lines away from traditional coastal hubs toward Gujarat and Tamil Nadu corridors.
- 5G spectrum sunsets:Operator decommissioning of legacy bands is forcing fleet refreshes across enterprise mobility programs in logistics and last-mile delivery.
- Gallium nitride charging:Higher-efficiency power ICs are enabling 100W+ fast charging in mid-range handsets without thermal throttling.
Market Restraints
- Lithium-ion cell concentration:China's dominance in cathode and separator production exposes brands to supply disruption from GB standards enforcement and export licensing.
- BIS compulsory registration:India's safety certification for battery cells adds 8-14 week lead times for non-captive suppliers without in-country testing labs.
- OLED panel input costs:Premium display substrates and driver ICs remain concentrated among Korean and Taiwanese foundries, limiting margin compression in mid-tier segments.
Strategic Opportunities
- Vietnam's electronics corridor:Bac Ninh and Bac Giang provinces offer tariff-advantaged assembly capacity for brands diversifying beyond Shenzhen and Dongguan.
- India's tier-two cities:Jaipur, Lucknow, and Indore are generating volume demand as 5G infrastructure reaches secondary urban centers ahead of saturation in metros.
- EU Radio Equipment Directive:Harmonized CE marking requirements are creating a single compliance pathway for refurbished and circular-economy handset programs.
Industry Challenges
- RF engineering talent scarcity:mmWave antenna design and beamforming expertise concentrates among semiconductor vendors, limiting OEM in-house capability.
- Carbon accounting compliance:CSRD and EU Green Deal scope-3 disclosure rules are forcing supply chain visibility investments without standardized measurement protocols.
- Modular repair mandates:France's reparability index and pending EU battery regulation are requiring redesign of sealed chassis and adhesive-bonded display assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Phones Market |
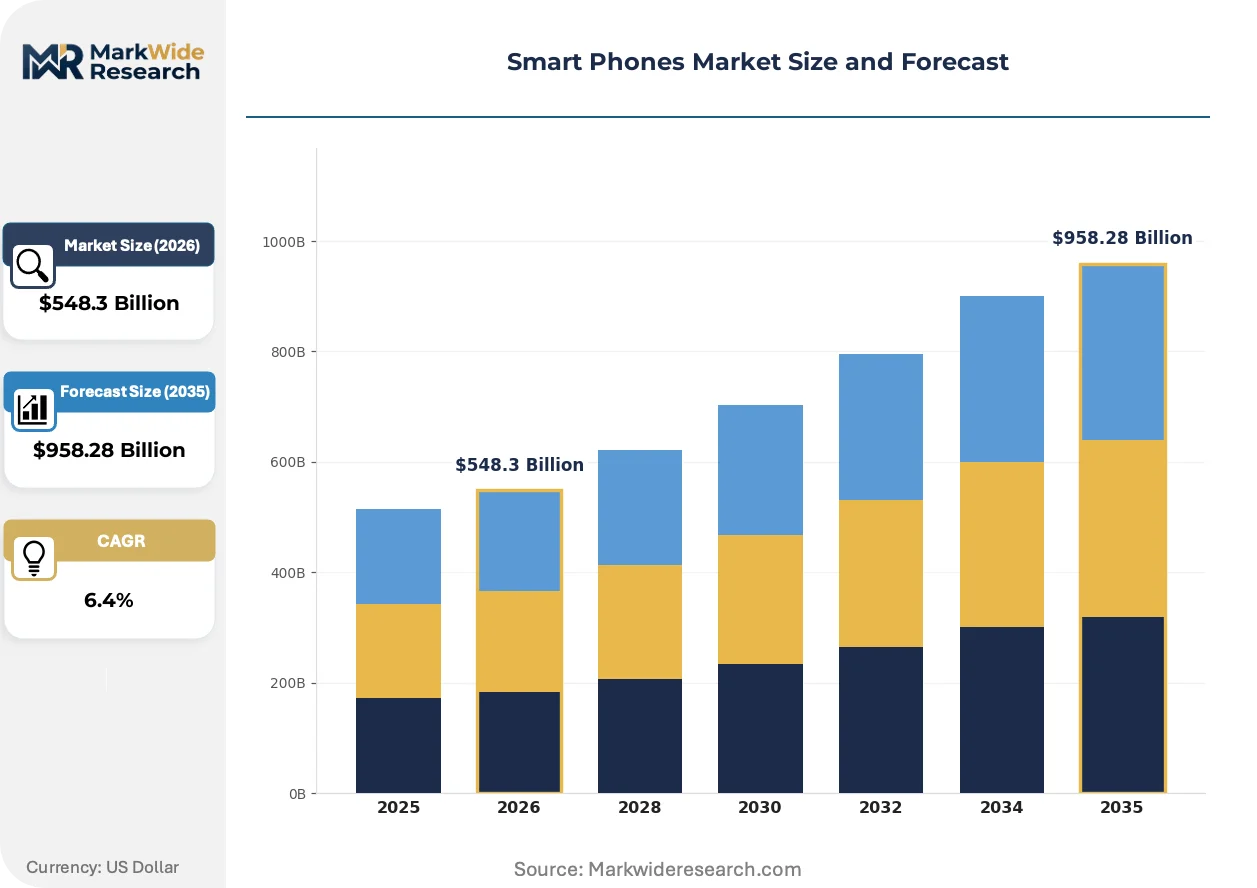
| Market Size in 2026 | $548.3 Billion |
| Market Size in 2035 | $958.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flagship, Mid-range, Budget, Gaming Technology: 5G, 4G LTE, Foldable, OLED Feature: Camera Quality, Battery Life, Storage Capacity, Screen Size End User: Consumers, Businesses, Gamers, Students |
| Companies Covered | Apple, Samsung, Xiaomi, Transsion, Vivo, Oppo, Huawei, Google, OnePlus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Phones Market Strategic Shifts & Innovations
Gallium nitride semiconductors, circular-economy mandates, and enterprise procurement centralization are simultaneously rewriting power architecture, product lifecycle obligations, and channel economics across the handset value chain.
GaN power ICs are rewriting charging subsystem economics by collapsing adapter size and thermal budgets while sustaining 120W+ output. Flagship and gaming-oriented tiers are adopting these chips fastest, with supply concentrating among foundries with compound-semiconductor capability. This compression is enabling fast-charging parity between premium and upper-mid tiers, eroding a historical differentiation axis.
France's reparability index and the EU's pending Ecodesign for Smartphones regulation are mandating spare parts availability and software update timelines. OEMs must now provision seven-year security patches and maintain component inventories, structurally raising post-sale service obligations. Premium vendors with captive service networks are absorbing compliance costs more efficiently than volume brands dependent on third-party repair channels.
Enterprise mobility managers are consolidating procurement through carrier-direct and managed mobility service providers, bypassing traditional retail and distributor channels. Logistics and field-service verticals are driving this concentration, negotiating fleet-level pricing and unified endpoint management. India and Southeast Asia are seeing this shift most acutely, where enterprise 5G rollouts coincide with vendor efforts to reduce channel margin leakage.
Smart Phones Market Segmentation
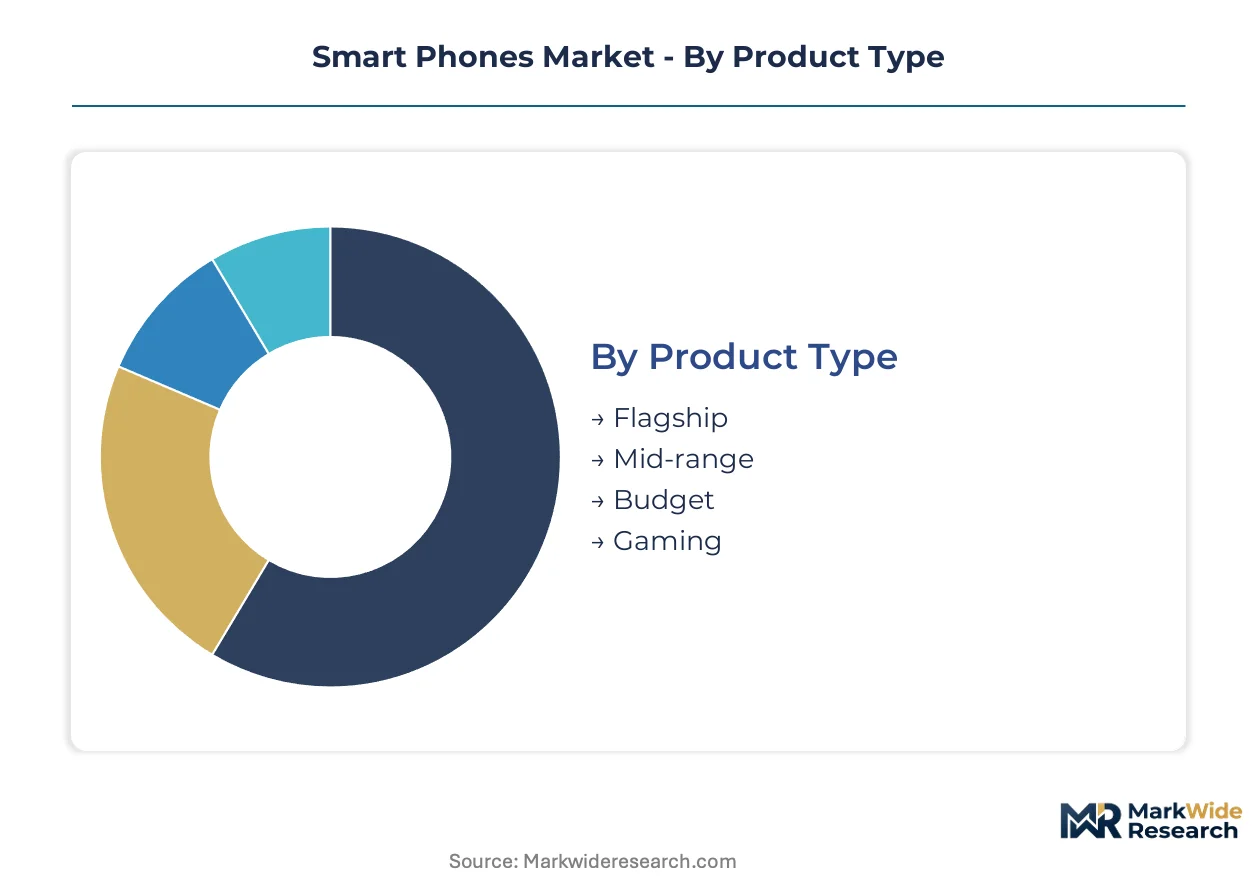
Smartphone segmentation dictates certification pathways, margin architecture, and supply chain configuration across the value chain. Each dimension carries distinct regulatory burdens and procurement patterns that reshape competitive positioning.
Product Type:
Flagship tiers face the heaviest FCC equipment authorization and CE marking electromagnetic compatibility testing loads, while budget segments navigate streamlined self-certification routes in emerging markets.
- Flagship:Premium handsets integrate proprietary application processors and multi-sensor camera arrays with computational photography. Demand concentrates in enterprise mobility refresh cycles across US logistics fleets and Korean corporate procurement, constrained by seven-year software update mandates under France's reparability index.
- Mid-range:Devices balancing 5G connectivity with cost-optimized OLED panels and GaN fast-charging subsystems. India's tier-two cities generate accelerating volume as PLI scheme assembly localization compresses landed costs for domestic brands.
- Budget:Entry-level handsets with 4G LTE modems and LCD displays serving prepaid subscriber bases.
- Gaming:Thermally engineered configurations with vapor chamber cooling and 144Hz refresh rate panels targeting esports participants.
Mid-range sits at the top of the volume ranking, with Gaming climbing the fastest.
Technology:
Technology segmentation determines foundry allocation, RF engineering complexity, and the geographic concentration of component sourcing.
- 5G:Handsets with sub-6GHz and mmWave modem integration requiring sophisticated antenna design and carrier aggregation certification. Enterprise fleet deployments in Vietnam's manufacturing corridors drive demand as operators sunset legacy spectrum.
- 4G LTE:Mature modem platforms serving price-sensitive prepaid markets with reduced certification overhead.
- Foldable:Ultra-thin glass and hinge mechanism assemblies with concentrated yield challenges at Korean display foundries.
- OLED:Flexible substrate panels with integrated fingerprint sensors commanding premium positioning in flagship tiers.
5G dominates absolute shipment volumes, with Foldable expanding most quickly.
Feature:
Feature prioritization varies sharply across procurement contexts, with enterprise buyers weighting durability and manageability against consumer emphasis on imaging and entertainment.
- Camera Quality:Computational photography systems with multi-frame noise reduction and periscope optical zoom. Content creator demand in China's tier-one cities sustains premium pricing despite sensor cost inflation.
- Battery Life:High-density silicon-carbon cells with adaptive refresh rate management. Field-service workforces in India's logistics sector prioritize this dimension for shift-long operational continuity.
- Storage Capacity:UFS 4.0 and expandable microSD configurations for media-intensive users.
- Screen Size:Display diagonal preferences clustering around 6.1-inch compact and 6.7-inch phablet form factors.
Camera Quality leads consumer preference rankings, with Battery Life gaining share fastest among enterprise segments.
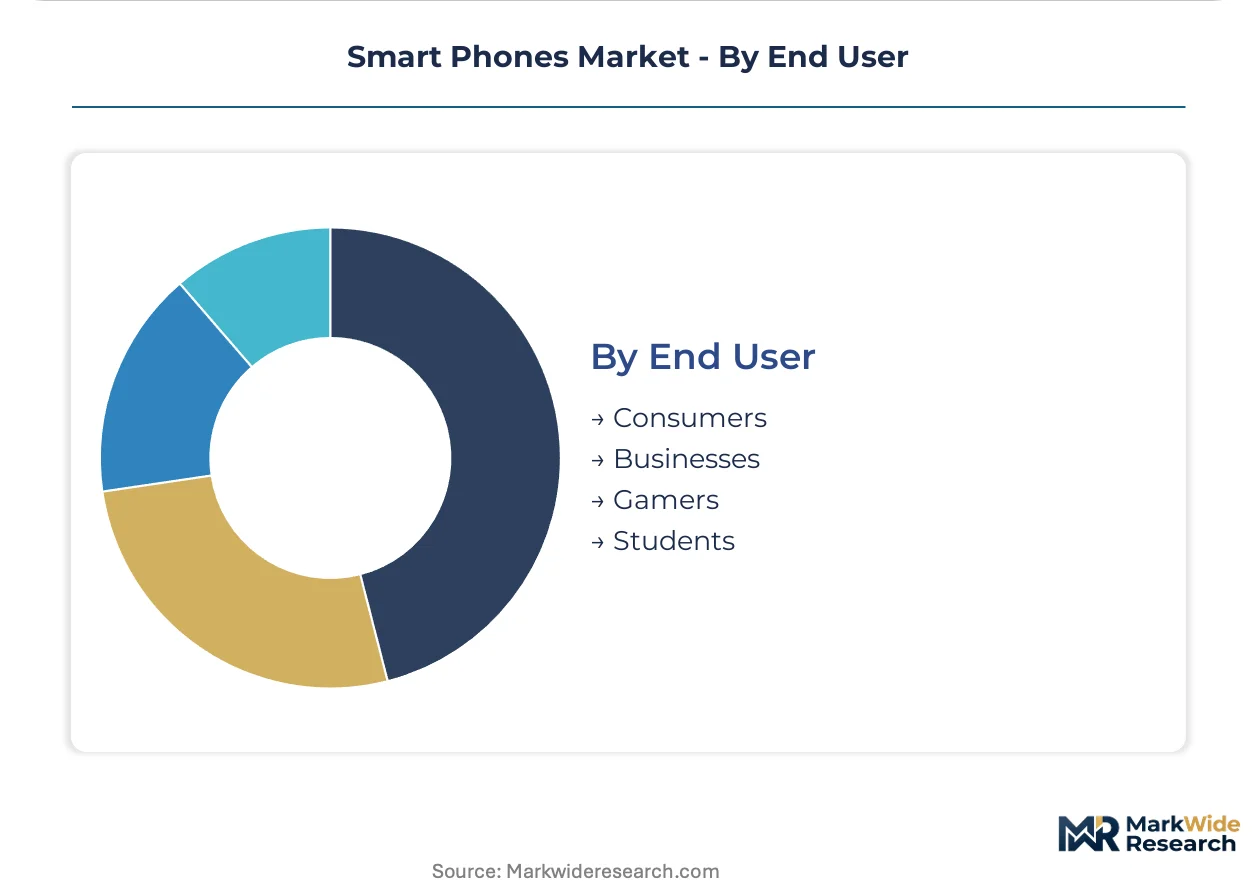
End User:
End user segmentation governs channel economics, with enterprise procurement centralizing through managed mobility providers while consumer sales fragment across retail and direct-to-consumer platforms.
- Consumers:Individual purchasers selecting devices through carrier subsidy programs and unlocked retail channels. Replacement cycles stretch as 5G network maturity reduces perceived upgrade urgency.
- Businesses:Corporate mobility managers negotiating fleet pricing with unified endpoint management integration. India's logistics and last-mile delivery verticals compress replacement cycles through PLI scheme-enabled domestic assembly.
- Gamers:Performance-oriented users prioritizing thermal headroom and haptic feedback precision.
- Students:Cost-conscious segment with strong price elasticity and parental purchase influence.
Consumers anchor volume leadership, with Businesses expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan anchor smartphone manufacturing capacity, though assembly geography is diversifying toward Vietnam's Bac Ninh corridor and India's Tamil Nadu-Gujarat belt under production-linked incentive schemes. Enterprise fleet refreshes and 5G infrastructure rollouts are redirecting demand toward tier-two urban centers across multiple continents.
United States
Enterprise mobility managers in logistics and field-service verticals compress replacement cycles through fleet-level procurement. FCC equipment authorization mandates rigorous electromagnetic compatibility testing for 5G mmWave handsets. Austin and Raleigh-Durham clusters concentrate RF engineering talent for antenna design and beamforming development.
China
MIIT dual carbon goals and GB standards enforcement are rerouting battery and display sourcing toward domestic supply chains. SAMR oversight of charger safety certification elevates compliance costs for brands without captive testing infrastructure. Pearl River Delta manufacturing hubs face margin pressure from carbon accounting disclosures under CSRD-aligned customer requirements.
India
Tier-two cities including Jaipur, Lucknow, and Indore generate accelerating volume as 5G infrastructure reaches secondary urban centers. BIS compulsory registration for lithium-ion cells adds 8-14 week lead times for non-captive suppliers. Tamil Nadu and Gujarat assembly corridors benefit from PLI scheme incentives that draw capacity from traditional coastal hubs.
Vietnam
Bac Ninh and Bac Giang provinces offer tariff-advantaged assembly capacity for brands diversifying beyond Shenzhen. Operator decommissioning of legacy spectrum bands forces enterprise fleet refreshes across manufacturing and logistics verticals. Northern electronics clusters absorb component sourcing shifts as brands reconfigure China-plus-one strategies.
Germany
Industrial procurement centralizes through managed mobility service providers with unified endpoint management integration. EU Radio Equipment Directive harmonization creates compliance pathways for circular-economy handset programs. Bavaria-based automotive and machinery enterprises drive ruggedized device demand for shop-floor and field-service deployments.
Smart Phones Market Key Industry Players
Capacity expansion dominates the current landscape as brands establish parallel assembly footprints in Vietnam and India. The vendor base stratifies across three tiers: integrated semiconductor fabricators controlling GaN adapter margins, volume specialists cost-engineering fast-charging implementations, and ecosystem-locked players sustaining premium positioning through proprietary chip design. Strategic archetypes include captive component producers, PLI scheme beneficiaries, and managed mobility service consolidators. Geographic diversification and vertical integration into battery and display supply chains constitute the dominant competitive moves.
Within the ecosystem-locked tier, Apple and Samsung exemplify divergent approaches to margin architecture. Apple sustains premium positioning through proprietary chip design that locks performance advantages to its ecosystem. Samsung leverages in-house semiconductor fabrication to control GaN adapter margins across its flagship lineup. Among volume specialists, Xiaomi occupies a position defined by cost-engineered GaN implementations that narrow the fast-charging gap with premium rivals.
| Leading Market Players |
|---|
| Apple |
| Samsung |
| Xiaomi |
| Transsion |
| Vivo |
| Oppo |
| Huawei |
| OnePlus |
| Others |
Cost & Logistics Intelligence
Gallium nitride wafer costs cascade through adapter pricing tiers, with Korean foundry premiums compressing margins for mid-range OEMs sourcing from Taiwanese compound-semiconductor suppliers under MIIT dual carbon compliance timelines.
Pricing Analysis
Input-cost pass-through from OLED driver IC shortages concentrates in flagship tiers where Samsung and Apple absorb foundry premiums through captive semiconductor fabrication. Price differentiation hinges on certification grade—CE marking under EU Radio Equipment Directive and FCC equipment authorization elevate testing burdens—and volume scale, with enterprise fleet procurement securing 15-20 point discounts off list. Pricing pressure stems from BIS compulsory registration adding certification overhead for non-captive battery suppliers. Budget segment buyers exhibit highest price sensitivity, while enterprise mobility managers prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, constraining advanced node migration for application processors at Korean and Taiwanese foundries. Lithium-ion cathode materials concentrate in China, South Korea, and Japan, with separator films and electrolyte salts following similar geographic clustering. Raw material dependencies span cobalt from DRC, rare earth elements for RF components, and high-purity silicon substrates. Single-source vulnerability in mmWave antenna modules creates chokepoint exposure as RF engineering talent concentrates among semiconductor vendors. Distribution runs through carrier-direct channels for enterprise segments and retail partnerships for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone market reads as a late-cycle quality story, with enterprise procurement centralization and seven-year software update mandates under France's reparability index shifting demand toward premium durability specifications.
For Market Incumbents: Extend GaN adapter margin control through backward integration into compound-semiconductor foundry partnerships, countering Xiaomi's cost-engineered fast-charging implementations. Fortify against PLI scheme beneficiaries in India's Tamil Nadu corridor by accelerating Gujarat assembly localization. Prioritize captive battery certification under BIS compulsory registration to neutralize 8-14 week lead time disadvantages. For New Entrants and Emerging Players: Enter via Vietnam's Bac Ninh electronics cluster, exploiting tariff-advantaged capacity as brands diversify China-plus-one strategies. Target India's tier-two cities—Jaipur, Lucknow, Indore—where 5G infrastructure rollout precedes metro saturation. Pursue managed mobility service provider partnerships to bypass retail channel margin leakage in enterprise logistics verticals. For Investors and Strategic Acquirers: Consolidation pressure builds where carbon accounting compliance costs under CSRD and EU Green Deal scope-3 disclosure rules outpace mid-tier OEM service network scale. Long-term viability favors vendors with captive component certification and seven-year parts inventory provisioning. Acquisition target archetype: regional assemblers with PLI scheme qualification and underdeveloped enterprise channels. Watch France's reparability index enforcement spread as inflection indicator for post-sale service obligation restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Compound-semiconductor access secures 120W+ charging differentiation against cost-engineered rivals. |
| PLI Scheme Localization | Tamil Nadu and Gujarat assembly qualification unlocks India's tier-two city demand expansion. |
| Seven-Year Parts Inventory | France's reparability index compliance requires structural redesign of sealed chassis supply chains. |
| Enterprise MSP Consolidation | Carrier-direct procurement bypasses retail margin leakage in logistics fleet refreshes. |
| BIS Certification Captivity | In-country testing labs neutralize 8-14 week battery cell registration lead times. |
Research Approach
Bottom-up enterprise fleet modeling reconciled against top-down component supply tracking forms the analytical core. Primary interviews with RF engineering directors, carrier procurement leads, PLI scheme compliance officers, and logistics fleet managers combined with secondary validation through FCC equipment authorization filings, BIS registration databases, MIIT dual carbon policy releases, and customs trade data. Triangulation across foundry capacity announcements and operator spectrum sunset schedules anchors volume projections.
Historical trendline analysis of replacement cycle compression and technology migration patterns informed the projection framework. Segmentation dimensions span product tier, technology generation, end-user archetype, and regional regulatory cluster. CAGRs derive from curve-fitting observed adoption S-cycles against infrastructure deployment timelines. Forecast inputs incorporate GaN penetration rates in charging subsystems and enterprise mobility centralization indices.
Inputs from foundry capacity disclosures and carrier capex guidance were available through the study window; gaps in mmWave antenna yield data and carbon accounting protocol standardization introduce uncertainty bands. Forecasts reflect assumptions on PLI scheme extension timelines and EU Ecodesign for Smartphones regulation finalization. Supply disruption from GB standards enforcement and CSRD scope-3 disclosure implementation costs warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Watch Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Kindle E-Reader Accessories Market