
 Global Office and Contact Center Headset Market | 2026-2036
Global Office and Contact Center Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Global Office and Contact Center Headset Market Foresight
Contact center agent attrition is collapsing institutional knowledge pools and forcing enterprises toward durable, easy-to-deploy audio hardware. EPOS Group A/S leverages its Sennheiser heritage to sustain premium acoustic engineering credibility. Yealink Network Technology Co., Ltd. anchors its position through tight integration with video conferencing platforms. GN Store Nord A/S (Jabra) dominates wireless DECT deployments in European corporate offices.
Office and contact center headsets are electro-acoustic wearable devices engineered for extended vocal communication, typically incorporating 20 Hz–20 kHz frequency response drivers, electret or MEMS microphones, and digital signal processing chipsets for real-time noise suppression. Their primary commercial purpose is to ensure intelligible voice transmission in high-density, acoustically challenging work environments. Wireless headsets now capture the fastest expansion as Bluetooth 5.3 and DECT 6.0 protocols eliminate cable management burdens in flexible floor plans. Wired USB headsets retain margin concentration in security-sensitive financial services and government contracting where air-gapped workstations prevail. Noise cancelling technology separates premium tiers from standard configurations, with active noise reduction algorithms demanding dedicated DSP hardware that elevates bill-of-materials costs.
FCC equipment authorization rules govern radio frequency emissions for wireless headsets sold in the United States, while CE marking under the EU Radio Equipment Directive mandates interoperability and safety testing for European market access. REACH compliance constrains substance selection in ear cushions and headband padding, pushing manufacturers toward silicone and thermoplastic elastomer alternatives. India's BIS certification requirement for imported electronics adds lead time complexity for brands without local assembly. Procurement teams must weigh total cost of ownership against acoustic performance benchmarks as vendor consolidation and platform-specific certification programs reshape supplier shortlists.
Market Dynamics
Cloud-based contact center deployments are collapsing refresh cycles from five-year hardware rotations to eighteen-month upgrade windows, forcing vendors to engineer for rapid obsolescence tolerance rather than decade-long durability.
Growth Catalysts
- Hybrid Work Mandates:United States federal agencies and Fortune 500 enterprises sustain bulk procurement of wireless DECT headsets to equip distributed agent workforces.
- Bluetooth 5.3 Protocol Adoption:Low-latency audio transmission enables seamless handoff between desk phones and softphone applications in open-plan offices.
- India's PLI Scheme:Production-linked incentives for electronics manufacturing attract headset assembly operations, reducing import dependency and landed cost structures.
Market Restraints
- Neodymium Magnet Volatility:Rare earth supply concentration in China's processing infrastructure exposes driver unit costs to export quota fluctuations.
- FCC Equipment Authorization Delays:Radio frequency certification backlogs for new wireless SKUs extend time-to-revenue by four to six months.
- Smartphone Earpod Substitution:Consumer-grade true wireless stereo devices encroach on entry-level enterprise headset deployments in cost-conscious SMB segments.
Strategic Opportunities
- AI-Enhanced Acoustic Analytics:Convergence of voice biometrics and real-time sentiment analysis creates attach-rate potential for sensor-rich premium tiers.
- German Mittelstand Penetration:Mid-sized industrial enterprises remain underpenetrated for unified communications headsets relative to Anglo-American markets.
- EU CSRD Reporting Requirements:Corporate sustainability disclosure mandates drive demand for repairable, modular designs with replaceable batteries and ear cushions.
Industry Challenges
- DSP Firmware Talent Scarcity:Active noise cancellation algorithm development requires scarce acoustic engineering expertise concentrated in Denmark and Japan.
- Legacy PBX Integration Complexity:Analog telephone adapter compatibility testing consumes engineering resources for hybrid telephony environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Office and Contact Center Headset Market |
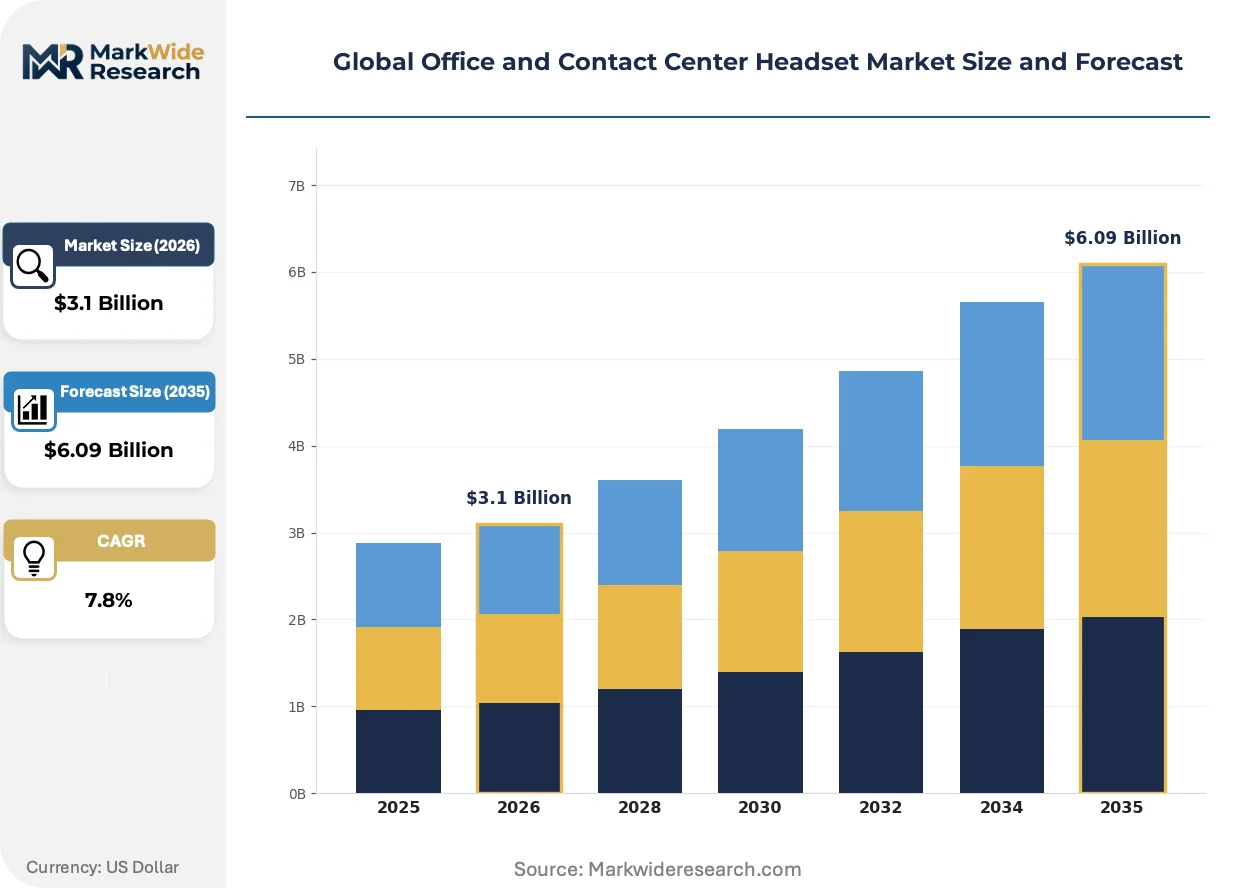
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Headsets, Wireless Headsets, USB Headsets, Bluetooth Headsets, DECT Headsets Technology: Noise Cancelling, Omni-Directional Microphone, Bone Conduction, Active Noise Reduction, Digital Signal Processing Application: Call Centers, Telecommunication, Customer Support, Remote Workstations, Virtual Meetings End User: Corporate Offices, Telemarketing Firms, IT Support Centers, Financial Services, Educational Institutions |
| Companies Covered | EPOS Group A/S, Yealink Network Technology Co., Ltd., Logitech International S.A., Avaya, Audio Technica US Inc., GN Store Nord A/S (Jabra), Sennheiser, Cisco, HP Inc. (Poly), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Office and Contact Center Headset Market Shifts & Advancements
Audio hardware vendors are racing to embed intelligence at the edge, transforming headsets from passive peripherals into computational platforms that preprocess voice data before transmission.
Beamforming microphone arrays with dedicated neural processing units are displacing omnidirectional electret capsules in high-density contact center floors. Financial services and healthcare call centers in Singapore and Switzerland adopt these configurations to satisfy stringent PCI-DSS and HIPAA voice recording requirements. The shift compresses acceptable noise floor specifications from 45 dB to 30 dB, disqualifying legacy designs from premium tenders.
REACH substance restrictions are forcing material transitions across European supply chains. ECHA enforcement of restricted substance lists in ear cushion foams accelerates silicone elastomer adoption, elevating unit costs but unlocking circular economy certification advantages. German automotive contact centers now specify REACH-compliant headsets as mandatory procurement criteria.
Enterprise buyers are consolidating vendor relationships around platform-certified hardware bundles. Microsoft's Teams Device Certification and Zoom's Hardware as a Service program capture procurement preference in United States and United Kingdom markets, marginalizing non-certified alternatives regardless of acoustic performance. This certification-driven consolidation reduces approved vendor lists from twelve to three suppliers in typical RFP processes.
Global Office and Contact Center Headset Market Segmentation
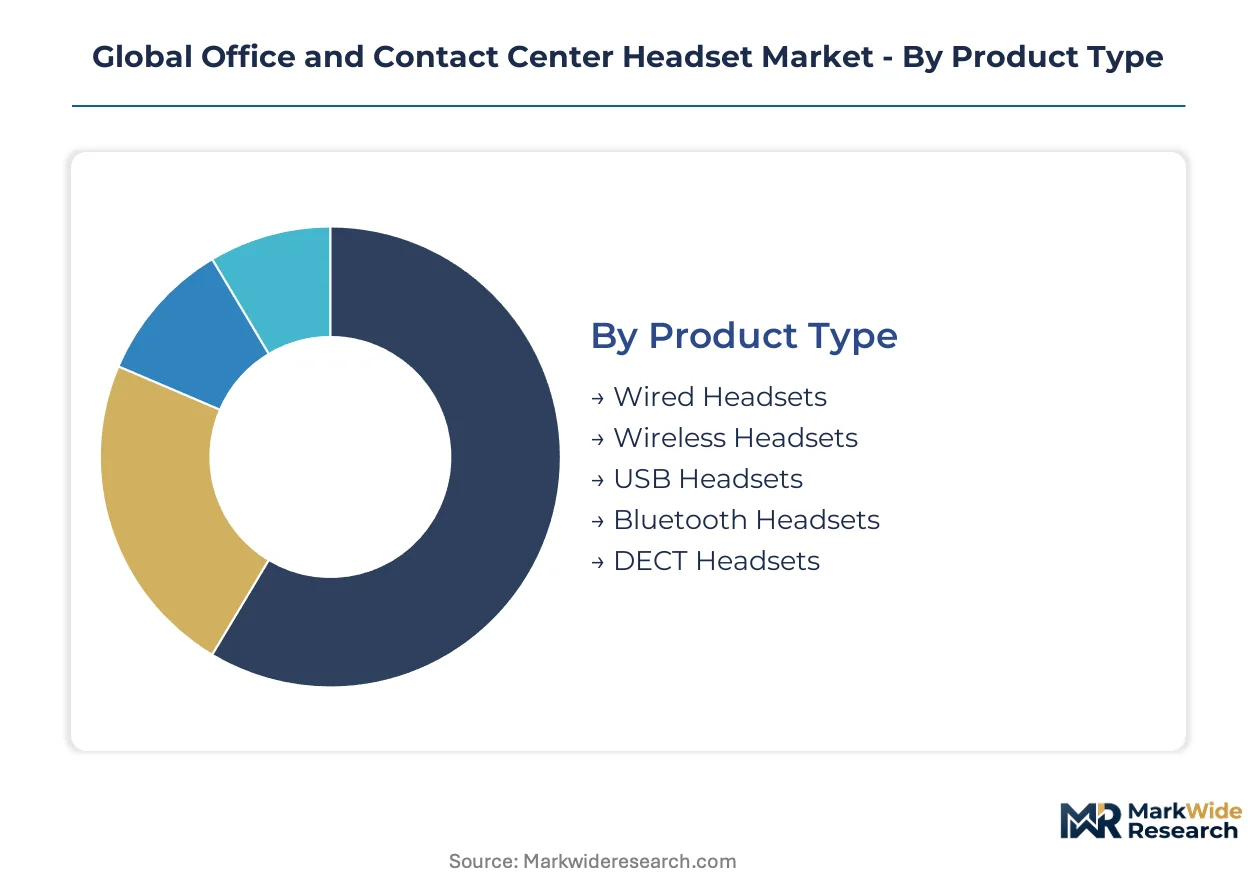
Headset procurement patterns diverge sharply across product architectures, acoustic technologies, deployment contexts, and buyer verticals. Each segmentation axis reveals distinct margin structures, certification requirements, and replacement cycle dynamics that reshape vendor prioritization.
Product Type:
Wired variants dominate domestic procurement in security-sensitive installations, while wireless configurations drive export-led expansion into flexible workforce deployments.
- Wireless Headsets:Bluetooth 5.3 and DECT 6.0 protocols enable seamless mobility between desk phones and softphone applications. United States federal agencies and Fortune 500 enterprises sustain bulk procurement to equip distributed agent workforces under hybrid mandates.
- DECT Headsets:Dedicated spectrum allocation eliminates interference in high-density contact center floors. GN Store Nord A/S anchors European corporate office deployments where building-scale wireless infrastructure demands deterministic latency performance.
- Wired Headsets:Analog and USB connectivity persists in air-gapped financial services workstations where RF emissions face strict prohibition.
- USB Headsets:Plug-and-play compatibility with unified communications platforms dominates rapid deployment scenarios in educational institutions.
- Bluetooth Headsets:Consumer-grade protocol adoption encroaches on entry-level enterprise segments as smartphone earpod functionality improves.
Wireless configurations hold the largest share; momentum sits with DECT variants in regulated European installations.
Technology:
Cost tier separation runs from premium DSP-enabled active cancellation through standard omnidirectional configurations to economy bone conduction alternatives.
- Noise Cancelling:Beamforming microphone arrays with neural processing units preprocess voice data before transmission. Singapore and Switzerland financial services call centers adopt these to satisfy PCI-DSS voice recording requirements with 30 dB noise floor specifications.
- Digital Signal Processing:Dedicated chipsets execute real-time noise suppression algorithms that differentiate premium tiers. Firmware development talent concentrates in Denmark and Japan, constraining supplier expansion.
- Active Noise Reduction:Hybrid feedforward-feedback architectures demand elevated bill-of-materials costs for driver unit integration.
- Omni-Directional Microphone:Electret capsule designs retain position in cost-conscious SMB segments where acoustic isolation is secondary.
- Bone Conduction:Transducer technology bypasses ear canal occlusion for hearing-impaired agents and open-ear situational awareness requirements.
DSP-enabled configurations command premium positioning; noise cancelling arrays are climbing the fastest in high-density contact center tenders.
Application:
Volume concentration clusters in persistent operational environments versus episodic use cases with elongated replacement cycles.
- Call Centers:Agent attrition forces rapid headset refresh to preserve acoustic consistency despite institutional knowledge loss. Cloud-based deployments collapse hardware rotation cycles from five years to eighteen months.
- Remote Workstations:Home office procurement lacks centralized IT management, creating fragmented purchasing authority and support complexity.
- Customer Support:Blended voice and digital channel requirements demand multipoint connectivity for simultaneous device pairing.
- Virtual Meetings:Video conferencing platform certification drives hardware bundling decisions in United States and United Kingdom enterprises.
- Telecommunication:Legacy PBX integration consumes engineering resources for hybrid analog-digital telephony environments.
Call center deployments hold the largest share; remote workstation procurement is gaining share fastest as hybrid policies institutionalize.
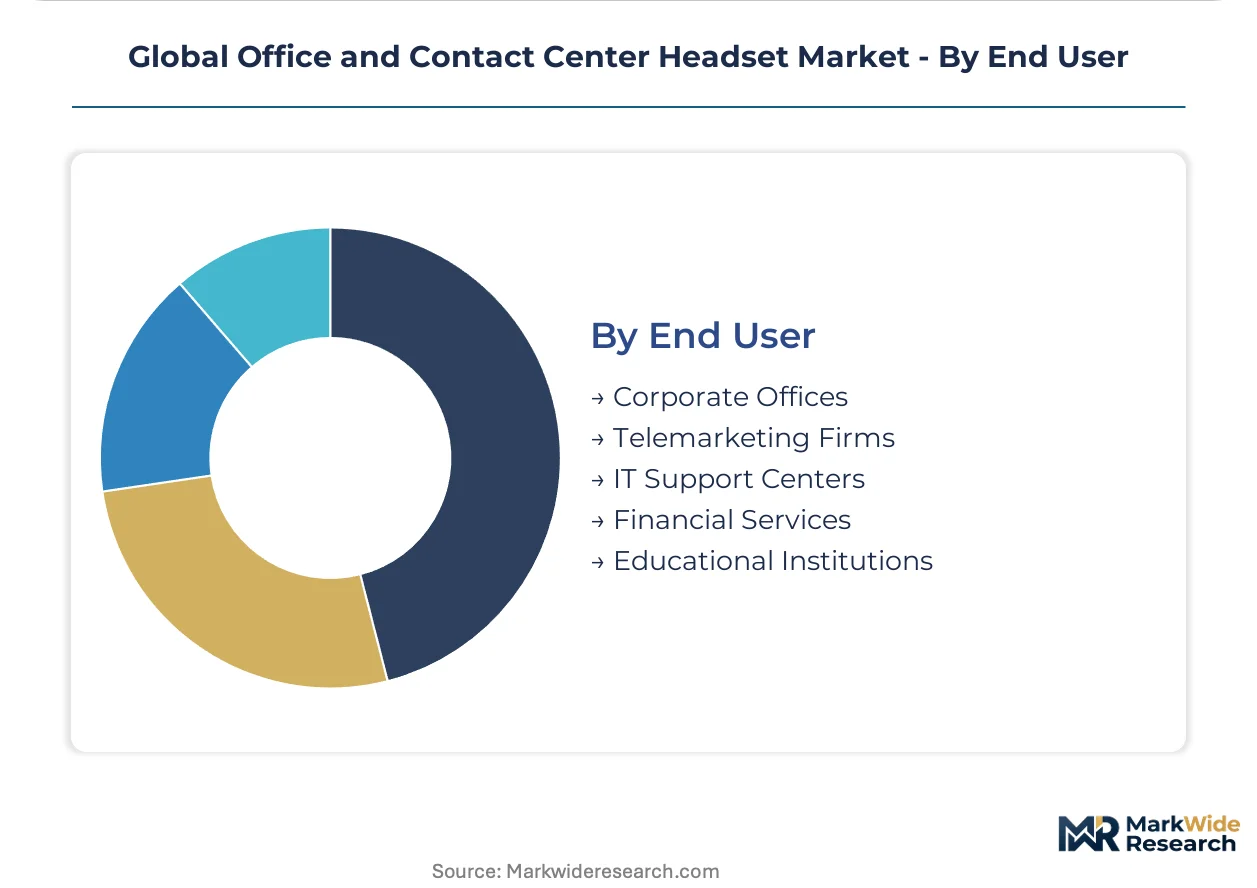
End User:
Customer type determines security certification depth, volume pricing leverage, and replacement cadence predictability.
- Corporate Offices:Platform-certified hardware bundles consolidate vendor relationships around Microsoft Teams Device Certification and Zoom Hardware as a Service programs, compressing approved supplier lists.
- Financial Services:HIPAA and PCI-DSS voice recording mandates specify acoustic performance thresholds that disqualify legacy designs from premium tenders.
- IT Support Centers:Technical user sophistication enables self-service deployment, reducing vendor support cost burdens.
- Telemarketing Firms:High agent turnover and cost pressure drive economy-tier procurement with minimal durability expectations.
- Educational Institutions:Budget-constrained bulk purchasing prioritizes replaceable components over integrated premium designs.
Corporate offices hold the largest share; financial services procurement is expanding most quickly under compliance-driven specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules anchor headset deployment in the United States, while CE marking under the EU Radio Equipment Directive governs European market access. India's BIS certification requirement adds lead time complexity for brands without local assembly operations.
United States
Federal agencies and Fortune 500 enterprises sustain bulk procurement of wireless DECT headsets under hybrid work mandates. FCC equipment authorization backlogs for new wireless SKUs extend time-to-revenue by four to six months. Dallas and Phoenix contact center clusters drive concentrated demand for platform-certified hardware bundles.
Germany
Mid-sized industrial enterprises in the Mittelstand segment remain underpenetrated for unified communications headsets relative to Anglo-American markets. ECHA enforcement of REACH substance restrictions in ear cushion foams accelerates silicone elastomer adoption. Stuttgart and Munich automotive contact centers now specify REACH-compliant headsets as mandatory procurement criteria.
India
Production-linked incentives for electronics manufacturing attract headset assembly operations, reducing import dependency and landed cost structures. BIS certification requirements for imported electronics add complexity for brands without local assembly. Bengaluru and Hyderabad IT support centers drive procurement for self-service deployment scenarios.
Singapore
Financial services and healthcare call centers adopt beamforming microphone arrays to satisfy stringent PCI-DSS and HIPAA voice recording requirements. The Monetary Authority of Singapore enforces operational resilience standards affecting communications infrastructure procurement. Marina Bay financial district contact centers specify 30 dB noise floor thresholds that disqualify legacy designs.
Switzerland
Financial services call centers adopt premium acoustic configurations to satisfy stringent voice recording requirements under banking secrecy frameworks. Swissmedic and FINMA oversight extends to communications infrastructure in healthcare and banking environments. Zurich private banking contact centers drive demand for sensor-rich premium tiers with voice biometric capabilities.
Global Office and Contact Center Headset Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform certification programs consolidating procurement decisions around Microsoft Teams and Zoom hardware ecosystems. The vendor base separates into three strategic archetypes: heritage audio engineering houses with Sennheiser lineage, video conferencing platform integrators, and enterprise IT infrastructure incumbents with unified communications portfolios. Dominant competitive moves include strategic partnerships for platform certification and geographic expansion through India-based assembly operations under PLI scheme incentives.
Among heritage audio engineering specialists, EPOS Group A/S and Sennheiser occupy positions anchored in premium acoustic credibility. Yealink Network Technology Co., Ltd. exemplifies the platform integration archetype through its China-based structure. GN Store Nord A/S (Jabra) represents the wireless infrastructure specialist tier with Danish corporate origins.
| Leading Market Players |
|---|
| EPOS Group A/S |
| Yealink Network Technology Co., Ltd. |
| Logitech International S.A. |
| Avaya |
| Audio Technica US Inc. |
| GN Store Nord A/S (Jabra) |
| Sennheiser |
| Cisco |
| HP Inc. (Poly) |
| Others |
Supply & Pricing Matrix
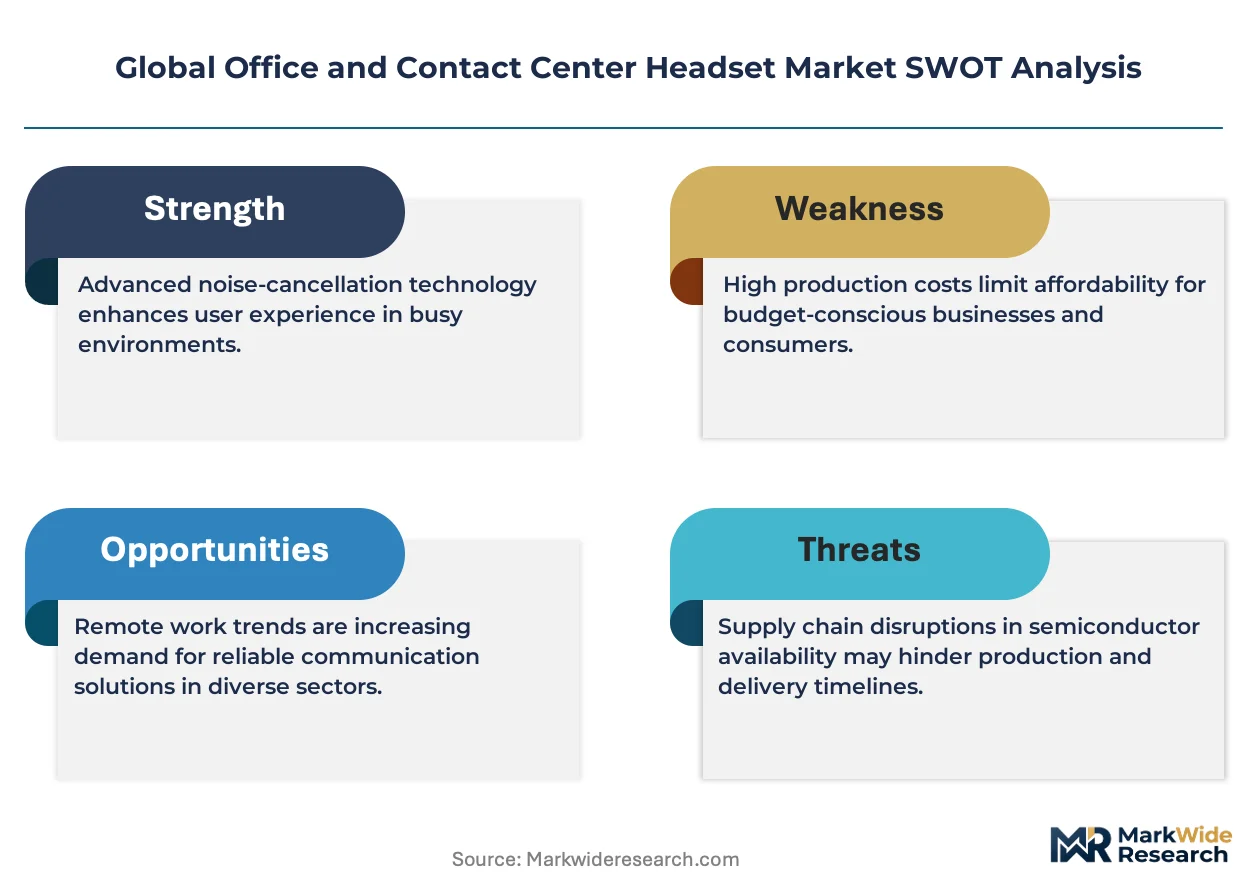
Eighteen-week lead times for FCC-authorized wireless SKUs compress margin buffers and concentrate pricing power among vendors with pre-certified inventory pools in United States distribution centers. This inventory scarcity dynamic elevates procurement costs for enterprise buyers while rewarding suppliers with backward-integrated assembly operations in India under PLI scheme incentives.
Pricing Analysis
United States-Germany price spreads of 15-22% for equivalent DECT configurations reflect divergent certification cost recovery models and VAT treatment. Pricing stratifies across premium DSP-enabled tiers, standard USB configurations, and economy Bluetooth alternatives, with differentiation anchored in Microsoft Teams Device Certification status and active noise cancellation performance. Cost compression in economy tiers intensifies as smartphone earpod functionality encroaches on entry-level enterprise deployments. Telemarketing firms exhibit acute price sensitivity, while financial services buyers prioritize compliance-grade acoustic specifications over unit cost.
Supply Chain Analysis
Days-of-inventory volatility for neodymium magnet stockpiles in Chinese processing facilities transmits directly to driver unit cost instability across assembly operations in Vietnam and Mexico. Rare earth supply concentration in China's infrastructure exposes bill-of-materials to export quota fluctuations, while REACH-compliant silicone elastomer alternatives for ear cushions elevate European-bound unit costs. Single-source vulnerability concentrates in DSP firmware development talent pools anchored in Denmark and Japan. Distribution runs through platform-certified hardware bundles that consolidate procurement decisions around Microsoft and Zoom ecosystem partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where platform certification entrenchment creates switching costs that lock enterprise buyers into approved vendor relationships spanning multi-year refresh cycles.
For Market Incumbents: Compound certification advantages by accelerating India-based assembly expansion under PLI scheme incentives to defend against emerging Chinese platform integrators. Deepen backward integration into DSP firmware development through Danish acoustic engineering talent acquisition, neutralizing the single-source vulnerability that constrains noise cancellation algorithm advancement. For New Entrants and Emerging Players: Differentiate on modular, repairable designs targeting EU CSRD compliance requirements as German Mittelstand enterprises pivot toward sustainability-disclosure-ready procurement. The underpenetrated mid-sized industrial segment in Stuttgart and Munich automotive clusters offers the most penetrable white-space, accessible through direct sales partnerships with unified communications platform resellers. For Investors and Strategic Acquirers: Carve-out targets emerge from heritage audio engineering divisions of diversified electronics conglomerates seeking to monetize non-core acoustic IP portfolios. Long-term viability hinges on voice biometric and sentiment analysis attach-rate expansion in financial services verticals. The signal to monitor is BIS certification simplification for India-assembled products, which would compress landed cost structures and accelerate geographic demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Certification Investment | Microsoft Teams Device Certification locks enterprise procurement into approved vendor shortlists, marginalizing non-certified alternatives regardless of acoustic performance benchmarks. |
| India PLI Assembly Expansion | Production-linked incentives reduce import dependency and compress landed cost structures for brands with Bengaluru or Hyderabad manufacturing footprints. |
| DSP Firmware Talent Acquisition | Danish and Japanese acoustic engineering expertise concentration constrains active noise cancellation algorithm development, creating acquisition premiums for scarce capability pools. |
| REACH-Compliant Material Transition | Silicone elastomer substitution for ear cushion foams unlocks circular economy certification advantages in German automotive contact center procurement mandates. |
| Voice Biometric Feature Integration | Sensor-rich premium tiers with real-time sentiment analysis attach-rate potential satisfy PCI-DSS and HIPAA voice recording requirements in Singapore and Swiss financial services. |
Research Methodology
Desk research of FCC equipment authorization databases, ECHA REACH substance restriction filings, and India PLI scheme beneficiary disclosures preceded structured interviews with contact center operations directors, enterprise IT procurement officers, and acoustic engineering leads at DSP firmware developers. Secondary validation drew from hyperscaler unified communications platform certification program documentation, customs import records for neodymium magnet flows, and hospital GPO contracts for healthcare call center infrastructure. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across product architecture, acoustic technology, deployment context, and buyer vertical dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within wireless DECT, Bluetooth 5.3, and wired USB configurations. Segmentation modeling incorporates connectivity protocol, noise cancellation technology tier, application intensity, and end-user security certification depth. CAGR derivation rests on cloud contact center deployment velocity, hybrid work policy institutionalization, and platform ecosystem consolidation trajectories. Industry-specific forecast inputs include agent attrition rates affecting refresh cycle compression and REACH enforcement timelines driving material substitution cost pass-through.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration, stable rare earth export policy, and platform certification program continuity would require recalibration. Forecasts reflect documented assumptions regarding FCC authorization backlog resolution and PLI scheme incentive persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Vape Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
North America Smartphone Accessories Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Sports Electronics Market