
 Streaming Devices Market | 2026-2036
Streaming Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Streaming Devices Market Analysis
CE marking under the EU Radio Equipment Directive is rotating toward stricter cybersecurity and spectrum efficiency requirements, filtering which manufacturers can serve European channels. Amazon.com, Inc. leverages its Prime ecosystem to lock in recurring content consumption through Fire TV devices. Roku, Inc. anchors the mid-tier segment in North America with an advertising-supported platform model. Apple, Inc. differentiates through proprietary silicon and tight integration with its services stack.
Streaming devices are dedicated hardware endpoints that decode digital video and audio streams over IP networks, typically supporting resolutions up to 4K with HDR10 or Dolby Vision output and HDMI 2.1 connectivity for consumer display integration. Their primary commercial purpose is to bridge broadband-delivered content to television displays without requiring operator-supplied set-top infrastructure. Streaming sticks lead household adoption due to minimal cost and plug-and-form-factor portability, while set-top boxes retain commercial space deployments where managed service reliability commands priority. Smart TVs with embedded streaming platforms are absorbing standalone device demand in premium residential segments, compressing margin pools for discrete media players.
The FCC equipment authorization process governs RF emissions for Wi-Fi and Bluetooth radios in US-bound devices, while the EU Radio Equipment Directive mandates interoperability and security baselines for CE-marked products entering European distribution. India's BIS compulsory registration order now covers wireless streaming hardware, adding a compliance gate for volume manufacturers targeting that market. Stakeholders must monitor whether fragmentation across national certification regimes begins to favor regional specialists over global platform operators.
Market Dynamics
Smart TV platforms are absorbing standalone streaming hardware demand in premium residential segments, compressing margin pools for discrete media players and forcing repositioning toward hospitality and commercial deployments.
Growth Catalysts
- Broadband Infrastructure Upgrades:Fiber-to-the-home rollouts in the United States and fiber densification in Germany expand addressable households for 4K and 8K streaming endpoints.
- Cord-Cutting Behavior:Subscriber losses among traditional pay-TV operators in Canada and Australia accelerate replacement demand for IP-based content delivery hardware.
- Hospitality In-Room Entertainment:North American and European hotel chains deploy managed streaming solutions to differentiate guest experiences and reduce legacy coaxial infrastructure maintenance.
Market Restraints
- Semiconductor Supply Concentration:Advanced SoC fabrication for HDR10+ and Dolby Vision decoding concentrates among Taiwanese foundries, exposing volume manufacturers to allocation volatility.
- Platform Licensing Costs:Operating system royalties for certified Android TV and Roku OS deployments erode hardware margins at sub-$50 retail price points.
- Embedded Substitution:Smart TVs from Samsung Electronics and LG Electronics with proprietary streaming stacks displace attach rates for external streaming sticks in replacement cycles.
Strategic Opportunities
- India Market Entry:BIS compulsory registration order enforcement creates compliance gates that favor established manufacturers with certification infrastructure over gray-market imports.
- Healthcare Display Integration:Streaming endpoints for patient entertainment systems in US hospital networks represent an underpenetrated vertical with managed service reliability requirements.
- Matter Protocol Convergence:Thread and Zigbee integration with streaming hardware enables unified smart home control, differentiating premium tier products in North American retail.
Industry Challenges
- RF Certification Timelines:FCC equipment authorization and EU Radio Equipment Directive testing queues extend hardware launch schedules by 4-8 months for Wi-Fi 6E and Bluetooth 5.3 implementations.
- Legacy Hospitality Infrastructure:Property management system integration with proprietary coaxial networks in aged hotel stock requires custom engineering that fragments deployment economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Streaming Devices Market |
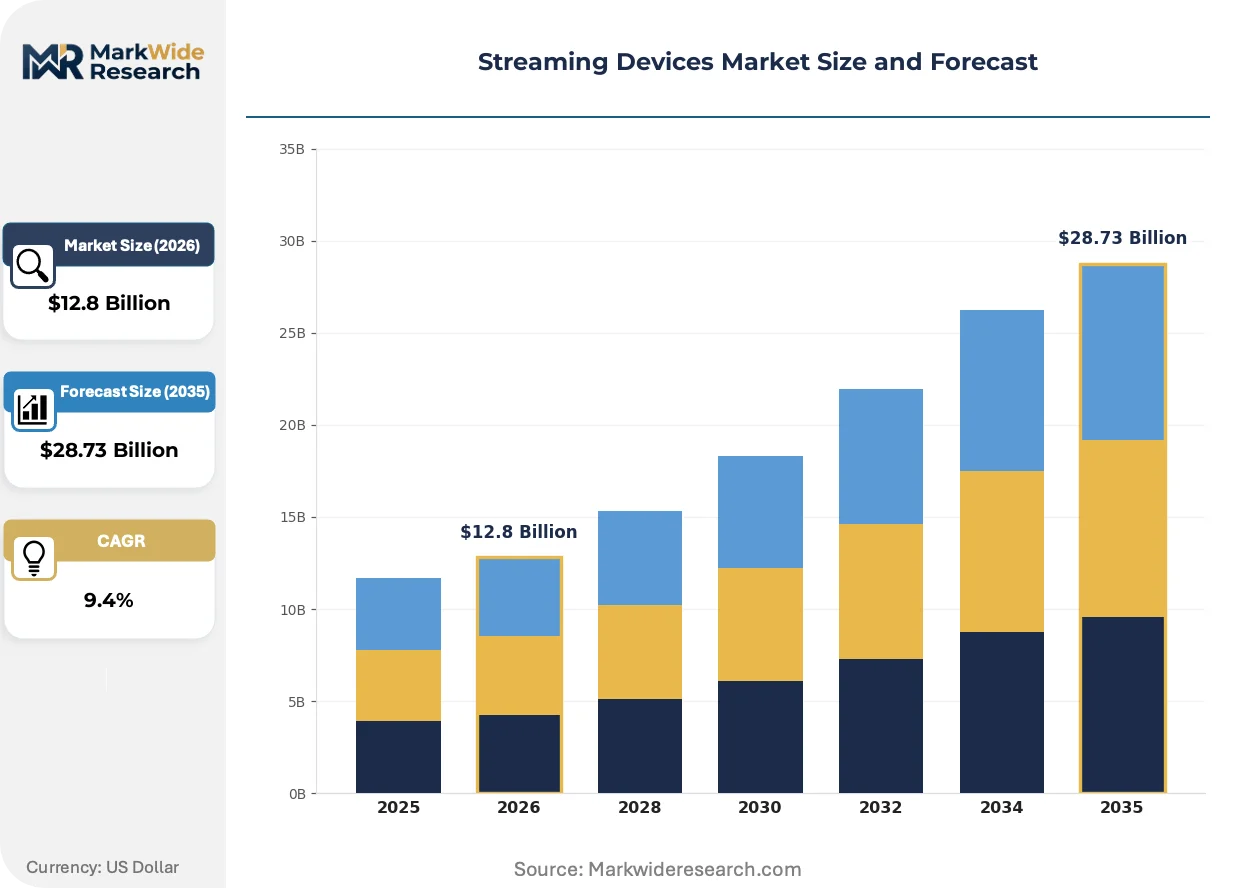
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Set-Top Boxes, Smart TVs, Streaming Sticks, Media Players Technology: Wi-Fi, Ethernet, Bluetooth, HDMI End User: Households, Commercial Spaces, Educational Institutions, Hospitality Distribution Channel: Online Retail, Direct Sales, Electronics Stores, Wholesale |
| Companies Covered | Amazon.com, Inc., Roku, Inc., Apple, Inc., Google, Inc., Sony Corporation, Nvidia Corporation, Xiaomi Corporation, Humax Holdings Co., Ltd., Philips Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Streaming Devices Market Emerging Trajectories
Codec efficiency improvements and regulatory cybersecurity mandates are reshaping hardware design priorities while distribution channels bifurcate between retail consumer and managed commercial procurement.
AV1 hardware decoding is fragmenting the premium streaming device tier as chip vendors integrate royalty-free codec support to reduce streaming platform bandwidth costs. Netflix and YouTube encode substantial catalogs in AV1, accelerating adoption among bandwidth-constrained households. This codec transition is fragmenting the decoder silicon supply base, compressing HEVC licensing revenue pools while enabling new entrants without patent pool obligations.
EU Radio Equipment Directive cybersecurity requirements are tightening CE marking standards for connected hardware entering European distribution. Manufacturers must demonstrate secure boot capabilities and vulnerability disclosure processes to maintain market access. Streaming device vendors targeting Germany, France, and Italy are redesigning firmware architectures to satisfy these mandates ahead of enforcement deadlines.
Enterprise procurement through managed service providers is displacing direct retail purchasing in hospitality and healthcare verticals. Property technology integrators bundle streaming hardware with content licensing and network management, capturing lifecycle value that hardware vendors previously accessed through replacement cycles. This channel shift concentrates most visibly in the United States, where REIT-owned hotel portfolios standardize technology stacks across properties.
Streaming Devices Market Segmentation
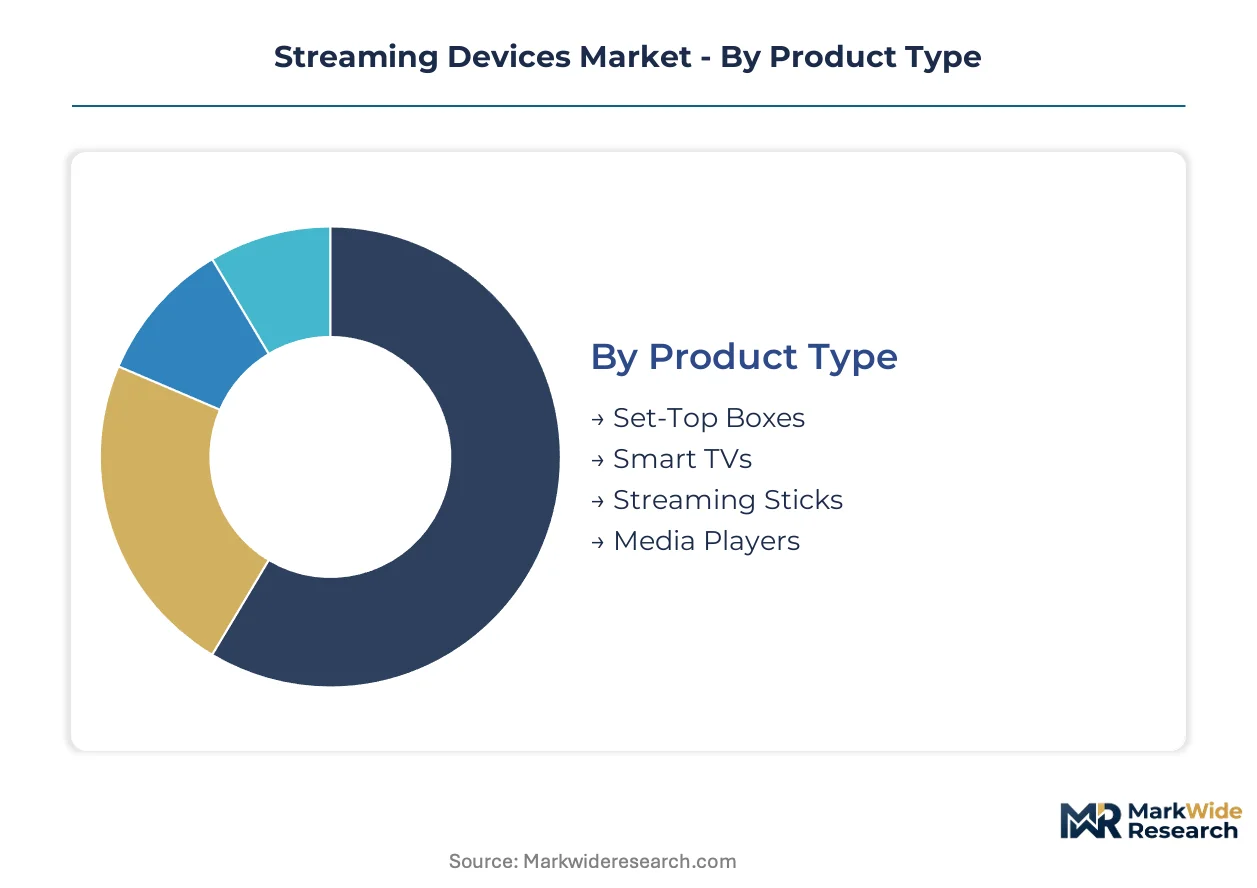
Streaming devices fragment across hardware form factors, connectivity protocols, and procurement channels that face diverging substitution pressures from embedded smart TV platforms and managed service bundling. Understanding these segment boundaries clarifies where standalone hardware retains pricing power versus where margin compression accelerates.
Product Type:
Smart TV platforms are absorbing demand for external streaming hardware in premium residential segments, compressing attach rates for discrete devices while hospitality and commercial deployments preserve standalone form factors.
- Set-Top Boxes:Purpose-built enclosures with advanced thermal management and managed firmware update capabilities serve hospitality chains and healthcare networks where service reliability commands priority. Demand concentrates in North American hotel portfolios controlled by REITs standardizing property technology stacks across hundreds of locations.
- Streaming Sticks:Compact HDMI dongles with integrated Wi-Fi radios and minimal power draw dominate household adoption through sub-fifty-dollar retail positioning and plug-and-play portability. United States cord-cutting households drive replacement cycles as legacy pay-TV subscriptions terminate.
- Smart TVs:Display-integrated streaming platforms from Samsung Electronics and LG Electronics with proprietary silicon and content ecosystems.
- Media Players:Premium-tier boxes targeting home theater enthusiasts with Dolby Vision output and lossless audio passthrough.
Streaming sticks anchor the volume base while set-top boxes gain share at the steepest rate through hospitality vertical expansion.
Technology:
Connectivity specifications stratify across cost tiers, with wireless implementations dominating consumer retail and wired protocols retaining commercial preference for bandwidth stability.
- Wi-Fi:Dual-band and Wi-Fi 6E implementations enable 4K HDR streaming without Ethernet infrastructure, though RF certification timelines extend hardware launch schedules. United States broadband infrastructure upgrades expand addressable households for wireless-first devices.
- HDMI:Version 2.1 ports with 48Gbps bandwidth and eARC support differentiate premium hardware for 8K readiness and advanced audio return channel functionality. Gaming console integration and home theater receiver compatibility sustain demand concentration.
- Ethernet:Gigabit wired connectivity for commercial deployments requiring deterministic latency and managed QoS policies.
- Bluetooth:Low-energy implementations for remote control pairing and audio accessory connectivity.
Wi-Fi carries the highest shipment volumes while HDMI specification upgrades command the steepest expansion trajectory through display refresh rate advancement.
End User:
Procurement authority separates consumer discretionary purchases from enterprise managed service contracts with diverging lifecycle and support requirements.
- Households:Individual consumers selecting hardware through retail channels based on content ecosystem lock-in and price positioning. Cord-cutting behavior in Canada and Australia accelerates replacement demand as traditional pay-TV subscriber losses mount.
- Hospitality:Hotel chains deploying in-room entertainment solutions to differentiate guest experiences and reduce legacy coaxial infrastructure maintenance costs. North American and European property portfolios standardize streaming hardware across hundreds of locations.
- Commercial Spaces:Corporate lobbies, retail environments, and fitness centers requiring digital signage and background content delivery.
- Educational Institutions:Universities and K-12 districts provisioning classroom and dormitory streaming access.
Households dominate absolute unit demand while hospitality represents the steepest expansion trajectory through property technology modernization cycles.
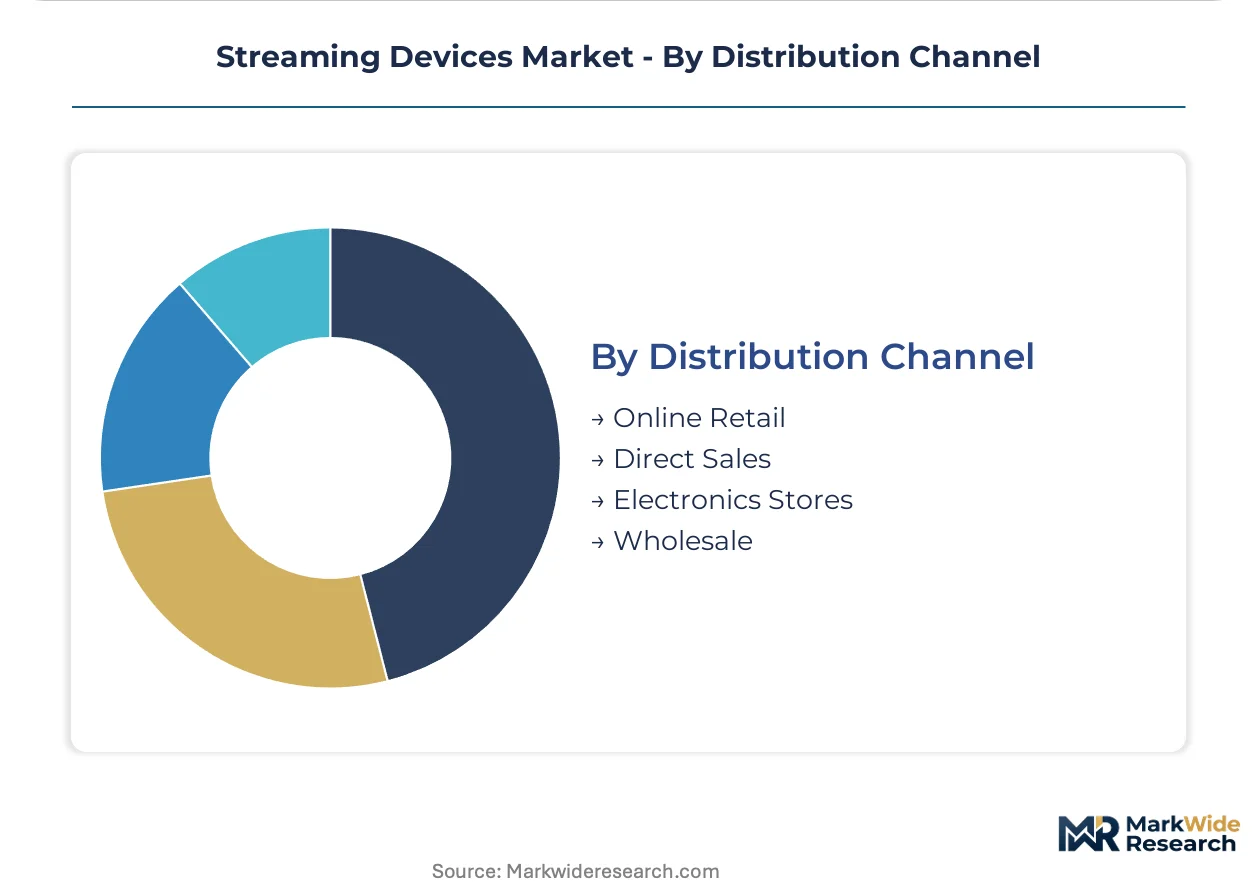
Distribution Channel:
Channel structure bifurcates between high-velocity retail and relationship-driven commercial procurement with fundamentally different margin and working capital profiles.
- Online Retail:Amazon.com marketplace and direct-to-consumer storefronts capture household demand through algorithmic recommendation engines and Prime ecosystem bundling. Fire TV device integration with Amazon's subscription services reinforces platform lock-in.
- Direct Sales:Enterprise procurement teams at hospitality chains and healthcare networks negotiate volume agreements with manufacturers and managed service providers. Property technology integrators bundle hardware with content licensing and network management.
- Electronics Stores:Best Buy and similar retailers providing hands-on product demonstration and immediate fulfillment.
- Wholesale:Distributor networks serving regional installers and smaller commercial accounts without direct manufacturer relationships.
Online retail anchors household volume while direct sales expand most quickly through hospitality vertical procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules and the EU Radio Equipment Directive are tightening electromagnetic compatibility standards, while India's BIS compulsory registration order adds compliance gates for volume manufacturers targeting emerging markets.
United States
Broadband infrastructure upgrades and cord-cutting behavior drive household replacement cycles for IP-based content delivery hardware. FCC equipment authorization governs RF emissions for Wi-Fi and Bluetooth radios in US-bound devices. Silicon Valley and Austin clusters concentrate streaming platform headquarters and semiconductor design operations.
Germany
Fiber densification expands addressable households for 4K and 8K streaming endpoints in residential segments. CE marking under the EU Radio Equipment Directive mandates interoperability and security baselines for products entering European distribution. Munich and Berlin host major electronics retailers and property technology integrators serving hospitality verticals.
India
Streaming hardware demand concentrates in urban households with improving broadband penetration and over-the-top content consumption growth. BIS compulsory registration order now covers wireless streaming hardware, filtering gray-market imports. Bangalore and Delhi-NCR clusters concentrate domestic electronics assembly and certification infrastructure.
United Kingdom
Cord-cutting acceleration among traditional pay-TV subscribers generates replacement demand for streaming endpoints. UKCA marking requirements align with post-Brexit regulatory divergence from EU CE standards. London anchors commercial procurement for hospitality chains standardizing in-room entertainment across European property portfolios.
Japan
High-resolution display adoption and gaming console integration sustain demand for premium-tier media players with advanced HDMI specifications. METI oversees radio equipment compliance and spectrum allocation for connected devices. Tokyo and Osaka metropolitan areas concentrate consumer electronics retail and semiconductor distribution networks.
Streaming Devices Market Vendor Landscape
Player mix skews toward platform-integrated technology conglomerates with content ecosystem lock-in capabilities. Market structure concentrates around three to five dominant operators controlling hardware-software integration and advertising-supported revenue models. Strategic archetypes include ecosystem-locked platform operators, advertising-first mid-tier specialists, and premium-tier integrated device manufacturers. Competitive moves center on content licensing exclusivity and hospitality vertical penetration through managed service bundling.
Within the ecosystem-locked tier, Amazon.com, Inc. and Apple, Inc. anchor platform strategies that merge hardware distribution with recurring content consumption. Roku, Inc. occupies a position exemplifying advertising-supported mid-tier positioning in North American retail channels. These three entities represent divergent approaches to hardware monetization—subscription bundling, premium device margins, and advertising revenue share—illustrating how competitive positioning fragments across revenue model selection rather than pure hardware specification differentiation.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Roku, Inc. |
| Apple, Inc. |
| Google, Inc. |
| Sony Corporation |
| Nvidia Corporation |
| Xiaomi Corporation |
| Humax Holdings Co., Ltd. |
| Philips Electronics |
| Others |
Supply Flow & Price Mechanics
Foundry-scale economies in Taiwan concentrate advanced SoC fabrication for HDR-capable decoders, compressing hardware margins at sub-fifty-dollar retail tiers while elevating pricing power for managed-service set-top deployments in hospitality verticals.
Pricing Analysis
Certification level under FCC equipment authorization and EU Radio Equipment Directive creates the primary spread between consumer retail and commercial procurement tiers. Three-tier pricing structure across premium, standard, and economy levels segments by connectivity specification and managed firmware capability. Cost compression in streaming sticks intensifies because platform licensing royalties for Android TV and Roku OS erode already thin hardware margins. Household consumers through online retail channels exhibit highest price sensitivity, while hospitality procurement teams negotiating direct volume agreements demonstrate lowest sensitivity due to lifecycle service bundling.
Supply Chain Analysis
Inventory cycles for Wi-Fi 6E and Bluetooth 5.3 RF modules extend hardware launch schedules by four to eight months as FCC and EU testing queues accumulate. Advanced SoC fabrication concentrates in Taiwan, with secondary capacity in South Korea and the United States. Silicon supply draws from semiconductor foundries, DRAM suppliers, and passive component manufacturers. Single-source vulnerability in Taiwanese foundry capacity exposes volume manufacturers to allocation volatility during demand surges. Distribution runs through managed service providers in hospitality and healthcare verticals alongside high-velocity online retail for household segments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Matter protocol convergence and embedded smart TV substitution are redistributing value capture between hardware vendors and ecosystem operators.
For Market Incumbents: Secure hospitality vertical relationships through managed service bundling before property technology integrators consolidate procurement authority across REIT-owned portfolios. Deepen backward integration into proprietary silicon design to escape Android TV and Roku OS royalty structures compressing margins at entry price tiers. Lock in certification infrastructure for India's BIS compulsory registration order to filter gray-market competition.
For New Entrants and Emerging Players: Anchor in healthcare patient entertainment systems where managed service reliability requirements and underpenetrated vertical status offer white-space expansion. Target US hospital networks seeking streaming endpoint integration with legacy nurse call infrastructure. Pursue direct sales channel development through property technology integrators rather than competing for saturated retail shelf space.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated operators with content ecosystem lock-in and advertising-supported monetization models. Long-term viability over the next decade favors entities controlling hardware-software integration rather than discrete component suppliers facing embedded substitution. Monitor AV1 codec hardware decoding adoption as an inflection signal for decoder silicon supply base fragmentation and new entrant viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Fire TV and Roku OS licensing reinforce ecosystem lock-in and recurring content consumption. |
| Vertical Penetration | Hospitality managed service bundling captures lifecycle value from REIT portfolio standardization. |
| Certification Investment | BIS registration infrastructure filters gray-market imports in India's expanding addressable base. |
| Silicon Differentiation | Proprietary chip design escapes Android TV royalty structures eroding hardware margins. |
| Protocol Convergence | Matter and Thread integration enables unified smart home control in premium North American retail. |
Methodological Framework
A spread of perspectives from streaming platform executives, hospitality technology integrators, semiconductor procurement leads, and FCC regulatory consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings, customs trade data, FCC equipment authorization databases, and EU Radio Equipment Directive implementation guidance. Bottom-up shipment modeling and top-down ecosystem revenue estimates were triangulated against broadband infrastructure deployment data and cord-cutting subscriber metrics.
Segmentation dimensions modeled include hardware form factor, connectivity protocol specification, procurement channel structure, and end-use vertical across the analysis window. CAGRs were derived from installed base replacement cycles, hospitality property technology modernization timelines, and smart TV substitution elasticity coefficients. Forecast inputs incorporated fiber-to-the-home rollout schedules, AV1 codec hardware adoption curves, and regional regulatory enforcement calendars.
Material uncertainties — semiconductor allocation volatility, platform licensing cost shifts, and smart TV embedded substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about broadband infrastructure investment continuity and hospitality capital expenditure recovery patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Europe Cigarette Lighter Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Ereader and Enotetaking Devices Market