
 Bluetooth Headphones Market | 2026-2036
Bluetooth Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Headphones Market Intelligence
Fitness enthusiasts is collapsing the historical dominance of casual commuters as the primary buyer archetype for Bluetooth headphones. Apple Inc. leverages its ecosystem lock-in to sustain premium pricing power across true wireless formats. Samsung Electronics Co. Ltd. anchors its position through backward integration into semiconductor and display components. Sony Group Corp. differentiates via acoustic engineering heritage and industry-leading active noise cancellation algorithms.
Bluetooth headphones are wireless audio transducers employing radio frequency communication in the 2.4 GHz ISM band, typically incorporating lithium-polymer batteries, dynamic or balanced armature drivers, and MEMS microphones for bidirectional audio exchange. Over-ear configurations retain the largest margin pool due to material intensity and audiophile price tolerance, while true wireless formats lead unit growth through relentless miniaturization of SoC packages. Gaming applications command premium positioning as low-latency codecs and spatial audio processing become baseline expectations for competitive play.
FCC certification governs RF emissions and spectrum allocation for products entering the United States, while CE marking under the EU Radio Equipment Directive mandates interoperability and safety testing for European market access. China's MIIT enforces type approval for wireless devices, creating a three-jurisdiction compliance burden that favors manufacturers with established regulatory affairs capabilities. Stakeholders must monitor codec standardization battles between Qualcomm's aptX and the LC3 codec within the Bluetooth LE Audio specification, as this technical inflection will reshape component sourcing and royalty structures.
Market Dynamics
The Bluetooth headphones market pivots on codec standardization battles between Qualcomm's proprietary aptX and the LC3 codec within Bluetooth LE Audio, a technical inflection reshaping component sourcing, royalty structures, and interoperability certification requirements across manufacturing ecosystems.
Growth Catalysts
- Fitness-Optimized Audio Wearables:Workout-specific form factors with biometric integration and sweat resistance are pulling hardware refresh cycles from casual commuters toward fitness enthusiasts as the primary buyer archetype.
- EU Radio Equipment Directive:Harmonized CE marking requirements for wireless transmission protocols are reducing fragmentation in European market access, consolidating compliance investment toward scalable manufacturers.
- Shenzhen Electronics Cluster:Concentrated component sourcing, final assembly, and domestic consumption within China's Pearl River Delta are compressing lead times and enabling rapid product iteration.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell production gravitates toward a narrow supplier base in East Asia, exposing finished goods manufacturers to input volatility and geopolitical logistics friction.
- Three-Jurisdiction Certification Burden:FCC testing for US RF emissions, CE marking under EU safety mandates, and MIIT type approval in China create fixed compliance costs that disproportionately burden smaller entrants.
- Wired Audio Residual Demand:Latency-sensitive professional audio and audiophile segments sustain preference for analog connections, capping total addressable market expansion in premium tiers.
Strategic Opportunities
- Gaming Application Premiumization:Low-latency codecs and spatial audio processing are establishing new price floors in competitive gaming headsets, with peripheral manufacturers capturing margin from display and console OEMs.
- Bluetooth LE Audio Rollout:The Auracast broadcast audio specification enables public venue accessibility applications, opening institutional procurement channels in transportation and hospitality verticals.
- India Manufacturing Incentives:PLI scheme benefits for electronics assembly are attracting contract manufacturers to establish capacity outside China, diversifying geographic supply footprint.
Industry Challenges
- MEMS Microphone Integration Complexity:Bidirectional audio exchange requirements for voice calls and virtual assistants demand acoustic engineering talent scarce outside established acoustic laboratories.
- Codec Licensing Fragmentation:Royalty stacking across Qualcomm aptX, Sony LDAC, and emerging LC3 implementations complicates BOM cost forecasting and margin protection.
- Active Noise Cancellation Algorithm Development:Real-time adaptive filtering requires DSP firmware expertise concentrated among semiconductor vendors, limiting differentiation for assembly-centric brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Headphones Market |
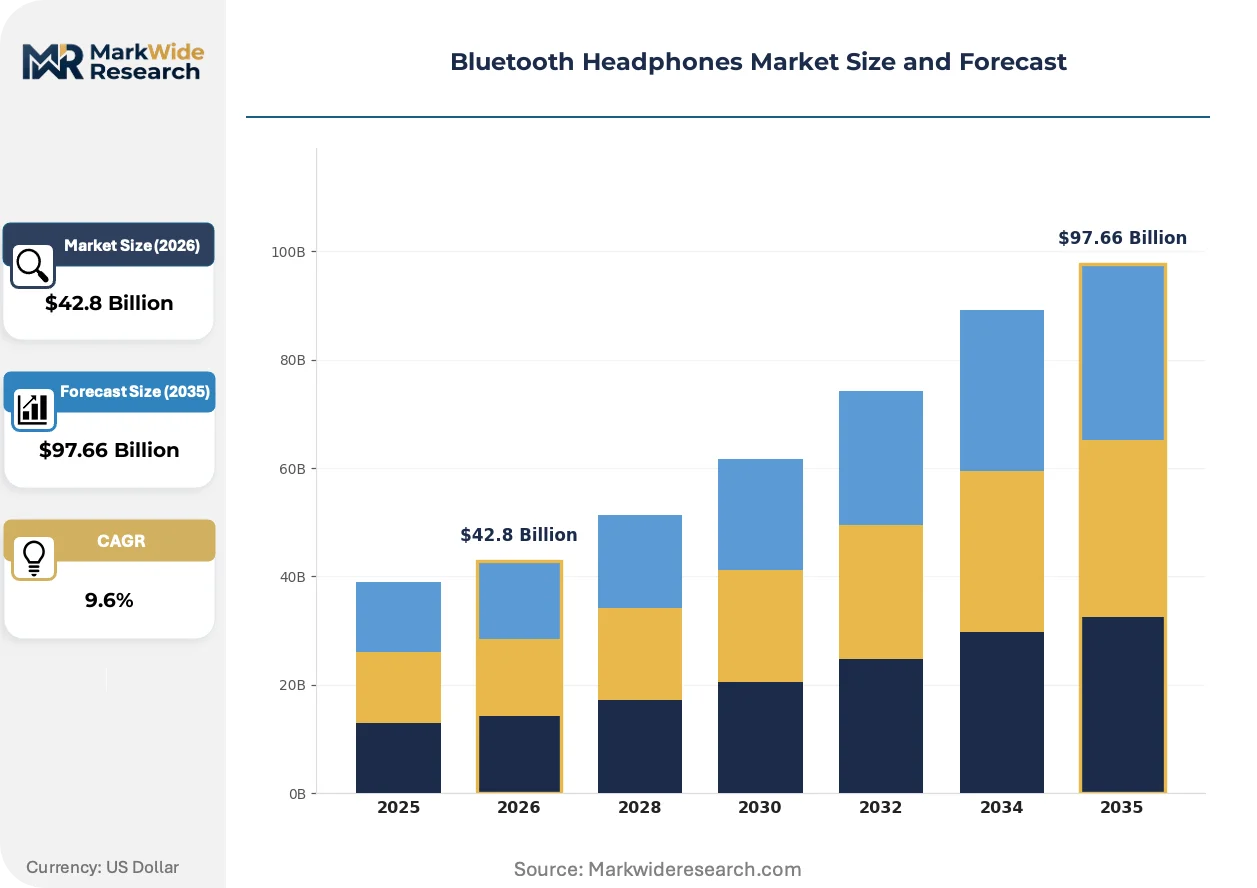
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $97.66 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, Over-Ear, On-Ear, True Wireless Technology: Active Noise Cancellation, Voice Assistant Integration, Multipoint Connectivity, Touch Controls, AptX Codec Application: Sports & Fitness, Gaming, Teleconferencing, Travel, Entertainment End User: Individual Consumers, Corporate Users, Audio Professionals, Educators, Fitness Enthusiasts |
| Companies Covered | Bose Corp., Koninklijke Philips NV, Apple Inc., Audio Technica US Inc., Xiaomi Inc., Sony Group Corp., Logitech International SA, Razer Inc., Samsung Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Headphones Market Strategic Shifts & Innovations
Codec migration and miniaturization are compressing product lifecycles while regulatory harmonization and demand rotation toward fitness and gaming applications are restructuring competitive positioning across price tiers.
Bluetooth LE Audio with its LC3 codec is displacing legacy SBC and AAC implementations in mid-tier product lines. Fitness enthusiasts and hearing-aid adjacent users are adopting Auracast-enabled devices at accelerated replacement cycles. This codec transition is displacing Qualcomm's royalty capture in volume segments while enabling broadcast audio applications previously impossible under Classic Audio profiles.
The EU Radio Equipment Directive's 2024 cybersecurity amendments are mandating firmware update capabilities and vulnerability disclosure protocols for wireless audio devices. Manufacturers must reconfigure supply chains to support over-the-air update infrastructure. Premium tier products with embedded software maintenance capabilities are capturing institutional procurement preference in European enterprise channels.
Direct-to-consumer subscription bundles are unbundling after-sales service from hardware margin, with fitness platforms and audio streaming services subsidizing device costs for captive ecosystem lock-in. Traditional retail distributors in North America and Western Europe are losing volume to manufacturer-owned channels. This channel compression is most visible in China, where live commerce and super-app integration dominate youth segment acquisition.
Bluetooth Headphones Market Segmentation
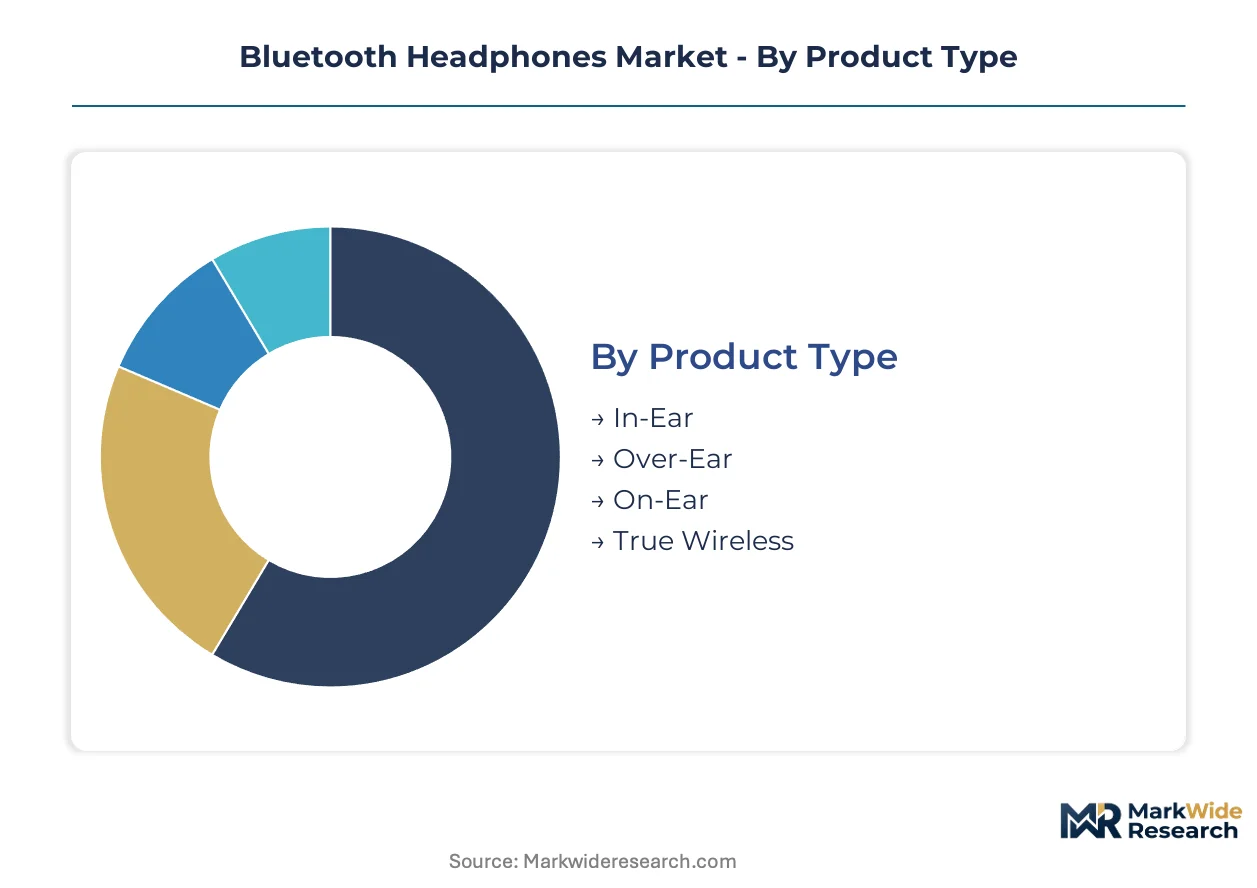
Bluetooth headphones segment across four dimensions that reshape procurement patterns and margin structures. Product type determines material intensity and acoustic engineering requirements. Technology tiers separate premium positioning from commoditized volume plays.
Product Type:
Domestic consumption in China favors compact form factors, while North American and European markets sustain demand for over-ear configurations with premium positioning.
- True Wireless:Completely cable-free earbud designs utilizing miniaturized SoC packages and lithium-polymer cells in individual housings. Shenzhen's manufacturing cluster compresses lead times for this format, with fitness enthusiasts driving replacement cycles through sweat-resistant IP ratings and biometric integration.
- Over-Ear:Circumaural designs with larger dynamic drivers, extended battery capacity, and passive isolation through clamping force and cushioning materials. Audiophile segments in Germany and Japan sustain price tolerance above other geographies, capping total addressable market expansion despite superior acoustic performance.
- In-Ear:Wired-replacement designs with neckband or cable-connected housings, typically employing balanced armature drivers for mid-tier frequency response. India's PLI scheme incentives are attracting contract manufacturers to establish assembly capacity for this price-sensitive format.
- On-Ear:Supra-aural configurations with reduced material intensity compared to over-ear alternatives, targeting portability-conscious commuters. Corporate procurement channels in France and the Netherlands favor this format for hybrid work teleconferencing deployments.
Over-ear configurations hold the largest share; momentum sits with true wireless formats.
Technology:
Cost tier separation runs through codec licensing fees, DSP firmware complexity, and certification requirements for bidirectional audio exchange.
- Active Noise Cancellation:Real-time adaptive filtering using feedforward and feedback microphones with inverse waveform generation. Sony and Apple capture premium positioning through proprietary algorithm development, while semiconductor vendors concentrate DSP expertise that limits differentiation for assembly-centric brands.
- Voice Assistant Integration:Wake-word detection engines and cloud API connectivity for hands-free command execution. MEMS microphone integration complexity demands acoustic engineering talent scarce outside established laboratories in Denmark and South Korea.
- Multipoint Connectivity:Simultaneous pairing with multiple source devices for seamless switching between laptop and smartphone audio streams. Corporate users in the United Kingdom prioritize this capability for hybrid work flexibility.
- Touch Controls:Capacitive sensing surfaces replacing mechanical buttons for gesture-based volume and playback management. Surface area constraints in true wireless formats challenge reliable implementation.
- AptX Codec:Qualcomm's proprietary low-latency audio compression with royalty-bearing licensing structure. Gaming applications command premium positioning as this codec becomes baseline expectation for competitive play.
Active noise cancellation dominates premium tier revenue; voice assistant integration is expanding most quickly through smart home ecosystem penetration.
Application:
Volume concentration varies sharply by use case, with fitness and gaming applications pulling hardware refresh cycles from legacy entertainment-centric purchasing.
- Sports & Fitness:Sweat-resistant IP ratings, earhook stabilizers, and biometric sensor integration for heart rate monitoring. China's domestic market leads unit consumption for this application.
- Gaming:Low-latency codec requirements and spatial audio processing for positional cue detection. Peripheral manufacturers capture margin from display and console OEMs through premium headset positioning.
- Teleconferencing:Beamforming microphone arrays and sidetone calibration for all-day wear comfort. Corporate procurement in Germany and the United States drives institutional volume.
- Travel:Hybrid active noise cancellation prioritizing engine frequency attenuation for aviation environments. Frequent flyer program partnerships sustain retail margin in airport duty-free channels.
- Entertainment:General-purpose consumption spanning music and video playback without specialized feature requirements. Price compression is most severe in this mature application.
Entertainment retains volume leadership; sports and fitness gains share fastest through replacement cycle acceleration.
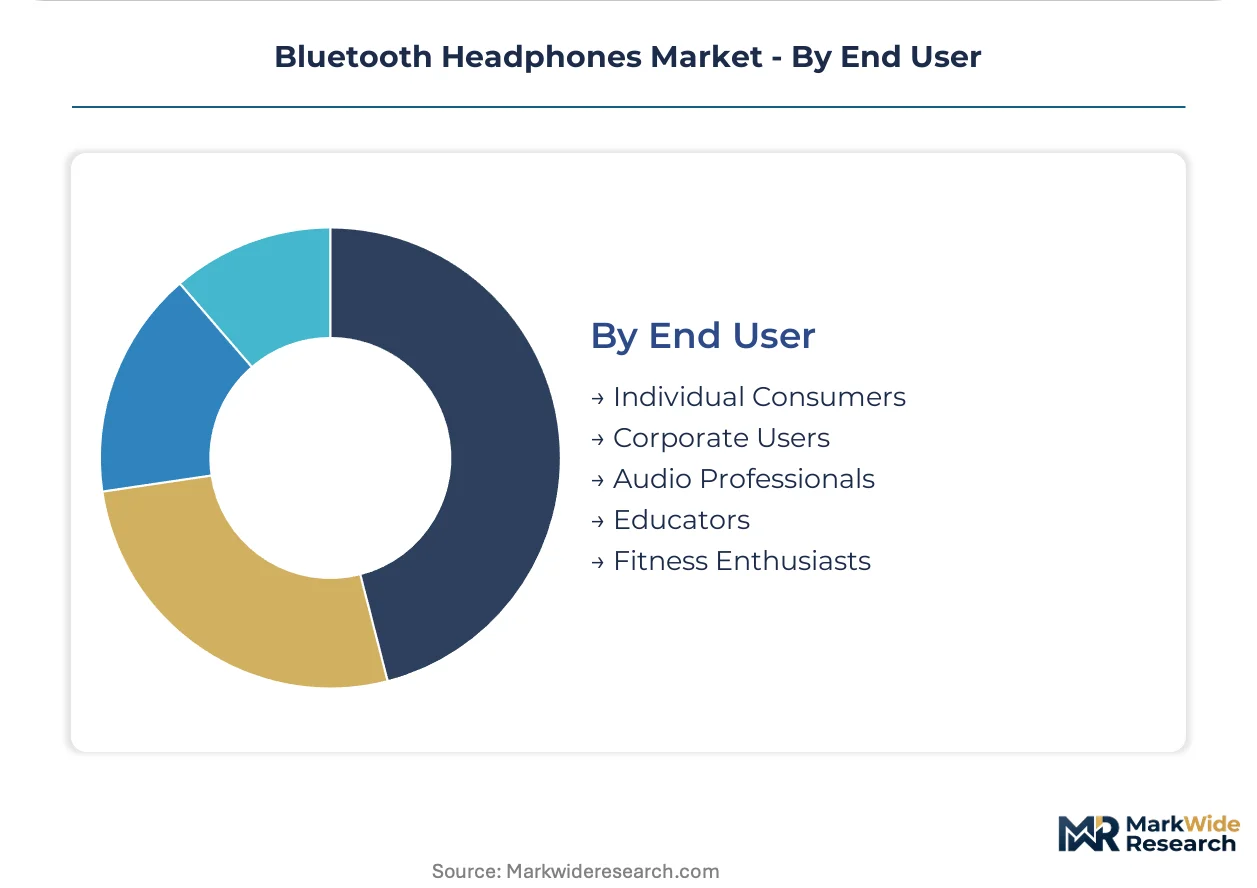
End User:
Customer type determines channel strategy, with direct-to-consumer subscription bundles unbundling after-sales service from hardware margin.
- Individual Consumers:Retail and e-commerce procurement with brand preference shaped by smartphone ecosystem lock-in. Live commerce and super-app integration dominate youth segment acquisition in China.
- Fitness Enthusiasts:Platform-integrated purchasing through workout subscription bundles subsidizing device costs. This segment is collapsing the historical dominance of casual commuters as primary buyer archetype.
- Corporate Users:Institutional procurement with standardized IT compatibility requirements and fleet management considerations. European enterprise channels favor vendors with embedded software maintenance capabilities.
- Audio Professionals:Latency-sensitive studio monitoring and field recording applications sustaining residual wired audio preference. This segment caps total addressable market expansion in premium tiers.
- Educators:Durability-focused procurement for classroom deployment with simplified controls and ruggedized construction. Auracast broadcast audio specifications enable accessibility applications in this vertical.
Individual consumers hold the largest share; fitness enthusiasts climb the fastest through platform ecosystem lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing cluster exports finished Bluetooth headphones to North American and European retail channels, with domestic absorption absorbing an expanding share of Pearl River Delta output.
United States
FCC certification governs RF emissions for wireless audio devices entering the market. Fitness enthusiasts and gaming applications drive replacement cycles through platform-integrated purchasing. The Pacific Northwest hosts acoustic engineering talent pools supporting MEMS microphone integration for voice assistant capabilities.
Germany
Audiophile segments sustain price tolerance for over-ear configurations above other geographies. CE marking under the EU Radio Equipment Directive mandates interoperability testing for European market access. Bavaria concentrates acoustic R&D laboratories developing active noise cancellation algorithms.
China
MIIT type approval enforces wireless device standards, creating compliance coordination with FCC and CE regimes. Live commerce and super-app integration dominate youth segment acquisition. Shenzhen's manufacturing cluster compresses lead times through concentrated component sourcing and final assembly.
India
PLI scheme incentives attract contract manufacturers establishing assembly capacity outside China. Price-sensitive demand favors in-ear and neckband formats over premium true wireless alternatives. Maharashtra and Karnataka host emerging electronics manufacturing zones benefiting from production-linked benefits.
Japan
METI oversees standards alignment for wireless audio equipment in a market with established audiophile preferences. Corporate procurement channels favor vendors with embedded software maintenance capabilities. Tokyo-Osaka corridor maintains acoustic engineering heritage supporting high-resolution codec implementation.
Bluetooth Headphones Market Key Industry Players
Listed leaders compete with private specialists across ecosystem integration and component sourcing dimensions. The vendor base stratifies into three tiers: semiconductor-integrated conglomerates, acoustic heritage specialists, and contract manufacturing assemblers. Strategic archetypes include ecosystem-locked premium brands, component-backward-integrated electronics groups, and gaming peripheral specialists. Competitive moves concentrate on codec licensing partnerships and geographic manufacturing diversification.
Among ecosystem-integrated technology groups, Apple Inc. and Samsung Electronics Co. Ltd. occupy positions defined by captive semiconductor and display component supply. Sony Group Corp. anchors the acoustic engineering specialist tier through heritage positioning in noise cancellation and high-resolution audio. Xiaomi Inc. represents the scale-driven contract assembly archetype leveraging Shenzhen manufacturing proximity for rapid product iteration.
| Leading Market Players |
|---|
| Bose Corp. |
| Koninklijke Philips NV |
| Apple Inc. |
| Audio Technica US Inc. |
| Xiaomi Inc. |
| Sony Group Corp. |
| Logitech International SA |
| Razer Inc. |
| Samsung Electronics Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Fourteen-day component lead times from Shenzhen's manufacturing cluster compress inventory carrying costs while amplifying pricing power for agile assemblers against slower-moving premium brands. This temporal advantage feeds directly into margin structures, as rapid product iteration enables faster codec transitions and reduced obsolescence risk.
Pricing Analysis
Codec-generation pricing gaps separate Bluetooth LE Audio-enabled products from legacy SBC implementations and emerging Auracast-capable next-gen devices. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by active noise cancellation algorithm sophistication and MEMS microphone array certification grade. Pricing pressure stems from lithium-polymer cell input volatility and royalty stacking across Qualcomm aptX and Sony LDAC licensing. Fitness enthusiasts show lowest price sensitivity through platform-subsidized subscription bundles, while India's price-sensitive demand favors economy-tier in-ear formats.
Supply Chain Analysis
Container availability fluctuations on the Shenzhen-Los Angeles trade lane expose finished goods manufacturers to inventory mismatches during peak retail replenishment cycles. Component sourcing concentrates in China for lithium-polymer cells and SoC packages, South Korea for MEMS microphones, and Taiwan for semiconductor fabrication. Raw material dependencies span rare earth magnets for driver assemblies, cobalt for battery cathodes, and copper for RF shielding. Single-source vulnerability in East Asian battery cell production creates structural risk. Distribution runs through manufacturer-owned direct-to-consumer channels, live commerce platforms, and traditional electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth headphones sit in early-cycle expansion as Auracast broadcast audio specifications unlock institutional procurement channels in transportation and hospitality verticals previously inaccessible under Classic Audio profiles.
For Market Incumbents: Fortify algorithm differentiation through captive acoustic engineering talent in Denmark and South Korea, while accelerating backward integration into MEMS microphone components to reduce semiconductor vendor dependency. Codec licensing fragmentation threatens margin protection; exclusive partnerships with Qualcomm or LC3 consortium members provide defensive moats. Channel control through fitness platform ecosystem lock-in preserves pricing power against retail compression. For New Entrants and Emerging Players: Lead with Auracast-enabled accessibility applications in European education and public transit verticals, where institutional procurement favors vendors with embedded software maintenance capabilities. India's PLI scheme incentives offer the most penetrable geography for contract manufacturing establishment. Direct-to-consumer live commerce integration in China provides lowest customer acquisition cost for youth segment entry. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer electronics conglomerates with underutilized acoustic R&D laboratories and dormant noise cancellation IP portfolios. Long-term viability centers on firmware update infrastructure and regulatory compliance capabilities across FCC, CE marking, and MIIT jurisdictions. The signal to watch is LC3 codec adoption velocity in mid-tier product lines, as this technical inflection reshapes royalty structures and component sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Codec Licensing Partnership | Exclusive Qualcomm aptX or LC3 consortium access secures margin protection against royalty stacking. |
| Geographic Manufacturing Diversification | India PLI scheme capacity establishment reduces China concentration risk and tariff exposure. |
| Firmware Update Infrastructure Investment | EU Radio Equipment Directive cybersecurity mandates create compliance-based competitive differentiation. |
| Fitness Platform Integration | Subscription bundle subsidies collapse hardware margin requirements while capturing ecosystem lock-in. |
| Acoustic Engineering Talent Acquisition | Copenhagen and Seoul laboratory access enables proprietary active noise cancellation algorithm development. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with product managers at audio OEMs, semiconductor vendor business development leads, and European regulatory affairs specialists; alongside secondary validation through FCC equipment authorization databases, MIIT type approval registries, EU Radio Equipment Directive implementation guidance, and customs trade flow records for lithium-polymer cells and MEMS microphone components. Bottom-up unit shipment modeling and top-down consumer electronics spend allocation triangulated market sizing.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, technology tier, application vertical, and end-user archetype. CAGRs derived from replacement cycle compression observations in fitness and gaming segments, codec transition velocity indicators, and geographic penetration rate differentials. Forecast inputs incorporated Shenzhen manufacturing cluster capacity utilization signals and Auracast specification adoption curves in institutional procurement channels.
The analysis sits within stated boundaries; outcomes outside sustained Bluetooth LE Audio ecosystem investment, stable East Asian battery supply logistics, and harmonized EU cybersecurity compliance enforcement would require recalibration. Forecasts reflect documented assumptions regarding codec standardization battles and fitness platform subsidy durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Europe Stylus Pen Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Education PC Market
Consumer Electronics
United States Stylus Pen Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Subwoofer Market