
 Blu Ray Players Market | 2026-2036
Blu Ray Players Market Size, Share, and Industry Trends Forecast 2026-2036
Blu Ray Players Market Intelligence
The emergence of Ultra HD Players with high dynamic range support is redrawing the landscape for physical media enthusiasts. Sony leverages its vast content library from its film division to promote its hardware. Panasonic differentiates with its focus on cinematic color accuracy, targeting the prosumer market. Pioneer sustains its brand legacy in the high-fidelity audio-visual space with premium-priced players.
A Blu-ray player is an optical disc playback device designed to read high-definition and ultra-high-definition video stored on Blu-ray Discs. The technology uses a 405nm blue-violet laser, enabling data densities far greater than standard DVDs. While standalone players remain the core product type, the Ultra HD Players segment now captures the highest value. Within applications, home entertainment dominates, but corporate presentations represent a stable, albeit smaller, niche.
Product compliance is governed by CE marking requirements in Europe, which dictate safety and electromagnetic compatibility standards. In the United States, devices must adhere to FCC regulations concerning radio frequency interference. Global ISO standards for optical media ensure disc and player interoperability. Stakeholders must now decide whether to invest in next-generation physical media formats or pivot towards streaming hardware integration.
Market Dynamics
The market's core dynamic is the deepening bifurcation between mass-market streaming convenience and a resilient niche demand for superior physical media fidelity. This is driven by cinephiles and audiophiles seeking uncompromised audio-visual quality from Ultra HD Blu-ray, a trend concentrated in specific enthusiast segments.
Growth Catalysts
- Ultra HD Standards:The proliferation of formats like HDR10+ and Dolby Vision compels enthusiasts to upgrade hardware for the ultimate home cinema experience.
- Physical Media Preference in Japan:Strong consumer preference for owning physical copies of films and music sustains stable demand for high-performance players in the Japanese market.
- Remastered Content Availability:Studios re-releasing back-catalogs in 4K creates a continuous content stream that justifies hardware investment for collectors.
Market Restraints
- Streaming Service Substitution:The convenience and low cost of video-on-demand services represent the primary threat, displacing physical media for most consumers.
- High-End Player Cost:Premium Ultra HD players have a significant price premium over streaming devices, limiting their appeal outside the dedicated enthusiast segment.
- Optical Drive Consolidation:A declining number of optical drive manufacturers creates supply chain bottlenecks and reduces component choice for player brands.
Strategic Opportunities
- Home Theater Integration:Developing players for the custom installation market, featuring advanced connectivity like RS-232 and IP control for home automation.
- Hybrid Functionality:Integrating streaming apps and network audio playback to position players as a central, all-in-one high-fidelity media hub.
- Niche European Markets:Targeting enthusiast communities in Germany and the UK, which have a strong history of home cinema and physical media collection.
Industry Challenges
- Codec Licensing Complexity:Manufacturers face high costs licensing essential audio and video codecs like Dolby Vision and DTS:X, impacting final product pricing.
- Shrinking Retail Presence:Declining shelf space for physical media in major retail chains reduces product visibility and limits impulse purchase opportunities.
- Component Obsolescence:Sourcing specialized video processors and audio DACs becomes difficult as the market contracts, challenging long-term product support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blu Ray Players Market |
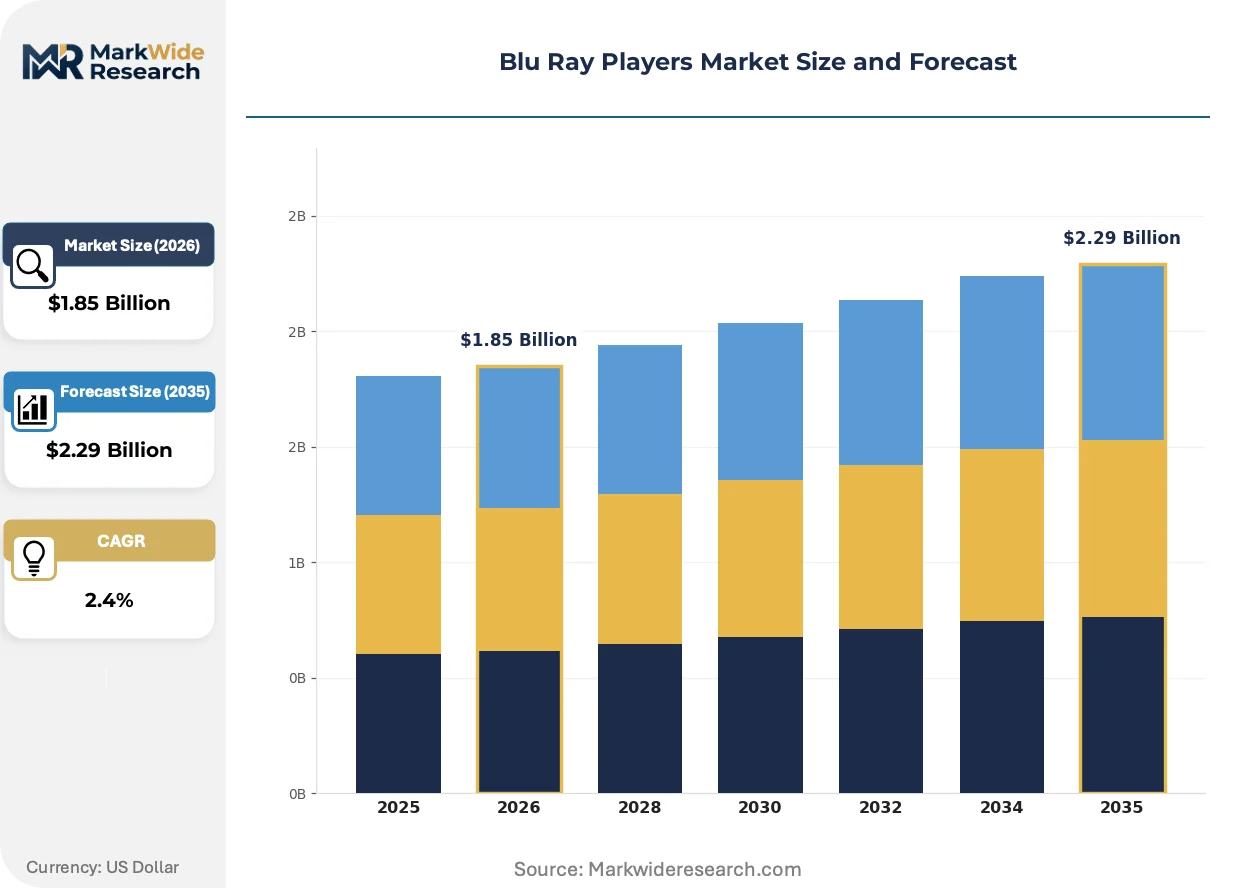
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Players, Built-in Drives, Portable Players, Ultra HD Players, 3D Compatible Players Technology: BD-ROM, BD-RE, BD-R, BD XL, Dual Layer Blu Ray Application: Home Entertainment, Corporate Presentations, Educational Use, Media Production, Gaming Consoles End User: Consumers, Office Environments, Educational Institutions, Media Studios, Gaming Centers |
| Companies Covered | Panasonic, Sony, LG, Magnetar, Pioneer, Reavon, Samsung, Philips, Yamaha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blu Ray Players Market Strategic Shifts & Innovations
The market's evolution is defined by a clear bifurcation. One path leads toward ultimate audio-visual fidelity for a dedicated niche, while the other sees low-end playback functions absorbed into multipurpose devices like gaming consoles.
High-resolution audio (HRA) playback is a key feature in premium players, supporting formats like DSD and lossless FLAC files. Audiophiles and home theater prosumers are the primary adopters, seeking sonic performance beyond standard formats. This focus on specialized audio capability is fragmenting the hardware market into video-centric devices and higher-cost, audio-focused entertainment hubs.
Mandatory compliance with CE marking in Europe and FCC Part 15 rules in the United States sets baseline requirements for product safety and electromagnetic interference. These regulations impose significant testing and certification costs on all manufacturers seeking access to these key markets. The entire standalone player segment is affected, with compliance being a non-negotiable step in the product development lifecycle.
A distinct channel shift is underway, moving sales from traditional brick-and-mortar electronics stores to specialist online retailers and direct-to-consumer websites. Mass-market retail is deprioritizing the category, while dedicated e-commerce sites supported by enthusiast forums become the main point of purchase. This pattern is most pronounced in North America and Western Europe.
Blu Ray Players Market Segmentation
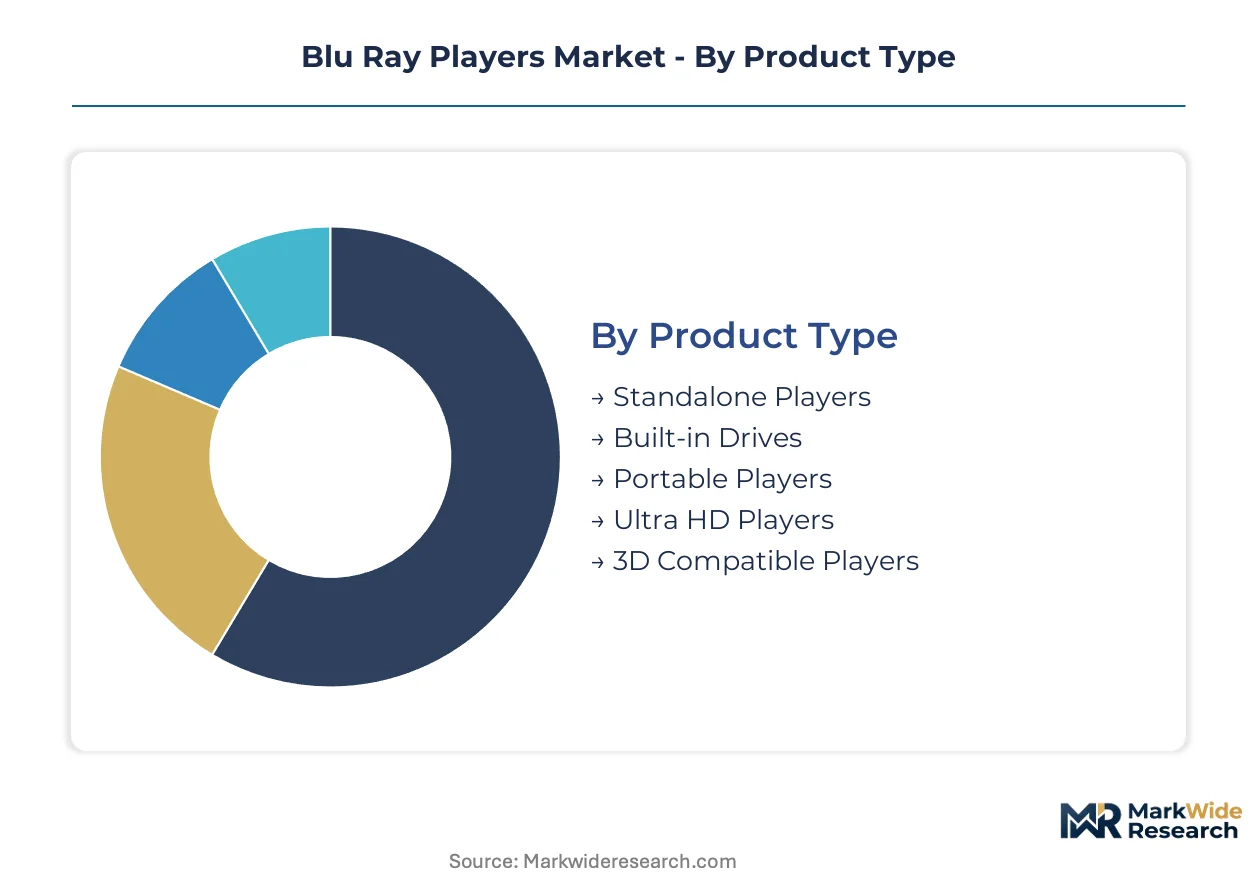
The Blu Ray Players market exhibits distinct segmentation, reflecting the varied technological requirements and application contexts across its user base. Understanding these segments is crucial for identifying areas of concentrated demand and specialized product development within the broader physical media landscape.
Product Type:
The distribution of Blu-ray player product types varies significantly by geography, with standalone devices enjoying broad domestic sales while premium Ultra HD players see concentrated demand in export-led high-income markets.
- Ultra HD Players:These high-end devices support 4K resolution and advanced HDR formats like HDR10+ and Dolby Vision. Demand for these players is particularly strong among cinephiles and audiophiles in regions like Japan and Western Europe, seeking uncompromised home cinema experiences.
- Standalone Players:These are dedicated devices designed solely for playing Blu-ray discs and often DVDs, forming the foundational product type for physical media consumption. They represent the largest volume segment, widely available across all major markets for general home entertainment.
- Built-in Drives:Integrated directly into other electronic devices such as laptops or desktop computers, these drives offer convenient Blu-ray playback capabilities. Their sales often correlate with the broader personal computer market, providing a secondary function for media consumption.
- Portable Players:Compact, battery-powered units designed for on-the-go entertainment, often featuring small integrated screens. This niche segment caters to travel and personal viewing preferences, offering flexibility outside a fixed home theater setup.
- 3D Compatible Players:Devices capable of playing Blu-ray discs formatted for 3D viewing, requiring a compatible display and glasses. This segment represents a legacy feature, with demand declining as 3D home entertainment adoption has waned globally.
Standalone Players holds the largest share; momentum sits with Ultra HD Players.
Technology:
Different Blu-ray technologies serve distinct applications, ranging from widespread commercial content distribution to specialized data archiving and professional media creation.
- BD-ROM:This read-only format is the standard for commercially released movies and software, providing a secure and high-capacity medium for content distribution. It remains the most prevalent technology, underpinning the entire physical media market for films and television.
- BD XL:Offering significantly increased storage capacity (up to 128 GB), this technology caters to specialized applications requiring large data volumes, such as professional video archiving or extensive data backup solutions. Demand for BD XL is concentrated in media production and corporate environments.
- BD-RE:Rewritable Blu-ray discs allow users to record, erase, and re-record data multiple times, making them suitable for data backup, temporary storage, and professional content workflows. This technology finds use in office environments and media studios for iterative projects.
- BD-R:Write-once Blu-ray discs enable permanent data storage, ideal for archiving personal videos, photos, or critical business documents. Educational institutions and individual consumers utilize BD-R for long-term preservation of digital content.
- Dual Layer Blu Ray:This technology doubles the storage capacity of a standard Blu-ray disc by using two data layers, commonly found in mainstream movie releases to accommodate longer features or higher bitrate content. It enhances the viewing experience for consumers without requiring specialized players.
BD-ROM technology remains central to the market, while BD XL capabilities are expanding quickly.
Application:
The volume of Blu-ray player usage varies significantly across applications, with consumer-driven entertainment dominating the market landscape.
- Home Entertainment:This application represents the primary use case for Blu-ray players, serving consumers who seek superior picture and audio quality for movies and television shows. Enthusiast segments, particularly in Japan and Germany, drive demand for premium players and Ultra HD content.
- Media Production:Professionals in film, television, and music industries utilize Blu-ray players for quality control, archival purposes, and distributing high-definition content to clients. This application demands robust players with precise color and audio reproduction capabilities.
- Corporate Presentations:Businesses employ Blu-ray players for delivering high-definition video content in boardrooms, training facilities, and trade show booths. The reliability and consistent quality of physical media are critical for professional corporate communications.
- Educational Use:Educational institutions use Blu-ray players for playing instructional videos, documentaries, and interactive course materials in classrooms and libraries. The durability of physical discs ensures long-term access to multimedia resources.
- Gaming Consoles:Modern gaming consoles integrate Blu-ray drives, primarily for distributing game titles but also serving as a secondary function for playing movies and other media. This application leverages the existing hardware for broader entertainment purposes.
Home Entertainment applications account for the vast majority of demand, with Media Production showing steady, specialized growth.
End User:
End-user segments exhibit varying margin profiles, influenced by purchase volume, feature requirements, and the need for specialized customization.
- Consumers:This segment includes individual households and home theater enthusiasts who purchase Blu-ray players for personal entertainment, driven by a desire for high-fidelity audio and video. Consumers often prioritize ease of use and compatibility with their existing home entertainment systems.
- Media Studios:Professional media companies, including film studios, post-production houses, and recording labels, use Blu-ray players for mastering, quality assurance, and archival storage of high-resolution content. These users demand industrial-grade reliability and specialized format support.
- Office Environments:Corporate offices and businesses utilize Blu-ray players for professional presentations, training modules, and secure data distribution. Stability and consistent performance are key requirements for devices deployed in these settings.
- Educational Institutions:Schools, universities, and public libraries acquire Blu-ray players for multimedia instruction, research, and providing access to educational content. Durability and ease of integration into existing AV systems are important considerations.
- Gaming Centers:Establishments offering gaming services often rely on Blu-ray drives integrated into consoles for game distribution and occasional media playback. This segment values robust hardware that can withstand frequent use.
Consumers represent the largest end-user group, while Media Studios drive demand for high-end, specialized units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for Blu-ray players shows a clear contrast, with mass-market segments highly sensitive to price and convenience, while enthusiast niches prioritize uncompromised audio-visual fidelity over cost. Regions with strong home entertainment cultures and disposable income continue to drive demand for premium Ultra HD players. Conversely, markets where streaming dominates see greater price sensitivity for physical media hardware.
Japan
Japanese consumers demonstrate a strong preference for physical media, driving consistent demand for high-performance Blu-ray players. The Ministry of Economy, Trade and Industry (METI) supports local electronics manufacturing, which indirectly benefits component suppliers for these devices. Tokyo's consumer electronics districts remain key hubs for showcasing and purchasing advanced home cinema equipment.
Germany
German home cinema enthusiasts sustain a robust market for premium Blu-ray players, valuing superior picture and sound quality. CE marking requirements ensure product safety and electromagnetic compatibility for all devices sold within the European Union. Munich and Berlin host numerous specialist audio-visual retailers catering to this discerning consumer base.
United States
A significant segment of American cinephiles and audiophiles invests in Ultra HD Blu-ray players for an optimal home theater experience. Devices must adhere to FCC regulations concerning radio frequency interference, ensuring consumer safety and device interoperability. Southern California, particularly the Los Angeles area, concentrates a large population of entertainment industry professionals and early adopters.
China
China's burgeoning middle class shows a rising interest in high-definition home entertainment, contributing to demand for Blu-ray players. The State Administration for Market Regulation (SAMR) oversees product quality and safety standards for consumer electronics. Shenzhen's electronics manufacturing ecosystem provides a competitive landscape for both domestic and international player brands.
Blu Ray Players Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure within the Blu-ray player market. Premium brands focus on advanced features and audio-visual performance, while others compete on affordability and basic functionality. Strategic partnerships with content providers and component suppliers represent a common competitive move.
On the premium-tier vector, Panasonic and Sony exemplify brands leveraging extensive heritage in consumer electronics and content ecosystems to differentiate their Blu-ray player offerings. Pioneer represents a specialist player, maintaining its brand legacy in high-fidelity audio-visual equipment for discerning audiophiles. These companies primarily cater to the enthusiast segment, where superior performance justifies higher price points.
| Leading Market Players |
|---|
| Panasonic |
| Sony |
| LG |
| Magnetar |
| Pioneer |
| Reavon |
| Samsung |
| Philips |
| Yamaha |
| Others |
Cost & Logistics Intelligence
Component lead times for specialized video processors extending to 12-18 weeks directly influence player manufacturing schedules. This tightens supply availability for premium Ultra HD models and bolsters their pricing power.
Pricing Analysis
After-sales service and extended warranty contracts drive significant lifetime value for premium Blu-ray players, particularly for complex home theater installations. Per-unit transactional sales remain the dominant pricing model for standalone players. Brand premium and customization for advanced home theater integration serve as key price differentiation drivers. Pricing softness for mass-market players stems from intense competition with streaming devices, while enthusiast segments are less price-sensitive.
Supply Chain Analysis
Port congestion and container availability challenges impact the timely delivery of optical drives and integrated circuits from key manufacturing hubs. Geographic supply concentration for critical components like optical drives and specialized chipsets sits primarily in China, Japan, and Taiwan. Component obsolescence, particularly for audio DACs and video processors, represents a structural supply chain risk. Distribution runs through specialist online retailers and direct-to-consumer channels, especially for high-end units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story, justified by the high switching costs associated with established physical media collections and integrated home theater systems.
For Market Incumbents: Fortify existing brand loyalty by expanding exclusive 4K physical media content partnerships with film studios. Invest in advanced R&D for next-generation audio and video processing to counter the ongoing threat from streaming service substitution. Control over key component supply, particularly optical drive manufacturing, represents a critical lever against supply chain bottlenecks.
For New Entrants and Emerging Players: CE marking and FCC certification fast-tracks offer a viable entry point for specialist manufacturers targeting niche European and American markets. Target the unserved segment of prosumer content creators requiring robust, high-fidelity playback for quality control. A direct-to-consumer sales model, supported by enthusiast community engagement, offers a cost-effective go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a niche technology play because of its enduring appeal to audiophiles and cinephiles prioritizing quality over convenience. Acquisition targets should focus on vertically integrated mid-cap specialists with strong intellectual property in audio-visual processing. The sustained release of remastered 4K content from major studios is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance High-Resolution Audio Integration | Captures increased spend from audiophiles seeking DSD and FLAC playback capabilities beyond standard video. |
| Develop Advanced Home Automation Connectivity | Integrates players into custom installation markets, securing premium sales through RS-232 and IP control. |
| Secure Long-Term Optical Drive Supply Agreements | Mitigates supply chain risks and ensures component availability amid declining optical drive manufacturing. |
| Expand Direct-to-Consumer Sales Channels | Bypasses shrinking retail presence and directly engages enthusiast communities in North America and Europe. |
| Partner for Exclusive 4K Physical Media Content | Strengthens hardware appeal by offering unique access to remastered films and high-fidelity audio releases. |
Research Approach
A spread of perspectives from home theater installers, consumer electronics retailers, optical drive manufacturers, and content studio distribution managers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders provided qualitative insights, which were then validated against extensive secondary research. This approach combined bottom-up market intelligence with top-down industry trends, ensuring a robust data foundation.
Product type, technology, application, end-user, and regional demand patterns formed the core segmentation dimensions modeled across the analysis window. The analytical framework integrated historical sales data with projected technological advancements to derive compound annual growth rates. Forecast inputs included Ultra HD content release schedules and optical drive supply forecasts, informing future market trajectory.
Underlying assumptions cover the continued preference for physical media among enthusiast segments, with deviation risk concentrated in the accelerated evolution of streaming service quality and component supply stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Tablet Market
Consumer Electronics
Advanced Baby Monitors Market
Consumer Electronics
Electronics Accessories Market