
 Noise Cancelling Headphones Market | 2026-2036
Noise Cancelling Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Noise Cancelling Headphones Market Analysis
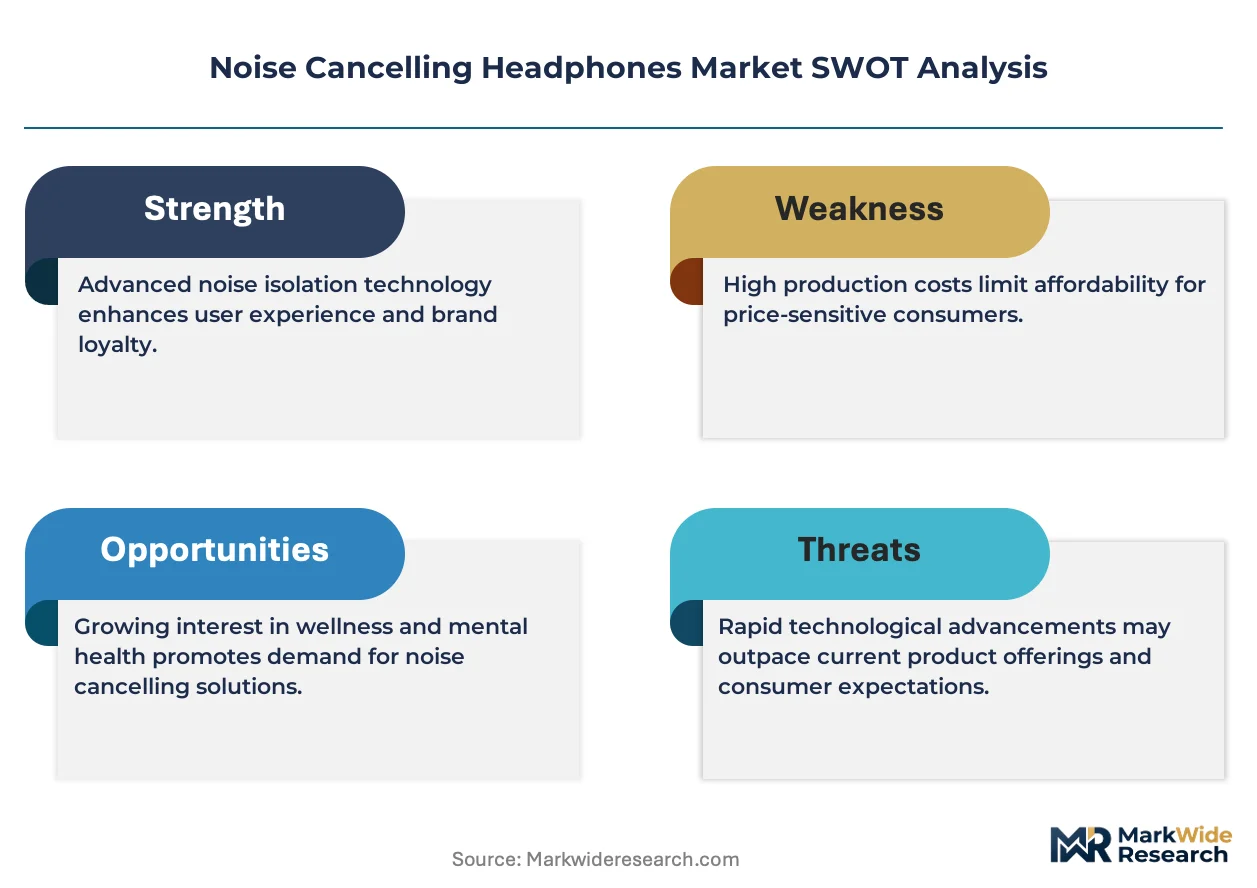
Enterprise procurement teams is redrawing the demand map for premium audio hardware as consumer gift-buying softens. Sony leverages its semiconductor foundry relationships to control MEMS microphone supply for flagship over-ear units. Bose anchors North American corporate channel partnerships through direct sales to Fortune 500 IT departments. Sennheiser specializes in broadcast-grade frequency response tuning that appeals to audio engineers and studio professionals.
Noise cancelling headphones integrate active circuitry with acoustic damping materials to attenuate ambient sound across target frequency bands, typically achieving 20-40 dB reduction at 100-1000 Hz through phase-inverted anti-noise generation. The primary commercial purpose spans commuter isolation, open-office productivity, and hearing protection in industrial settings. True wireless in-ear configurations capture the fastest volume expansion as smartphone OEMs omit legacy headphone jacks, while over-ear products retain the dominant margin pool due to larger driver enclosures and extended battery capacities. Hybrid noise cancellation technology leads R&D investment as manufacturers combine feedforward and feedback microphone arrays for adaptive environmental filtering.
The FCC enforces hearing aid compatibility standards that constrain electromagnetic emission profiles and influence coil driver architecture in US-bound products. The EU's RoHS and REACH frameworks restrict hazardous substances in solder joints and earpad foams, compelling Asian contract manufacturers to reformulate material supply chains. California's Proposition 65 warning requirements add labeling compliance costs for products containing trace phthalates in cable insulation. Stakeholders must monitor evolving right-to-repair legislation across multiple states that could mandate replaceable battery designs and shift warranty cost structures.
Market Dynamics
Hybrid work mandates from enterprise IT departments have compressed hardware refresh cycles, forcing manufacturers to prioritize over-ear ANC platforms with all-day battery endurance and seamless multi-device pairing protocols.
Growth Catalysts
- FCC Hearing Aid Compatibility Mandates:Regulatory pressure in the United States is accelerating transducer redesign toward coil architectures that serve dual hearing assistance and premium audio functions.
- MEMS Microphone Supply Control:Captive semiconductor foundry relationships enable flagship-tier feedforward array integration for adaptive environmental filtering.
- Enterprise IT Budget Expansion:Fortune 500 procurement teams are redirecting capital from facility buildouts toward distributed workforce audio hardware.
Market Restraints
- Rare Earth Magnet Price Volatility:Neodymium and dysprosium cost swings in Chinese processing facilities compress driver margin structures unpredictably.
- RoHS and REACH Compliance Burden:ECHA substance restrictions force Asian contract manufacturers to reformulate solder alloys and earpad foam chemistries at elevated qualification expense.
- True Wireless Commoditization:Smartphone OEM bundling and white-label in-ear substitutes erode perceived differentiation in entry-level ANC tiers.
Strategic Opportunities
- Industrial Hearing Protection:OSHA-compliant ANC systems for manufacturing floors represent an underpenetrated application with mandated procurement triggers.
- Right-to-Repair Legislation:Emerging state-level battery replacement mandates in the United States create first-mover advantage for modular hardware architectures.
- Broadcast-Grade Frequency Response:Studio professional demand for flat EQ tuning opens premium pricing above consumer-tuned consumer electronics.
Industry Challenges
- Acoustic Engineer Talent Scarcity:Feedforward-feedback algorithm optimization requires specialized DSP expertise concentrated in Danish and Japanese audio clusters.
- Proposition 65 Labeling Complexity:California's trace phthalate disclosure rules add SKU-specific packaging validation cycles that delay regional launches.
- Multi-Device Pairing Certification:Bluetooth SIG qualification timelines for seamless laptop-phone-tablet switching extend time-to-revenue for flagship releases.
Report Scope
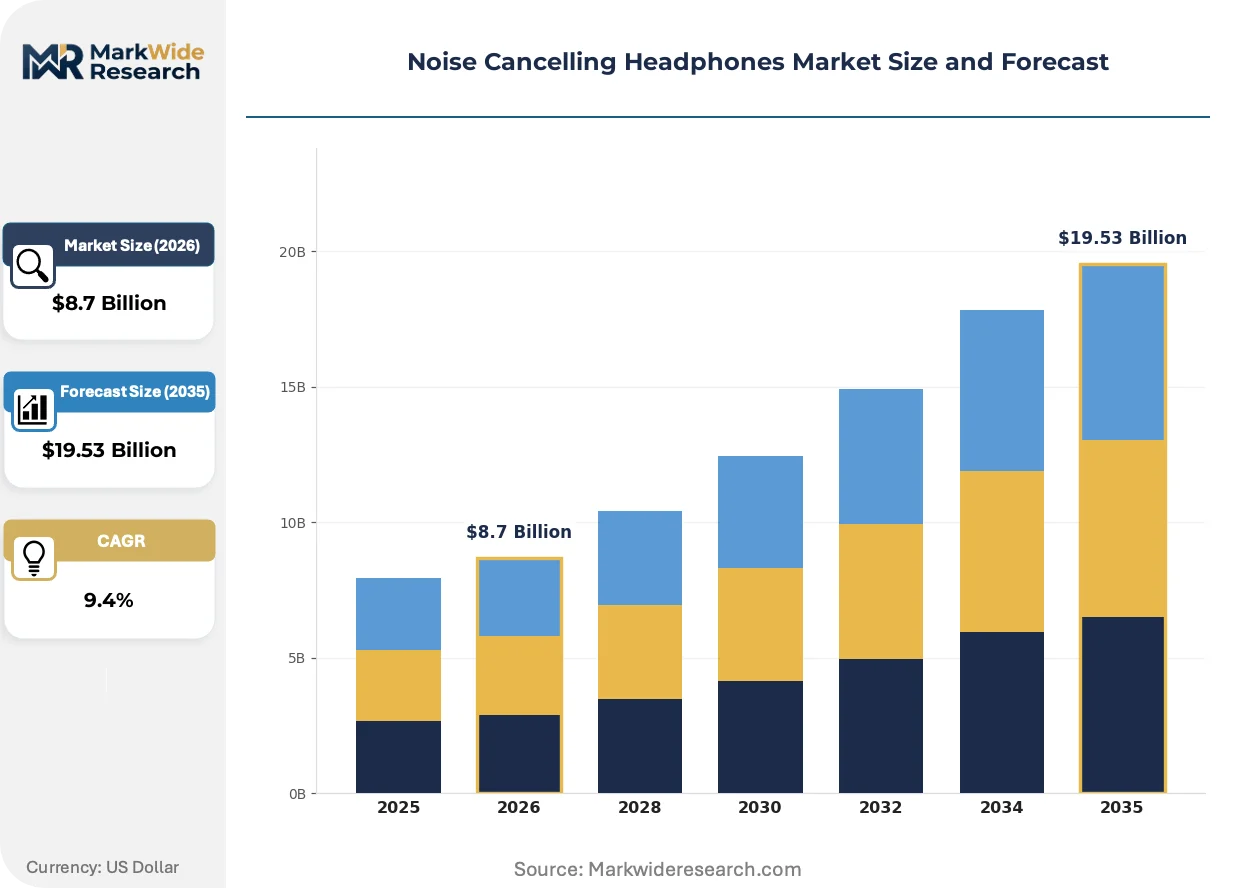
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise Cancelling Headphones Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Ear, On-Ear, In-Ear, True Wireless Technology: Active Noise Cancellation, Passive Noise Cancellation, Hybrid Noise Cancellation, Bone Conduction End User: Consumers, Professionals, Gamers, Travelers Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Distributors |
| Companies Covered | Apple, Bowers & Wilkins, Sony, EPOS, Yealink, Bose, Focal, Poly, Sennheiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise Cancelling Headphones Market Emerging Trajectories
Active noise cancellation hardware is converging with biometric sensing and spatial audio rendering, compressing the traditional boundary between professional monitoring tools and consumer wellness devices.
Hybrid ANC chipsets is miniaturizing. These silicon packages combine feedforward exterior microphones with feedback interior sensors to enable real-time environmental adaptation. Enterprise procurement teams are specifying adaptive hybrid architectures for open-office deployments. The technology is miniaturizing enclosure volumes while preserving 40 dB attenuation performance, collapsing the size premium that previously separated over-ear from in-ear efficacy.
REACH substance restrictions are tightening across the European Union. ECHA's candidate list expansion now targets flame retardants in PCB assemblies and plasticizers in cable sheathing. Manufacturers serving EU-bound SKUs must maintain dual material bills and segregated production lines. German retail channels are demanding full material disclosure documentation as a listing prerequisite.
Enterprise bulk purchasing is displacing individual consumer transactions. Fortune 500 IT departments now negotiate direct annual hardware allowances rather than reimbursing employee retail acquisitions. This concentrates buying power among three to four preferred vendor relationships. The shift is most visible in United States technology and financial services verticals where remote-work policies remain entrenched.
Noise Cancelling Headphones Market Segmentation
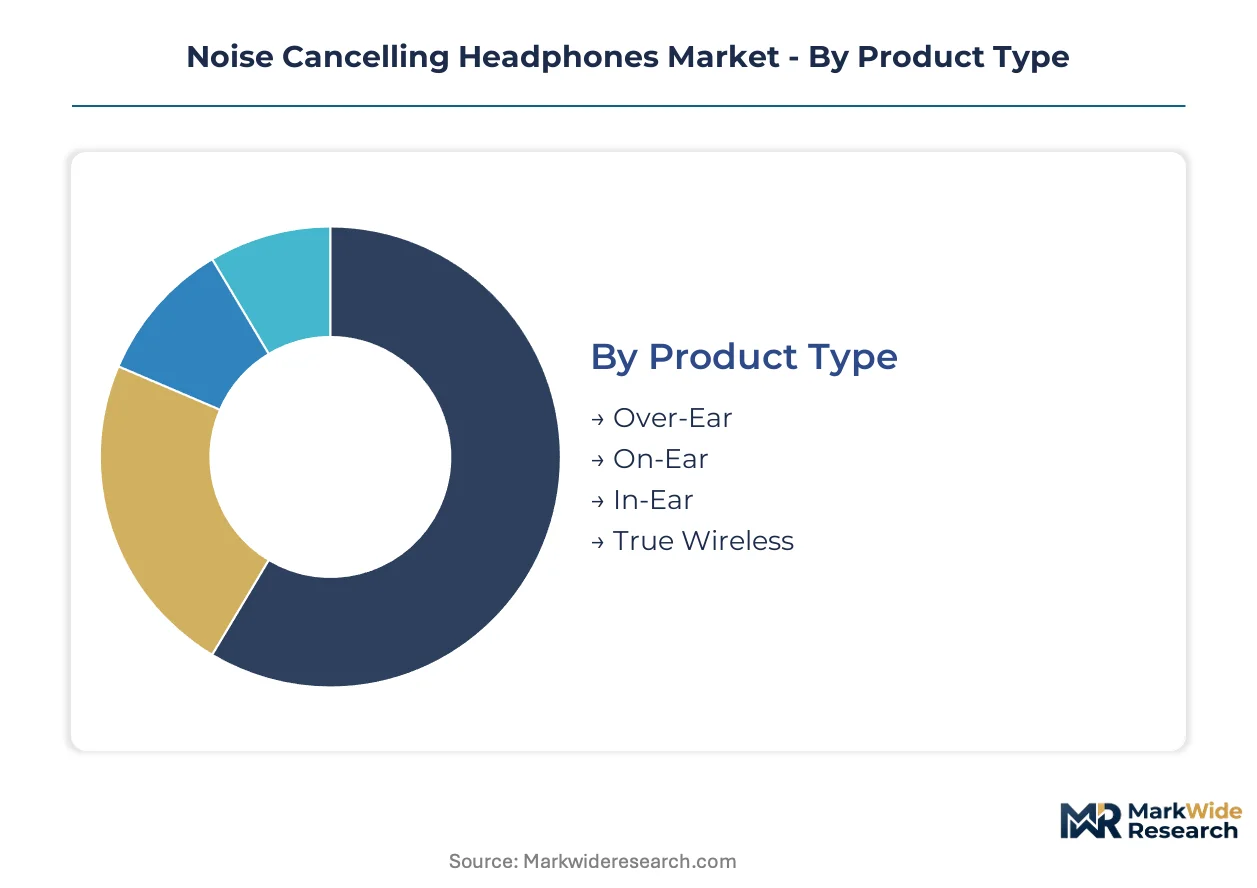
Segmentation in noise cancelling headphones reveals how substitution pressures reshape procurement patterns across form factors and use cases. Enterprise buyers and individual consumers face diverging trade-offs between acoustic performance, portability, and price-to-feature ratios.
Product Type:
True wireless in-ear configurations face the most acute substitution threat from smartphone OEM bundling and white-label alternatives, compressing differentiation space at entry price tiers.
- Over-Ear:Large driver enclosures accommodate extended battery capacities and multiple microphone arrays for adaptive hybrid ANC. Fortune 500 IT departments in the United States concentrate procurement here for all-day remote work endurance, prioritizing seamless multi-device pairing protocols over portability.
- True Wireless:Smartphone OEMs omitting legacy headphone jacks have accelerated volume expansion, though margin structures erode rapidly under commoditization pressure from white-label substitutes and bundled accessories.
- On-Ear:Compact form factor suits commuter segments requiring moderate isolation without full enclosure bulk.
- In-Ear:Wired and wireless variants serve price-sensitive buyers and legacy device compatibility needs.
Over-ear configurations anchor the volume base among enterprise procurement teams while true wireless gains share at the steepest rate through smartphone ecosystem integration.
Technology:
Cost tier stratification separates flagship adaptive systems from basic feedforward implementations, with R&D investment concentrating at the premium hybrid intersection.
- Hybrid Noise Cancellation:Combines feedforward exterior microphones with feedback interior sensors for real-time environmental adaptation. Danish and Japanese audio engineering clusters concentrate DSP algorithm expertise here, with enterprise open-office deployments driving specification requirements.
- Active Noise Cancellation:Phase-inverted anti-noise generation achieves 20-40 dB attenuation at 100-1000 Hz, serving commuter isolation and industrial hearing protection applications.
- Passive Noise Cancellation:Acoustic damping materials provide baseline attenuation without power consumption, appealing to cost-constrained segments and battery-life prioritization.
- Bone Conduction:Transducer architecture bypassing eardrum stimulation serves situational awareness requirements in cycling and industrial safety contexts.
Hybrid architectures command the premium tier while active noise cancellation maintains the broadest installed base across consumer and professional segments.
End User:
Application-specific frequency response tuning and microphone array configurations differentiate professional-grade procurement from mass-market consumer transactions.
- Professionals:Broadcast-grade flat EQ tuning and extended frequency accuracy serve audio engineers and studio monitoring applications. Sennheiser and specialized manufacturers anchor supply here through direct channel relationships with post-production facilities.
- Consumers:Mass-market tuning emphasizes bass enhancement and consumer-friendly EQ profiles, with gift-buying softness redirecting volume toward enterprise bulk purchasing.
- Gamers:Low-latency wireless protocols and spatial audio rendering integrate with console and PC ecosystems.
- Travelers:Compact form factors and airline adapter compatibility prioritize portability over acoustic fidelity.
Consumer segments generate the highest unit volumes while professional tiers sustain the most durable margin structures through technical specification barriers.
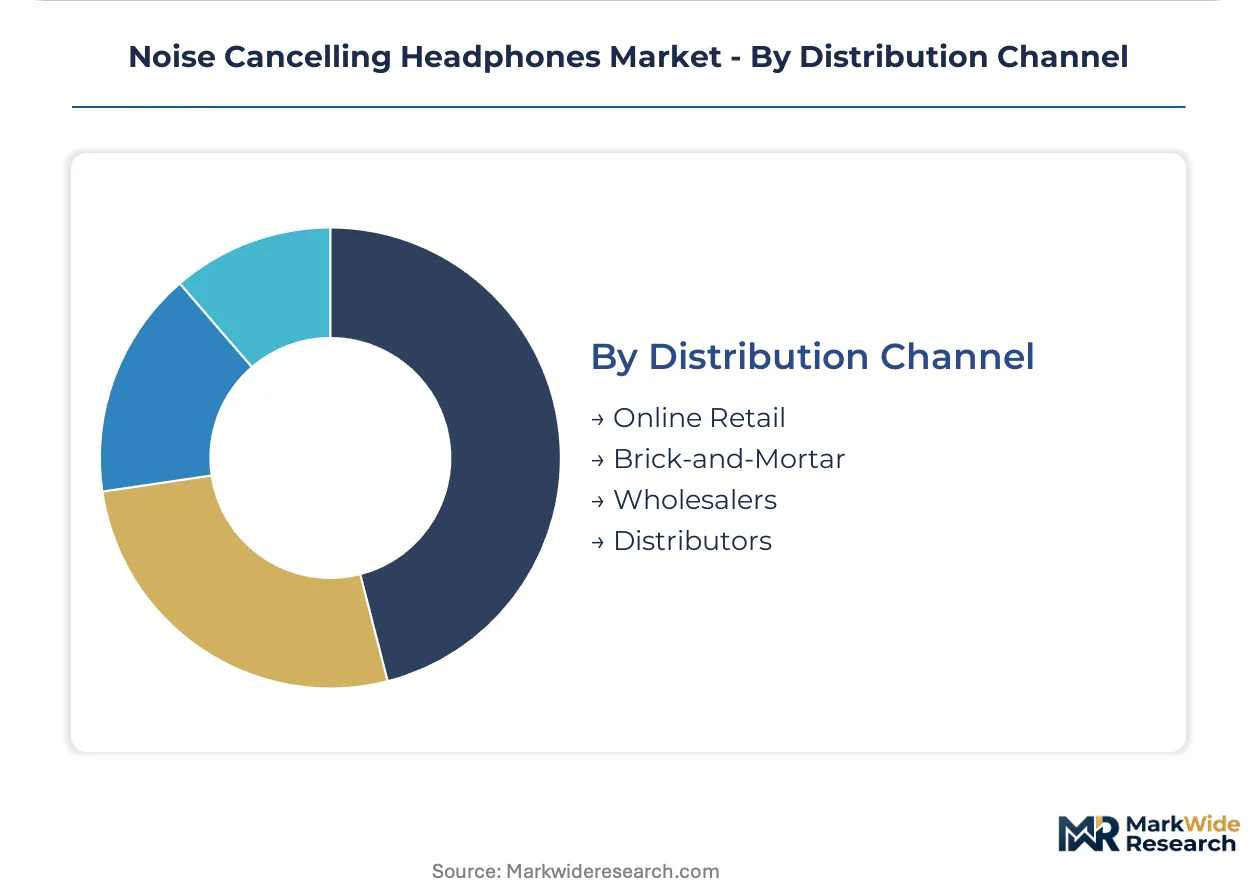
Distribution Channel:
Customer type bifurcation concentrates buying power among direct enterprise relationships while fragmenting individual purchasing across digital and physical touchpoints.
- Online Retail:E-commerce platforms capture consumer comparison shopping and subscription-renewal hardware refresh cycles, with FCC hearing aid compatibility filtering influencing search and recommendation algorithms.
- Brick-and-Mortar:Physical demonstration of fit and acoustic isolation sustains relevance for premium over-ear purchases despite volume migration online.
- Wholesalers:Bulk procurement intermediaries serve mid-market retail chains and regional electronics distributors.
- Distributors:Value-added logistics and localized warranty support address enterprise deployment scale across distributed workforces.
Online retail handles the majority of consumer transactions while direct distributor relationships expand most quickly among Fortune 500 annual hardware allowance negotiations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States concentrate bulk purchasing power, while consumer segments fragment across Germany, Japan, China, and the United Kingdom with diverging regulatory and technology adoption patterns.
United States
Fortune 500 IT departments drive hardware refresh cycles through direct annual allowance negotiations rather than retail reimbursement. FCC hearing aid compatibility mandates reshape transducer coil architectures for US-bound products. Austin and Seattle technology corridors host distributed workforce audio procurement teams specifying adaptive hybrid ANC for open-office deployments.
Germany
Broadcast-grade frequency response tuning attracts studio professionals and post-production facilities demanding flat EQ accuracy. ECHA REACH substance restrictions compel reformulation of solder alloys and earpad foam chemistries for EU-bound manufacturing. Berlin and Munich audio engineering clusters concentrate DSP algorithm expertise for feedforward-feedback optimization.
Japan
MEMS microphone foundry relationships anchor semiconductor supply control for flagship-tier feedforward array integration. METI industrial standards influence hearing protection specifications for manufacturing floor ANC deployments. Tokyo and Osaka metropolitan areas concentrate captive semiconductor fabrication partnerships with consumer electronics OEMs.
China
Asian contract manufacturers face rare earth magnet price volatility from neodymium and dysprosium processing facilities. MIIT telecommunications standards govern electromagnetic emission profiles for domestic market certification. Shenzhen and Dongguan electronics manufacturing hubs manage dual material bills to segregate RoHS-compliant EU-bound production lines.
United Kingdom
Hybrid work policies sustain premium audio procurement among financial services and technology verticals with entrenched remote-work arrangements. UKCA marking requirements post-Brexit create parallel conformity assessment pathways alongside retained EU regulations. London and Cambridge technology corridors specify multi-device pairing protocols for distributed professional workforces.
Noise Cancelling Headphones Market Vendor Landscape
Player mix skews toward diversified consumer electronics conglomerates with captive semiconductor supply chains, supplemented by specialized audio engineering houses and enterprise-focused communication equipment vendors. The structure tiers across premium flagship positioning, mid-market feature differentiation, and entry-level white-label substitution. Strategic archetypes include vertically integrated platform owners controlling MEMS microphone supply, broadcast-grade tuning specialists serving studio professionals, and corporate channel anchors with direct Fortune 500 relationships. Competitive moves concentrate on foundry partnership exclusivity and enterprise IT certification acceleration.
Within the diversified technology platform tier, Apple and Sony exemplify archetypes leveraging captive semiconductor ecosystems for adaptive ANC integration. Bose occupies a position anchoring North American corporate channel partnerships through direct sales architectures. Sennheiser sits within the broadcast-grade specialization segment, representing engineering-intensive frequency response tuning for professional monitoring applications. EPOS and Poly exemplify enterprise communication equipment vendors pivoting toward hybrid work audio hardware procurement channels.
| Leading Market Players |
|---|
| Apple |
| Bowers & Wilkins |
| Sony |
| EPOS |
| Yealink |
| Bose |
| Focal |
| Poly |
| Sennheiser |
| Others |
Supply Flow & Price Mechanics
FCC hearing aid compatibility mandates gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb coil redesign costs at the premium tier while entry-level SKUs face commoditization from white-label substitutes. Enterprise IT procurement teams exploit this bifurcation by negotiating volume allowances that collapse retail-equivalent pricing for adaptive hybrid ANC platforms.
Pricing Analysis
Current-generation adaptive hybrid ANC commands a 40-60% premium over prior-generation feedforward-only implementations, while next-generation biometric-integrated architectures are pre-positioning at flagship tier. Pricing stratifies across premium, standard, and economy tiers based on MEMS microphone array count and FCC certification grade. Cost compression in the true wireless tier is intensifying because smartphone OEM bundling erodes perceived differentiation. Enterprise buyers exhibit the lowest price sensitivity due to amortized productivity gains, while gift-buying consumers show acute elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites 70% of rare earth magnet feedstock for neodymium driver assemblies, exposing margin structures to logistics volatility. Manufacturing concentrates in China, Vietnam, and Malaysia, with MEMS microphone fabrication anchored in Taiwanese foundries. The chain draws from neodymium-dysprosium magnets, lithium-polymer cells, and RoHS-compliant solder alloys. Single-source vulnerability in Taiwanese semiconductor supply represents the dominant structural risk. Distribution runs through enterprise IT distributors, consumer electronics retailers, and direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise firmware subscription and extended warranty attach rates are expanding faster than hardware unit growth, reframing the market as a service-attach opportunity with recurring revenue multiples.
For Market Incumbents: Secure captive MEMS microphone foundry allocation through multi-year supply agreements to defend against feedstock competition from smartphone OEMs. Fortify direct Fortune 500 channel relationships before IT procurement consolidates around three-vendor panels. Vertical integration into adaptive DSP algorithm development addresses acoustic engineer talent scarcity in Danish and Japanese clusters. For New Entrants and Emerging Players: Lead with OSHA-compliant industrial hearing protection as the most penetrable white-space segment, where mandated procurement triggers bypass consumer price elasticity. Target mid-market enterprise distributors lacking hybrid ANC portfolios. Position through modular battery architectures that anticipate right-to-repair legislation. For Investors and Strategic Acquirers: FCC hearing aid compatibility mandates reshape the acquisition landscape by privileging coil-driver engineering capabilities over commodity assembly assets. Five-to-ten year viability favors targets with broadcast-grade frequency response tuning IP and direct studio professional relationships. Monitor ECHA REACH candidate list expansion as the inflection signal for material compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership Exclusivity | Taiwanese semiconductor allocation secures feedforward array supply against smartphone OEM competition. |
| Enterprise IT Certification Acceleration | Bluetooth SIG qualification compression reduces time-to-revenue for multi-device pairing protocols. |
| Modular Battery Architecture Development | Replaceable cell designs anticipate state-level right-to-repair mandates in California and New York. |
| Broadcast-Grade Frequency Response Tuning | Flat EQ accuracy opens premium pricing above consumer-tuned electronics in post-production facilities. |
| Industrial Hearing Protection Certification | OSHA compliance enables mandated procurement triggers in manufacturing floor deployments. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with audio engineering directors, enterprise IT procurement managers, MEMS foundry supply chain leads, and FCC regulatory affairs specialists; and secondary validation through SEC electronics OEM filings, Bluetooth SIG qualification databases, ECHA REACH substance restriction updates, and customs import records for neodymium magnet feedstock. Bottom-up unit shipment estimates triangulated against top-down enterprise IT hardware budget disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, ANC technology generation, end-user application, and regional regulatory cluster. CAGRs derived from weighted average of historical refresh cycle compression and enterprise procurement penetration curves. Forecast inputs incorporated hybrid work policy persistence indices and rare earth price volatility bands.
The analysis sits within stated boundaries; outcomes outside sustained enterprise IT budget expansion or accelerated right-to-repair legislative adoption would require recalibration. Forecasts reflect documented assumptions around MEMS microphone supply continuity and FCC mandate implementation timelines. Practitioners should keep alternative scenarios live as ECHA substance restriction scope and Chinese rare earth export policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Global Beauty Camera Apps Market