
 Latin America Consumer Electronics Market | 2026-2036
Latin America Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Consumer Electronics Market Foresight
ANATEL certification is rotating as the primary gating mechanism for device commercialization across Brazil, forcing manufacturers to adapt testing protocols and local documentation. Samsung Electronics leverages its established Brazilian manufacturing footprint to sustain cost advantages in smartphone assembly. Xiaomi Corporation competes aggressively on price-performance positioning, while SEMP TCL anchors regional production through its joint-venture television and appliance facilities.
Latin America consumer electronics encompass portable and fixed electronic devices designed for personal computing, communication, entertainment, and home automation, typically operating on semiconductor architectures with power consumption thresholds between 5W and 65W depending on form factor. These products serve commercial purposes spanning workforce mobility, educational access, digital commerce enablement, and connected lifestyle management across diverse socioeconomic strata. Smartphones occupy the dominant value pool given replacement cycles and 5G transition momentum, while wearables represent the fastest-expanding category as health-monitoring functionality penetrates mid-tier price bands. The price tier dimension stratifies sharply, with budget and mid-range segments capturing volume leadership and premium tiers concentrating margin pools in urban centers.
Brazil's ANATEL mandates electromagnetic compatibility and radio frequency standards that directly determine import eligibility and local assembly requirements. Mexico's PROFECO consumer protection framework and energy efficiency labeling rules shape product specifications and warranty obligations for electronics retailers. Argentina's import substitution policies and Brazil's local content incentives are forcing stakeholders to reassess supply chain footprints and manufacturing partnerships.
Market Dynamics
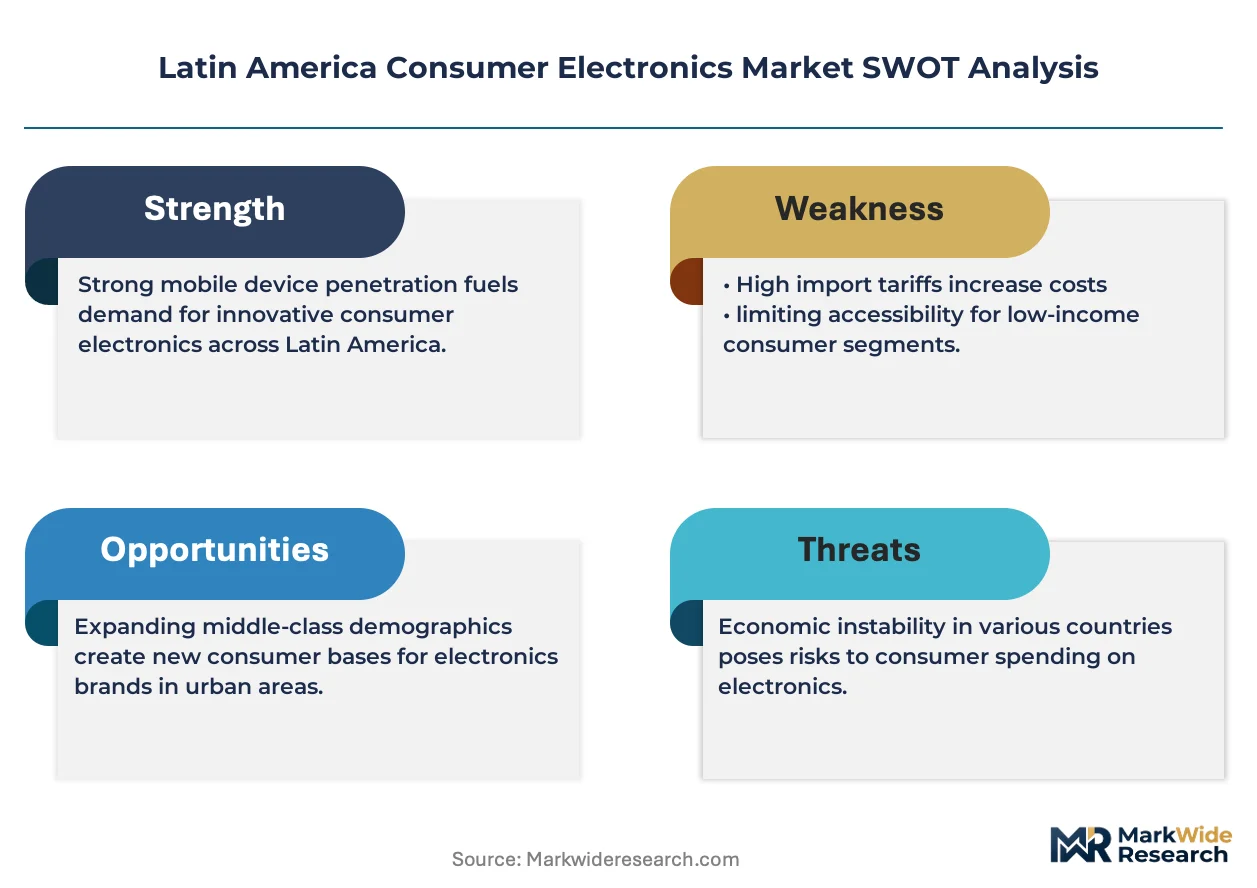
Brazil's ANATEL certification mandates are forcing manufacturers to restructure testing protocols and local assembly footprints, creating a bifurcated supply landscape where certified domestic production gains systematic preference over direct import channels.
Growth Catalysts
- 5G network deployment:Mobile operators in Brazil, Mexico, and Colombia are accelerating infrastructure rollout, compressing smartphone replacement cycles as consumers upgrade to compatible devices. Urban centers in São Paulo and Mexico City show the steepest adoption curves.
- PROFECO energy efficiency labeling:Mexico's consumer protection framework mandates standardized efficiency disclosures, creating transparent comparison tools that stimulate mid-tier appliance and electronics turnover among price-conscious households.
- Local content assembly incentives:Brazil's fiscal benefits for domestic manufacturing are pulling component suppliers toward Manaus and São Paulo state, shortening lead times for regional smartphone and television production.
Market Restraints
- Semiconductor input volatility:Memory chip and processor supply remains concentrated among East Asian foundries, exposing Latin American assemblers to freight cost swings and allocation prioritization during capacity crunches.
- Import substitution enforcement:Argentina's central bank foreign exchange controls and product-specific licensing create unpredictable clearance timelines for finished electronics, forcing distributors to maintain elevated safety inventory.
- Electromagnetic compatibility testing bottlenecks:ANATEL's limited accredited laboratory capacity in Brazil generates certification queues that delay product launches by 8-14 weeks for unestablished applicants.
Strategic Opportunities
- Colombian market underpenetration:Bogotá and Medellín exhibit smartphone penetration gaps relative to southern cone peers, with mobile wallet adoption creating bundled device-financing openings for operators.
- Health-monitoring wearables convergence:Integration of continuous glucose monitoring and sleep analytics into sub-$150 bands targets Mexico's diabetes-prevalent population and Brazil's fitness-conscious millennials.
- Direct-to-consumer channel expansion:Manufacturer-owned online storefronts bypass traditional retail markups in price-sensitive Chile and Peru, capturing margin while offering installment payment integration.
Industry Challenges
- RF engineering talent scarcity:Brazil's ANATEL certification complexity demands specialized electromagnetic compatibility expertise that local universities produce insufficiently, forcing manufacturers to import testing engineers or outsource to São Paulo consultancies.
- Legacy warranty infrastructure:Extended service obligations under Mexico's PROFECO framework strain authorized repair networks, particularly in secondary cities where parts logistics remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Consumer Electronics Market |
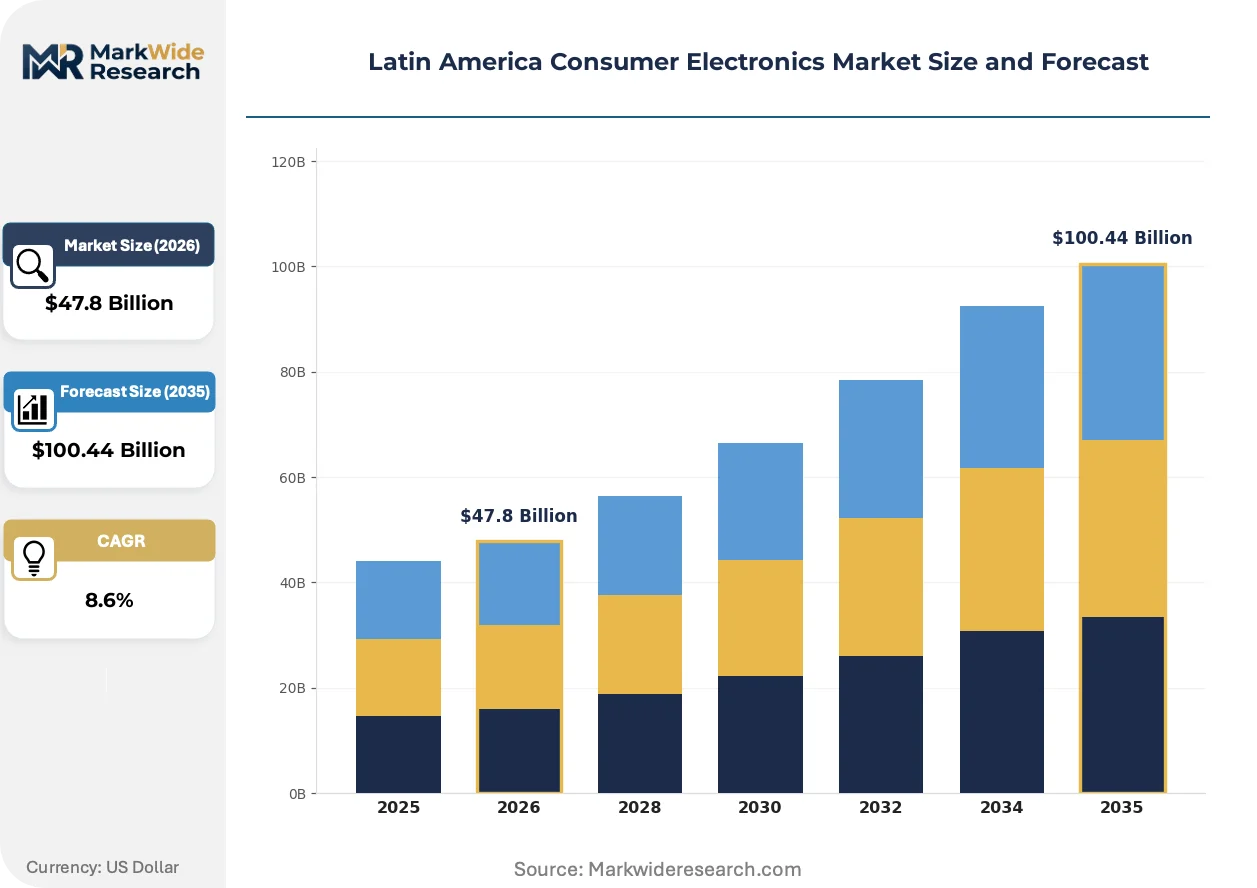
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables End User: Households, Educational Institutions, Businesses, Retailers Distribution Channel: Online Retail, Electronics Stores, Wholesale, Supermarkets Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Motorola Solutions Inc, Lenovo Group Ltd, Samsung Electronics, Panasonic Holdings Corp, HP Inc, LG Electronics, Xiaomi Corporation, SEMP TCL, Apple Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Consumer Electronics Market Shifts & Advancements
Modular hardware architectures and AI-embedded processing are decomposing traditional device categories, enabling function-specific electronics that challenge the smartphone's role as the universal computing endpoint.
System-in-package (SiP) integration is decomposing the discrete component stack in wearables and hearables. Fitness-focused consumers in Brazil's southeastern states are adopting these compact devices at rates outpacing traditional smartwatches. The technology is decomposing price-performance tradeoffs, allowing regional brands to source turnkey modules rather than designing from silicon.
ANATEL's updated electromagnetic compatibility protocols are tightening radio frequency emission limits for all wireless devices entering Brazilian commerce. Manufacturers must now submit to localized interference testing that adds 6-8 weeks to product qualification. Premium smartphone assemblers with existing Manaus facilities absorb this friction more readily than new market entrants reliant on import channels.
Subscription-based device refresh programs are displacing outright ownership among urban professionals in Mexico City and São Paulo. Mobile operators bundle annual handset upgrades with data plans, compressing replacement cycles while capturing lifetime value through financing spreads. This pattern is most visible in the 25-34 demographic segment where credit access and digital payment penetration intersect.
Latin America Consumer Electronics Market Segmentation
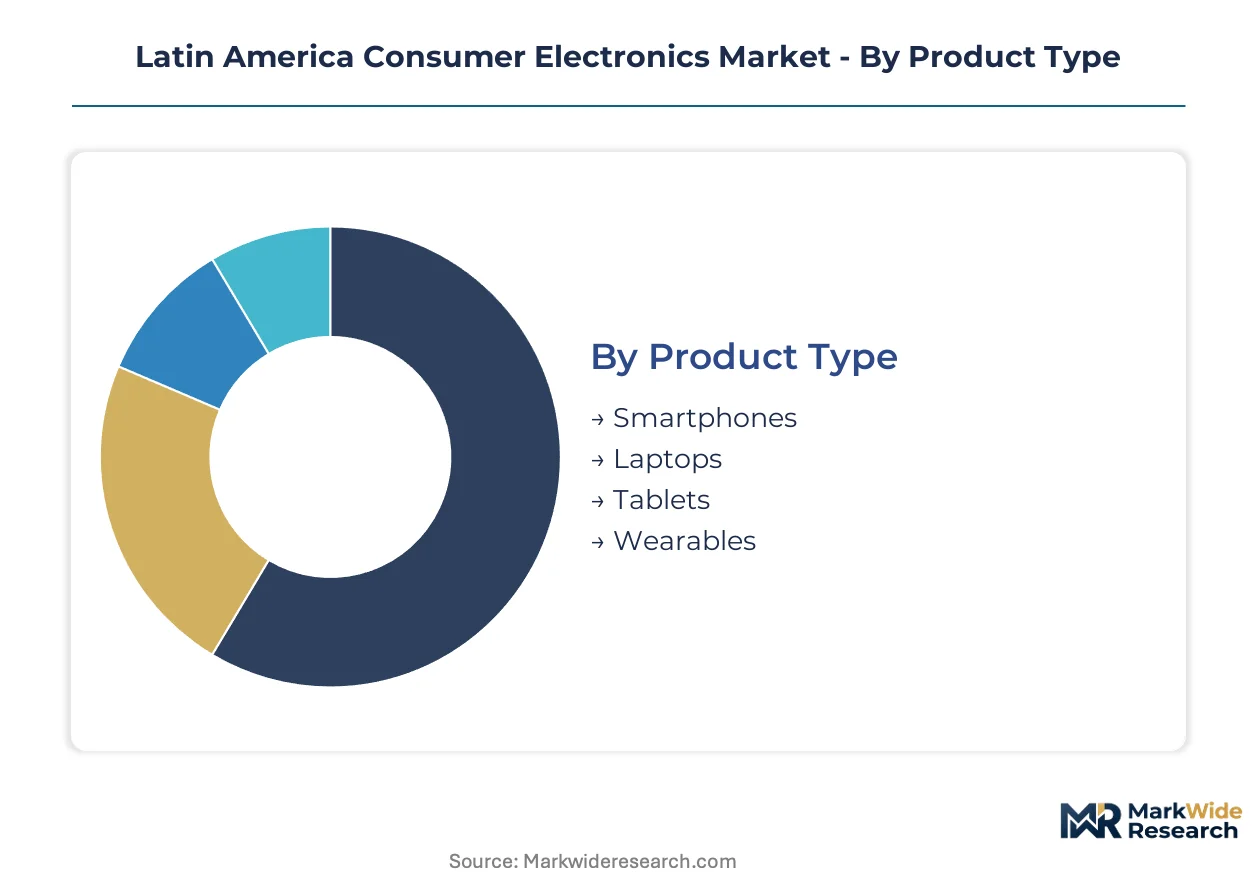
Segmentation in the Latin America Consumer Electronics Market reveals how certification requirements, income stratification, and channel infrastructure reshape competitive positioning across product categories. Manufacturers must align portfolio depth with ANATEL compliance costs and regional purchasing power dispersion.
Product Type:
Smartphones and laptops concentrate domestic assembly in Brazil's Manaus Free Trade Zone, while wearables and tablets flow primarily through import channels subject to electromagnetic compatibility testing delays.
- Smartphones:5G-enabled devices with system-on-chip architectures dominate semiconductor allocation. São Paulo and Mexico City households drive replacement cycles as mobile operators bundle financing with data plans.
- Wearables:Continuous health-monitoring bands and smartwatches integrate compact sensors for glucose and sleep tracking. Brazilian millennials in southeastern states adopt fitness-focused devices faster than traditional watch formats.
- Laptops:Hybrid work requirements sustain demand for lightweight computing with 10-15 hour battery thresholds. Educational institutions in Colombia and Peru prioritize cost-optimized Chromebooks for remote learning infrastructure.
- Tablets:Content consumption devices face smartphone screen-size convergence pressure. Retailers in Chile discount inventory through direct-to-consumer storefronts bypassing traditional markup layers.
Smartphones command the established base. The steepest expansion runs through wearables.
End User:
Cost tier alignment separates household discretionary spending from institutional procurement frameworks with diverging warranty and volume requirements.
- Households:Individual purchasers prioritize installment accessibility and PROFECO-mandated efficiency disclosures. Mexico's middle-class families concentrate spending on mid-range smartphone upgrades during promotional windows.
- Businesses:Enterprise mobility programs demand fleet management capabilities and centralized device enrollment. Brazilian corporations in finance and logistics sectors refresh laptop inventories on 24-36 month cycles.
- Educational Institutions:Public school systems procure through government tender processes with extended payment terms. Argentina's import substitution policies complicate tablet deployment timelines for provincial education ministries.
- Retailers:Electronics chains and independent shops manage inventory exposure to currency volatility. Colombian mall-based retailers leverage mobile wallet integration for device-financing origination.
Households absorb the volume concentration. Businesses deliver the margin premium.
Distribution Channel:
Channel selection determines working capital intensity and ANATEL certification documentation requirements for cross-border fulfillment.
- Online Retail:Manufacturer-owned storefronts and marketplace platforms compress price points through direct fulfillment. Chilean and Peruvian consumers adopt installment-integrated checkout fastest in the region.
- Electronics Stores:Specialized retailers provide hands-on demonstration and immediate technical support. Brazil's authorized networks handle warranty claims under ANATEL-mandated service obligations.
- Wholesale:Distributors manage bulk procurement for regional retail chains and corporate resellers. Inventory positioning in São Paulo state reduces lead times for smartphone assembly inputs.
- Supermarkets:Mass merchandisers stock entry-level devices alongside grocery categories. Mexican hypermarkets leverage foot traffic for impulse accessory purchases.
Electronics stores anchor the established volume. Online retail captures the steepest trajectory.
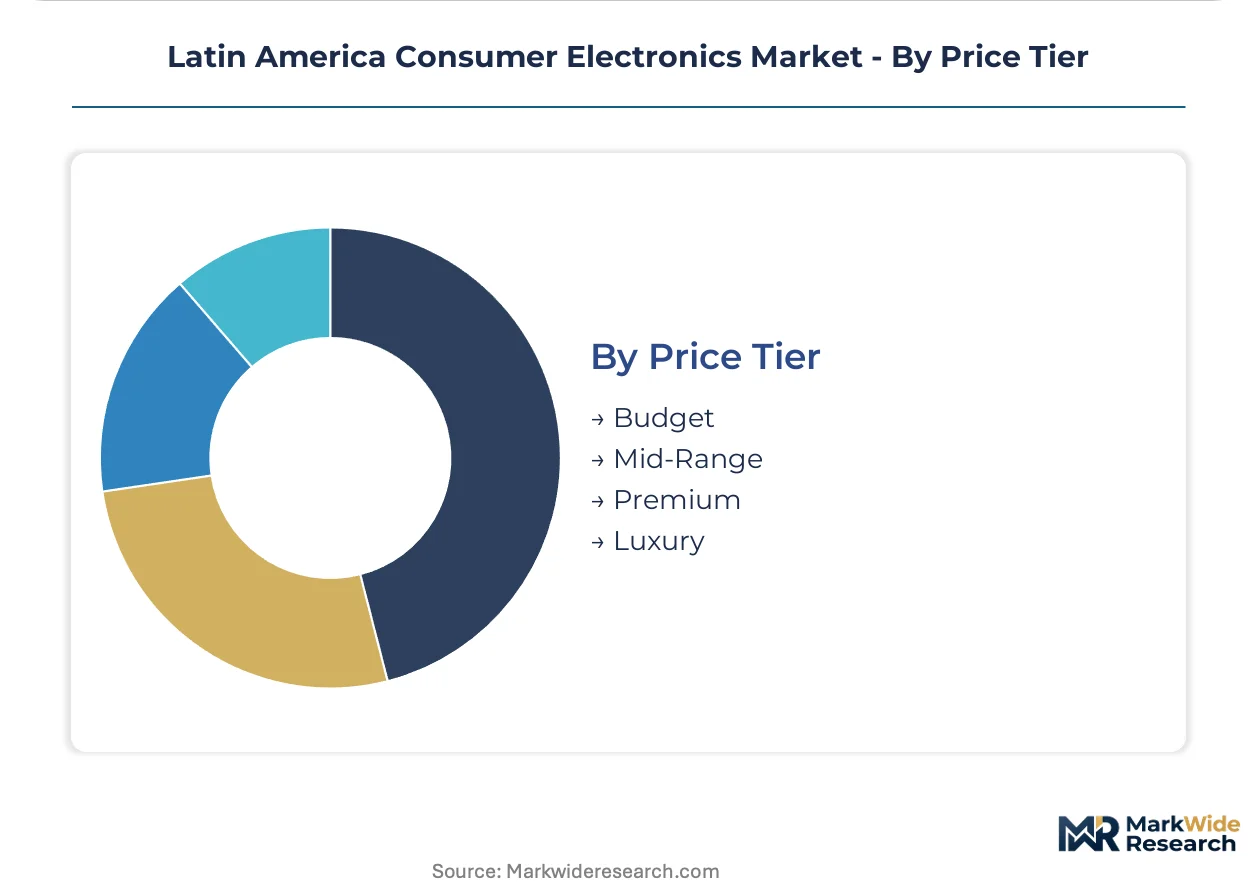
Price Tier:
Certification cost absorption and local assembly incentives create divergent margin structures across tier positioning.
- Budget:Sub-$150 devices prioritize essential connectivity with reduced processor specifications. Price-sensitive households in Peru and secondary Colombian cities dominate this segment's absorption.
- Mid-Range:$150-$400 smartphones balance camera performance and storage capacity for mainstream adoption. Brazilian young professionals upgrade through operator-subsidized refresh programs.
- Premium:Flagship devices with advanced AI processing and display technology target urban centers. São Paulo and Mexico City concentrate discretionary spending on top-tier specifications.
- Luxury:Limited-edition designs and concierge service bundles address ultra-high-net-worth segments. Miami-import channels serve Caribbean and Central American elite demand.
Mid-range pricing commands the volume base. Premium tier delivers the margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in São Paulo and Mexico City drive premium smartphone turnover, while mid-tier households across secondary cities anchor volume absorption. Certification costs and local assembly incentives reshape competitive positioning country by country.
Brazil
Southeastern millennials upgrade wearables with health-monitoring features at rates exceeding traditional smartwatch adoption. ANATEL's electromagnetic compatibility mandates force manufacturers to submit devices to localized interference testing, extending qualification timelines. Manaus Free Trade Zone hosts smartphone and television assembly operations that shorten component lead times for regional distribution.
Mexico
Middle-class families concentrate spending on mid-range smartphone upgrades during operator promotional windows. PROFECO's energy efficiency labeling framework mandates standardized disclosures that stimulate appliance turnover among price-conscious households. Mexico City mobile operators bundle annual handset upgrades with data plans, compressing replacement cycles in the 25-34 demographic.
Colombia
Bogotá and Medellín exhibit smartphone penetration gaps relative to southern cone peers, with mobile wallet adoption creating bundled device-financing openings. The national government tenders for educational technology procurement follow extended payment terms that complicate tablet deployment timelines. Mall-based retailers in major urban centers leverage mobile wallet integration for device-financing origination.
Argentina
Provincial education ministries face unpredictable clearance timelines for finished electronics due to central bank foreign exchange controls and product-specific licensing. Import substitution enforcement forces distributors to maintain elevated safety inventory against currency volatility. Buenos Aires-based retail chains manage exposure through conservative stocking of entry-level devices.
Chile
Urban professionals in Santiago adopt manufacturer-owned online storefronts fastest in the region, bypassing traditional retail markups through installment-integrated checkout. The country's consumer protection framework shapes warranty obligations for electronics retailers operating across metropolitan and secondary markets. Direct-to-consumer channels capture margin while offering payment flexibility in price-sensitive segments.
Latin America Consumer Electronics Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with established regional manufacturing footprints. Market structure concentrates around three to four integrated assemblers with domestic certification capabilities, while import-dependent specialists occupy peripheral positions. Dominant archetypes include vertically integrated television and appliance manufacturers, smartphone specialists with operator financing partnerships, and component-scale assemblers leveraging free trade zone incentives. Competitive moves center on local content compliance investments and direct-to-consumer channel expansion.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics anchor regional production through established Brazilian facilities that absorb ANATEL certification friction. Xiaomi Corporation occupies a position exemplifying price-performance positioning against mid-tier volume segments. SEMP TCL represents the joint-venture archetype, combining regional manufacturing scale with international technology licensing to serve television and appliance demand across price tiers.
| Leading Market Players |
|---|
| Motorola Solutions Inc |
| Lenovo Group Ltd |
| Samsung Electronics |
| Panasonic Holdings Corp |
| HP Inc |
| LG Electronics |
| Xiaomi Corporation |
| SEMP TCL |
| Apple Inc. |
| Others |
Supply & Pricing Matrix
System-in-package module substitution for discrete component stacks simultaneously pulls assembly activity toward Manaus and São Paulo while compressing margin capture for import-dependent distributors lacking local certification capabilities.
Pricing Analysis
Cost-plus contracts indexed to memory chip spot markets dominate component procurement for Brazilian assemblers. Price differentiation hinges on ANATEL certification tier and volume scale, with certified domestic production commanding premium positioning over grey-market imports. Pricing pressure stems from Xiaomi's aggressive price-performance positioning in mid-range smartphones. Budget-tier households in Peru and secondary Colombian cities exhibit highest price sensitivity, while São Paulo urban professionals absorb premium markups for health-monitoring wearables.
Supply Chain Analysis
Panama Canal transit congestion periodically chokes semiconductor shipments from East Asian foundries to Brazilian assembly plants. Component supply concentrates in Taiwan, South Korea, and China, with memory chips and system-on-chip processors forming critical dependencies. Single-source vulnerability in advanced node fabrication exposes regional assemblers to allocation prioritization during capacity crunches. Distribution runs through São Paulo-based wholesale hubs serving electronics chains across the southern cone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as 5G infrastructure deployment accelerates smartphone replacement waves across Brazil, Mexico, and Colombia.
For Market Incumbents: Fortify ANATEL certification capabilities through accredited laboratory partnerships or captive testing infrastructure to deflect new entrant price pressure. Deepen backward integration into system-in-package module sourcing to neutralize East Asian foundry allocation risk. Prioritize operator financing relationship lock-in against direct-to-consumer channel disintermediation. For New Entrants and Emerging Players: Post-sale technical support and warranty fulfillment gaps in Colombia's secondary cities offer service-layer differentiation against established Brazilian-centric networks. Target Bogotá and Medellín smartphone penetration gaps with mobile wallet-integrated device financing. Pursue direct-to-consumer online storefronts with installment checkout to bypass traditional retail markup structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding ANATEL certification infrastructure but lacking direct-to-consumer channel development. Long-term viability favors vertically integrated assemblers with Manaus Free Trade Zone manufacturing footprints over pure-import specialists. Monitor mobile operator subsidy program expansion as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Investment | Accredited laboratory capacity eliminates 8-14 week product launch delays for new device submissions. |
| Operator Financing Partnership | Bundled handset upgrade programs capture lifetime value through subscription spreads in São Paulo and Mexico City. |
| Direct-to-Consumer Channel Launch | Manufacturer-owned storefronts bypass retail markups while integrating installment payment in Chile and Peru. |
| System-in-Package Integration | Turnkey module sourcing enables regional brands to compete without silicon design capabilities. |
| Health-Monitoring Wearable Expansion | Continuous glucose and sleep tracking features target Mexico's diabetes-prevalent population segments. |
Research Methodology
A spread of perspectives from smartphone procurement managers at mobile operators, ANATEL certification consultants, electronics retail chain buyers, and component distribution executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ANATEL regulatory filings, PROFECO consumer protection disclosures, customs import records, and operator quarterly capex reports. Bottom-up smartphone shipment modeling triangulated against top-down consumer electronics spending estimates.
Segmentation dimensions modeled include product type, end user category, distribution channel, and price tier across the projection horizon. CAGRs derived from replacement cycle compression rates, 5G subscriber conversion curves, and wearables penetration trajectories. Forecast inputs incorporated mobile operator infrastructure rollout schedules and local content assembly incentive evolution.
Forecasts assume regulatory continuity in Brazil's ANATEL electromagnetic compatibility regimes and Mexico's PROFECO energy efficiency labeling frameworks; material policy shifts would require re-modeling. Semiconductor supply allocation disruptions or Argentine foreign exchange control intensification could revise volume assumptions. Practitioners should keep alternative scenarios live as mobile operator subsidy program depth and East Asian foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
4K Television Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Gaming Mouse Market