
 Global Automated Laundromat Services Market | 2026-2036
Global Automated Laundromat Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Laundromat Services Market Intelligence
A shift in the customer mix towards time-sensitive working professionals is realigning service expectations from basic self-service to full-service models. Speed Queen specializes in durable, high-efficiency machinery for operators, creating a reputation for reliability. CSC ServiceWorks leverages its extensive network within multi-family housing and university campuses to secure long-term contracts. Electrolux Professional positions its solutions around sustainability and lower utility consumption for laundromat owners.
Automated laundromat services involve the deployment of commercial laundry equipment integrated with unattended payment and control systems. These systems, which often include cloud-based monitoring, enable 24/7 operation without constant on-site staff. While traditional self-service remains the foundation, pickup & delivery services represent the fastest-growing service type. Within technology, mobile app integration is becoming a standard expectation, offering a superior user experience compared to older card payment systems or coin-operated machines.
Equipment manufacturers must comply with water and energy efficiency standards, such as those set by the EPA in the United States. In Europe, payment terminals must adhere to CE marking requirements, while app-based services that collect user data fall under the purview of GDPR. The critical decision for operators is how to phase technology upgrades, balancing investment in new payment systems and cloud monitoring with the need to maintain competitive pricing in local markets.
Market Dynamics
The convergence of IoT connectivity and mobile payment platforms is the central force shaping the market. This shift is transforming laundromats from capital-intensive, hardware-focused businesses into technology-enabled service platforms, prioritizing user experience and operational efficiency.
Growth Catalysts
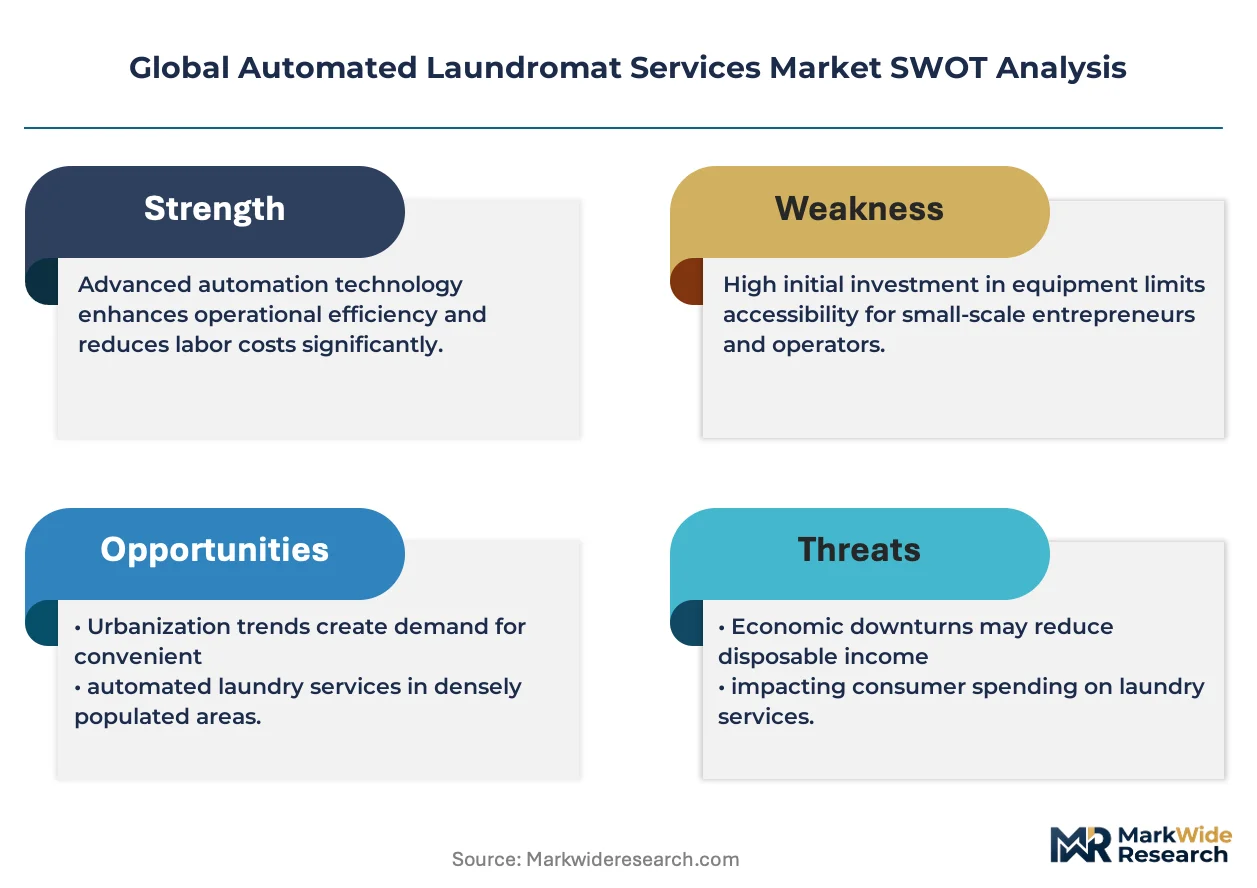
- Urban Density:Growing populations of renters in high-density housing in cities across the United States and Europe lack in-unit laundry, creating sustained demand for external services.
- Efficiency Mandates:Water and energy regulations, including EPA standards, compel operators to invest in modern equipment that often bundles automated payment and control systems.
- Mobile Payments:The ubiquity of smartphones allows for the integration of app-based payment and monitoring, offering a more convenient user experience than legacy coin or card systems.
Market Restraints
- High Capital Outlay:The significant upfront investment for new automated machinery and payment systems acts as a major financial barrier for independent operators seeking to upgrade.
- Data Privacy Compliance:Adhering to diverse data regulations like Europe's GDPR for app-based services adds operational complexity and cost for technology providers and operators.
- In-Unit Amenity Competition:The trend of including washers and dryers in new apartment construction directly reduces the available customer base for external laundromat services in those areas.
Strategic Opportunities
- Emerging Market Penetration:Expanding into dense urban centers in countries like India, where urbanization creates new demand for convenient, outsourced laundry services among working professionals.
- Subscription Model Development:Creating subscription-based, full-service wash-and-fold offerings with integrated logistics to capture recurring revenue from time-sensitive customers.
- Smart Building Integration:Partnering with property technology companies to embed laundry service booking and payment within the resident apps of smart apartment complexes and campuses.
Industry Challenges
- Legacy Equipment Integration:Operators face significant technical hurdles and costs when attempting to retrofit modern, cloud-connected payment systems onto older, disparate laundry machine models.
- User Onboarding and Education:Transitioning customers accustomed to simple coin operations to app-based payment systems requires effective user education to overcome initial resistance and confusion.
- Remote Maintenance Logistics:Ensuring rapid service response for machine failures in unattended, 24/7 locations is operationally complex and critical for maintaining revenue and customer satisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Laundromat Services Market |
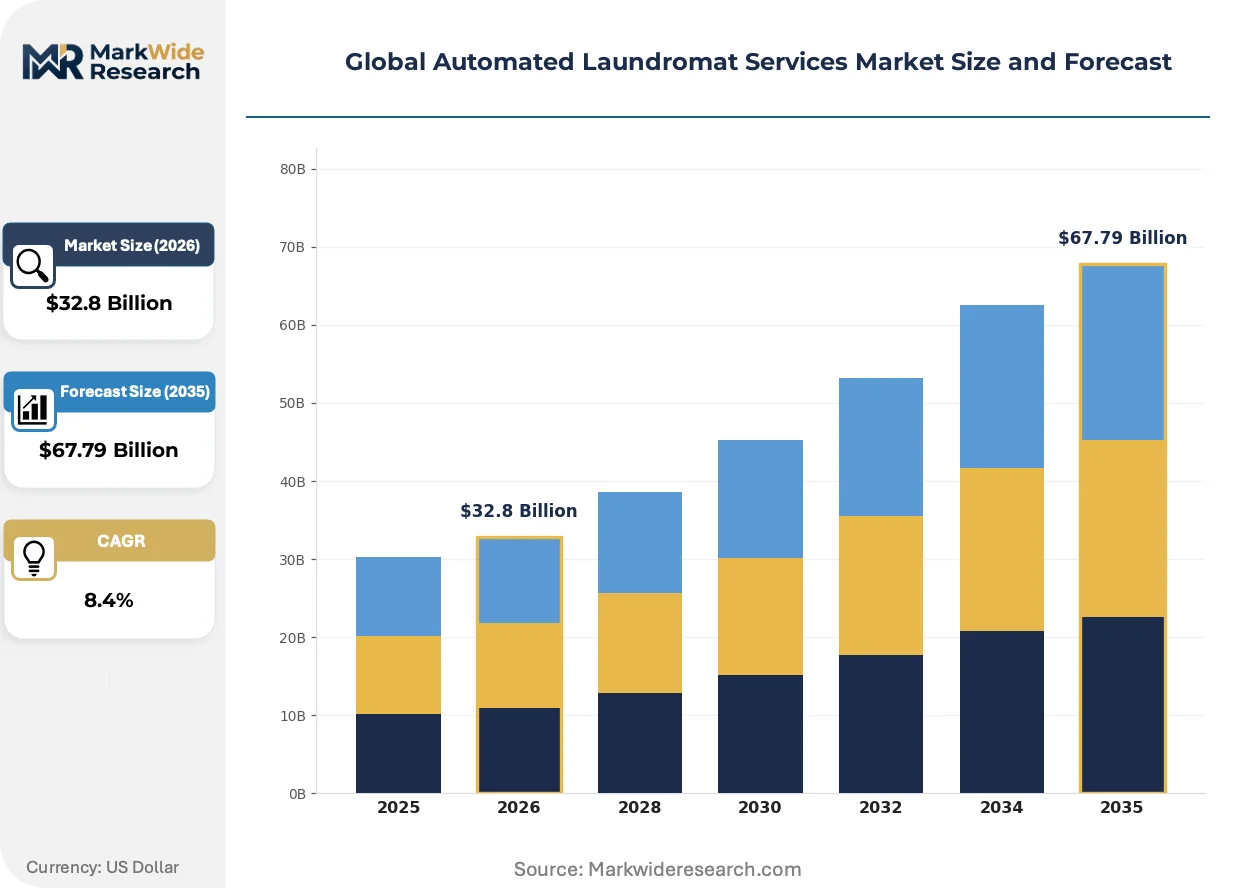
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Service, Full-Service, Pickup & Delivery, Maintenance & Repair Customer Type: Students, Tourists, Working Professionals, Senior Citizens Technology: Card Payment Systems, Mobile App Integration, Coin-Operated Machines, Cloud-Based Monitoring Deployment: Standalone Units, Mall Kiosks, Campus Locations, Residential Complexes |
| Companies Covered | CSC ServiceWorks, Huntington Cleaners & Shirt Laundry, FlyCleaners, Broomfield Launderette, DhobiLite, Speed Queen, Electrolux Professional, Continental Girbau, Dexter Laundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Laundromat Services Market Strategic Shifts & Innovations
The market's evolution centers on the shift from a transactional, hardware-centric business to a recurring, service-based model. This transformation is driven by digital platforms that redefine the relationship between operators, machines, and the end-users they serve.
Cloud-based management software integrated with IoT sensors provides operators with real-time data on machine usage, diagnostics, and revenue. Multi-location owners and franchise operators are the primary adopters, seeking centralized control. This technology is rewriting the operational playbook, enabling dynamic pricing, predictive maintenance, and remote management, fundamentally changing how laundromats are run.
Data privacy mandates, exemplified by Europe's GDPR, are imposing new requirements on service providers. The regulation requires explicit user consent for data collection and transparent policies on how payment and usage information is processed. App developers targeting the European Union are most affected, now embedding privacy-by-design principles into their software architecture.
A notable shift in preference from do-it-yourself to do-it-for-me services is gaining traction. This change disrupts the traditional self-service model in favor of full-service, subscription-based wash-and-fold offerings managed via mobile apps. The trend is most pronounced in dense urban centers in North America and Europe with large populations of time-poor professionals.
Global Automated Laundromat Services Market Segmentation
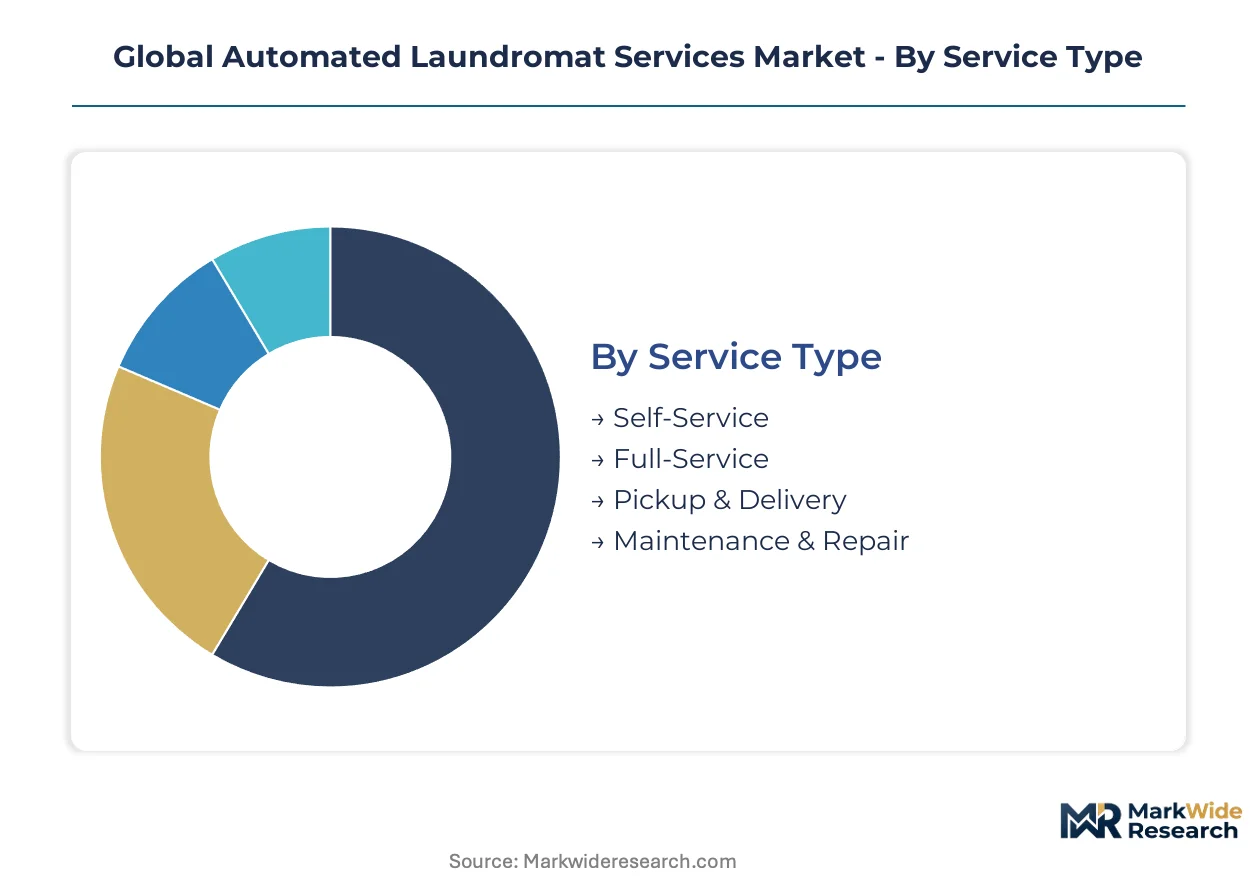
Understanding the varied segments within the automated laundromat services market allows operators to tailor offerings and technology investments effectively. Segmentation highlights distinct customer needs and operational models, informing strategic decisions for market penetration and service differentiation.
Service Type:
The availability of specialized logistics and processing infrastructure dictates the reach of advanced laundromat services.
- Pickup & Delivery:This service involves collecting laundry from a customer's location, processing it, and returning it, often managed via mobile applications. Demand is concentrating among time-constrained working professionals in dense urban centers like New York and London, seeking ultimate convenience.
- Full-Service:Customers drop off their laundry at a facility for washing, drying, and folding by staff, then pick it up later. This model appeals to individuals who prioritize time savings over cost, particularly in high-density residential areas lacking in-unit laundry facilities.
- Self-Service:Patrons use coin-operated or card-based machines to wash and dry their own clothes on-site. This traditional segment remains foundational for budget-conscious consumers.
- Maintenance & Repair:This segment encompasses the upkeep and servicing of commercial laundry equipment, ensuring operational continuity for laundromat owners.
Today's leader: Self-Service. Tomorrow's challenger: Pickup & Delivery.
Customer Type:
Diverse demographic needs shape the service offerings and operational models within automated laundromats.
- Working Professionals:This group consists of individuals with limited free time who seek convenient, often outsourced, laundry solutions. Urban density in cities across Europe and the United States drives a significant portion of this demand due to busy schedules.
- Students:University and college students living in dormitories or off-campus housing frequently rely on external laundry services. Campus locations provide a consistent customer base, often preferring app-based payment for ease of use.
- Tourists:Travelers requiring laundry services during their trips often utilize automated laundromats, valuing accessibility and quick turnaround. Hotels and short-term rentals near tourist destinations represent key demand points.
- Senior Citizens:This demographic may find automated laundromats beneficial for their ease of use or due to physical limitations preventing in-home laundry tasks.
Working Professionals represent the fastest-growing demand segment, indicating a shift towards convenience-driven services.
Technology:
The technological maturity of payment and management systems defines the user experience and operational sophistication.
- Mobile App Integration:This technology allows users to pay, start machines, monitor cycle status, and receive notifications via their smartphones. It enhances user experience and provides operators with valuable usage data, particularly in technologically advanced markets.
- Cloud-Based Monitoring:This system provides operators with real-time data on machine performance, revenue, and diagnostics from a centralized platform. Multi-location owners leverage this for predictive maintenance and dynamic pricing strategies.
- Card Payment Systems:These systems use reloadable cards for machine operation, offering a cashless alternative to traditional coins. They provide a more secure and convenient payment method than coin-only machines.
- Coin-Operated Machines:These are traditional machines that accept physical coins for payment, still prevalent in some markets due to lower initial investment.
Mobile App Integration is rapidly displacing Coin-Operated Machines, reflecting consumer preference for digital interactions.
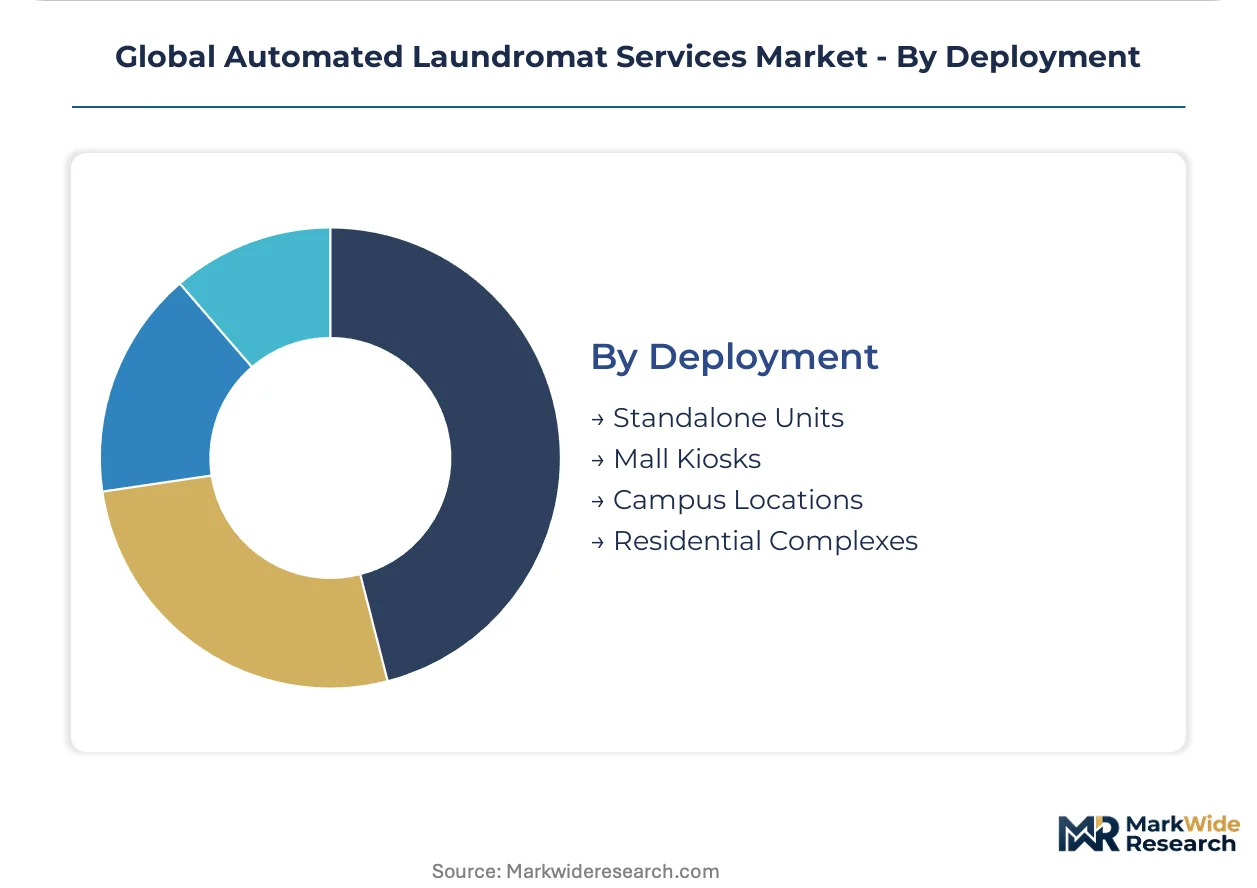
Deployment:
The physical location and surrounding population density significantly influence the viability and scale of automated laundromat deployments.
- Residential Complexes:Automated laundromats located within or near large apartment buildings serve a consistent customer base. High-density housing in cities like Berlin and San Francisco often lacks in-unit washers, creating sustained demand.
- Campus Locations:Laundromat facilities situated on university or college campuses provide essential services to students and faculty. These locations benefit from a captive audience and predictable usage patterns throughout the academic year.
- Standalone Units:These are independent laundromat businesses operating as dedicated facilities in commercial areas. They cater to a broader local community, often serving multiple customer types.
- Mall Kiosks:Smaller, often unattended laundromat setups within shopping malls provide convenience for shoppers or mall employees.
Residential Complexes and Campus Locations consistently drive high volume, making them critical deployment sites for operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-density urban residential clusters across the United States drive significant demand for automated laundromat services. This market expansion is further supported by evolving regulatory frameworks and technological advancements in payment systems. Key regions are adapting service models to meet the specific needs of their urban populations.
United States
Urban density in major metropolitan areas, coupled with a large population of working professionals, fuels demand for convenient laundry solutions. EPA standards for water and energy efficiency compel operators to invest in modern, automated equipment. Cities like New York City and San Francisco show high adoption of mobile app-based payment systems in residential complexes.
Germany
The German market benefits from a strong focus on sustainability and high-density urban living, particularly in major cities. Payment terminals must comply with CE marking requirements, ensuring product safety and quality. Berlin and Munich exhibit a concentration of smart laundromats leveraging cloud-based monitoring for operational efficiency.
United Kingdom
Demand in the United Kingdom concentrates in dense urban centers like London, driven by time-constrained working professionals seeking outsourced laundry options. GDPR regulations govern data privacy for app-based services, impacting technology providers. The London metropolitan area leads in the adoption of pickup and delivery services for ultimate convenience.
India
Rapid urbanization and a growing middle-class population in India create substantial new demand for automated laundry services. The Bureau of Indian Standards (BIS) influences equipment quality and safety requirements. Major cities such as Mumbai and Bengaluru are experiencing significant penetration of app-enabled laundromats among young professionals.
France
French urban populations, especially in cities with limited in-unit laundry facilities, increasingly utilize automated laundromats for convenience. European regulations like GDPR and CE marking are critical for service providers and equipment manufacturers. Paris and Lyon are key markets where full-service and mobile app integration are gaining traction.
Global Automated Laundromat Services Market Key Industry Players
Technology integration dominates the current landscape, transforming automated laundromat services from hardware-centric operations into sophisticated service platforms. The market structure is evolving from fragmented local businesses towards consolidated networks supported by advanced technology providers. Key archetypes include established equipment manufacturers, specialized service network operators, and innovative software developers. Strategic partnerships and geographic expansion are primary competitive moves.
Anchoring the equipment manufacturing segment, Speed Queen and Electrolux Professional exemplify distinct approaches to market leadership. Speed Queen represents a focus on durable, high-efficiency machinery, building a reputation for reliability among operators. Electrolux Professional positions its solutions around sustainability and lower utility consumption, appealing to environmentally conscious owners. CSC ServiceWorks, a prominent service network operator, leverages its extensive presence within multi-family housing and university campuses to secure long-term contracts, emphasizing operational reach and consistent service delivery.
| Leading Market Players |
|---|
| CSC ServiceWorks |
| Huntington Cleaners & Shirt Laundry |
| FlyCleaners |
| Broomfield Launderette |
| DhobiLite |
| Speed Queen |
| Electrolux Professional |
| Continental Girbau |
| Dexter Laundry |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists, consolidating regional laundromat chains, exert significant influence over both equipment procurement and end-user pricing strategies. This ownership pattern drives demand for bulk equipment purchases and integrated software solutions, impacting supplier relationships and market-wide service costs.
Pricing Analysis
Distributor margin on commercial laundry equipment often reflects the bundled value of machinery, installation, and ongoing service contracts. Subscription-based models are emerging for full-service wash-and-fold offerings, while traditional self-service typically uses a per-unit transactional model. Price differentiation stems from convenience level and technology integration, with app-enabled services commanding a premium over coin-operated machines. Pricing pressure stems from the increasing prevalence of in-unit laundry amenities in new residential construction. Budget-conscious consumers utilizing self-service laundromats exhibit the highest price sensitivity, whereas time-sensitive working professionals are less sensitive to pricing for premium services.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly common among major equipment manufacturers to mitigate supply risks. Geographic supply concentration for commercial laundry equipment components primarily resides in China, Germany, and Italy. The industry depends on raw materials such as stainless steel for machine casings and microcontrollers for digital payment systems. Single-source vulnerability for specialized payment terminal components represents a structural risk. Distribution runs through established networks of equipment dealers and direct sales channels to large operators and multi-location franchises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated laundromat services market is a stable compounder, driven by sustained urban population growth and the increasing demand for convenience among working professionals.
For Market Incumbents:To counter the threat of in-unit amenity competition, incumbents should aggressively upgrade legacy equipment with integrated mobile payment and cloud monitoring systems. Expand full-service pickup & delivery offerings, leveraging existing operational infrastructure and customer trust. Invest in software integration capabilities to provide a seamless user experience across all service types, reinforcing customer loyalty through convenience and reliability.
For New Entrants and Emerging Players:Launch via strategic partnerships with property management companies in high-density residential complexes and university campuses. The most penetrable segment is app-based, full-service wash-and-fold targeting time-poor urban professionals. Focus on a strong technology-first go-to-market angle, emphasizing user-friendly mobile interfaces and transparent real-time service tracking for superior customer engagement.
For Investors and Strategic Acquirers:Valuations sit cheapest among fragmented independent operators with outdated equipment, offering consolidation opportunities. The long-term viability favors technology-enabled service platforms with recurring revenue streams and strong regional presence. Acquire specialized software developers to enhance platform capabilities and capture market share. The signal to watch is the percentage of revenue generated from subscription-based services, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Mobile Payment Platforms | Operators enhance user convenience and collect valuable usage data for operational optimization. |
| Expand Pickup & Delivery Services | Businesses capture recurring revenue from time-sensitive working professionals in urban centers. |
| Form Smart Building Partnerships | Service providers gain direct access to captive customer bases within modern residential complexes. |
| Invest in Predictive Maintenance Software | Laundromat owners minimize machine downtime and reduce operational costs through proactive servicing. |
| Consolidate Regional Independent Operators | Large players achieve economies of scale and expand geographic reach for service delivery. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to ensure a robust data foundation. Primary research involved discussions with laundromat owners, equipment manufacturers, software developers, and property managers. Secondary data sources included industry association reports, financial filings of public companies, technology patent databases, and urban development statistics. This approach facilitated bottom-up and top-down triangulation for market sizing.
The forecast framework anchored the analysis window to historical reference periods, ensuring continuity and relevance. Segmentation dimensions modeled included service type, customer type, technology, deployment, and regional regulatory frameworks. Compound annual growth rates were derived from a comprehensive historical trend analysis and future projection based on identified market dynamics. Key industry-specific forecast inputs included urban population growth rates and smartphone penetration rates.
Several conditions sit outside the modeled scope, including unforeseen macroeconomic shocks or rapid shifts in global housing trends. Forecasts reflect assumptions regarding current technological trajectories and regulatory stability. Deviation in consumer preferences for in-home laundry solutions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Smart TV Market