
 Speakerphones Market | 2026-2036
Speakerphones Market Size, Share, and Industry Trends Forecast 2026-2036
Speakerphones Market Analytics
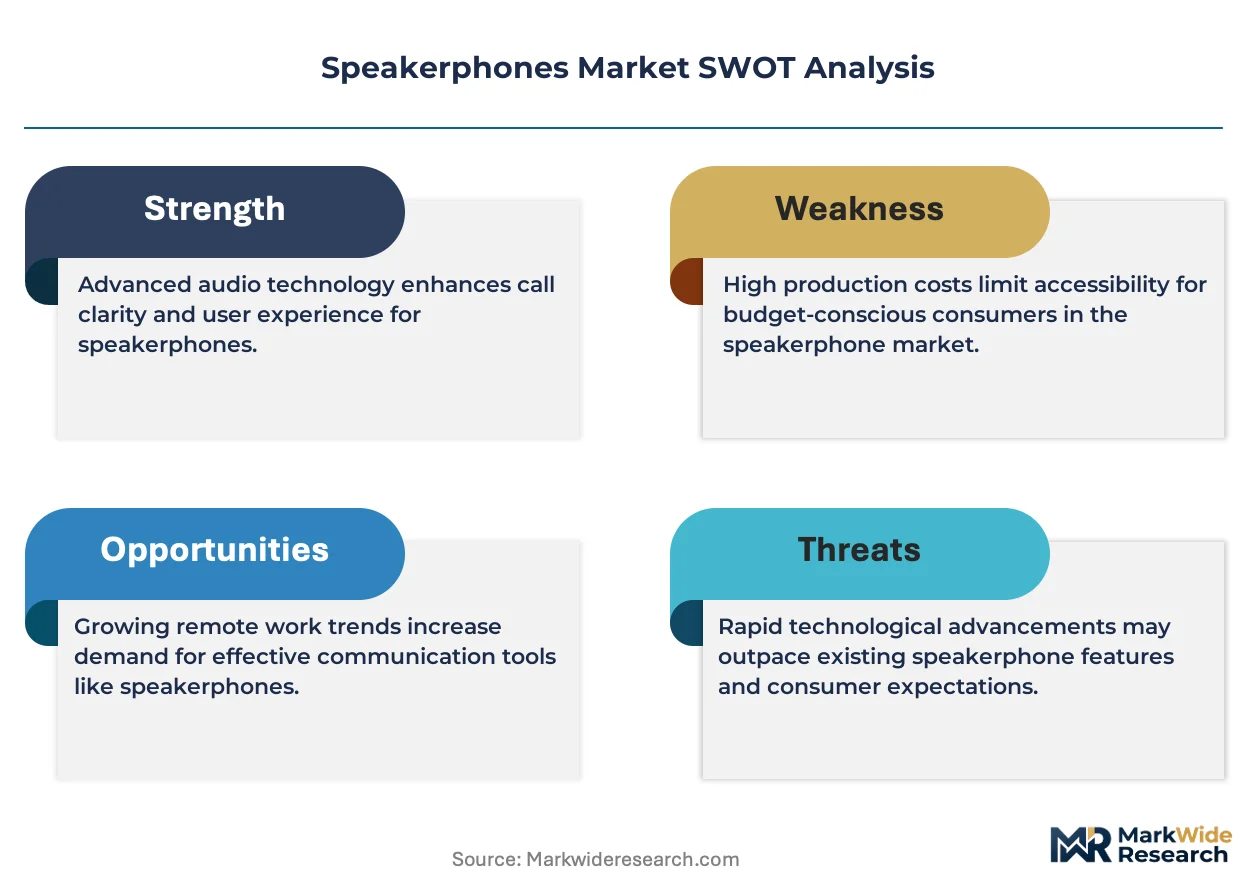
The gap between premium and commodity speakerphone tiers is broadening. Enterprise buyers now separate acoustic performance, AI noise suppression, and multi-device orchestration from basic tabletop units. Jabra leverages its heritage in professional audio to sustain engineering credibility in high-ASP conference products. Logitech competes through channel density, anchoring retail and direct-to-business fulfillment networks that commodity OEMs cannot replicate. Poly differentiates via legacy installed-base migration, converting telephone-centric customers toward unified-communications endpoints.
Speakerphones are electroacoustic transducer assemblies engineered for full-duplex voice reproduction in shared environments, typically integrating microphone arrays with loudspeaker drivers, digital signal processors, and network interfaces to enable group telephony. Modern units incorporate beamforming microphone arrays with pickup ranges exceeding five meters and acoustic echo cancellation algorithms operating below fifty milliseconds latency. Wireless and Bluetooth product types now lead volume growth as cable-free deployment simplifies huddle-room retrofits, while USB segments retain margin concentration through enterprise security and firmware management requirements. Corporate end users represent the deepest demand pool, though educational institutions show faster expansion as hybrid learning infrastructure standardizes on voice-optimized peripherals.
FCC equipment authorization requirements govern RF emissions for wireless speakerphones sold in the United States, while CE marking under the EU Radio Equipment Directive regulates Bluetooth and Wi-Fi spectrum compliance across European member states. REACH restrictions on hazardous substances in electronics affect material selection for housings and circuit assemblies, pushing manufacturers toward halogen-free flame retardants. Stakeholders must monitor whether emerging AI voice-processing capabilities trigger additional privacy certifications under GDPR voice-data provisions or sector-specific healthcare communication standards.
Market Dynamics
USB-C connectivity mandates and Bluetooth LE Audio certification requirements in North America and Europe are forcing procurement specification rewrites across enterprise IT departments, compressing legacy analog product lifecycles while elevating firmware-managed endpoints.
Growth Catalysts
- Hybrid Work Infrastructure:Corporate real estate reconfigurations in the United States are driving huddle-room audio upgrades as facilities teams standardize on voice-optimized peripherals for distributed meeting equity.
- FCC Equipment Authorization:RF emissions compliance for wireless speakerphones sold in the United States creates a certification moat that filters out unqualified commodity OEMs, protecting margin pools for certified suppliers.
- Beamforming Arrays:Five-meter-plus pickup ranges enabled by microphone array DSPs are displacing basic tabletop units in mid-market conference rooms where acoustic performance now outweighs price sensitivity.
Market Restraints
- Silicon Supply Concentration:DSP and Bluetooth SoC fabrication concentrates among Taiwan-based foundries, exposing speakerphone manufacturers to geopolitical supply interruptions and allocation rationing.
- REACH Substance Restrictions:Halogen-free flame retardant sourcing for housings and circuit assemblies increases material costs and narrows qualified supplier pools across European-bound production lines.
- Smartphone Substitution:Native speakerphone modes in flagship handsets and tablets threaten basic tabletop segment volumes in price-sensitive small-office deployments.
Strategic Opportunities
- Educational Hybrid Learning:Voice-optimized peripheral standardization in K-12 and university IT refresh cycles offers faster expansion than saturated corporate verticals, particularly in district-wide deployment tenders.
- GDPR Voice-Data Provisions:Emerging AI voice-processing capabilities trigger additional privacy certification requirements that first-mover vendors can weaponize as competitive differentiation in European enterprise accounts.
- Healthcare Communication Standards:Sector-specific HIPAA-aligned endpoint certifications for telemedicine consultation rooms create a premium segment insulated from commodity pricing pressure.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Full-duplex echo cancellation algorithm development and anechoic chamber validation expertise concentrates among a handful of audio-specialist firms, constraining in-house R&D scaling.
- Multi-Protocol Certification Timelines:Simultaneous Bluetooth SIG, USB-IF, and Zoom/Teams hardware certification requirements extend product launch windows and increase pre-revenue engineering burn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speakerphones Market |
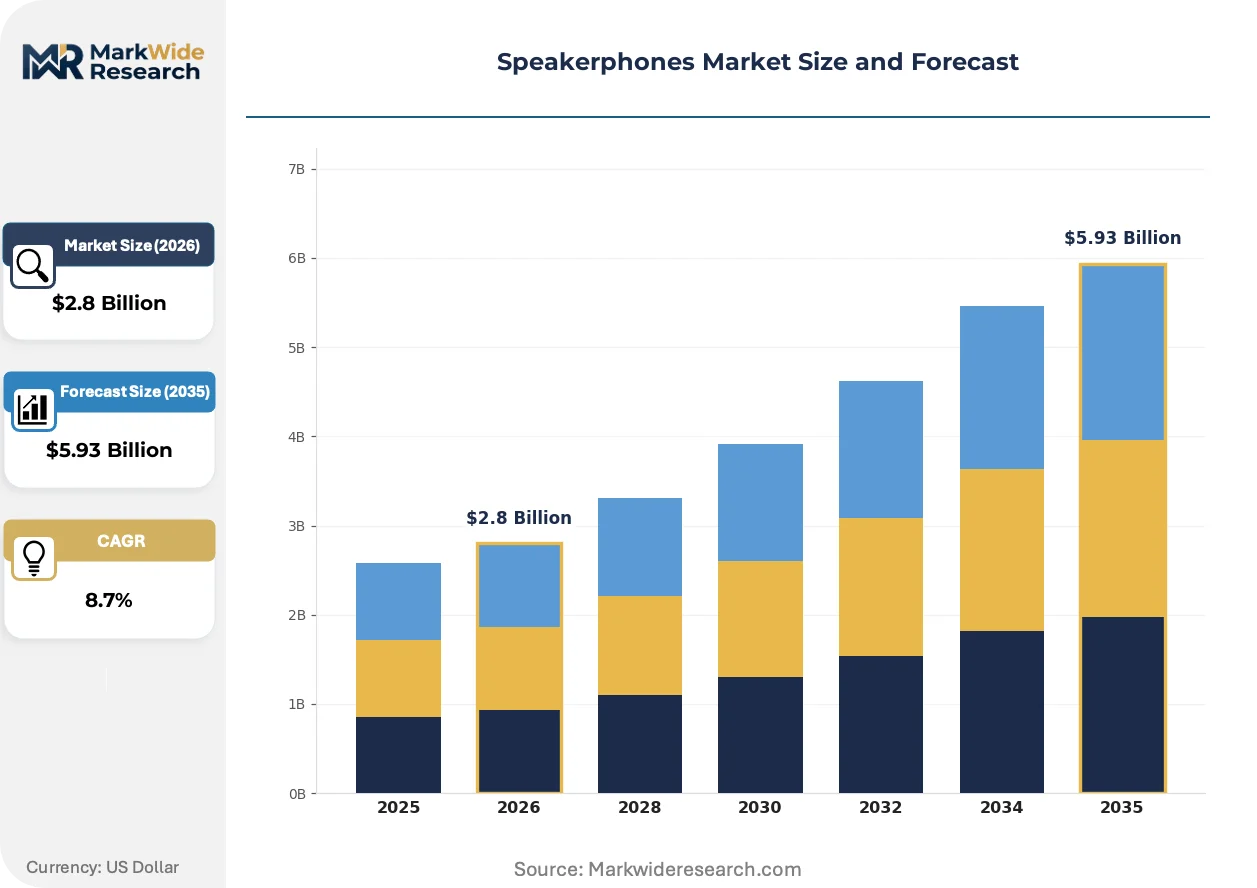
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, USB, Bluetooth End User: Corporate, Educational Institutions, Call Centers, Homes Technology: Analog, Digital, VoIP, Hybrid Feature: Noise Cancellation, HD Audio, Voice Recognition, Multipoint Connectivity |
| Companies Covered | Sennheiser, Logitech, Jabra, Shure, Panasonic, Poly, Konftel, Beyerdynamic, Yealink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speakerphones Market Evolving Landscape
AI inference at the edge is compressing latency budgets for real-time noise suppression while procurement specifications increasingly weight firmware update lifecycles alongside acoustic metrics.
Beamforming microphone arrays with embedded neural processing units are integrating on-device voice isolation that eliminates cloud dependency for sensitive conversations. Financial services and legal sector buyers in the United States are prioritizing these endpoints for client confidentiality compliance. The technology is integrating acoustic echo cancellation directly into array hardware, reducing host processor load and enabling thinner client deployments.
CE marking under the EU Radio Equipment Directive now encompasses cybersecurity baseline requirements for Bluetooth and Wi-Fi spectrum compliance, adding penetration testing documentation to technical construction files. Manufacturers serving European member states must embed secure boot chains and signed firmware updates. Medical and legal end-use verticals face the steepest compliance burden as voice-data sensitivity intersects with MDR and GDPR adjacency.
Enterprise IT departments are consolidating vendor relationships around unified-communications platform certification tiers rather than standalone audio specifications. Direct-to-business fulfillment networks with same-day replacement logistics are displacing traditional distributor stocking models for mid-market accounts. This concentration is most visible in the United States where hybrid work infrastructure spending sustains premium segment pull-through against commodity alternatives.
Speakerphones Market Segmentation
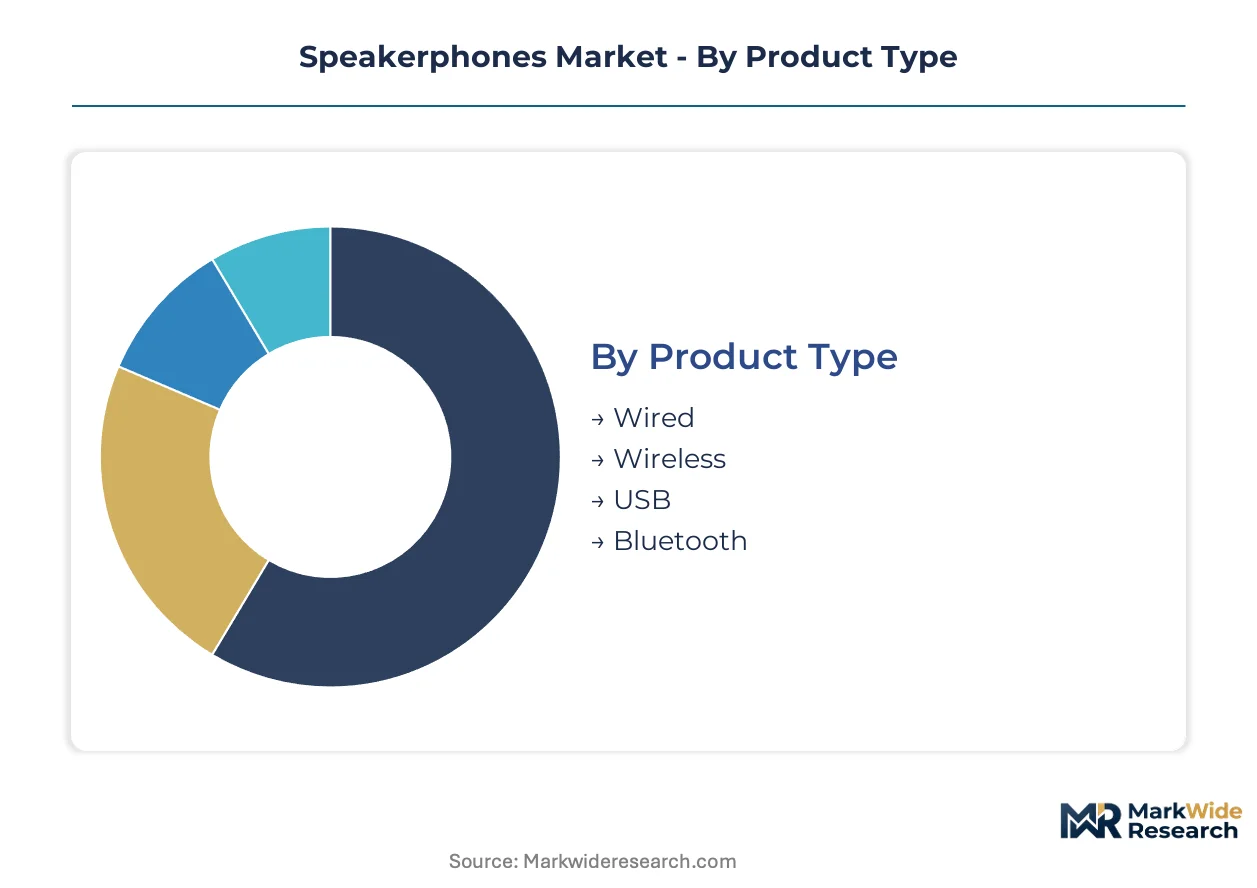
Speakerphone procurement specifications fragment across connectivity standards, acoustic performance tiers, and compliance regimes. IT refresh cycles force buyers to reconcile legacy infrastructure with emerging USB-C mandates and Bluetooth LE Audio certification requirements.
Product Type:
Enterprise upgrade timelines diverge sharply between cable-free retrofits and firmware-managed wired deployments.
- Wireless:Radio-frequency endpoints with integrated battery management and beamforming arrays enable huddle-room reconfigurations without structural cabling. United States corporate real estate teams favor these units for rapid deployment in satellite offices where meeting equity for remote participants drives specification authority.
- USB:Tethered connectivity through USB-C or legacy USB-A interfaces delivers enterprise-grade security with centralized firmware management and host processor dependency for DSP offload. IT departments in regulated industries mandate these endpoints for audit-compliant meeting room infrastructure.
- Bluetooth:Short-range wireless protocol implementations prioritize personal workspace flexibility and smartphone pairing workflows over group acoustic performance.
- Wired:Analog or digital tethered connections persist in cost-constrained small-office deployments where electromagnetic interference resilience outweighs cable management concerns.
Wireless sits at the top of the volume ranking, with USB climbing the fastest.
End User:
Demand concentration varies by procurement authority structure and budget cycle timing.
- Corporate:Enterprise IT departments with standardized unified-communications platforms drive premium segment specification through platform certification requirements and same-day replacement logistics contracts. United States hybrid work infrastructure spending sustains this vertical's margin concentration against commodity alternatives.
- Educational Institutions:K-12 districts and university systems execute district-wide refresh cycles with faster expansion trajectories than saturated corporate accounts, particularly where hybrid learning infrastructure standardizes on voice-optimized peripherals for lecture capture and remote student participation.
- Call Centers:Agent-desk deployments prioritize acoustic echo cancellation and full-duplex voice reproduction for customer interaction quality monitoring.
- Homes:Individual purchasers in remote work arrangements substitute native smartphone speakerphone modes for dedicated peripherals in price-sensitive segments.
Corporate commands the largest revenue pool, with educational institutions gaining share fastest.
Technology:
Signal processing architecture determines compliance burden and interoperability depth.
- Digital:Native digital signal processing with embedded DSP chips enables real-time beamforming, noise suppression, and firmware-upgradeable feature expansion. FCC equipment authorization requirements for RF emissions create certification moats that filter unqualified suppliers in United States-bound shipments.
- VoIP:Packet-switched voice transmission over IP networks integrates directly with unified-communications platforms, displacing circuit-switched alternatives in enterprise greenfield deployments.
- Hybrid:Dual-mode analog-digital architectures bridge legacy telephone infrastructure with modern UC platforms during migration windows.
- Analog:Continuous signal transmission persists in legacy installed bases and cost-minimized small-office segments where digital conversion adds unacceptable latency.
Digital dominates current procurement specifications, with VoIP expanding most quickly.
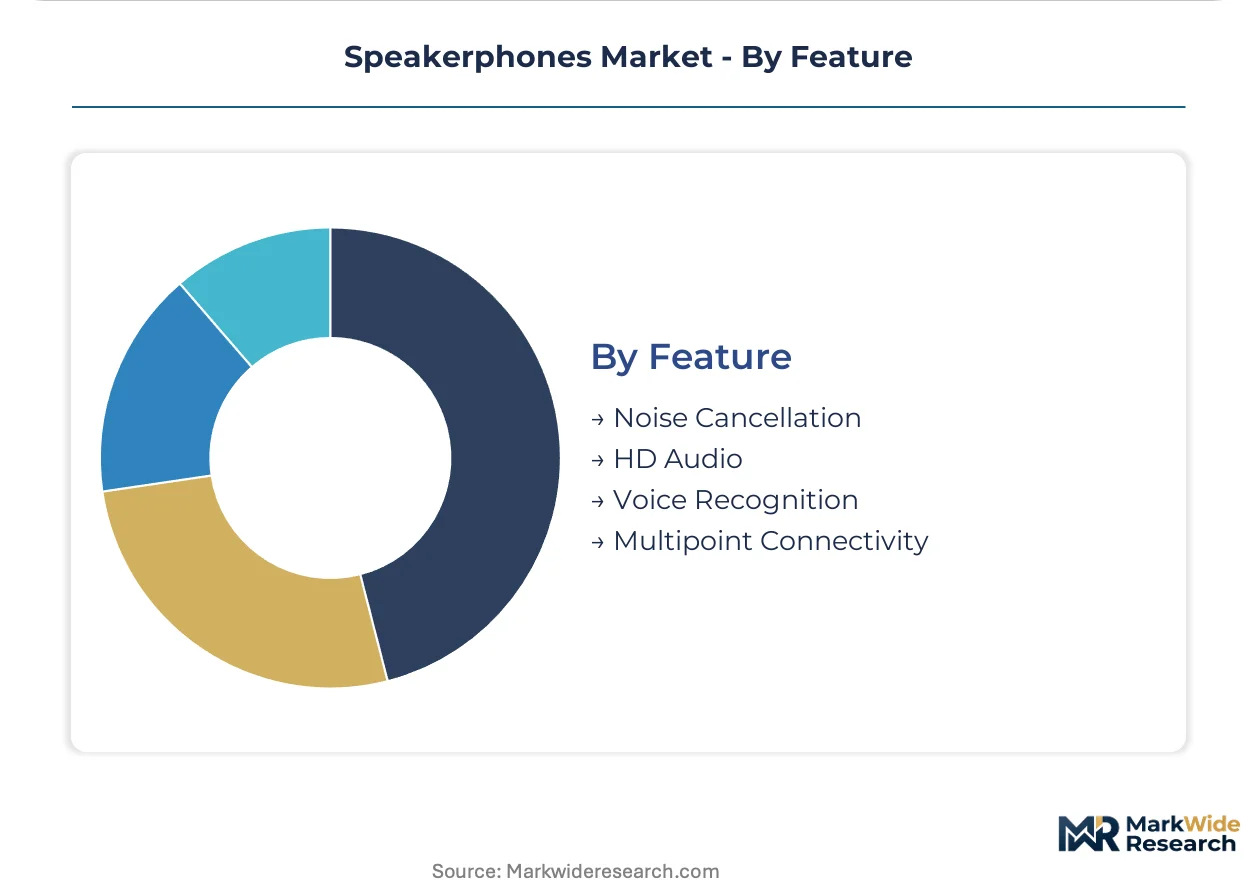
Feature:
Capability bundles separate premium pricing tiers from commodity tabletop units.
- Noise Cancellation:AI inference at the edge with neural processing units enables real-time voice isolation without cloud dependency. Financial services and legal sector buyers in the United States prioritize these endpoints for client confidentiality compliance under professional responsibility standards.
- HD Audio:Wideband frequency response beyond traditional telephone narrowband specifications improves intelligibility for accented speech and technical vocabulary in multinational corporate deployments.
- Voice Recognition:On-device speaker identification and command processing trigger additional GDPR voice-data provision scrutiny in European enterprise accounts.
- Multipoint Connectivity:Simultaneous pairing with multiple host devices supports workflow transitions between personal and conference room contexts.
Noise Cancellation leads premium tier attachment rates, with Voice Recognition climbing fastest amid AI capability proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise IT refresh cycles outpace German procurement velocity, while educational hybrid learning infrastructure in India accelerates faster than saturated corporate verticals in Japan. Regulatory fragmentation across FCC equipment authorization, CE marking under the EU Radio Equipment Directive, and India's BIS certification creates divergent compliance burdens.
United States
Corporate real estate reconfigurations and hybrid work infrastructure spending drive huddle-room audio upgrades. FCC equipment authorization requirements for RF emissions filter unqualified commodity OEMs, protecting margin pools for certified suppliers. San Francisco Bay Area technology campuses standardize on voice-optimized peripherals with same-day replacement logistics.
Germany
REACH substance restrictions on halogen-free flame retardants increase material costs for European-bound production lines. CE marking under the EU Radio Equipment Directive now encompasses cybersecurity baseline requirements for Bluetooth compliance. Bavaria's industrial manufacturing clusters concentrate acoustic engineering talent for full-duplex echo cancellation development.
China
Domestic unified-communications platform adoption and government-led smart office initiatives expand procurement volumes. MIIT radio transmission equipment type approval governs Bluetooth and Wi-Fi spectrum compliance for locally manufactured endpoints. Shenzhen's electronics manufacturing ecosystem supplies DSP and Bluetooth SoC components to international speakerphone brands.
India
K-12 district-wide refresh cycles and university hybrid learning infrastructure standardize on voice-optimized peripherals faster than saturated corporate accounts. BIS certification requirements for electronic goods create entry barriers for uncertified imports. Karnataka's Bangalore technology corridor hosts multinational IT services firms driving enterprise endpoint demand.
Japan
Corporate telephony infrastructure migration toward unified-communications platforms sustains replacement demand in legacy-installed bases. METI industrial standards and JIS certification frameworks regulate electromagnetic compatibility for conference room electronics. Tokyo's dense commercial real estate limits huddle-room deployment flexibility, favoring compact beamforming array designs.
Speakerphones Market Competitive Landscape
Top-tier vendors anchor premium certification tiers, while mid-market specialists compete on channel density and price-accessible beamforming. The vendor base stratifies across professional audio heritage, consumer electronics scale, and telecommunications legacy migration capabilities. Two dominant competitive moves are emerging: platform certification consolidation around Microsoft Teams and Zoom hardware programs, and direct-to-business fulfillment network expansion with same-day replacement logistics.
Within the professional audio heritage tier, Sennheiser and Shure exemplify engineering credibility sustained through anechoic chamber validation expertise and broadcast-industry lineage. Jabra and Logitech occupy distinct positioning vectors—Jabra through professional audio credibility in high-ASP conference products, Logitech through retail and direct-to-business channel density that commodity OEMs cannot replicate. Poly anchors the telecommunications legacy migration archetype, converting telephone-centric installed bases toward unified-communications endpoints.
| Leading Market Players |
|---|
| Sennheiser |
| Logitech |
| Jabra |
| Shure |
| Panasonic |
| Poly |
| Konftel |
| Beyerdynamic |
| Yealink |
| Others |
Value Network & Pricing Analysis
DSP and Bluetooth SoC fabrication costs in Taiwan-based foundries cascade through speakerphone pricing tiers, compressing margins for mid-market OEMs while premium vendors with certification moats capture firmware-managed ASP premiums from enterprise IT departments in the United States and Germany.
Pricing Analysis
Capacity additions in China's Shenzhen electronics corridor are reshaping price floors for commodity speakerphone tiers, forcing incumbents to differentiate through three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FCC equipment authorization tier and beamforming array performance grade. Cost compression in economy segments intensifies because smartphone substitution threatens basic tabletop volumes. Educational institutions exhibit highest price sensitivity, while financial services buyers in the United States demonstrate lowest sensitivity due to client confidentiality compliance requirements.
Supply Chain Analysis
Direct-to-business channels handle hyperscale enterprise demand with same-day replacement logistics, displacing traditional distributor stocking models. Component fabrication concentrates in Taiwan, China, and South Korea, with DSP chips, microphone MEMS sensors, and Bluetooth SoCs as critical inputs. Single-source vulnerability in Taiwan-based foundry capacity exposes manufacturers to geopolitical allocation rationing. Distribution runs through certified supplier networks anchored by platform certification tiers from Microsoft Teams and Zoom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speakerphone market economics favor margin expansion through AI noise suppression premium-tier attachment and halogen-free flame retardant cost-down initiatives in European-bound production lines.
For Market Incumbents: Anticipate smartphone substitution threats in basic tabletop segments by accelerating beamforming array integration into mid-market SKUs and deepening backward integration into DSP chip sourcing from Taiwan-based foundries to secure allocation priority during supply crunches. For New Entrants and Emerging Players: Unified-communications platform certification programs offer the most penetrable entry vector for unlicensed OEMs, particularly through white-label partnerships with channel partners serving K-12 educational institutions in India where district-wide refresh cycles outpace saturated corporate verticals. For Investors and Strategic Acquirers: Roll-up economics work for acoustic engineering specialists because full-duplex echo cancellation algorithm development expertise concentrates among a handful of audio-specialist firms with anechoic chamber validation capabilities. Long-term viability favors targets with HIPAA-aligned endpoint certifications for telemedicine verticals. Monitor Bluetooth LE Audio certification completion rates as inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Certification Consolidation | Microsoft Teams and Zoom hardware programs anchor enterprise procurement specifications, filtering uncertified competitors. |
| Direct-to-Business Fulfillment Expansion | Same-day replacement logistics contracts with United States corporate IT departments displace traditional distributor models. |
| AI Edge Inference Integration | Neural processing units embedded in beamforming arrays enable on-device voice isolation for GDPR-sensitive European accounts. |
| Educational Vertical Penetration | District-wide deployment tenders in India's K-12 systems outpace saturated corporate refresh cycles. |
| Healthcare Endpoint Certification | HIPAA-aligned speakerphone certifications create premium segment insulation from commodity pricing pressure. |
Research Methodology
Multiple input streams — primary interviews with unified-communications platform engineers, enterprise IT procurement officers, and acoustic R&D directors; secondary validation through FCC equipment authorization databases, Bluetooth SIG certification listings, and SEC filings from publicly traded audio equipment manufacturers; plus customs and trade data from United States and European import records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across connectivity standards, acoustic performance tiers, and end-user verticals generated volume and value outputs over the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology architecture, and regional regulatory cluster. CAGRs derived from historical shipment trajectories and procurement specification evolution, with forecast inputs incorporating IT refresh cycle timing and certification mandate compliance deadlines.
Revisions become necessary when FCC equipment authorization timelines extend, REACH substance restrictions tighten, or Taiwan-based foundry allocation rationing materializes. Forecasts reflect documented assumptions regarding hybrid work infrastructure spending persistence and platform certification consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Portable Laptop Stands Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Earphones Market
Consumer Electronics
Foldable Phone Market