
 Out-Door Signage Market | 2026-2036
Out-Door Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Out-Door Signage Market Outlook
ISO 14001 environmental management certification is unwinding competitive barriers for outdoor signage fabricators seeking municipal contracts in European cities. JCDecaux leverages its vertically integrated manufacturing footprint across France and Germany to sustain premium positioning in street furniture advertising. Lamar Advertising Company anchors its dominance through dense billboard portfolios along interstate corridors in the United States.
Outdoor signage encompasses freestanding, wall-mounted, and suspended visual communication structures fabricated from plastic, metal, wood, or fabric substrates, typically engineered to withstand wind loads and UV degradation while delivering brand messaging or wayfinding functions in public spaces. Digital signage now captures the fastest-expanding margin pool as LED module costs decline and content management platforms enable real-time advertiser analytics. Billboards retain the largest installed base but face structural pressure from shorter-term digital campaign contracts that reduce committed revenue visibility.
EPA emissions standards for vinyl substrate production and REACH chemical registration requirements in Europe are reshaping material sourcing decisions across the supply chain. The EU AI Act's transparency provisions for automated content delivery will soon govern algorithmic ad rotation on connected digital displays. Stakeholders must monitor how municipal zoning boards reconcile aesthetic preservation mandates with revenue-sharing agreements for smart city signage infrastructure.
Market Dynamics
LED module cost deflation is compressing payback periods for digital billboard conversions, while municipal revenue-sharing frameworks for smart city infrastructure are redrawing competitive terrain between outdoor advertising operators and urban technology vendors.
Growth Catalysts
- EU Green Deal material mandates:Substrate disclosure requirements are accelerating PVC-to-aluminum transitions across French and German installations, creating replacement demand for compliant fabrication capacity.
- São Paulo zoning liberalization:Brazil's largest metropolitan market streamlined digital billboard permitting in 2024, unlocking inventory expansion for street-level LED networks.
- Real-time content management platforms:Cloud-based ad rotation systems enable programmatic inventory trading, attracting data-driven advertisers from e-commerce and fintech verticals.
Market Restraints
- Epoxy resin supply volatility:LED encapsulant feedstock prices fluctuate with Asian petrochemical output, squeezing module assembler margins during contract pricing cycles.
- REACH chemical registration burdens:European substrate coating formulations face multi-year toxicity evaluation timelines, delaying product launches versus non-EU competitors.
- Static vinyl inventory overhang:Traditional printed billboard substrates retain 60-plus percent of US installed base, creating asset stranding risk for dedicated digital converters.
Strategic Opportunities
- Smart city infrastructure convergence:5G small cell integration into street furniture units creates dual-revenue streams for municipalities and operators in Barcelona and Amsterdam.
- ISO 14001 certification arbitrage:Environmental management credentials unlock municipal contract eligibility in Scandinavian cities with green procurement mandates.
- Wayfinding-digital hybrid formats:Transit authority partnerships in Singapore and Dubai combine navigation utility with advertising inventory, commanding premium CPM rates.
Industry Challenges
- Electrical contractor certification gaps:High-voltage LED installation licensing requirements outpace vocational training program throughput in several US states.
- Legacy content management system fragmentation:Proprietary protocols from 2015-2019 hardware generations complicate network-wide software updates and cybersecurity patching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Out-Door Signage Market |
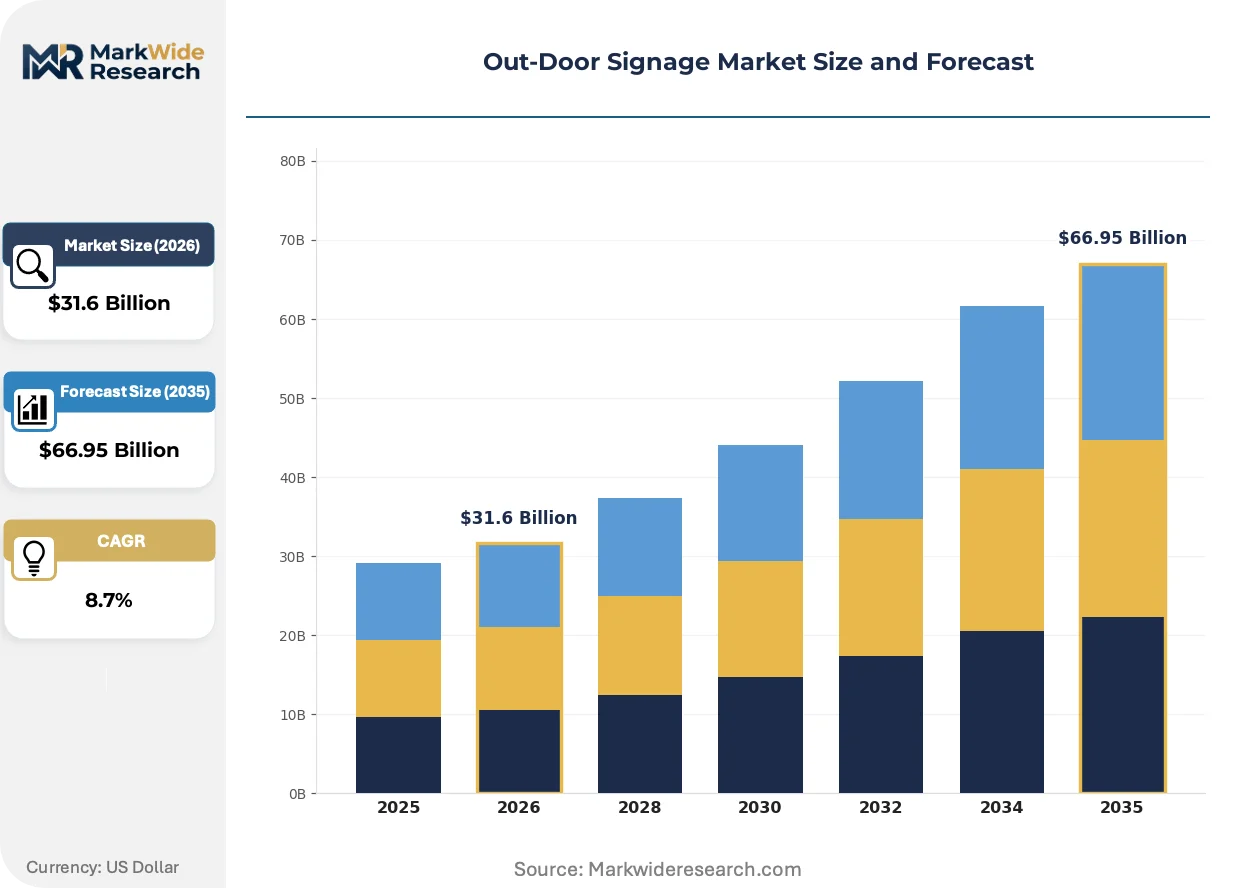
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $66.95 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billboards, Banners, Pylons, Digital Signage Material: Plastic, Metal, Wood, Fabric Installation Type: Freestanding, Wall-Mounted, Suspended, Ground Sign End User: Retail, Transportation, Event Organizers, Government |
| Companies Covered | Clear Channel Outdoor Holdings, Outfront Media, JCDecaux, Lamar Advertising Company, Daktronics, Samsung Electronics, LG Electronics, Avery Dennison Corporation, Ströer SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Out-Door Signage Market Strategic Shifts
Technological substitution and regulatory disclosure mandates are converging to accelerate format turnover, while procurement sophistication among advertisers is compressing contract tenures and elevating performance transparency requirements.
MicroLED display modules are displacing conventional SMD LED packages in premium urban installations due to superior daylight visibility and energy efficiency. Luxury automotive and beverage brands now specify microLED specifications for flagship campaigns in Times Square and Shibuya Crossing. This displacement is compressing residual value calculations for SMD-based inventory purchased between 2019 and 2022.
EPA emissions standards for vinyl chloride monomer production are tightening feedstock costs for traditional printed substrate manufacturers. The industrial consequence is accelerated plant consolidation among US-based PVC film extruders. Large-format printing houses in Texas and California are responding by diversifying into textile-based dye-sublimation alternatives for temporary installations.
Advertiser procurement teams now mandate impression verification through independent audience measurement rather than publisher-reported metrics. Media buying agencies are disintermediating direct site-owner relationships in favor of programmatic exchanges with third-party validation. This behavioral shift is most visible in London and New York, where out-of-home now commands digital-style accountability terms.
Out-Door Signage Market Segmentation
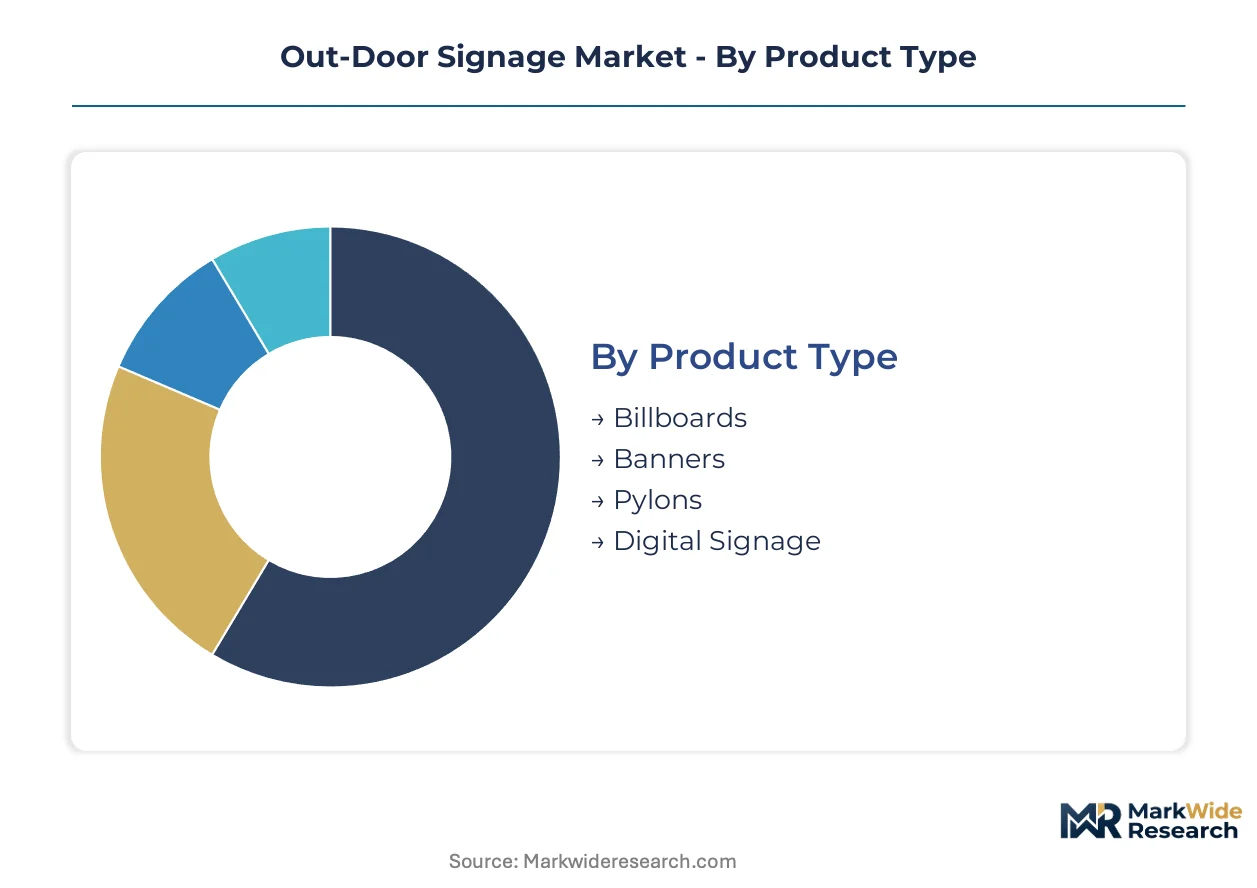
Outdoor signage procurement patterns diverge sharply across product formats, with legacy static formats dominating replacement cycles while digital installations concentrate in high-traffic urban corridors. Material selection and mounting configuration determine regulatory compliance pathways and installation cost structures across municipal jurisdictions.
Product Type:
Domestic demand concentrates in static formats for highway corridors, while digital deployments skew toward export-led metropolitan networks in São Paulo and Dubai.
- Billboards:Large-format static or digital displays engineered for maximum visibility along interstate corridors and urban arterials. Lamar Advertising anchors its US dominance through dense portfolio concentration along major highway systems, though shorter-term digital campaign contracts erode committed revenue visibility versus legacy vinyl leases.
- Digital Signage:LED-based connected displays enabling real-time content rotation and programmatic inventory trading. São Paulo's streamlined permitting codes accelerated inventory expansion for street-level networks, while luxury automotive brands now specify microLED specifications for flagship campaigns in Times Square and Shibuya Crossing.
- Banners:Flexible printed substrates suspended from building facades or street furniture for temporary promotional campaigns.
- Pylons:Freestanding vertical structures common at retail entries and transportation hubs for wayfinding and brand identification.
Billboards hold the largest share; momentum sits with Digital Signage.
Material:
Cost tiers separate commodity substrates from premium alternatives, with regulatory pressure forcing mid-tier substitutions.
- Plastic:PVC and polyethylene films dominate large-format printing for temporary installations. EPA emissions standards for vinyl chloride monomer production are tightening feedstock costs and accelerating plant consolidation among US-based extruders.
- Metal:Aluminum and steel substrates provide structural durability for permanent installations and digital display housings. EU Green Deal material disclosure mandates are accelerating PVC-to-aluminum transitions across French and German fabrication facilities.
- Wood:Traditional substrate for rustic aesthetic applications in recreational and hospitality settings.
- Fabric:Textile-based dye-sublimation alternatives gaining share among Texas and California printing houses seeking temporary installation flexibility.
Plastic retains volume leadership; aluminum substrates are climbing the fastest on regulatory tailwinds.
Installation Type:
Application context determines structural engineering requirements and municipal permitting complexity.
- Freestanding:Self-supporting structures including pylons and monument signs requiring foundation engineering. These units face the most stringent wind load calculations and zoning setback requirements.
- Wall-Mounted:Building-attached displays common in dense urban cores where ground space is constrained. JCDecaux leverages vertically integrated manufacturing across France and Germany to sustain premium positioning in street furniture advertising.
- Suspended:Overhead installations spanning pedestrian corridors and transit platforms.
- Ground Sign:Low-profile directional and wayfinding markers typical of retail campuses and healthcare facilities.
Freestanding captures the greatest installed base; wall-mounted formats are gaining share fastest in space-constrained metropolitan districts.
End User:
Customer type dictates contract tenure, with government and transportation authorities favoring multi-year agreements versus retail's campaign-based procurement.
- Retail:Chains are expanding digital screen networks in urban cores and mandating impression verification through independent audience measurement. Procurement teams now favor programmatic exchanges with third-party validation over direct site-owner relationships.
- Transportation:Transit authority partnerships in Singapore and Dubai combine navigation utility with advertising inventory, commanding premium CPM rates through wayfinding-digital hybrid formats.
- Event Organizers:Temporary installation demand peaks around major sporting and cultural programming.
- Government:Municipal procurement increasingly requires ISO 14001 environmental management certification for contract eligibility in Scandinavian cities with green procurement mandates.
Retail commands the greatest revenue concentration; transportation partnerships are expanding most quickly through smart city infrastructure convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail procurement teams and municipal governments anchor demand across major economies, with digital inventory expansion concentrated in metropolitan corridors where zoning liberalization intersects with advertiser appetite for programmatic trading.
United States
Interstate corridor density and highway-adjacent real estate concentration sustain billboard portfolio economics. EPA emissions standards for vinyl chloride monomer production tighten feedstock costs for traditional substrate manufacturers. Dallas-Fort Worth and Atlanta metropolitan clusters see accelerated digital conversion timelines as LED module payback periods compress.
Germany
EU Green Deal material disclosure mandates accelerate PVC-to-aluminum substrate transitions across fabrication facilities. REACH chemical registration requirements impose multi-year toxicity evaluation timelines on coating formulations. The Rhine-Ruhr industrial corridor hosts vertically integrated manufacturing footprints serving street furniture advertising networks.
Brazil
São Paulo's streamlined digital billboard permitting codes unlock inventory expansion for street-level LED networks. ANVISA regulatory frameworks govern material safety certifications for imported display components. The São Paulo metropolitan region concentrates permit approval velocity and advertiser demand density.
China
MIIT standards for connected display hardware and SAMR oversight of advertising content shape deployment parameters. Dual carbon goals pressure energy efficiency specifications for outdoor LED installations. The Yangtze River Delta manufacturing cluster supplies LED modules to domestic and export markets.
United Arab Emirates
Smart city infrastructure convergence and 5G small cell integration create dual-revenue streams for municipalities and operators. MOHAP material safety protocols govern substrate imports for temporary installations. Dubai's transit authority partnerships combine navigation utility with advertising inventory.
Out-Door Signage Market Competitive Environment
Player mix skews toward vertically integrated outdoor advertising operators and specialized display technology fabricators. Tiered competitive structure separates scale-driven billboard portfolio holders from premium digital infrastructure specialists. Two strategic archetypes dominate: interstate corridor density aggregators and urban street furniture network operators. Competitive moves concentrate on municipal revenue-sharing negotiations and LED module cost deflation capture.
Among France-based operators, JCDecaux occupies a position exemplifying street furniture advertising specialization through manufacturing footprint control. Lamar Advertising Company represents the interstate corridor density archetype with billboard portfolio concentration. Daktronics anchors the display technology fabrication tier with LED module supply relationships. These three entities sit within distinct competitive vectors that rarely intersect directly.
| Leading Market Players |
|---|
| Clear Channel Outdoor Holdings |
| Outfront Media |
| JCDecaux |
| Lamar Advertising Company |
| Daktronics |
| Samsung Electronics |
| LG Electronics |
| Avery Dennison Corporation |
| Ströer SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
ISO 14001 environmental management certification gates municipal contract eligibility while simultaneously enabling price premiums for compliant fabricators across Scandinavian procurement frameworks. This dual function compresses margins for uncertified competitors and rewards upstream investment in audited production systems.
Pricing Analysis
Cost-plus contracts with aluminum indexation dominate large-format fabrication agreements across European installations. Three-tier pricing structure across premium, standard, and economy levels separates microLED specifications from SMD LED packages from static vinyl substrates. Cost compression in legacy printed formats is intensifying because EPA emissions standards tighten vinyl chloride monomer feedstock economics. Retail procurement teams exhibit the highest price sensitivity due to campaign-based buying cycles, while transportation authorities with multi-year wayfinding contracts show the lowest.
Supply Chain Analysis
Inventory cycles for LED encapsulant epoxy resin stretch 14-18 weeks, creating working capital intensity for module assemblers during Asian petrochemical output fluctuations. Manufacturing gravity centers on China for LED module production, Germany for aluminum substrate fabrication, and the United States for final billboard assembly. Raw material dependencies span gallium nitride wafers, aluminum coil stock, and vinyl chloride monomer resin. Single-source vulnerability concentrates in Asian epoxy resin supply. Distribution runs through vertically integrated outdoor advertising operators with captive installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electrical contractor certification for high-voltage LED installation represents the binding constraint on digital conversion velocity, with vocational training program throughput lagging permit approval rates in multiple US states. This capability gap creates acquisition premiums for certified installation assets.
For Market Incumbents: Compound municipal revenue-sharing agreements by integrating 5G small cell infrastructure into street furniture units, capturing dual-revenue streams before urban technology vendors establish presence. Prioritize backward integration into aluminum substrate fabrication to secure EU Green Deal compliance margins against PVC-dependent competitors. Lock in long-term LED module supply contracts before epoxy resin volatility transmits to hardware costs. For New Entrants and Emerging Players: ISO 14001 certification fast-track through accredited Scandinavian auditors unlocks municipal contract eligibility in green procurement jurisdictions with incumbent-light competitive intensity. Target São Paulo's streamlined permitting environment where digital billboard approval velocity outpaces installed operator capacity. Pursue transit authority partnerships in secondary Gulf cities replicating Dubai's wayfinding-digital hybrid format success. For Investors and Strategic Acquirers: The EU AI Act's transparency provisions for automated content delivery reshape the acquisition landscape by elevating software compliance costs for connected display networks. Five-to-ten year viability favors operators with programmatic platform integration and municipal revenue-sharing contract structures. Monitor São Paulo permit approval velocity as inflection indicator for Brazilian inventory expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrate Fabrication | EU Green Deal compliance secures premium positioning in French and German municipal contracts. |
| 5G Small Cell Infrastructure Convergence | Dual-revenue streams with Barcelona and Amsterdam municipalities outpace pure advertising yields. |
| MicroLED Module Specification Partnerships | Luxury automotive brand mandates in Times Square and Shibuya Crossing command premium CPM rates. |
| ISO 14001 Certification Investment | Green procurement eligibility in Scandinavian cities creates contract arbitrage against uncertified competitors. |
| Programmatic Platform Integration | Third-party impression verification attracts data-driven advertisers from e-commerce and fintech verticals. |
Study Parameters
Cross-validation between municipal permitting databases and LED module import customs records anchors the qualitative findings on inventory expansion velocity. Primary interviews with outdoor advertising operators, electrical contractor licensing boards, aluminum substrate procurement managers, and transit authority planning officers combined with secondary validation from EPA emissions filings, REACH chemical registration databases, EU Green Deal implementation directives, and SAMR connected display standards. Bottom-up unit economics for digital conversion payback periods triangulate against top-down market sizing from billboard inventory counts.
Sensitivity analysis around LED module cost deflation rates and municipal revenue-sharing terms stress-tests base case assumptions across the projection horizon. Segmentation dimensions modeled include product format, substrate material, installation configuration, end-user vertical, and regional regulatory cluster. CAGRs derive from installed base turnover rates and replacement cycle timing. Forecast inputs incorporate São Paulo permit approval trajectories and epoxy resin price volatility indices.
Underlying assumptions cover continued zoning liberalization in Brazilian metropolitan markets and sustained EU material disclosure enforcement, with deviation risk concentrated in REACH chemical registration timeline extensions and Asian petrochemical supply disruptions. Forecasts reflect these conditions with explicit scenario weighting. Revision becomes warranted when LED module cost deflation crosses thresholds that accelerate static-to-digital conversion timelines beyond modeled replacement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Consumer Shopping Cart Market
Retailing
Australia Retail Bags Market
Retailing
Qatar Retail Market
Retailing
Out Store Signage Market
Retailing
China Retail Market
Retailing
Furniture Rental Service Market
Retailing
Electronics Retailing Market
Retailing
Gift Baskets Market
Retailing
Vietnam Retail Market
Retailing
Retail Signage Market
Retailing
Floor Mat Rental Service Market
Retailing
Floor Displays Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Clothing Retail Market
Retailing
In Store Signage Market
Retailing
Subscription Box Market