
 Canada Gaming Headsets Market | 2026-2036
Canada Gaming Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Gaming Headsets Market Insights
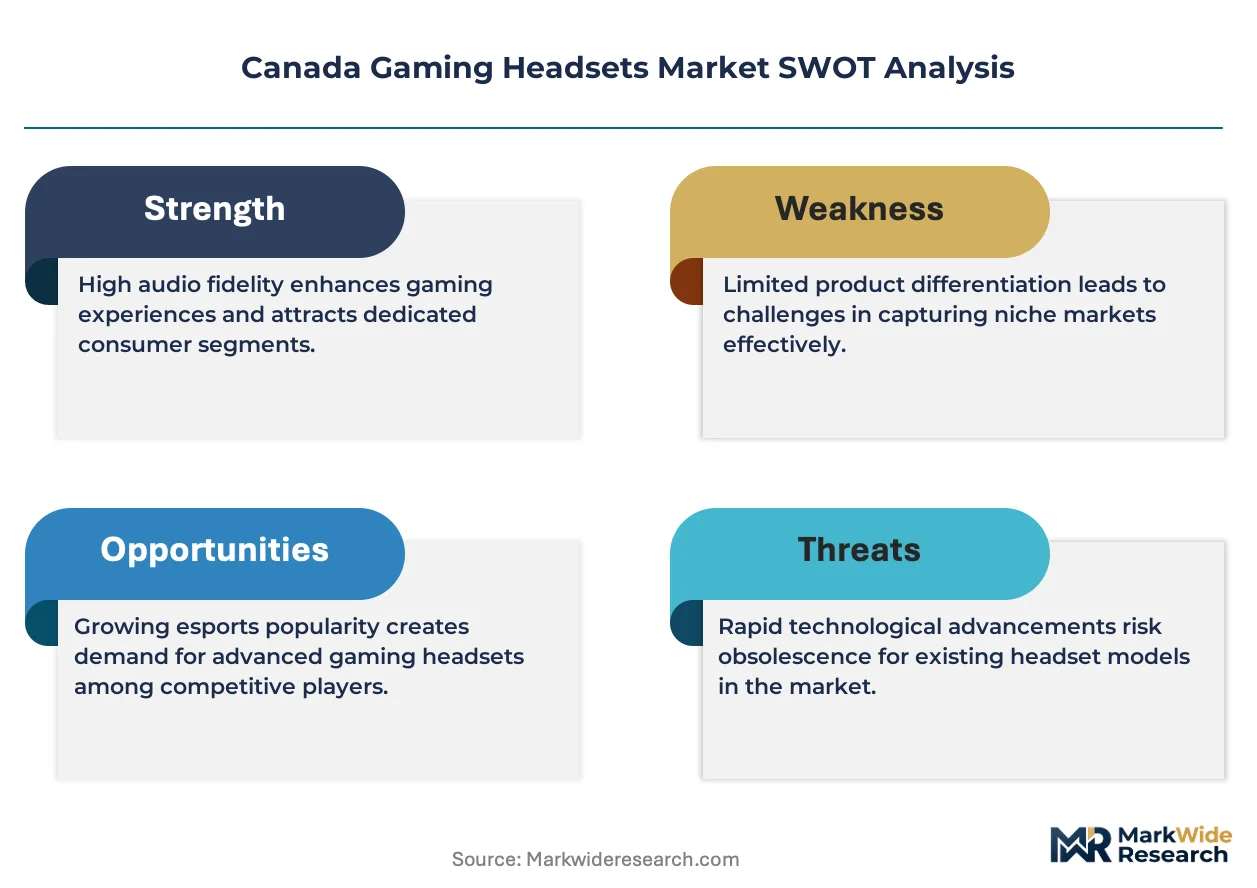
Aluminum alloy is hardening as the preferred headband material, displacing polycarbonate across mid-range and premium tiers to improve durability-to-weight ratios. Logitech International SA leverages its G-brand engineering pipeline to sustain acoustic R&D intensity in Waterloo, Ontario. Razer Inc anchors its Canadian presence through direct-to-consumer channel control and esports sponsorship density. Turtle Beach Corporation specializes in console-optimized audio profiles, differentiating its product stack against PC-centric rivals.
A gaming headset is a wearable audio peripheral engineered with 20 Hz–20 kHz frequency response, 32–50 mm dynamic drivers, and integrated boom or beamforming microphones for real-time voice communication during interactive gameplay. Its commercial purpose centers on delivering positional audio cues and noise-isolated team coordination that standard music headphones cannot replicate. Wireless models now lead volume shipments across the product type dimension, though wired variants retain margin pools among competitive esports teams where latency tolerance approaches zero. Spatial audio technology within the technology dimension represents the fastest-expanding feature set, as game engines from Canadian studios adopt object-based sound rendering.
Health Canada regulates radiation-emitting devices including Bluetooth and wireless headsets under the Radiocommunication Act, while Innovation, Science and Economic Development Canada enforces RSS-102 RF exposure standards that manufacturers must clear before market entry. These frameworks extend product certification timelines but also filter out uncertified imports, reinforcing quality expectations among Canadian consumers. Stakeholders must monitor whether ISED tightens RF power thresholds for next-generation low-latency protocols, as this would force hardware redesigns ahead of protocol adoption cycles.
Market Dynamics
Spatial audio adoption by Canadian game studios is compressing product refresh cycles as positional sound rendering becomes a baseline expectation rather than a premium feature.
Growth Catalysts
- RSS-102 RF Exposure Standards:Health Canada's certification framework filters uncertified wireless imports, reinforcing quality premiums that domestic retailers exploit.
- Esports Tournament Infrastructure:Zero-latency wired headsets retain mandatory status at competitive events, sustaining a parallel premium tier alongside wireless volume growth.
- Toronto-Waterloo Creator Density:Ontario's concentrated streaming and game development clusters generate concentrated replacement demand for broadcast-grade audio peripherals.
Market Restraints
- Aluminum Alloy Supply Concentration:Mid-range and premium headband material sourcing depends on limited North American extrusion capacity, creating input cost volatility.
- Certification Timeline Friction:Innovation, Science and Economic Development Canada's sequential testing protocols extend product launch windows by four to eight months versus unregulated markets.
- Smartphone Audio Substitution:Low-latency Bluetooth codecs in flagship handsets reduce dedicated headset necessity among casual mobile-first gamers.
Strategic Opportunities
- Quebec Indie Studio Expansion:Montreal's growing narrative-driven game development sector represents underpenetrated demand for cinematic spatial audio hardware.
- Direct-to-Consumer Channel Maturation:Bypassing retail markup through owned e-commerce platforms captures margin pools currently absorbed by big-box distributors.
- Provincial Esports Infrastructure Grants:Ontario and British Columbia public funding for competitive gaming venues creates mandated procurement pipelines for tournament-certified equipment.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Waterloo region's limited pipeline of DSP and transducer specialists forces manufacturers to compete for the same constrained labor pool.
- Cross-Platform Certification Complexity:Simultaneous compliance with Health Canada radiation standards and console manufacturer audio specifications fragments testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Gaming Headsets Market |
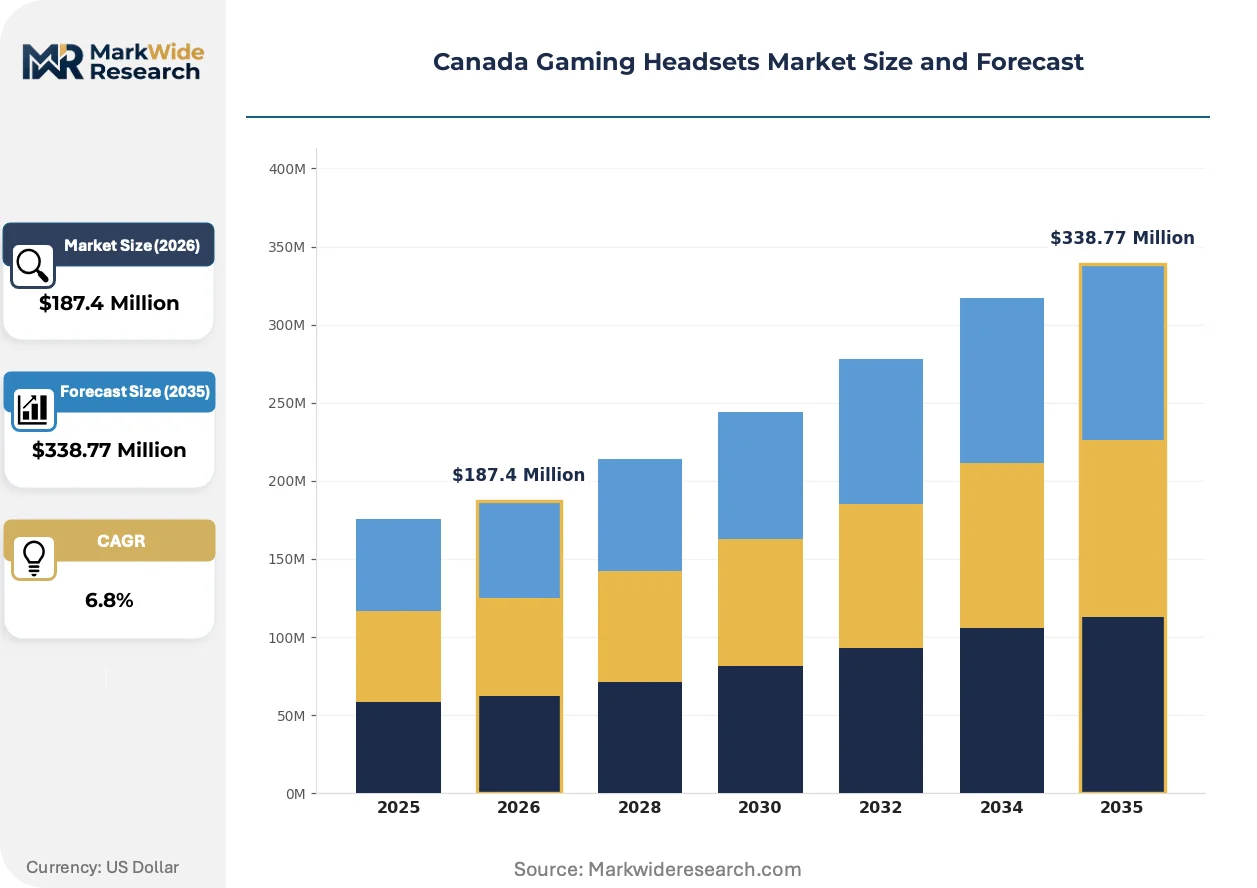
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Surround Sound, Bluetooth End User: Casual Gamers, Professional Gamers, Streamers, Esports Teams Technology: Active Noise Cancellation, Spatial Audio, Voice Assistant, Ultra Low Latency Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | HyperX (HP Inc.), Logitech International SA, Razer Inc, Turtle Beach Corporation, Microsoft Corporation, JBL (Harman International Industries, Incorporated), ASUSTeK COMPUTER INC, JVCKENWOOD Canada Inc, Corsair Gaming Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Gaming Headsets Market Trends and Innovations
Hardware differentiation is narrowing around three vectors: material science in structural components, regulatory compliance as a competitive filter, and creator-economy purchasing patterns reshaping channel economics.
Beamforming microphone arrays are consolidating as the standard voice-capture architecture across mid-tier and premium wireless headsets. Canadian streaming professionals and esports competitors now demand AI-driven noise suppression without boom-arm protrusion. This convergence is consolidating feature parity between external USB microphones and integrated headset solutions, compressing the standalone microphone peripheral market.
Health Canada's Radiocommunication Act enforcement is intensifying documentation requirements for RF-emitting gaming peripherals. Manufacturers must now submit expanded specific absorption rate testing before ISED grants market authorization. The wireless product category bears the heaviest compliance burden, with some vendors delaying Canadian launches to batch-certify with subsequent hardware revisions.
Creator-economy procurement patterns are fragmenting traditional retail dominance in Ontario and British Columbia. Individual streamers and small production collectives now source equipment through manufacturer-direct subscription programs rather than electronics retailers. This channel shift is most visible in Vancouver's YouTube and Twitch production clusters, where bulk direct orders from shared studio spaces displace single-unit retail purchases.
Canada Gaming Headsets Market Segmentation
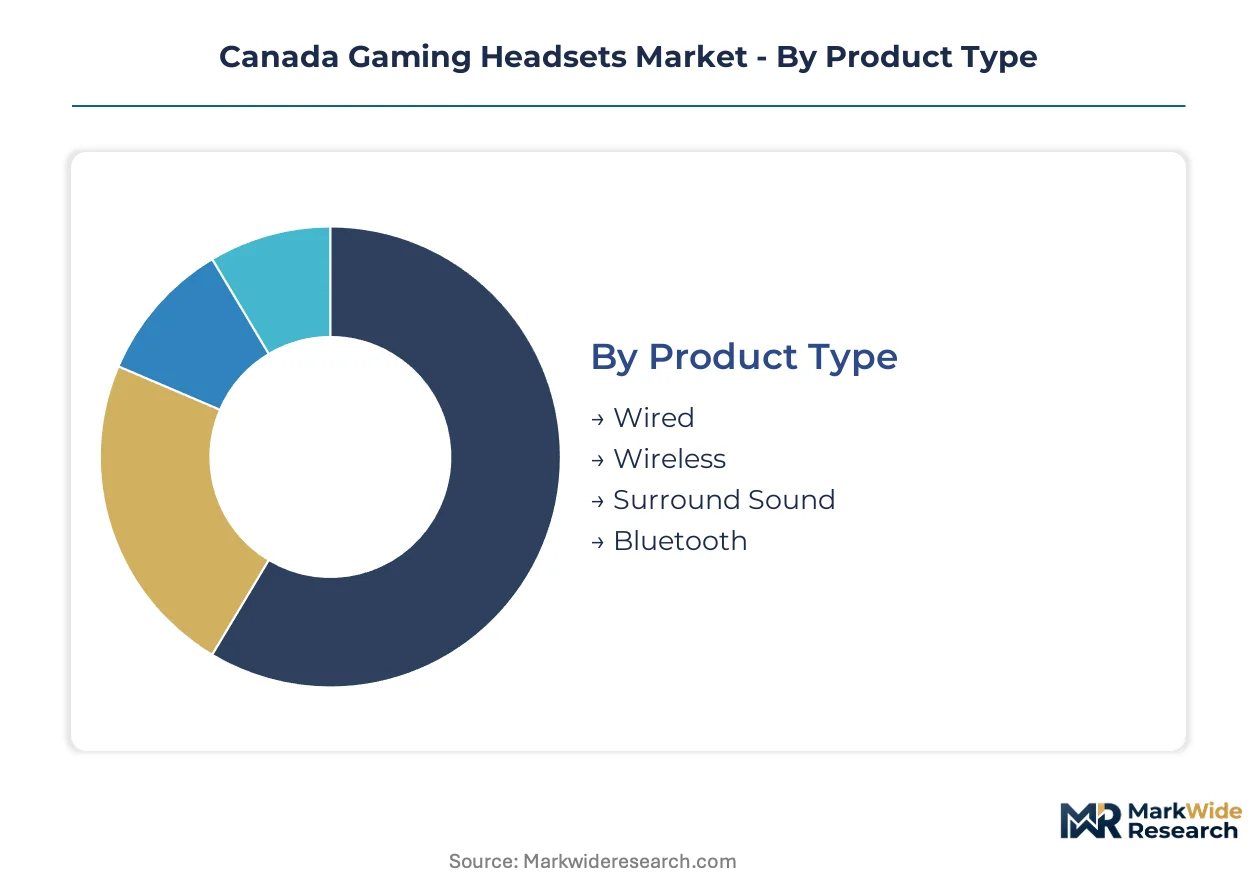
Segmentation in the Canada Gaming Headsets Market reveals distinct capital allocation patterns across hardware architectures, user workflows, and acoustic technologies. Each dimension carries different upfront engineering investments and certification burdens that reshape vendor prioritization.
Product Type:
Wireless variants demand the heaviest upfront capital, requiring RF engineering labs, antenna design cycles, and sequential Health Canada ISED certification runs that extend development timelines by months.
- Wired:Zero-latency copper connectivity uses established driver platforms with minimal RF compliance overhead. Esports tournament mandates in Toronto and Vancouver sustain concentrated procurement from competitive leagues where latency tolerance approaches absolute zero.
- Wireless:Bluetooth and proprietary 2.4 GHz protocols require discrete RF modules, battery integration, and RSS-102 specific absorption rate documentation. Ontario's streaming creator clusters drive replacement cycles as beamforming microphone arrays displace boom-arm setups in broadcast environments.
- Surround Sound:Multi-driver chamber architectures with discrete DSP processing for positional audio rendering.
- Bluetooth:Standardized codec implementations with compressed latency profiles for mobile-first casual use cases.
Most installed capacity flows through Wired. Expansion is steepest in Wireless.
End User:
Professional gamers and esports teams concentrate procurement volume through institutional purchasing pipelines, while streamers fragment demand across individual direct-to-consumer channels.
- Professional Gamers:Tournament-grade specifications mandate zero-latency wired connectivity, broadcast-quality microphone clarity, and durability certification for travel-intensive competition schedules. British Columbia's esports infrastructure grants create mandated procurement channels for venue-certified equipment.
- Esports Teams:Organizational purchasing at scale with standardized peripherals across roster members, prioritizing acoustic consistency and sponsor visibility compliance.
- Casual Gamers:Price-sensitive volume segment with substitution risk from smartphone audio and entry-level Bluetooth alternatives.
- Streamers:Creator-economy procurement through manufacturer-direct subscription programs, particularly concentrated in Vancouver's YouTube and Twitch production clusters.
Professional Gamers anchor current revenue density. Streamers are climbing the fastest.
Technology:
Spatial audio and ultra-low latency protocols require the deepest acoustic engineering talent pools, a constraint that forces Waterloo-region manufacturers into direct competition for DSP specialists.
- Spatial Audio:Object-based sound rendering engines that map game-world positioning to headphone output through head-related transfer function modeling. Montreal's narrative-driven indie studios generate underpenetrated demand for cinematic implementations.
- Ultra Low Latency:Proprietary 2.4 GHz protocols and codec optimization that compress transmission delay below perceptible thresholds for competitive reaction-time dependencies.
- Active Noise Cancellation:Feedforward and feedback microphone arrays for environmental isolation in shared living and transit contexts.
- Voice Assistant:Integrated wake-word processing and cloud connectivity for hands-free device control during gameplay.
Spatial Audio commands premium positioning. Ultra Low Latency is gaining share fastest.
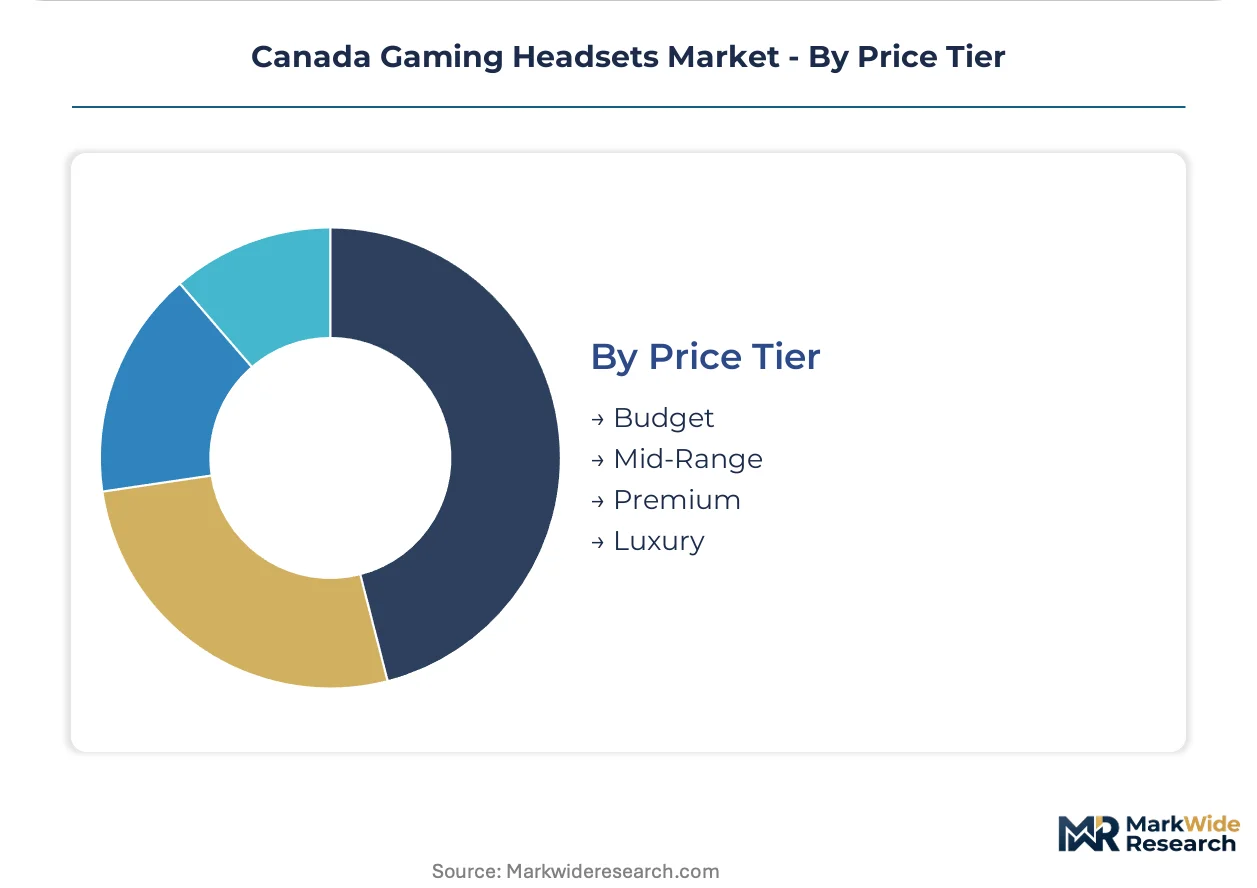
Price Tier:
Premium and luxury tiers absorb disproportionate aluminum alloy headband costs and extended ISED certification timelines, while budget segments compete on polycarbonate economies of scale.
- Premium:Aluminum alloy construction, spatial audio, and beamforming microphones at price points that amortize acoustic R&D across narrower volume bases. Toronto-Waterloo corridor density supports direct-to-consumer margin capture.
- Luxury:Limited-edition collaborations, exotic material finishes, and concierge support services targeting collector and influencer segments.
- Mid-Range:Aluminum alloy migration from premium tiers as extrusion capacity scales and manufacturing learning curves compress.
- Budget:Polycarbonate dominance with feature truncation to hit mass retail price anchors.
Premium absorbs the highest unit margins. Mid-Range shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Toronto-Waterloo corridor anchors Canadian gaming headset demand through concentrated esports infrastructure and streaming creator density. Provincial funding programs and municipal venue investments sustain equipment procurement pipelines. Health Canada certification requirements filter market entry, reinforcing quality premiums that domestic retailers exploit.
Ontario
Esports tournament infrastructure in Toronto and Waterloo drives institutional procurement of zero-latency wired headsets. Ontario's provincial esports infrastructure grants create mandated procurement channels for venue-certified equipment. The Toronto-Waterloo corridor hosts Canada's densest concentration of streaming professionals and game development studios.
British Columbia
Vancouver's YouTube and Twitch production clusters generate bulk direct-to-consumer orders through manufacturer subscription programs. Provincial public funding for competitive gaming venues mandates tournament-grade audio equipment procurement. The city's creator economy displaces traditional retail channels with shared studio space purchasing.
Quebec
Montreal's narrative-driven indie game studios generate underpenetrated demand for cinematic spatial audio hardware. The province's cultural industry tax incentives attract audio post-production facilities that cross-pollagate gaming audio standards. Local developer clusters remain underserved by headset vendors focused on Ontario and British Columbia markets.
Alberta
Calgary and Edmonton's emerging esports venues drive replacement demand for broadcast-grade peripherals. Provincial economic diversification programs channel funding into digital entertainment infrastructure. Local gaming cafes and collegiate esports programs sustain mid-range volume shipments.
Canada Gaming Headsets Market Competitive Landscape
Global majors compete with regional champions across certification compliance and creator-economy channel control. The vendor base stratifies into three tiers: multinational electronics conglomerates with diversified peripheral portfolios, gaming-specialized audio hardware firms, and console ecosystem-integrated suppliers. Strategic moves concentrate on direct-to-consumer channel maturation and esports sponsorship density. Aluminum alloy sourcing partnerships and ISED pre-certification investments represent parallel defensive positions.
Within the gaming-specialized tier, Logitech International SA, Razer Inc, and Turtle Beach Corporation exemplify divergent positioning archetypes. Logitech leverages its Waterloo engineering presence for acoustic R&D proximity to Canadian talent pools. Razer anchors market presence through direct-to-consumer channel control and competitive gaming sponsorship density. Turtle Beach occupies the console-optimized specialization, differentiating against PC-centric rivals through platform-specific audio profiles. Each represents a distinct bet on which end-user workflow—competitive esports, streaming content creation, or console casual gaming—will command premium pricing power.
| Leading Market Players |
|---|
| HyperX (HP Inc.) |
| Logitech International SA |
| Razer Inc |
| Turtle Beach Corporation |
| Microsoft Corporation |
| JBL (Harman International Industries, Incorporated) |
| ASUSTeK COMPUTER INC |
| JVCKENWOOD Canada Inc |
| Corsair Gaming Inc |
| Others |
Pricing and Supply Chain Analysis
Esports tournament mandates for zero-latency wired headsets in Toronto and Vancouver force manufacturers to maintain dual production lines for copper and RF architectures, compressing economies of scale and amplifying cost pass-through pressure into premium tiers. Health Canada's RSS-102 certification timeline friction extends working capital cycles, embedding compliance premiums into final pricing.
Pricing Analysis
Aluminum alloy extrusion cost pass-through dominates mid-range and premium tier pricing, with polycarbonate budget segments absorbing polycarbonate resin volatility through volume scale. Price differentiation hinges on ISED certification tier and beamforming microphone array inclusion, with wireless variants commanding certification-grade premiums. Cost compression in the budget tier intensifies as smartphone Bluetooth codec substitution erodes dedicated headset necessity among casual mobile-first gamers. Casual gamers exhibit highest price sensitivity; professional esports teams demonstrate lowest sensitivity due to sponsor-funded procurement pipelines.
Supply Chain Analysis
Direct-to-consumer channels handle creator-economy demand from Vancouver and Toronto-Waterloo streaming clusters, while big-box retail retains casual gamer volume. Component sourcing draws from China for RF modules and dynamic drivers, Taiwan for DSP chips, and domestic North American extruders for aluminum alloy headbands. Single-source vulnerability concentrates in Bluetooth chipset supply from integrated semiconductor foundries. Distribution runs through manufacturer-owned e-commerce platforms, esports venue procurement pipelines, and electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's gaming headset market functions as a geographic-arbitrage play where Waterloo-region acoustic engineering talent pools command lower cost bases than Silicon Valley equivalents, while Health Canada certification barriers filter price-competitive Asian imports.
For Market Incumbents: Extend ISED pre-certification investments to compress launch windows for next-generation low-latency protocols before regulatory thresholds tighten. Defend against smartphone audio substitution by deepening beamforming microphone differentiation in streaming creator segments. Anchor Waterloo R&D capacity through exclusive partnerships with University of Waterloo co-op programs to lock in DSP talent pipelines. For New Entrants and Emerging Players: Manufacturer-direct subscription programs targeting Vancouver's YouTube and Twitch production clusters offer the lowest customer acquisition cost route into Canadian market presence. Quebec's Montreal indie studio ecosystem remains underpenetrated for cinematic spatial audio hardware, presenting white-space entry before Ontario-focused incumbents redirect attention. Prioritize esports venue procurement relationships in Calgary and Edmonton where provincial diversification funding creates mandated equipment pipelines with lower competitive density. For Investors and Strategic Acquirers: Asymmetric upside sits with console-optimized audio profile specialists who can leverage platform-specific partnerships against PC-centric rivals. Long-term viability over the coming decade hinges on regulatory compliance capabilities as Health Canada intensifies RF documentation requirements. Watch for ISED announcements on low-latency protocol power thresholds as the inflection signal forcing hardware redesign cycles and consolidation among undercapitalized vendors.| Strategic Initiative | Industry Significance |
|---|---|
| ISED Pre-Certification Investment | Compresses Health Canada launch timelines before RF threshold tightening. |
| Waterloo Talent Pipeline Lock-In | Secures constrained DSP and transducer engineering capacity against rival bids. |
| Direct-to-Consumer Channel Maturation | Captures margin pools from Vancouver creator-economy bulk procurement patterns. |
| Quebec Indie Studio Partnership | Opens cinematic spatial audio demand ahead of incumbent geographic expansion. |
| Esports Venue Procurement Integration | Aligns with Ontario and British Columbia public infrastructure grant pipelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with esports team equipment managers, streaming production engineers, retail category buyers, and Health Canada regulatory affairs specialists with secondary validation through ISED certification databases, customs import records, and provincial esports infrastructure grant disclosures. Bottom-up shipment estimates from vendor channels and top-down demand modeling from creator-economy cluster analysis were triangulated for convergence.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation dimensions spanning connectivity architecture, end-user workflow, acoustic technology tier, and price positioning. CAGRs were derived from installed base replacement cycles, esports infrastructure investment pipelines, and spatial audio adoption curves from Canadian game engine developers. Forecast inputs incorporated beamforming microphone penetration rates and aluminum alloy headband material migration timelines.
The model assumes a particular technology adoption path; alternative pathways for proprietary low-latency wireless protocols would alter the outlook if ISED accelerates RF power threshold revisions ahead of hardware refresh cycles. Forecasts reflect documented assumptions on certification timeline friction and creator-economy channel shift velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
India Gaming Headset Market
Audio Equipment
Amps & Effects Market
Audio Equipment
Professional Microphones Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
Commercial Microphone Market
Audio Equipment
Studio Headphones Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
Car Audio Market
Audio Equipment
Global Audio Devices and Components Market
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
India Wireless Speaker Market
Audio Equipment
India Wireless Audio Market
Audio Equipment
Global Wireless Audio Market
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
Audio Interface Market