
 Portable Media Player Market | 2026-2036
Portable Media Player Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Media Player Market Analysis
Buyer concentration among fitness enthusiasts and outdoor athletes is shifting toward specialized high-resolution audio devices. Apple Inc. leverages its ecosystem lock-in to sustain premium positioning across integrated wearable formats. Sony Group Corporation anchors audiophile credibility through dedicated digital audio player engineering. FiiO Electronics Technology competes on specification density for lossless codec support at accessible price tiers.
A portable media player is a battery-powered electronic device designed for stored or streamed digital audio and video playback, typically incorporating flash memory or solid-state storage, DAC circuitry with signal-to-noise ratios exceeding 100 dB, and codec compatibility spanning MP3, AAC, FLAC, and DSD formats. Its primary commercial purpose centers on personal, mobile consumption of media content outside fixed entertainment systems. Flash memory-based devices dominate volume shipments due to mechanical durability and shrinking semiconductor costs, while digital audio players command disproportionate margin pools among discerning listeners. Cloud-based technology segments show structural momentum as subscription streaming integration reduces local storage dependency.
FCC equipment authorization requirements govern radio frequency emissions for US-bound devices, while EU REACH and RoHS frameworks restrict hazardous substance thresholds in solder and component finishes. Japan's METI enforces energy efficiency benchmarks that influence power management IC selection across product lines. Stakeholders must monitor regulatory divergence between battery safety standards and right-to-repair mandates as these shape both design architecture and aftermarket service economics.
Market Dynamics
Fitness enthusiasts and outdoor athletes are consolidating demand around specialized high-resolution audio hardware, while EU Green Deal right-to-repair provisions force redesigns of device longevity and component accessibility.
Growth Catalysts
- Wearable Audio Integration:Fitness tracking ecosystems are incorporating lossless playback capabilities, creating pull for dedicated portable players that bridge athletic performance data with audiophile-grade sound.
- REACH and RoHS Compliance:EU hazardous substance restrictions are accelerating lead-free solder and finish transitions, which incumbent manufacturers have absorbed as competitive moats against unqualified entrants.
- Cloud Streaming Architecture:Subscription service APIs are embedding directly into device firmware, reducing local storage requirements while expanding addressable hardware markets.
Market Restraints
- NAND Flash Price Volatility:Memory contract pricing swings compress margin predictability for flash-based device portfolios.
- Shenzhen Supply Concentration:Final assembly and SMT capacity clusters in Guangdong province create single-point vulnerability for global shipment schedules.
- Smartphone Substitution:Handset DAC improvements and streaming app ubiquity displace standalone player relevance among casual listeners.
Strategic Opportunities
- India Market Underpenetration:Domestic manufacturing incentives and rising disposable income create whitespace for mid-tier digital audio player localization.
- Right-to-Repair Mandates:EU Green Deal provisions favor modular battery and screen designs that extend product lifecycles and unlock aftermarket service revenue.
- LDAC and aptX Adaptive Convergence:Lossless Bluetooth codec proliferation enables wireless audiophile positioning without 3.5mm jack dependency.
Industry Challenges
- RF Certification Timelines:FCC equipment authorization and METI radio law approvals extend launch windows for WiFi-enabled streaming players.
- Legacy 3.5mm Integration:Balanced output and high-impedance headphone amplifier engineering require analog circuit expertise scarce in consumer electronics talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Media Player Market |
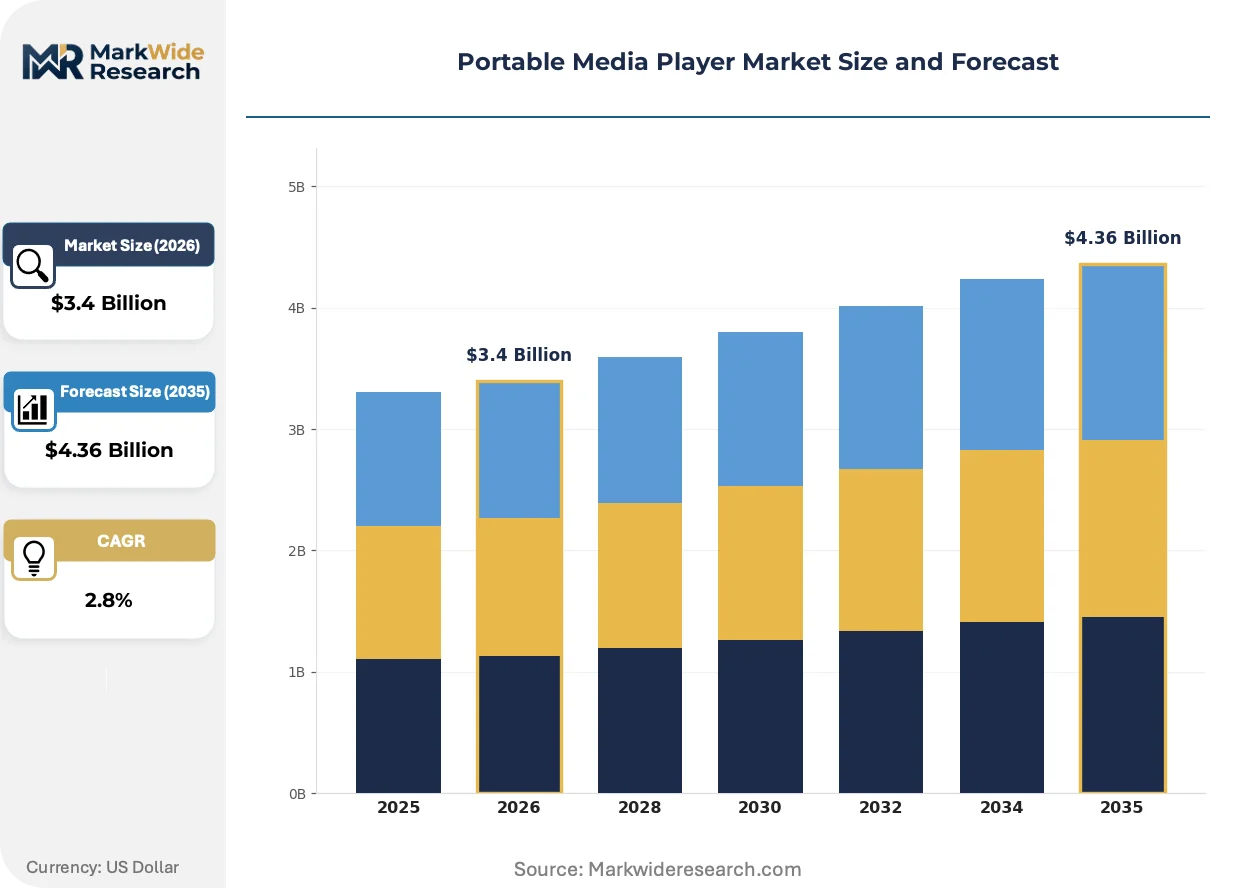
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $4.36 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MP3 Players, Multimedia Players, Digital Audio Players, Streaming Devices End User: Consumers, Educational Institutions, Fitness Enthusiasts, Professionals Technology: Flash Memory, Hard Drive, Cloud-Based, Hybrid Devices Distribution Channel: Online Retail, Physical Stores, Resellers, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Sony Group Corporation, Creative Technology Ltd., Western Digital Corporation, ARCHOS, Koninklijke Philips N.V., Microsoft, FiiO Electronics Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Media Player Market Emerging Trajectories
Portable media player architecture is fragmenting across three vectors: hardware modularity for repair compliance, regulatory pressure on material composition, and buyer segmentation between streaming-first and local-storage purists.
FPGA-based digital signal processing is modularizing high-end player architectures. Audiophile-grade manufacturers are adopting field-programmable gate arrays for DSD upsampling and custom filter implementations. This silicon flexibility is compressing ASIC development cycles while enabling firmware-upgradeable audio pipelines that extend hardware relevance across codec evolution.
EU Green Deal right-to-repair provisions are mandating battery accessibility and component modularity. Manufacturers must now design for disassembly with standard fasteners and documented repair procedures. Premium digital audio player lines face the steepest compliance costs due to compact unibody aluminum chassis that resist non-destructive opening.
Subscription streaming integration is displacing local library management as the primary buyer interface. Fitness enthusiasts and commuter segments prioritize Spotify Connect and Tidal offline sync over FLAC file curation. This behavioral pivot concentrates demand in China and South Korea, where domestic streaming platforms have secured exclusive high-resolution catalog licensing.
Portable Media Player Market Segmentation
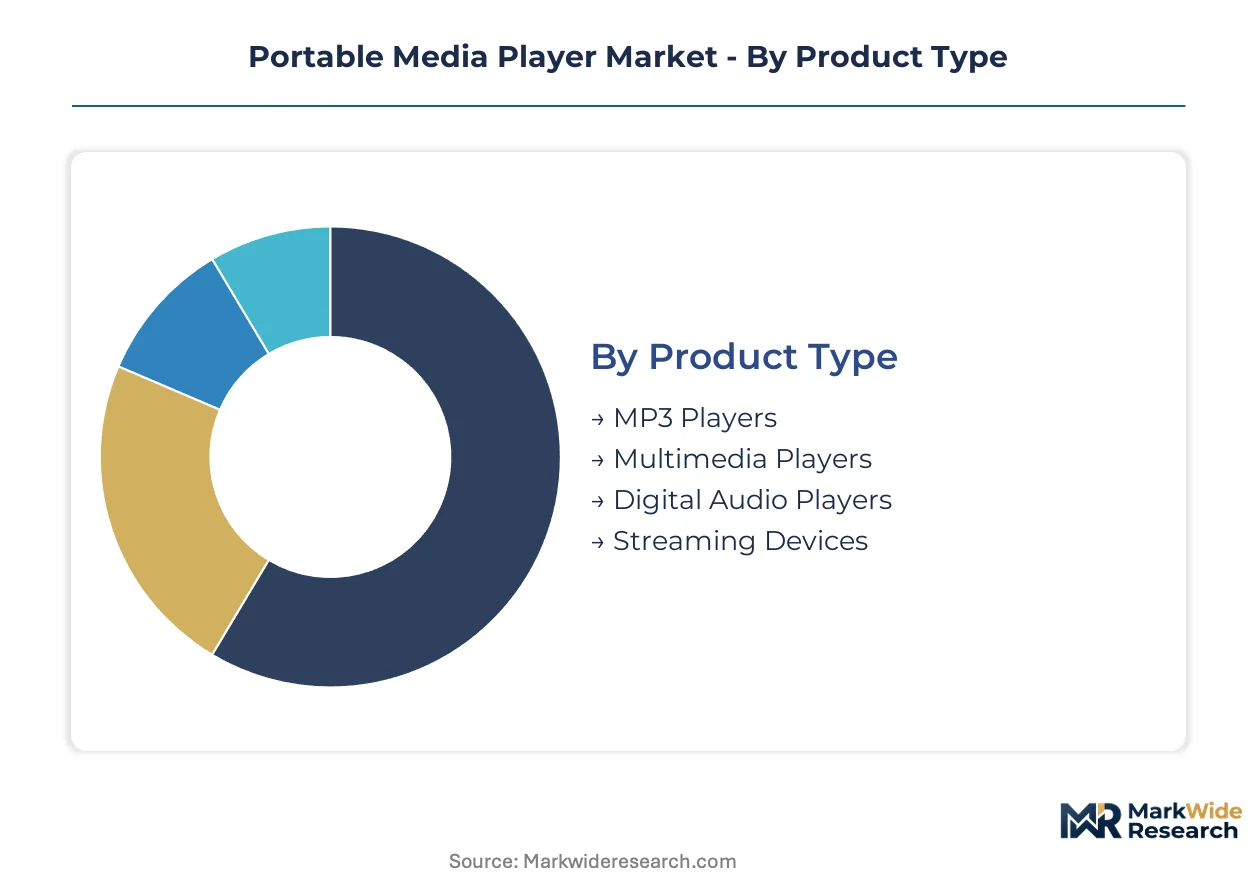
Segmentation in portable media players reveals divergent hardware requirements across listener sophistication tiers. Upgrade cycles vary dramatically between casual streaming adopters and audiophile equipment collectors, creating distinct margin architectures within each category.
Product Type:
Replacement cycles stretch longest for basic MP3 hardware while digital audio players command accelerated refresh rates among specification-focused buyers.
- MP3 Players:Entry-level devices utilizing compressed codec playback with basic 16-bit DAC architectures. Demand clusters in emerging markets and gift-giving occasions where minimal functionality suffices. NAND flash integration keeps bill-of-materials below premium thresholds, though smartphone substitution erodes installed base longevity.
- Digital Audio Players:Dedicated audiophile hardware featuring balanced output stages, discrete amplifier circuits, and native DSD256 decoding. Fitness enthusiasts and commuter segments in China and South Korea drive volume for mid-tier units; Japan and Germany sustain ultra-premium tiers above five-hundred-dollar price points.
- Multimedia Players:Video-capable devices with color LCD panels and broader codec support including H.264 and AV1. Educational procurement in India and Brazil sustains institutional volume despite consumer drift toward tablets.
- Streaming Devices:WiFi-enabled players with embedded Spotify Connect, Tidal, and domestic platform APIs. Cloud-first architecture reduces local storage requirements while expanding subscription service addressability.
Volume placements concentrate in MP3 Players; the faster expansion belongs to Streaming Devices.
End User:
Cost tier stratification separates mass-market consumer hardware from specialized professional equipment with calibrated reference outputs.
- Consumers:General-purpose listeners prioritizing convenience and ecosystem integration. Casual buyers in the United States and United Kingdom exhibit shortest replacement cycles, typically aligning with smartphone upgrade schedules.
- Fitness Enthusiasts:Athletes requiring sweat-resistant housings, clip-on form factors, and offline playlist synchronization. This segment commands premium pricing for heart rate monitor integration and GPS logging capabilities.
- Educational Institutions:K-12 and university procurement for language labs, testing centers, and media studies programs. Bulk purchasing agreements favor durability specifications and centralized fleet management over audiophile performance.
- Professionals:Audio engineers, musicians, and broadcast technicians requiring bit-perfect playback and reference-grade output impedance. Japan's METI energy efficiency standards influence power management design for studio deployment.
Margin concentration sits with Professionals; steepest volume expansion trajectory belongs to Fitness Enthusiasts.
Technology:
Supply concentration for NAND flash controllers in Taiwan and South Korea shapes component availability across storage architectures.
- Flash Memory:Solid-state devices employing NAND flash with no moving mechanical components. Mechanical durability dominates volume shipments; Shenzhen assembly clusters achieve lowest per-unit manufacturing costs.
- Cloud-Based:Minimal local storage hardware dependent on persistent connectivity and subscription service APIs. This architecture is gaining share fastest in urban China where 5G coverage enables seamless high-resolution streaming.
- Hard Drive:Rotating magnetic media offering terabyte-scale capacity at lowest per-gigabyte cost. Niche survival in archival applications and professional field recording where maximum storage density outweighs shock vulnerability.
- Hybrid Devices:Combined flash cache with hard drive bulk storage or local library with cloud sync capability. Complexity premium limits adoption to enthusiast segments unwilling to choose between access models.
Flash Memory captures dominant volume placement; Cloud-Based segments climb the fastest.
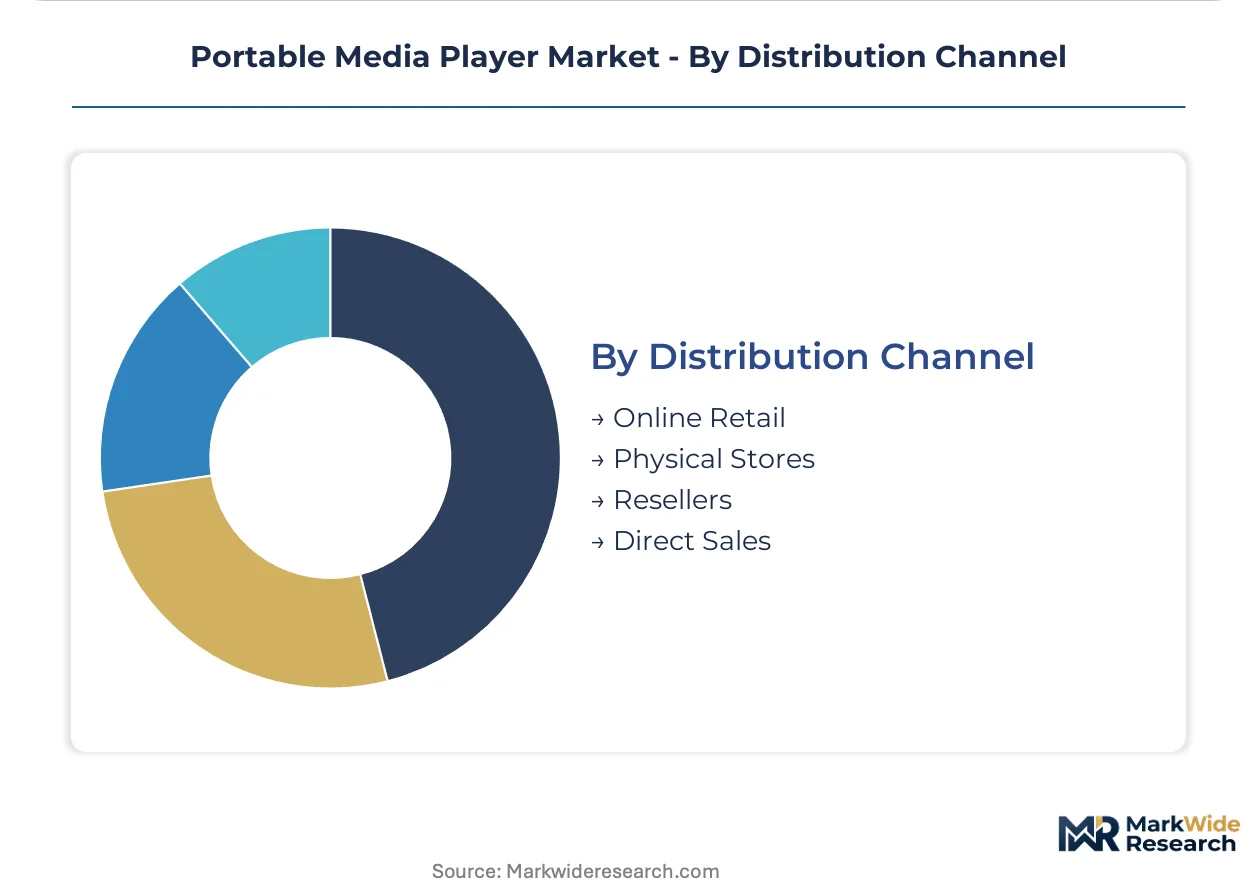
Distribution Channel:
Geography determines channel effectiveness, with urban density in China favoring online fulfillment while tactile evaluation needs sustain physical retail in Japan and Germany.
- Online Retail:E-commerce platforms and brand-direct storefronts offering specification comparison and community reviews. Tmall and JD.com in China, Amazon in Western markets, and domestic platforms in South Korea concentrate volume.
- Physical Stores:Electronics retailers and dedicated audio boutiques enabling hands-on DAC evaluation and headphone pairing. Japan's Bic Camera and Yodobashi chains sustain premium positioning through trained sales staff.
- Resellers:Third-party distributors serving regional markets with limited direct brand presence. Gray market channels in Southeast Asia and Latin America introduce warranty complexity.
- Direct Sales:Manufacturer-owned channels capturing full margin and enabling subscription bundling. Apple's ecosystem lock-in exemplifies this model with seamless device-to-service integration.
Online Retail dominates volume placements; Direct Sales achieves fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates portable media player demand through domestic manufacturing clusters and streaming platform integration. Fitness enthusiasts and commuter segments drive volume across Asia-Pacific urban centers. Regulatory divergence on repairability and hazardous substances shapes hardware design requirements in major consumer markets.
China
Domestic streaming platforms with exclusive high-resolution licensing sustain hardware pull from fitness enthusiasts and audiophile commuters. MIIT enforces GB standards for electronic product safety and radio frequency emissions. Shenzhen and Dongguan assembly clusters achieve lowest per-unit manufacturing costs while supplying global brand OEM requirements.
United States
Ecosystem-integrated wearable audio and subscription streaming APIs dominate consumer preference among fitness trackers and smartwatch adopters. FCC equipment authorization governs WiFi-enabled player launches with extended approval timelines. Austin and Seattle tech corridors concentrate firmware development talent for cloud-streaming architecture integration.
Germany
Audiophile-grade digital audio players command premium positioning through specialized retail channels serving discerning listeners. EU REACH and RoHS frameworks restrict hazardous substances in solder and component finishes. Munich and Berlin sustain boutique audio engineering clusters focused on high-resolution DAC implementation.
Japan
Reference-grade output specifications and energy efficiency requirements shape professional and consumer hardware procurement. METI enforces stringent energy efficiency benchmarks influencing power management IC selection. Tokyo-Osaka electronics corridors maintain discrete amplifier circuit expertise scarce in broader consumer electronics.
South Korea
Domestic streaming platform integration and LDAC codec adoption accelerate wireless audiophile hardware refresh cycles. MFDS and national radio law frameworks govern device certification for Bluetooth and WiFi connectivity. Seoul Capital Area semiconductor design houses supply NAND flash controllers and DAC silicon globally.
Portable Media Player Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized audiophile positioning and modular repair-compliant designs. The vendor base stratifies across three tiers: ecosystem-integrated technology conglomerates, dedicated audio engineering specialists, and contract manufacturing assemblers serving private label requirements. Dominant competitive moves include strategic partnerships for streaming service API integration and portfolio diversification into fitness-tracking wearable convergence.
Within the ecosystem-integrated tier, Apple Inc. and Samsung Electronics Co. Ltd. represent platform lock-in strategies that bundle hardware with subscription service distribution. Sony Group Corporation exemplifies the dedicated audio engineering archetype through sustained investment in discrete circuit design and reference-grade output specifications. FiiO Electronics Technology occupies a position within the accessible premium segment, competing on specification density for lossless codec support.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Sony Group Corporation |
| Creative Technology Ltd. |
| Western Digital Corporation |
| ARCHOS |
| Koninklijke Philips N.V. |
| Microsoft |
| FiiO Electronics Technology |
| Others |
Supply Flow & Price Mechanics
Discrete amplifier circuit expertise concentrated in Tokyo-Osaka electronics corridors widens labor-cost differentials between premium digital audio players and mass-market MP3 hardware, compressing mid-tier pricing spreads as Shenzhen assembly achieves lowest per-unit manufacturing costs.
Pricing Analysis
Volume placements concentrate in entry-level MP3 hardware while margin pools accrue to digital audio players with balanced output stages and native DSD256 decoding. Three-tier pricing structure across premium, standard, and economy levels separates audiophile-grade devices above five-hundred-dollar thresholds from fitness-integrated mid-tier units and gift-market economy players. Cost compression in flash memory tiers is intensifying because NAND contract pricing swings compress margin predictability. Casual listeners in the United States and United Kingdom exhibit highest price sensitivity, while professionals in Japan and Germany demonstrate least elasticity for reference-grade specifications.
Supply Chain Analysis
FCC equipment authorization and EU REACH compliance gating favor incumbent manufacturers with absorbed regulatory costs, creating competitive moats against unqualified entrants. Component supply draws from Taiwan and South Korea for NAND flash controllers, China for Shenzhen and Dongguan final assembly clusters, and Japan for discrete amplifier silicon. Raw material dependencies span lead-free solder alloys, aluminum unibody chassis, and high-grade DAC chipsets. Single-source vulnerability concentrates in Guangdong province SMT capacity. Distribution runs through Tmall and JD.com in China, Amazon in Western markets, and domestic platforms in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal right-to-repair provisions are forcing consolidation as modular redesign costs eliminate marginal players lacking capital reserves for compliance engineering.
For Market Incumbents: Anticipate smartphone DAC improvements and streaming app ubiquity eroding casual listener segments by accelerating fitness-tracking wearable convergence with lossless playback capabilities. Absorb REACH and RoHS transitions as competitive moats while extending product lifecycles through modular battery architectures that unlock aftermarket service revenue. For New Entrants and Emerging Players: The pricing gap between premium digital audio players and economy MP3 hardware creates whitespace for accessible specification density targeting fitness enthusiasts in India and mid-tier audiophiles in South Korea. Prioritize LDAC and aptX Adaptive codec integration as wireless positioning without 3.5mm jack dependency. Pursue direct-to-consumer online retail with community-driven specification comparison to bypass established physical retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing assemblers with captive Shenzhen capacity and firmware development talent in Austin or Seattle corridors. Long-term viability hinges on streaming service API integration capabilities and right-to-repair compliance infrastructure. Monitor EU battery accessibility mandate enforcement timelines as inflection indicators for hardware lifecycle extension economics.| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Service API Integration | Embedded Spotify Connect and Tidal offline sync expand addressable hardware markets beyond local-storage purists. |
| Modular Battery Architecture Redesign | EU Green Deal right-to-repair compliance extends product lifecycles and unlocks recurring aftermarket service revenue streams. |
| Fitness Wearable Convergence | Heart rate monitor and GPS logging integration captures premium pricing from athletic performance data segments. |
| LDAC Codec Certification Investment | Lossless Bluetooth positioning without 3.5mm dependency addresses wireless audiophile demand in Japan and South Korea. |
| India Market Localization | Domestic manufacturing incentives and rising disposable income create whitespace for mid-tier digital audio player assembly. |
Methodological Framework
Multi-period observation of NAND flash contract pricing, streaming platform API adoption rates, and right-to-repair compliance timelines anchored the trend analysis, supplemented by interviews with digital audio player engineering leads, procurement managers at Shenzhen assembly clusters, streaming service partnership directors, and specialty audio retail buyers. Secondary validation drew from FCC equipment authorization filings, MIIT GB standard publications, EU REACH regulatory updates, and SEC disclosures from component suppliers. Bottom-up shipment estimates triangulated against top-down market value reconstructions.
Input-output matrix modeling connected NAND flash price indices, DAC chipset availability, and streaming subscription penetration to hardware shipment projections across the analysis window. Segmentation dimensions spanned product type, end user sophistication tier, storage architecture, and regional regulatory cluster. CAGRs were derived from curve-fitting observed replacement cycles against disposable income elasticity coefficients. Industry-specific forecast inputs included LDAC codec licensing velocity and EU battery accessibility mandate implementation schedules.
Underlying measurement precision varies by segment; flash memory-based volume placements carry tighter precision than hard drive archival niche estimates due to consolidated supply chain visibility. Forecasts reflect documented assumptions about streaming platform exclusivity licensing durability and Shenzhen capacity expansion trajectories. A model refresh is warranted upon material change in EU right-to-repair enforcement timelines or NAND flash supply concentration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
PC Accessories Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
United States Stylus Pen Market