
 Makeup Setting Powder Market | 2026-2036
Makeup Setting Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Makeup Setting Powder Market Insights
REACH is repositioning the cost-of-entry calculus for cosmetic ingredient compliance across European and export-oriented markets. L'Oréal S.A. leverages its integrated R&D infrastructure to reformulate setting powders ahead of regulatory deadlines. Estée Lauder Companies Inc. anchors its premium positioning through controlled distribution in department stores and specialty beauty retailers. Shiseido Company, Limited differentiates via technology leadership in skin-adaptive powder formulations developed at its Yokohama research center.
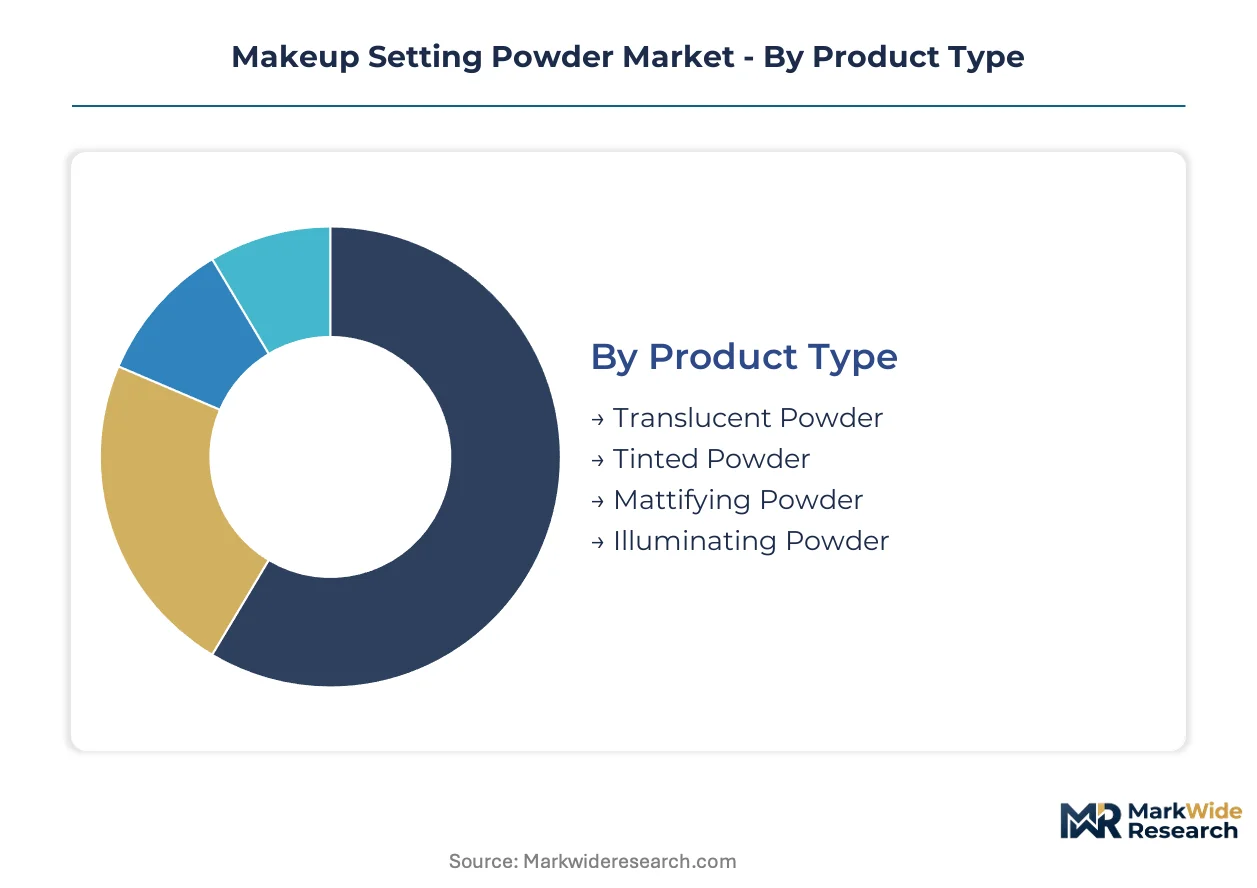
Makeup setting powder comprises finely milled particulate formulations—typically talc, silica, mica, or starch-based—engineered to absorb facial sebum, lock foundation coverage, and extend cosmetic wear time through film-forming or oil-binding mechanisms. The product type dimension shows translucent powder occupying the volume lead due to universal shade compatibility, while illuminating powder captures disproportionate margin pools among beauty enthusiasts and influencer-driven segments. Within formulation, loose powder dominates professional artist channels for buildable coverage control, whereas pressed powder sustains broader everyday user accessibility through portable application formats.
FDA cosmetic oversight under the Modernization of Cosmetics Regulation Act, EU REACH chemical registration requirements, and China's GB standards for cosmetic safety collectively elevate testing burdens and documentation thresholds for market access. These frameworks compel manufacturers to maintain dual-compliant formulation portfolios or risk exclusion from priority distribution channels. Stakeholders must monitor evolving ingredient restriction lists and pre-market notification timelines to preserve product registration validity and avoid supply chain disruptions.
Market Dynamics
EU REACH chemical registration requirements are compressing formulation timelines and forcing raw material substitution across setting powder supply chains. Professional makeup artists in film and television production now demand dual-compliant portfolios that satisfy both European and Chinese GB standards simultaneously.
Growth Catalysts
- FDA Modernization of Cosmetics Regulation Act:Pre-market notification requirements are elevating documentation standards and creating competitive moats for compliant manufacturers.
- Film and television production:Professional artist channels absorb premium loose powder volumes for buildable coverage control under high-definition camera conditions.
- Silica-based formulations:Oil-binding particulate technologies extend cosmetic wear time beyond traditional talc alternatives in humid climates.
Market Restraints
- Talc supply concentration:Reliance on specific mining jurisdictions creates input volatility and reputational exposure from asbestos contamination concerns.
- REACH registration costs:Small and mid-size formulators face disproportionate testing burdens for novel ingredient categories.
- Starch substitution threat:Plant-based absorbents from food-grade suppliers encroach on conventional mineral powder positioning in clean beauty segments.
Strategic Opportunities
- India tier-two cities:Underpenetrated urban markets beyond Mumbai and Delhi present whitespace for pressed powder accessibility formats.
- Skin-adaptive technology convergence:Film-forming polymers combined with color-matching pigments enable personalized finish outcomes.
- Direct-to-artist subscription channels:Professional supply houses bypass traditional retail markup structures for recurring bulk purchases.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging color science and regulatory compliance commands premium compensation.
- Dual certification timelines:Parallel EU REACH and China NMPA registration processes delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Makeup Setting Powder Market |
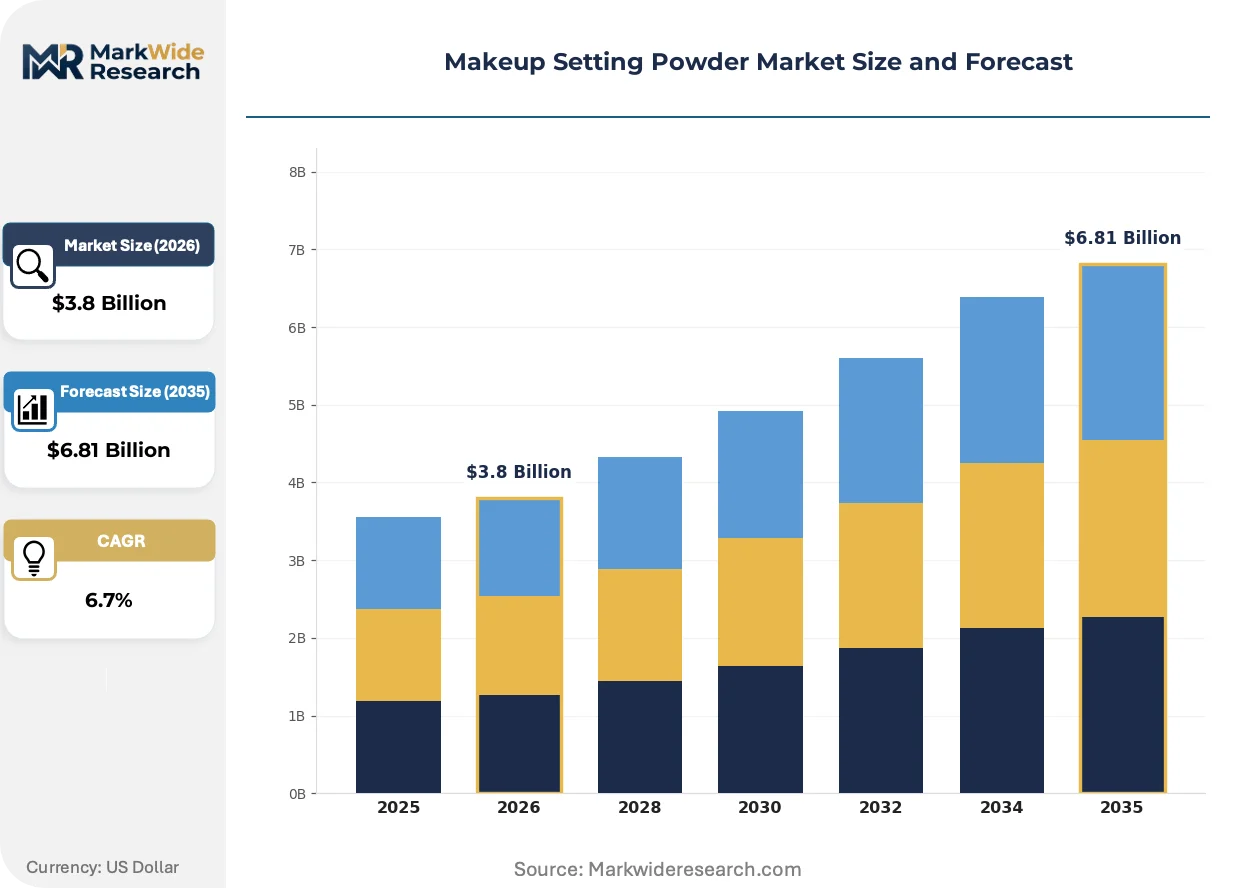
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Translucent Powder, Tinted Powder, Mattifying Powder, Illuminating Powder Formulation: Loose Powder, Pressed Powder, Gel Powder, Spray Powder End User: Professional Artists, Everyday Users, Beauty Enthusiasts, Influencers Distribution Channel: Online Retailers, Department Stores, Specialty Beauty Stores, Pharmacies |
| Companies Covered | Chanel S.A., Revlon, Inc., L'Oréal S.A., Bobbi Brown Professional Cosmetics, Inc., Maybelline New York, Estée Lauder Companies Inc., Coty Inc., Tom Ford, Shiseido Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Makeup Setting Powder Market Trends and Innovations
Active ingredient transparency and performance verification are reshaping how setting powders compete. Formulators now balance film-forming efficacy against clean-label positioning while navigating divergent regulatory thresholds across priority markets.
Micronized silica spheres with controlled porosity are expanding into professional artist kits and influencer-driven premium segments. These particulates deliver superior sebum absorption without flashback under studio lighting. L'Oréal S.A. and Shiseido Company, Limited are expanding into this material class ahead of talc restriction expansions.
REACH Annex XVII updates on microplastic restrictions are forcing reformulation of conventional loose powder vehicles. The regulation compels substitution of synthetic film-formers with biodegradable alternatives. Pressed powder formats face compressed innovation cycles as manufacturers race to preserve registration validity.
Beauty enthusiasts now verify ingredient provenance through third-party certification apps before purchase. This behavior fragments brand loyalty and elevates transparency-focused challengers. China and South Korea exhibit the most pronounced certification-driven preference shifts, where MFDS and NMPA disclosure requirements intersect with consumer digital research habits.
Makeup Setting Powder Market Segmentation
Setting powder manufacturers navigate distinct performance requirements across user archetypes and application contexts. Segmentation reveals where formulation investments concentrate versus where packaging and channel economics dominate purchasing decisions.
Product Type:
Integration depth varies sharply—translucent and tinted powders function as standalone complexion products, while mattifying and illuminating variants embed into broader finishing routines.
- Translucent Powder:Finely milled silica or starch-based formulations provide universal shade compatibility without color alteration. Demand concentrates among professional artists in film and television production where HD camera conditions require flashback-resistant finishes under studio lighting.
- Illuminating Powder:Light-reflecting particulates containing mica or synthetic fluorphlogopite create dimensional radiance. Beauty enthusiasts and influencer-driven segments absorb disproportionate margin pools through premium positioning and social media visibility.
- Tinted Powder:Pigment-infused bases offer sheer coverage correction across skin tone ranges.
- Mattifying Powder:High-absorbency talc or silica blends target sebum control in humid climates.
Translucent powder leads volumes today; illuminating powder is gaining share fastest.
Formulation:
Cost tier stratification separates professional-grade loose powders from mass-market pressed formats, with spray and gel occupying niche premium positioning.
- Loose Powder:Uncompressed particulate systems enable buildable coverage control through variable application density. Professional makeup artists in film and television production drive volume through bulk procurement from specialty supply houses.
- Pressed Powder:Compressed cakes with binder systems deliver portable application formats for everyday users. China manufacturing clusters in Guangzhou and Shanghai scale production capacity for both domestic consumption and export markets.
- Gel Powder:Hybrid cream-to-powder textures target specific finish preferences.
- Spray Powder:Aerosolized or pump-dispersed formats serve quick-application use cases.
Pressed powder dominates everyday accessibility; loose powder commands premium professional channels.
End User:
Customer type determines performance validation requirements and price elasticity across the purchase journey.
- Professional Artists:Film and television production crews demand dual-compliant portfolios satisfying EU REACH and China GB standards simultaneously for location-flexible kit portability.
- Beauty Enthusiasts:Digital-native consumers verify ingredient provenance through third-party certification apps before purchase, fragmenting brand loyalty across transparency-focused challengers.
- Everyday Users:Mass-market consumers prioritize convenience and accessibility in retail channels.
- Influencers:Content creators drive trial through visible product integration and recommendation economics.
Everyday users anchor volume bases; professional artists generate highest per-unit economics.
Distribution Channel:
Channel selection dictates margin structure and regulatory documentation burdens for market access.
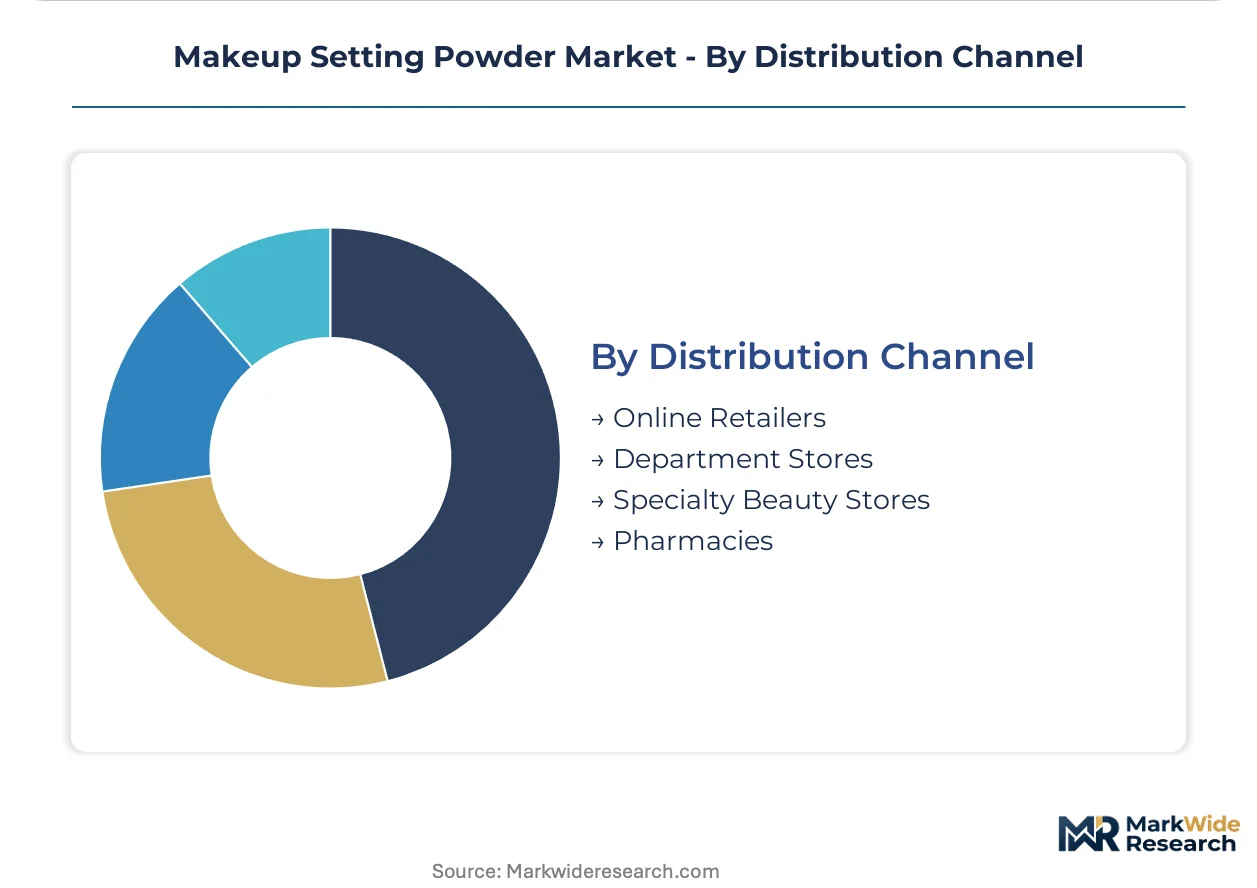
- Specialty Beauty Stores:Curated assortments with trained staff support premium positioning and skin-matching services. Estée Lauder Companies Inc. anchors controlled distribution through this channel to defend brand equity.
- Online Retailers:Direct-to-consumer platforms enable subscription mechanics and bulk professional purchasing. Direct-to-artist subscription channels bypass traditional retail markup structures for recurring orders.
- Department Stores:Traditional prestige retail maintains foot traffic among established demographics.
- Pharmacies:Accessible distribution reaches mass-market and sensitive-skin positioning.
Online retailers are expanding most quickly; specialty beauty stores retain margin leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional makeup artists and cosmetic chemists cluster disproportionately in markets with established film production infrastructure and regulatory sophistication. Their concentration determines where formulation innovation and compliance investment concentrate.
United States
Hollywood production studios and New York-based beauty headquarters drive professional-grade demand for HD-compatible formulations. FDA Modernization of Cosmetics Regulation Act pre-market notification requirements are elevating documentation burdens for new ingredient introductions. Los Angeles and New York City anchor the dual concentration of film industry procurement and prestige brand R&D operations.
China
Domestic beauty brands and manufacturing scale create integrated supply advantages for both local consumption and export markets. NMPA cosmetic registration requirements and GB standards for ingredient safety are tightening parallel to EU REACH alignment efforts. Guangzhou and Shanghai manufacturing clusters are expanding pressed powder production capacity for Southeast Asian export markets.
France
L'Oréal S.A. headquarters and luxury heritage brands anchor premium formulation expertise and perfumery-adjacent powder technologies. ECHA REACH enforcement and Annex XVII microplastic restrictions are compressing reformulation timelines for conventional loose powder vehicles. Paris and Lyon concentrate corporate R&D facilities alongside specialty raw material distributors serving Mediterranean export markets.
Japan
Shiseido Company, Limited and precision manufacturing culture drive skin-adaptive powder technology development. METI industrial standards and PMDA cosmetic safety frameworks emphasize pre-market testing rigor comparable to pharmaceutical-grade processes. Yokohama research centers and Osaka production facilities integrate polymer science from adjacent electronics and materials industries.
South Korea
K-beauty export momentum and influencer-driven trial cycles accelerate format innovation and packaging differentiation. MFDS cosmetic disclosure requirements intersect with consumer digital verification habits through third-party certification apps. Seoul Capital Area manufacturing complexes and Incheon port logistics support rapid turnaround for trend-responsive product launches.
Makeup Setting Powder Market Competitive Landscape
The competitive structure tilts toward integrated beauty conglomerates with captive R&D infrastructure and regulatory compliance capabilities. Three tiers separate multinational prestige houses from mid-scale specialty brands and private-label manufacturers. Strategic moves concentrate on dual-certification portfolio expansion for EU and China market access alongside micronized particulate technology licensing.
Among French and Japanese beauty conglomerates, L'Oréal S.A., Shiseido Company, Limited, and Estée Lauder Companies Inc. exemplify the integrated archetype combining formulation science, controlled distribution, and multi-jurisdictional regulatory navigation. These entities occupy positions where vertical control over raw material qualification and pre-market testing timelines creates defensive moats against smaller competitors facing REACH and NMPA registration cost burdens.
| Leading Market Players |
|---|
| Chanel S.A. |
| Revlon, Inc. |
| L'Oréal S.A. |
| Bobbi Brown Professional Cosmetics, Inc. |
| Maybelline New York |
| Estée Lauder Companies Inc. |
| Coty Inc. |
| Tom Ford |
| Shiseido Company, Limited |
| Others |
Pricing and Supply Chain Analysis
Professional makeup artists in film and television production concentrate procurement volumes through specialty supply houses, anchoring a contract-based long-term offtake model that rewards dual-certified formulation portfolios with pricing premiums over mass-market alternatives.
Pricing Analysis
Product-plus-service bundling separates professional-grade loose powders with technical support from unbundled pressed powder formats sold through retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with REACH-compliant formulations commanding tier premiums. Pricing pressure stems from starch-based substitutes encroaching on mineral powder positioning in clean beauty segments. Everyday users exhibit highest price sensitivity through retail comparison shopping, while professional artists prioritize performance validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with talc mining jurisdictions concentrated in China, India, and the United States. Formulation draws from silica deposits, mica processing facilities, and starch conversion plants as secondary inputs. Tariff exposure on processed minerals creates margin volatility for manufacturers dependent on cross-border raw material flows. Distribution runs through Guangzhou and Shanghai manufacturing clusters feeding specialty beauty retailers and direct-to-artist subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The makeup setting powder market functions as a stable compounder, with regulatory compliance burdens creating persistent barriers that protect incumbent positions and sustain margin structures.
For Market Incumbents: Lock in dual-certification advantages by accelerating EU REACH and China NMPA registration timelines ahead of smaller competitors facing testing cost burdens. Deepen backward integration into micronized silica production to secure supply ahead of talc restriction expansions. Prioritize captive R&D infrastructure at Yokohama and Paris facilities to maintain formulation leadership against clean beauty challengers. For New Entrants and Emerging Players: Direct-to-artist subscription channels offer the most penetrable route for bypassing traditional retail markup structures and securing recurring bulk orders from professional makeup artists. Target underpenetrated tier-two Indian cities beyond Mumbai and Delhi with pressed powder accessibility formats. Lead with transparency-focused positioning verified through third-party certification apps to fragment established brand loyalty among beauty enthusiasts. For Investors and Strategic Acquirers: Beauty conglomerates with integrated R&D infrastructure are the most active acquirer in this space, seeking targets with REACH-compliant formulation libraries and established professional channel relationships. Mid-scale specialty brands with dual-certification capabilities and direct-to-artist subscription mechanics represent priority acquisition archetypes. Monitor REACH Annex XVII microplastic restriction enforcement timelines as the critical signal for reformulation investment cycles and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Portfolio Expansion | REACH and NMPA compliance unlocks priority distribution channels in EU and China markets. |
| Micronized Silica Technology Licensing | Controlled porosity particulates displace talc in professional artist kits ahead of regulatory bans. |
| Direct-to-Artist Subscription Launch | Bypasses traditional retail markups for recurring bulk procurement from film production crews. |
| Backward Integration into Raw Material Processing | Captive silica qualification secures supply chains against input volatility and contamination concerns. |
| Clean Beauty Sustainability Repositioning | Biodegradable film-formers substitute synthetic vehicles under REACH Annex XVII microplastic restrictions. |
Research Methodology
Direct dialogue with cosmetic chemists, professional makeup artists, regulatory affairs specialists at beauty conglomerates, and procurement managers at specialty supply houses grounded qualitative insights, cross-referenced with customs records, ECHA REACH registration databases, NMPA cosmetic filing disclosures, and SEC 10-K filings from listed beauty companies. Bottom-up and top-down triangulation validated volume estimates against production capacity data from Guangzhou and Shanghai manufacturing clusters.
Bottom-up modeling aggregated segment-level demand across product type, formulation, end user, and distribution channel dimensions, while top-down constraints checked aggregate outputs against macroeconomic indicators and beauty industry revenue trends. CAGRs were derived from regression analysis of historical volume trajectories and forward-looking regulatory impact assessments. Forecast inputs incorporated REACH Annex XVII enforcement timelines, NMPA registration processing rates, and professional artist channel growth patterns.
The model assumes a particular technology adoption path; alternative pathways for starch-based and biodegradable film-former formulations would alter the outlook if clean beauty preference shifts accelerate beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and raw material substitution elasticities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Professional Scalp Care Products Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Eyeliner Pen Market