
 Home Theater Systems Market | 2026-2036
Home Theater Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Home Theater Systems Market Outlook
Multi-source component procurement is realigning how manufacturers balance cost control against acoustic consistency. Sony Corporation leverages in-house semiconductor fabrication to secure proprietary signal-processing chips for its receiver lines. Bose Corporation sustains premium positioning through controlled distribution and proprietary speaker array designs. Samsung Electronics anchors volume production by operating vertically integrated display and audio supply chains across multiple Asian facilities.
Home theater systems integrate amplifiers, speakers, source components, and display devices to reproduce cinema-grade audio-visual experiences in domestic or semi-commercial environments, with power output, channel count, and frequency response defining performance tiers. Soundbars dominate unit shipments due to spatial constraints in urban apartments, while Dolby Atmos-enabled configurations command margin pools as consumers prioritize height-channel immersion over legacy surround formats. AV Receivers retain structural importance among enthusiast segments where modular upgrade paths preserve long-term customer value.
The Federal Communications Commission governs wireless transmission standards for rear-channel and subwoofer connectivity in the United States, while the EU Green Deal's ecodesign requirements mandate standby power limits for networked audio equipment sold across Europe. China's MIIT enforces GB standards for electromagnetic compatibility that shape product certification timelines for imported amplification hardware. Stakeholders must monitor evolving energy efficiency mandates and wireless spectrum reallocations that could obsolete existing connectivity protocols before replacement cycles complete.
Market Dynamics
Object-based audio formats are compressing replacement cycles and forcing manufacturers to redesign amplification architectures around height-channel processing, while semiconductor sourcing constraints reshape component availability timelines across the supply base.
Growth Catalysts
- Dolby Atmos penetration:Height-channel configurations are pulling residential consumers toward full receiver-and-speaker upgrades from legacy soundbar setups, expanding addressable hardware spend per household.
- EU Green Deal ecodesign mandates:Standby power limits for networked audio equipment are accelerating efficiency investments that differentiate premium product lines in European retail channels.
- China's urban apartment densification:Space-constrained living environments in tier-one cities are concentrating demand for compact yet immersive audio solutions that replicate cinema experiences domestically.
Market Restraints
- Semiconductor input volatility:Proprietary signal-processing chips face extended lead times from foundry capacity constraints, compressing margin visibility for amplification hardware manufacturers.
- Wireless spectrum fragmentation:Rear-channel and subwoofer connectivity protocols lack unified standards across regulatory jurisdictions, forcing redundant SKU development for multi-region product lines.
- Soundbar substitution pressure:All-in-one audio bars with virtualized surround processing satisfy mainstream acoustic expectations at lower price points, constraining full-system category expansion.
Strategic Opportunities
- Germany's retrofit housing stock:Existing residential structures with dedicated media rooms present installation service attach-rate potential for custom integration providers.
- Wireless convergence with Wi-Fi 6E:Uncompressed multi-channel audio streaming over enhanced wireless protocols enables cable-free speaker placement without proprietary radio hardware.
- India's import tariff structure:Local assembly incentives under PLI scheme provisions create manufacturing cost advantages for regional market penetration.
Industry Challenges
- Acoustic calibration expertise scarcity:Room-correction algorithm deployment requires specialized audio engineering talent that concentrates in legacy AV integration firms.
- Legacy HDMI interconnect compatibility:Existing display and source device installed bases force continued support for outdated handshake protocols, complicating firmware maintenance.
- Certification timeline compression:GB standards enforcement by China's MIIT extends electromagnetic compatibility testing durations for amplification hardware imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Theater Systems Market |
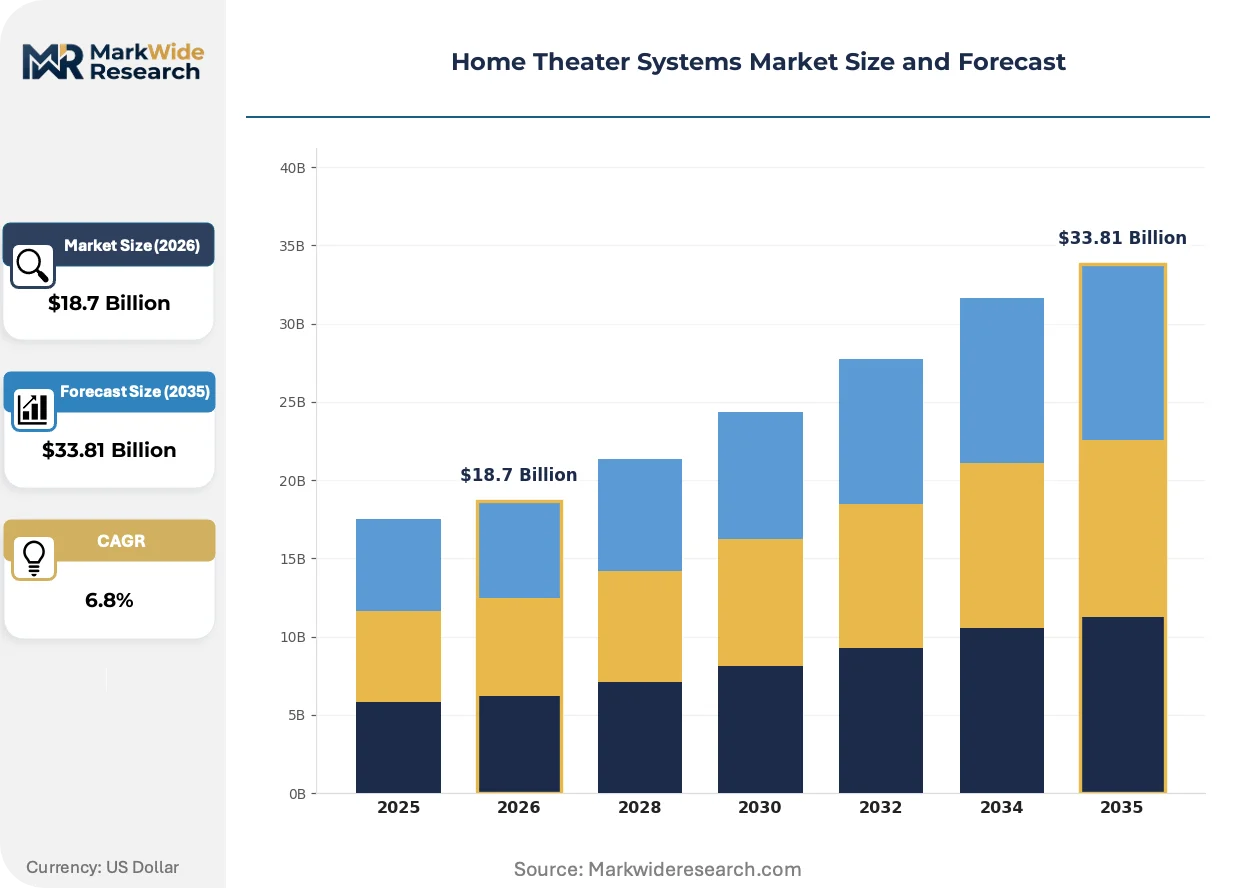
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soundbars, AV Receivers, Projectors, Home Theater Speakers Technology: Dolby Atmos, DTS:X, 4K UHD, Smart TV End User: Residential, Commercial, Cinemas, Educational Institutions Distribution Channel: Online Retail, Specialty Stores, Electronics Chains, Wholesale |
| Companies Covered | LG Electronics, Pioneer Corporation, Bose Corporation, Denon, Onkyo Corporation, Sony Corporation, Yamaha Corporation, JBL, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Theater Systems Market Strategic Shifts
Wireless audio transmission standards and spatial processing algorithms are redistributing value capture between component manufacturers and software licensors, while installation service models adapt to declining consumer technical proficiency.
Immersive audio processing hardware is modularizing around discrete height-channel amplification blocks that integrate with existing receiver platforms. Enthusiast segments are adopting these add-on modules faster than full-system replacements, compressing average selling prices for base units while expanding attach-rate potential for upgrade components. This architecture is modularizing how manufacturers stage product roadmaps and manage inventory risk across replacement cycles.
The EU Green Deal's ecodesign requirements are mandating networked standby power limits below two watts for audio equipment sold across Europe. Manufacturers are redesigning power supply architectures and firmware sleep states to maintain network connectivity at reduced consumption levels. Premium receiver lines targeting German and French markets are absorbing these engineering costs into tiered product positioning.
Direct-to-consumer channel expansion is compressing traditional AV retailer margins and shifting technical support burdens onto manufacturer service organizations. Online-first buyers in the United States are demanding remote calibration assistance and video-based installation guidance that replaces in-store consultation. This behavioral shift concentrates in metropolitan markets where dedicated home theater retailers have contracted footprint.
Home Theater Systems Market Segmentation
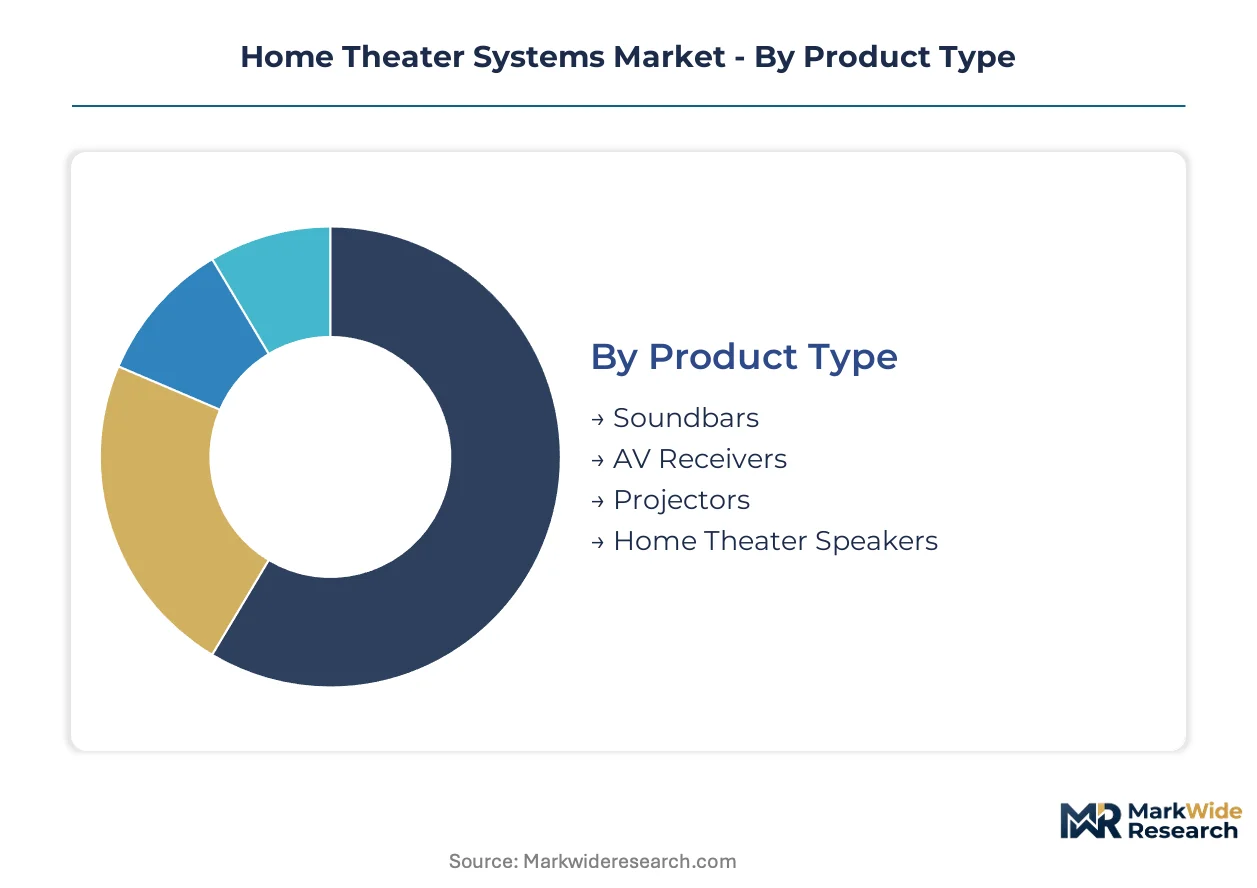
Home theater systems fragment across acoustic architectures, signal processing standards, and installation complexity tiers that reshape capital deployment for manufacturers. Each segmentation dimension carries distinct margin profiles and replacement cycle dynamics that determine competitive positioning.
Product Type:
Capital intensity varies sharply across acoustic form factors, with multi-channel amplification hardware demanding substantially higher upfront tooling investment than compact integrated solutions.
- Soundbars:Integrated speaker arrays with built-in amplification and wireless subwoofer pairing dominate unit shipments in space-constrained urban apartments. Demand concentrates in China's tier-one cities where apartment densification limits floor-standing speaker placement, though virtualized surround processing constrains premium pricing power compared to discrete channel systems.
- AV Receivers:Modular amplification platforms with HDMI switching and object-based audio decoding require substantial semiconductor content and thermal management engineering. Enthusiast segments in the United States and Germany sustain demand for upgradeable architectures that preserve long-term customer value through firmware-expandable channel counts.
- Projectors:DLP and LCoS imaging engines with high-lumen output for ambient-light rejection.
- Home Theater Speakers:Floor-standing, bookshelf, and in-wall transducer arrays requiring acoustic cabinet engineering.
Most installed capacity flows through Soundbars. Expansion is steepest in AV Receivers.
Technology:
Intellectual property licensing structures differentiate margin capture between audio format stewards and hardware implementers.
- Dolby Atmos:Object-based audio encoding with height-channel metadata enables immersive soundscapes through ceiling-mounted or up-firing speaker modules. Residential consumers in the United States and Germany are pulling toward full receiver-and-speaker upgrades from legacy configurations, expanding addressable hardware spend per household despite proprietary licensing fees.
- DTS:X:Flexible object-based alternative with speaker-agnostic rendering algorithms. Demand concentrates among value-oriented enthusiasts seeking immersive audio without ecosystem lock-in, particularly in Asian markets where alternative format adoption accelerates through bundled licensing arrangements.
- 4K UHD:High-resolution video transmission with HDR metadata and HDCP encryption.
- Smart TV:Integrated streaming platforms with wireless audio output protocols.
Format licensing revenue concentrates with Dolby Atmos. DTS:X is gaining share fastest in price-sensitive tiers.
End User:
Application context determines acoustic performance requirements and installation service attach rates.
- Residential:Domestic living spaces with variable room acoustics and aesthetic constraints represent the primary adoption vector for immersive audio-visual equipment. Consumers upgrading entertainment infrastructure in the United States, China, and Germany drive premium configuration demand where disposable income supports dedicated media room investments.
- Commercial:Hospitality and corporate environments with distributed audio requirements.
- Cinemas:Post-production screening rooms and premium exhibition spaces.
- Educational Institutions:Lecture halls and media studies facilities with budget-constrained procurement.
Revenue concentration sits with Residential. Commercial applications are expanding most quickly as hybrid work normalizes corporate amenity investments.
Distribution Channel:
Channel mix determines technical support burdens and margin retention for manufacturers.
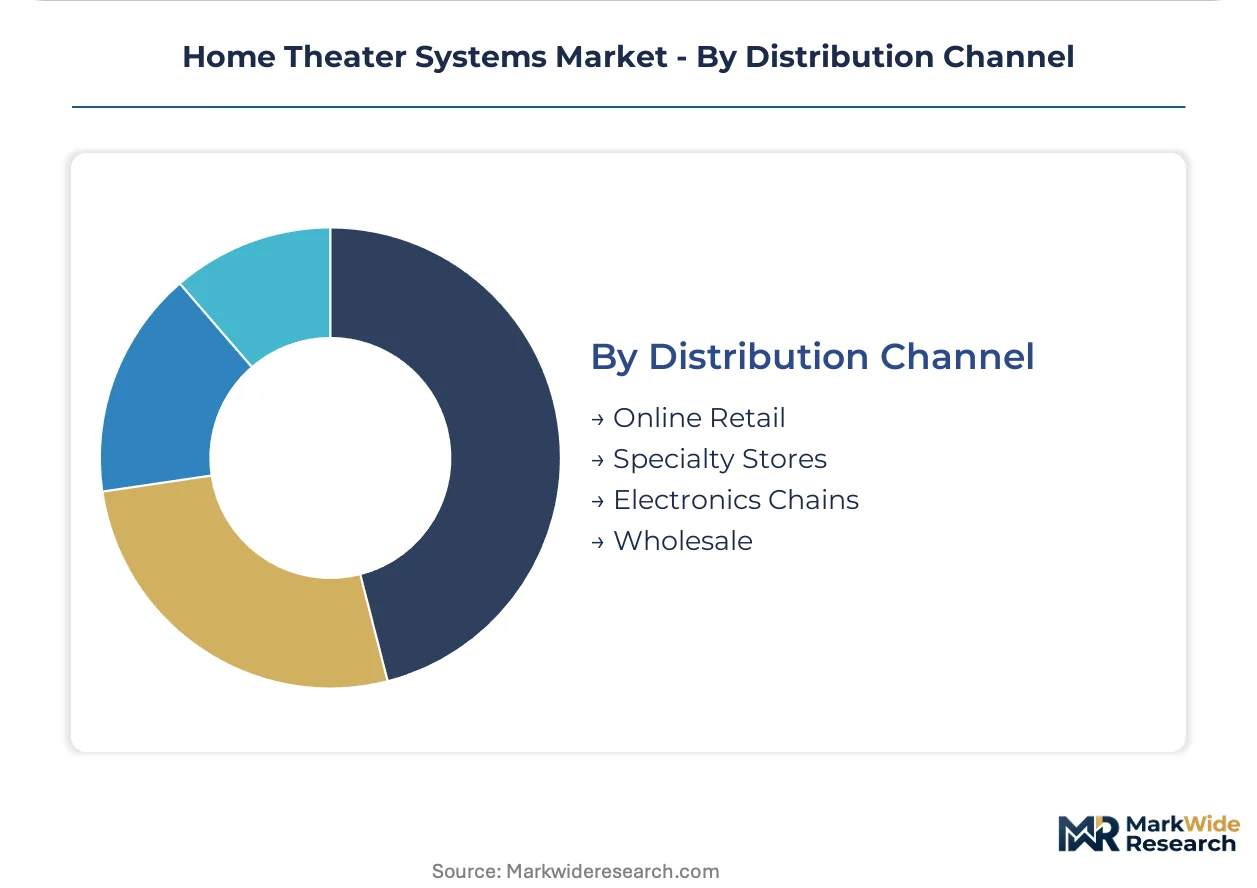
- Online Retail:Direct-to-consumer platforms with video-based installation guidance and remote calibration assistance. Metropolitan markets in the United States show accelerating concentration here as dedicated home theater retailer footprints contract, shifting pre-purchase consultation burdens onto manufacturer service organizations.
- Specialty Stores:Custom integration showrooms with in-room demonstration capabilities.
- Electronics Chains:Mass-market retailers with limited acoustic expertise and return-rate exposure.
- Wholesale:Builder and architect specification channels for new construction pre-wiring.
Volume flows through Electronics Chains. Margin retention is strongest in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor supplies amplification hardware and speaker components to brands worldwide, anchoring production capacity for object-based audio systems. Consumer demand concentrates in affluent metropolitan clusters across three continents.
United States
Residential media room investments and streaming service penetration drive hardware upgrades in suburban markets. The Federal Communications Commission governs wireless transmission standards for rear-channel connectivity, shaping product certification requirements. Austin and Seattle host engineering operations for spatial audio algorithm development.
Germany
Retrofit housing stock with dedicated entertainment spaces sustains demand for discrete channel systems. EU Green Deal ecodesign mandates enforce standby power limits below two watts for networked audio equipment. Berlin and Munich concentrate custom integration showrooms serving high-end residential clients.
China
Tier-one city apartment densification accelerates compact immersive audio adoption despite spatial constraints. MIIT enforces GB standards for electromagnetic compatibility that extend certification timelines for imported amplification hardware. Shenzhen and Dongguan anchor vertically integrated manufacturing clusters for transducer and semiconductor components.
India
Rising disposable income in metropolitan areas supports premium home cinema investments among affluent households. PLI scheme provisions create local assembly incentives that reduce manufacturing costs for regional market penetration. Mumbai and Bangalore concentrate distribution infrastructure for imported audio-visual equipment.
Japan
Enthusiast segments sustain demand for modular receiver architectures with firmware-expandable capabilities. METI oversees industrial standards for high-resolution audio transmission protocols. Tokyo and Osaka host specialized retailers serving audiophile communities with demonstration facilities.
Home Theater Systems Market Competitive Environment
Global majors compete with regional champions across semiconductor sourcing and acoustic engineering capabilities. The vendor base organizes into three tiers: integrated electronics conglomerates with captive display supply chains, audio specialists with proprietary transducer technologies, and contract manufacturers serving private-label brands. Strategic moves concentrate on backward integration into signal-processing chip design and geographic expansion through direct-to-consumer channel development.
Within the premium audio tier, Bose Corporation and Sony Corporation exemplify positioning through controlled distribution and in-house semiconductor fabrication respectively. Samsung Electronics anchors volume production through captive supply of display and audio components across Asian facilities. These three entities represent divergent strategic archetypes: proprietary ecosystem lock-in, vertical manufacturing control, and platform-scale integration.
| Leading Market Players |
|---|
| LG Electronics |
| Pioneer Corporation |
| Bose Corporation |
| Denon |
| Onkyo Corporation |
| Sony Corporation |
| Yamaha Corporation |
| JBL |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
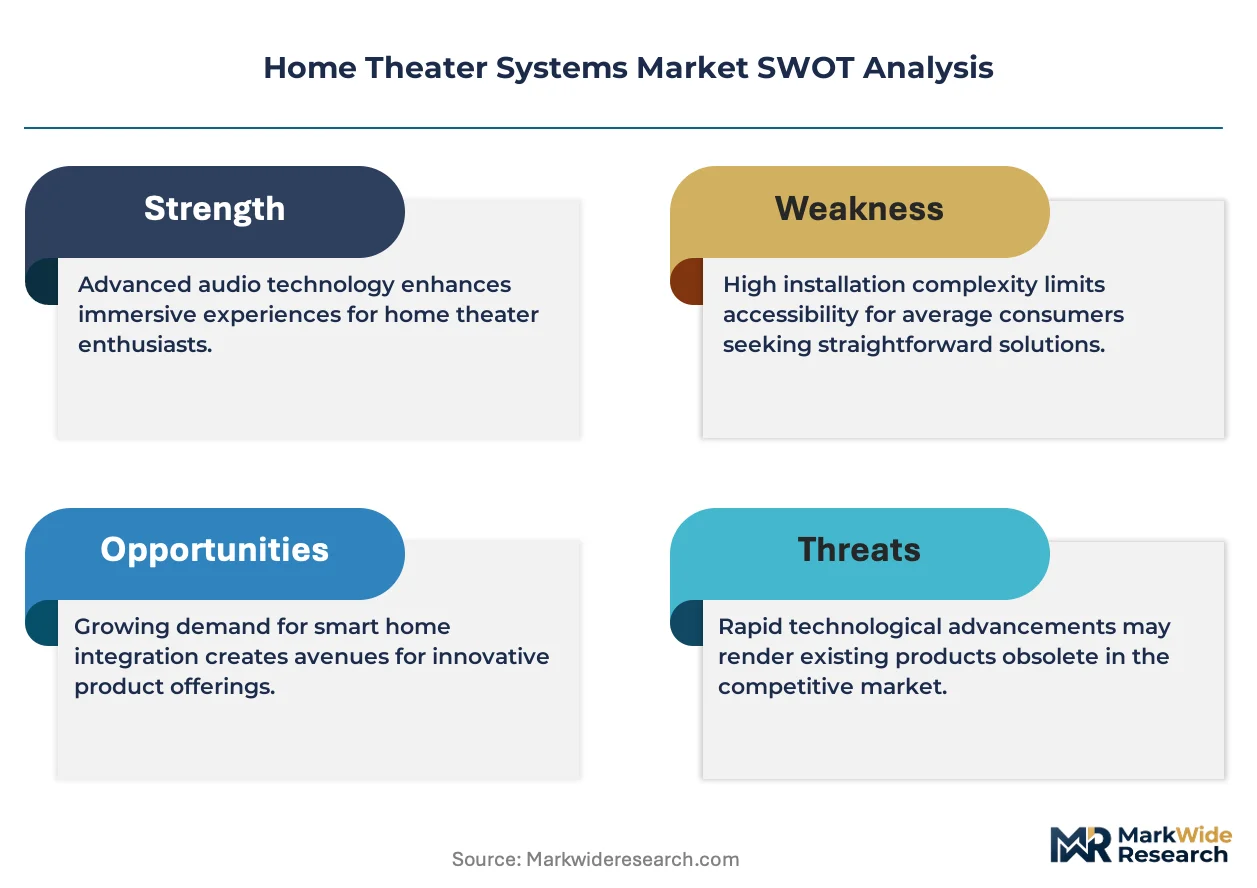
Dolby Atmos certification tiers split home theater hardware into parallel cost structures that diverge sharply in semiconductor content and foundry access. Premium receiver lines absorb proprietary licensing fees and discrete height-channel amplification blocks, while entry-level soundbars compete on consolidated chip designs sourced from open-architecture suppliers.
Pricing Analysis
Input-cost pass-through from signal-processing semiconductors is compressing margins for mid-tier AV receiver manufacturers without captive foundry relationships. Three-tier pricing structure across premium, standard, and economy levels separates Dolby-licensed immersive configurations from virtualized surround alternatives and basic stereo bars. Pricing pressure stems from soundbar substitution in China's tier-one cities, where apartment densification constrains floor-standing speaker placement. Residential enthusiasts in Germany and the United States show lowest price sensitivity, prioritizing modular upgrade paths over initial acquisition cost.
Supply Chain Analysis
Workforce availability in Shenzhen and Dongguan anchors transducer and amplification hardware production for global brands. Semiconductor inputs draw from Taiwan foundries and South Korean memory suppliers, while rare-earth magnets for speaker drivers concentrate in Chinese processing facilities. Single-source vulnerability in proprietary Dolby decoding chips creates bottlenecks for receiver manufacturers without backward integration into chip design. Distribution runs through vertically integrated electronics conglomerates with captive Asian manufacturing footprints and direct-to-consumer platforms with remote calibration service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal ecodesign mandates are accelerating efficiency investments that differentiate premium product lines and compress laggard margins.
For Market Incumbents: Lock in semiconductor sourcing through captive foundry partnerships or long-term allocation agreements with Taiwan suppliers, insulating against lead-time volatility that threatens receiver production schedules. Deepen proprietary ecosystem control by integrating room-correction algorithms with hardware sales, countering direct-to-consumer entrants lacking acoustic calibration expertise.
For New Entrants and Emerging Players: Capture India's PLI scheme assembly incentives to establish regional manufacturing cost advantages beneath import tariff barriers. Target Germany's retrofit housing stock with installation-service bundling for existing media rooms, penetrating where custom integration providers concentrate showroom presence.
For Investors and Strategic Acquirers: Asymmetric upside sits with modular amplification specialists possessing firmware-expandable receiver architectures and established enthusiast channel relationships. Five-to-ten-year viability hinges on format licensing diversification beyond single-ecosystem dependency. Monitor Wi-Fi 6E wireless audio convergence as inflection indicator for cable-free speaker placement adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Signal-Processing Semiconductors | Sony's captive chip fabrication secures proprietary receiver lines against foundry allocation constraints. |
| Direct-to-Consumer Channel Expansion | Online-first buyers in US metropolitan markets demand remote calibration replacing in-store consultation. |
| EU Ecodesign Compliance Investment | Premium receiver lines absorb sub-two-watt standby power engineering into tiered German positioning. |
| Modular Height-Channel Amplification Blocks | Add-on modules compress base-unit ASPs while expanding attach-rate potential across enthusiast segments. |
| PLI Scheme Local Assembly in India | Mumbai and Bangalore distribution infrastructure supports regional cost advantages for market penetration. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's stakeholder ecosystem. The analysis combines interviews with AV receiver product managers, custom integration showroom operators, semiconductor procurement leads, and streaming platform hardware partnership directors with secondary validation from FCC equipment authorization databases, EU ecodesign regulatory filings, MIIT GB standard certification records, and customs trade data for amplification hardware imports. Bottom-up shipment modeling and top-down consumer expenditure triangulation cross-validate volume and value estimates.
Rate-of-change decomposition separates replacement-cycle compression effects from format-upgrade acceleration and wireless protocol transition impacts across the projection horizon. Segmentation dimensions include acoustic form factor, object-based audio format, installation complexity tier, and regional regulatory cluster. CAGRs derive from logistic diffusion modeling of immersive audio adoption curves and input-cost trajectory assumptions for semiconductor content. Industry-specific forecast inputs incorporate Dolby licensing fee structures and Wi-Fi 6E chipset availability timelines.
Semiconductor allocation disruptions, wireless spectrum reallocation decisions, and object-based audio format substitution velocity are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding replacement cycle duration and premium-tier price elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Cleaning Appliance Market
Consumer Goods
Global Fragrances and Perfumes Market
Consumer Goods
Latin America Jewelry Market
Consumer Goods
India Small Home Appliances Market
Consumer Goods
Men Shirts Market
Consumer Goods
Screen Cleaner Market
Consumer Goods
Pet Accessories Market
Consumer Goods
Disposable Electric Toothbrushes Market
Consumer Goods
Smart Cleaning and Hygiene Market
Consumer Goods
Electric Facial Cleansing Brush Market
Consumer Goods
Toilet Care Products Market
Consumer Goods
Sports Shoes Market
Consumer Goods
Luxury Watches Market
Consumer Goods
Middle East and Africa Beauty and Personal Care Products Market
Consumer Goods
Sports Bras Market
Consumer Goods
Asia-Pacific E Cigarettes Market