
 Phone Headsets Market | 2026-2036
Phone Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Phone Headsets Market Insights
Enterprise buyers are bifurcating from personal consumers as the dominant volume segment in phone headsets. Apple leverages its ecosystem control to anchor premium wireless deployments in corporate settings. Sony competes through audio fidelity specialization that targets gaming and professional hybrid users. Sennheiser Electronic GmbH sustains its position in call center infrastructure through durable wired and wireless configurations engineered for all-day wear.
Phone headsets are electro-acoustic transducer assemblies designed for bidirectional voice communication, typically incorporating noise-canceling microphones, 20 Hz–20 kHz frequency response drivers, and digital signal processing for echo suppression. Their primary commercial purpose is to enable hands-free telephony in professional environments where clarity and ergonomic endurance determine productivity outcomes. Wireless Bluetooth headsets now lead enterprise refresh cycles while USB-C connectivity is displacing analog interfaces in hardware procurement specifications. Over-ear designs capture margin pools in aviation and financial trading floors where isolation and comfort justify premium positioning.
The Federal Communications Commission governs radio frequency emissions for wireless headsets sold in the United States, while the EU F-Gas Regulation and REACH directives constrain material choices and battery disposal pathways for products entering European markets. Enterprise buyers must now navigate overlapping compliance requirements from OSHA ergonomic standards and GDPR-aligned data handling protocols embedded in headset firmware. Stakeholders should monitor how upcoming energy efficiency certifications and right-to-repair legislation reshape total cost of ownership calculations across procurement categories.
Market Dynamics
Enterprise procurement of wireless headsets is accelerating as hybrid work protocols become permanent, forcing vendors to reconfigure product roadmaps around Bluetooth Low Energy audio standards and USB-C mandates from the EU.
Growth Catalysts
- Bluetooth Low Energy Audio:The new LC3 codec reduces power consumption by fifty percent while doubling audio quality, enabling all-day battery life in lightweight form factors that call center operators demand.
- EU USB-C Mandate:Directive 2022/2380 requires universal charging ports for small electronics, eliminating proprietary connectors and simplifying enterprise fleet management across multi-vendor environments.
- Aviation Over-Ear Demand:Flight deck communication requirements are driving premium noise-canceling specifications that migrate downward into financial trading floor deployments.
Market Restraints
- Lithium Supply Concentration:Battery cell manufacturing clusters in China's Hunan and Jiangxi provinces create geopolitical exposure for wireless headset production schedules.
- REACH Compliance Costs:ECHA substance restrictions on flame retardants and plasticizers force reformulation of headband padding and ear cushion foams, adding twelve to eighteen months to product certification timelines.
- Smartphone Speaker Substitution:Improved beamforming microphones in handsets reduce headset dependency for casual voice calls among consumer segments.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for electronics manufacturing attract assembly operations serving domestic IT services and business process outsourcing sectors.
- Hearing Health Integration:Convergence of hearing aid DSP architectures with consumer headset platforms opens regulated medical device channels previously inaccessible to audio brands.
- Direct Enterprise SaaS Bundling:Unified-communications-as-a-service vendors now embed hardware subscriptions, bypassing traditional distribution tiers.
Industry Challenges
- Acoustic Engineering Talent Scarcity:DSP firmware development for multi-microphone beamforming requires specialized expertise concentrated in Denmark and California.
- Interoperability Certification Delays:Microsoft Teams and Zoom qualification programs create bottlenecks that stall product launches by three to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phone Headsets Market |
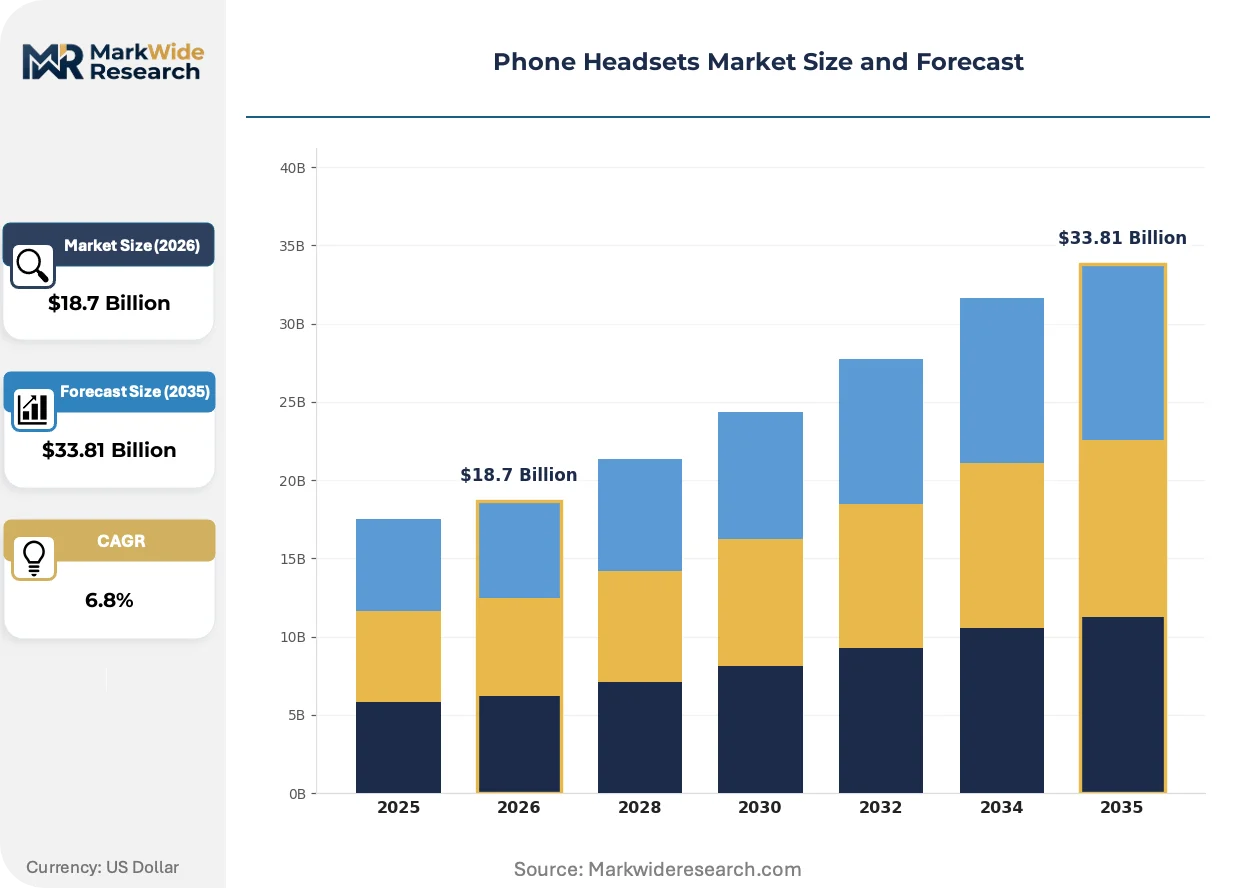
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless, Wired, Over-Ear, In-Ear Technology: Bluetooth, NFC, USB-C, Analog End User: Enterprise, Gaming, Personal Use, Call Centers Distribution Channel: Online Retail, Physical Stores, Direct Sales, Resellers |
| Companies Covered | Apple Inc., Sony Corporation, Samsung Electronics, Bose Corporation, Sennheiser Electronic GmbH, Logitech International, HP Inc., GN Store Nord, Skullcandy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phone Headsets Market Trends and Innovations
Audio hardware is undergoing platform convergence as voice communication, hearing assistance, and biometric monitoring merge into single wearable devices. This integration is compressing development cycles and blurring traditional category boundaries.
LC3 codec implementation is supplanting legacy SBC and AAC transmission in enterprise-grade wireless headsets. Fortune 500 IT departments are specifying LE Audio compatibility in refresh tenders issued this quarter. The shift is compressing ASP differentiation between mid-tier and premium SKUs as codec performance becomes table stakes.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are phasing out specific blowing agents used in memory foam ear cushions. Manufacturers are reformulating with water-blown alternatives that alter acoustic damping properties. German industrial testing houses report extended validation cycles as suppliers iterate density specifications.
Corporate buyers are consolidating vendor relationships through hardware-as-a-service subscriptions that bundle devices, firmware updates, and end-of-life recycling. This displaces capital expenditure models and compresses replacement cycles from thirty-six to twenty-four months. United States federal contractor compliance requirements are accelerating this transition in government-facing professional services.
Phone Headsets Market Segmentation
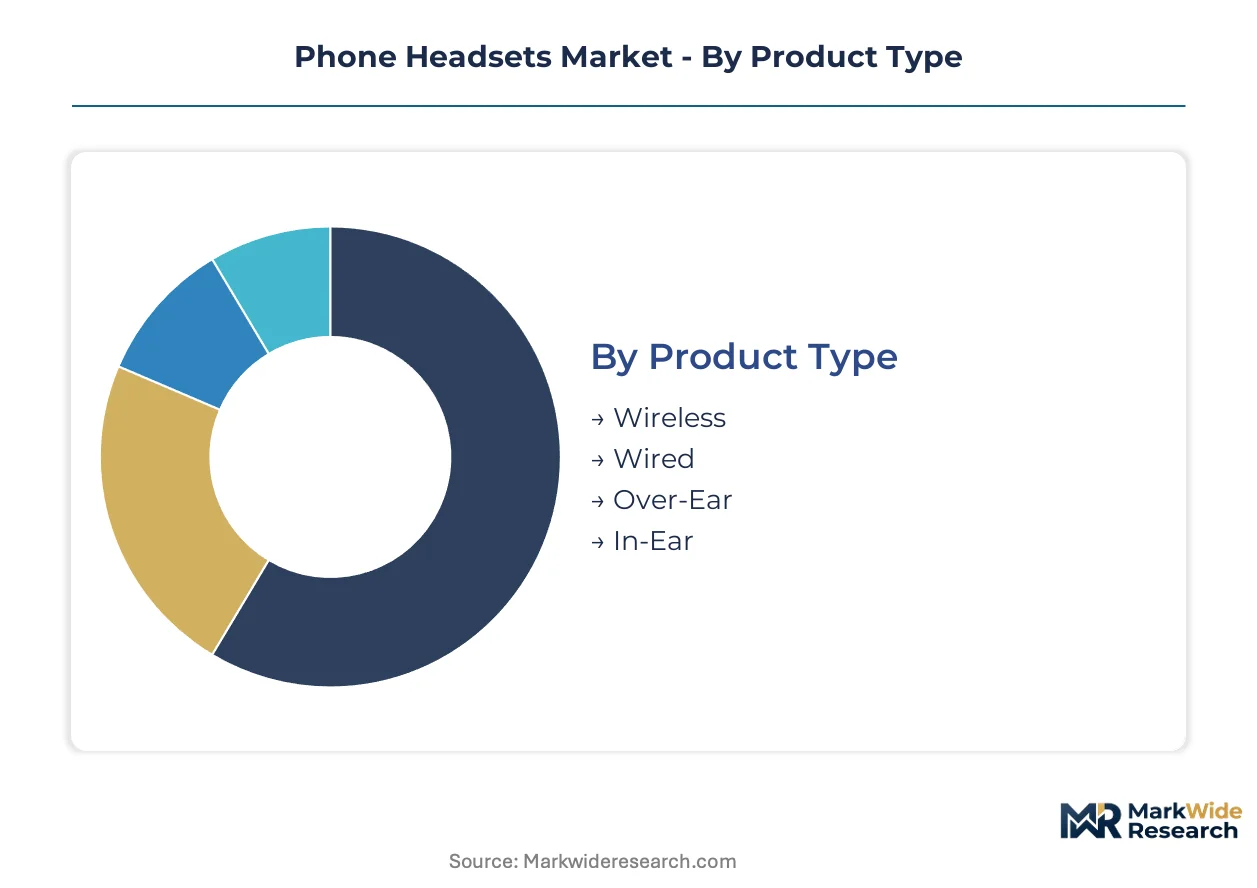
Phone headset procurement splits sharply between enterprise fleet buyers and individual consumers, with technical specifications and compliance requirements diverging across each channel. Vendors must architect separate product lines to capture margin in premium corporate deployments while defending volume in price-sensitive personal use segments.
Product Type:
Wireless configurations face intensifying substitution pressure from smartphone speakerphone quality improvements, while wired headsets retain defensible positions in security-sensitive environments.
- Wireless:Bluetooth Low Energy Audio implementations with LC3 codec support now dominate Fortune 500 refresh tenders. Microsoft Teams and Zoom certification requirements filter procurement toward qualified vendors, compressing replacement cycles from thirty-six to twenty-four months in United States federal contractor environments.
- Over-Ear:Aviation-grade noise-canceling specifications migrate into financial trading floors where isolation and all-day comfort justify premium positioning. EU F-Gas Regulation constraints on memory foam blowing agents extend German industrial testing cycles as suppliers reformulate acoustic damping properties.
- Wired:USB-C connectivity displaces analog interfaces in hardware procurement specifications following Directive 2022/2380 mandates.
- In-Ear:Lightweight form factors target mobile professionals requiring discrete telephony during transit.
Wireless retains volume leadership; over-ear holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium codec implementations from legacy transmission standards, with USB-C mandates forcing rapid interface transitions across enterprise fleets.
- Bluetooth:LE Audio compatibility now specified in corporate tenders issued this quarter, with LC3 implementation supplanting legacy SBC and AAC transmission. The fifty percent power reduction enables all-day battery life that call center operators demand.
- USB-C:EU Directive 2022/2380 eliminates proprietary connectors, simplifying fleet management across multi-vendor enterprise environments. United States federal agencies align procurement to this standard for interoperability compliance.
- NFC:Tap-to-pair functionality accelerates deployment in high-turnover contact center seating configurations.
- Analog:Declining share concentrates in legacy aviation and military communication systems with extended certification timelines.
Bluetooth commands volume leadership; USB-C climbs the fastest as regulatory deadlines approach.
End User:
Application-specific requirements fragment the vendor base, with call center durability specifications diverging sharply from gaming audio fidelity demands.
- Enterprise:Hardware-as-a-service subscriptions displace capital expenditure models, bundling devices with firmware updates and end-of-life recycling. OSHA ergonomic standards and GDPR-aligned data handling protocols in headset firmware create overlapping compliance requirements.
- Call Centers:All-day wear specifications prioritize durable headband padding and replaceable ear cushions. India PLI scheme incentives attract assembly operations serving domestic IT services and business process outsourcing sectors.
- Gaming:Spatial audio and low-latency transmission target professional hybrid users demanding broadcast-quality voice streaming.
- Personal Use:Beamforming microphone improvements in handsets reduce headset dependency for casual voice calls.
Enterprise retains volume leadership; call centers gain share fastest as outsourcing expands.
Distribution Channel:
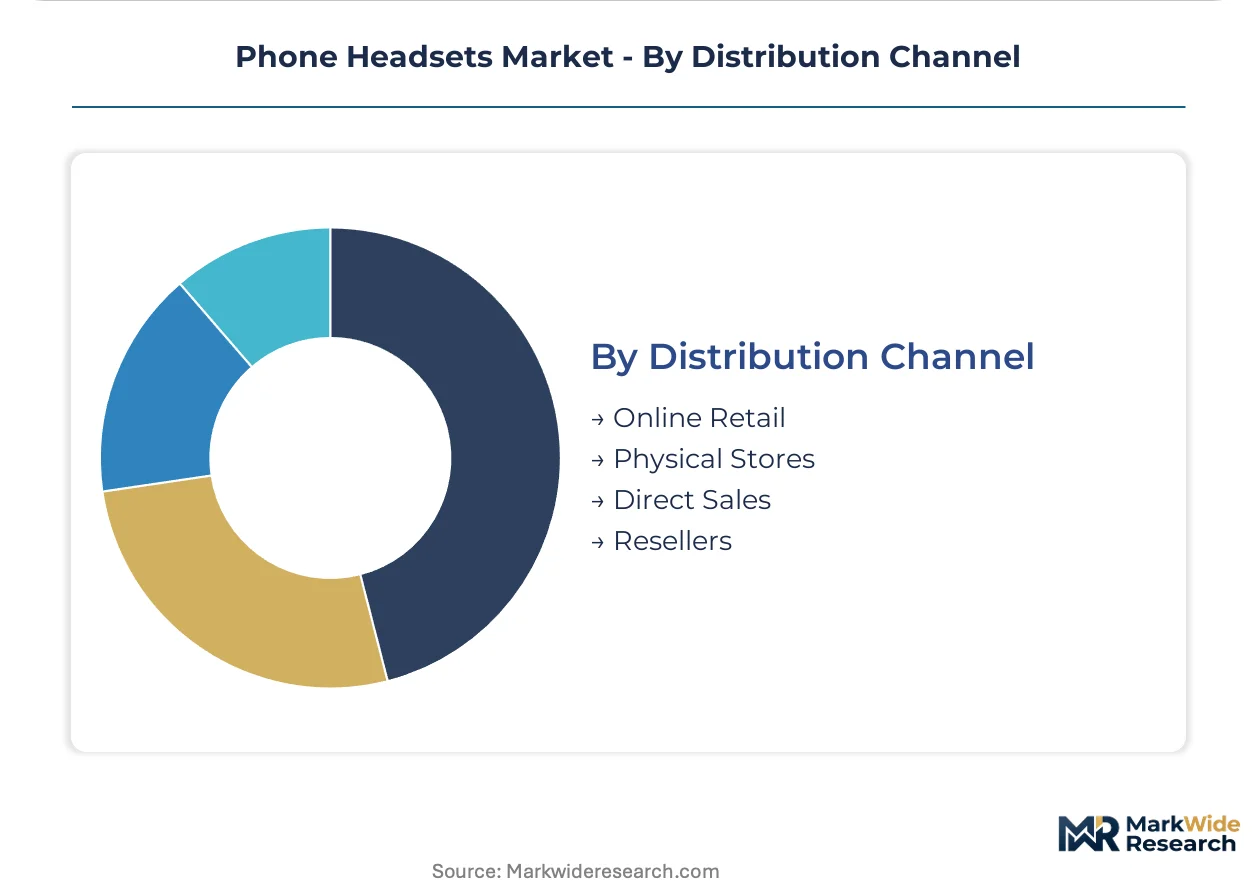
Customer type concentration drives channel strategy, with direct enterprise relationships capturing margin while online retail defends consumer volume.
- Direct Sales:Unified-communications-as-a-service vendors embed hardware subscriptions, bypassing traditional distribution tiers. Corporate buyers consolidate vendor relationships through multi-year fleet agreements.
- Online Retail:Consumer self-selection dominates personal use procurement, with specification comparison tools compressing mid-tier and premium ASP differentiation.
- Resellers:Value-added distributors manage Microsoft Teams and Zoom qualification bottlenecks that stall product launches.
- Physical Stores:Fitting and ergonomic assessment retain relevance for over-ear aviation and enterprise trial programs.
Direct sales retains volume leadership; online retail expands most quickly in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States drive the largest procurement volumes for phone headsets, with call center modernization and federal IT refresh cycles concentrating demand in specific metropolitan corridors. Hybrid work permanence has shifted procurement authority from individual consumers to fleet managers in corporate IT departments.
United States
Federal contractor compliance requirements and OSHA ergonomic standards are accelerating hardware-as-a-service adoption among professional services firms. The FCC governs radio frequency emissions for wireless headsets sold domestically. Dallas-Fort Worth and Phoenix host major call center operations where all-day wear specifications dominate procurement tenders.
Germany
Industrial testing houses in Stuttgart and Munich validate acoustic damping properties for reformulated ear cushion foams. The ECHA REACH directive restricts flame retardants and plasticizers in headband padding, extending certification timelines. Bavaria-based manufacturing clusters supply durable wired configurations engineered for European enterprise fleets.
India
Business process outsourcing expansion in Bangalore and Hyderabad is driving volume procurement from domestic assembly operations. The PLI scheme for electronics manufacturing attracts headset production serving IT services sectors. TRAI regulations on telecom equipment interoperability shape technical specifications for devices deployed in contact centers.
China
Battery cell manufacturing clusters in Hunan and Jiangxi provinces create supply concentration for wireless headset production schedules. MIIT standards govern Bluetooth transmission protocols and USB-C implementation timelines. Shenzhen-based electronics assemblers manage component sourcing for brands serving North American and European markets.
United Kingdom
Financial trading floors in London demand aviation-grade noise-canceling specifications that justify premium over-ear positioning. GDPR-aligned data handling protocols embedded in headset firmware create compliance requirements for enterprise deployments. The Midlands manufacturing corridor supplies wired USB-C configurations for public sector procurement frameworks.
Phone Headsets Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with audio divisions, creating a tiered structure where ecosystem control and component integration determine margin capture. Three strategic archetypes dominate: ecosystem-anchored platforms leveraging device integration, audio fidelity specialists targeting professional hybrid users, and infrastructure-grade suppliers engineered for call center durability. Competitive moves center on Microsoft Teams and Zoom qualification programs that stall product launches, plus hardware-as-a-service subscriptions that displace traditional distribution tiers.
Among Cupertino-based platform operators, Apple Inc. exemplifies ecosystem-anchored positioning through premium wireless deployments in corporate settings. Sony Corporation and Sennheiser Electronic GmbH occupy positions within the audio fidelity and infrastructure-grade tiers respectively, with the German GmbH structure indicating family-owned engineering heritage focused on durable configurations for all-day wear environments.
| Leading Market Players |
|---|
| Apple Inc. |
| Sony Corporation |
| Samsung Electronics |
| Bose Corporation |
| Sennheiser Electronic GmbH |
| Logitech International |
| HP Inc. |
| GN Store Nord |
| Skullcandy Inc. |
| Others |
Pricing and Supply Chain Analysis
LC3 codec adoption replacing legacy SBC transmission is redrawing procurement economics across enterprise fleets while compressing supplier margins in China and Vietnam assembly clusters. This substitution simultaneously shifts value capture toward Bluetooth semiconductor licensors and erodes pricing power for analog headset manufacturers in Dongguan.
Pricing Analysis
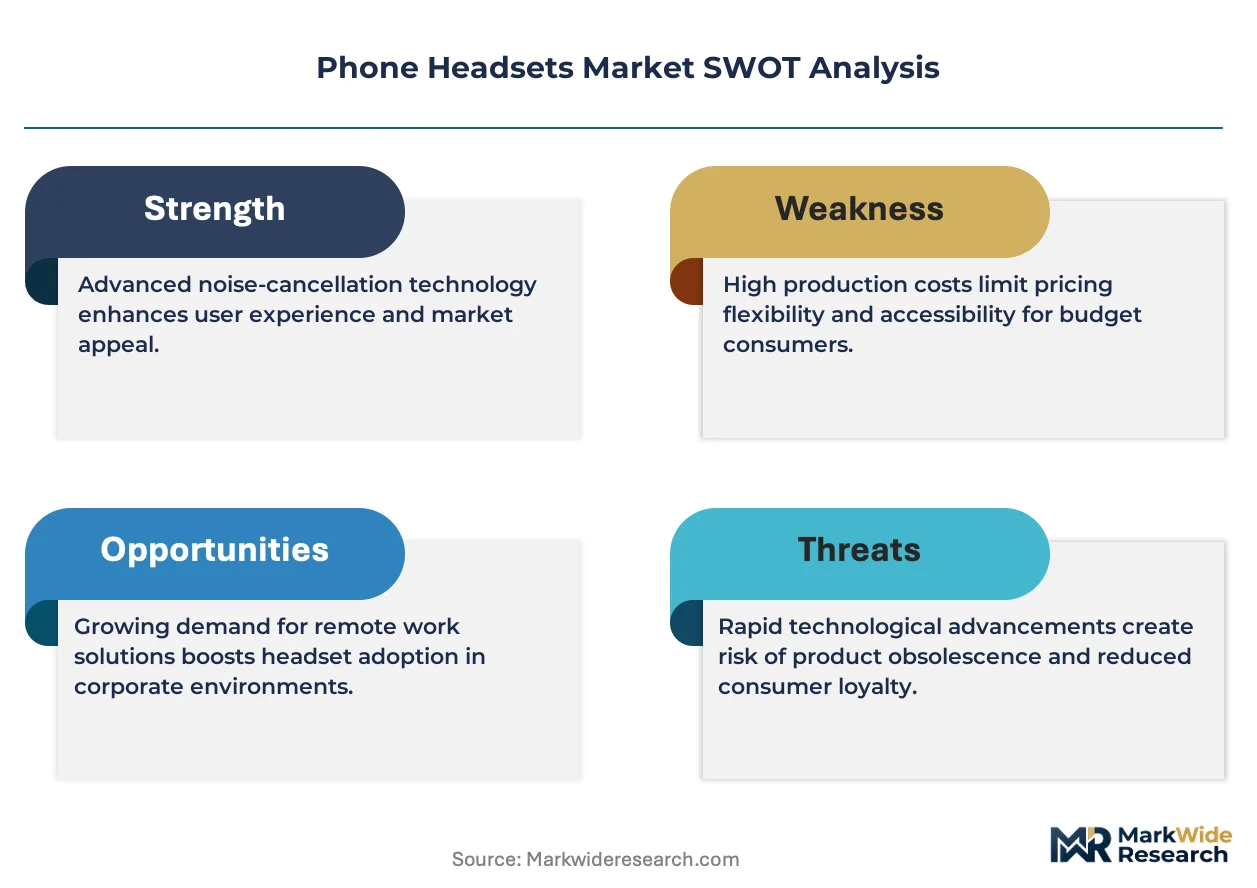
Bluetooth Low Energy Audio generation pricing gaps separate LC3-enabled premium tiers from SBC legacy mid-market and analog economy configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by Microsoft Teams certification status and battery endurance specifications. Cost compression in economy wired headsets is intensifying because USB-C mandate compliance absorbs engineering resources without commensurate ASP recovery. Call center operators exhibit highest price sensitivity; aviation and financial trading floors show lowest.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells from Hunan and Jiangxi provinces now dominates inventory strategy as procurement managers buffer against geopolitical disruption. Battery chemistry sourcing draws from China, South Korea, and Japan; acoustic driver manufacturing clusters in Shenzhen and Dongguan; final assembly concentrates in Vietnam and India under PLI incentives. Single-source vulnerability in rare-earth magnet supply creates exposure. Distribution runs through direct enterprise SaaS bundling and value-added resellers managing Teams certification workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise headset procurement sits at an early-cycle expansion story as hardware-as-a-service subscriptions penetrate federal contractor compliance environments and displace capital expenditure models.
For Market Incumbents: Secure Microsoft Teams and Zoom qualification pipelines as defensive moats against unlicensed competitors. Deepen backward integration into Bluetooth module design to capture codec licensing value pools. Prioritize firmware update infrastructure investments that sustain recurring revenue attachment rates under hardware-as-a-service contracts. For New Entrants and Emerging Players: Differentiate on hearing health convergence by pursuing FDA medical device pathways that incumbent consumer audio brands avoid. Target India's domestic IT services sector through PLI-linked assembly partnerships with Bangalore and Hyderabad BPO operators. Deploy direct enterprise sales teams that bypass crowded retail channel structures. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated component suppliers with captive DSP firmware capabilities. Long-term viability hinges on regulatory alignment across OSHA ergonomic mandates and GDPR data handling protocols. Acquisition target archetype: mid-tier vendors with established Teams certification and distressed by codec transition costs. Watch for inflection when hardware-as-a-service penetration crosses majority share in Fortune 500 tenders.| Strategic Initiative | Industry Significance |
|---|---|
| LE Audio Codec Integration | LC3 implementation halves power draw while doubling audio fidelity in enterprise wireless configurations. |
| Hardware-as-a-Service Launch | Subscription bundling compresses replacement cycles from thirty-six to twenty-four months in federal contractor environments. |
| Teams Certification Investment | Qualification bottlenecks stall unlicensed competitors by three to six months at product launch. |
| EU F-Gas Compliance Reformulation | Water-blown foam alternatives alter acoustic damping properties and extend German testing cycles. |
| India PLI Manufacturing Footprint | Production-linked incentives attract assembly serving domestic Bangalore and Hyderabad BPO sectors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with enterprise IT procurement officers, call center operations directors, acoustic engineering leads, and unified-communications platform vendors; and secondary validation against FCC equipment authorization databases, EU ECHA REACH substance restrictions, SEC 10-K filings from listed audio hardware manufacturers, and customs trade records from Vietnam and India electronics exports. Bottom-up volume triangulation across product type, technology, and end-user segments was cross-checked against top-down market sizing from enterprise fleet refresh disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including connectivity architecture, form factor tier, certification status, and geographic regulatory cluster. CAGRs were derived from weighted average of segment-level growth trajectories calibrated to enterprise procurement cycle timing and consumer replacement elasticity. Industry-specific forecast inputs incorporated Bluetooth SIG adoption curves for LE Audio and EU Directive 2022/2380 implementation timelines.
Material uncertainties — lithium supply disruption, REACH substance restriction amendments, and Teams certification backlog durations — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding hybrid work permanence and hardware-as-a-service penetration rates. Revision becomes warranted when battery chemistry cost volatility crosses thresholds that alter LC3 codec adoption economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Headset Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Armenia Consumer Goods Market