
 Automotive Microcontrollers (MCU) Market | 2026-2036
Automotive Microcontrollers (MCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Microcontrollers (MCU) Market Insights
Tier-1 supplier procurement is rebalancing toward direct MCU sourcing as OEMs consolidate domain controllers and zone architectures. Infineon Technologies AG dominates automotive powertrain silicon with in-house fabrication of AURIX multicore devices. NXP Semiconductors N.V. leverages its S32 platform to anchor safety-critical processing across brake-by-wire and steering systems. Texas Instruments Incorporated competes in isolated gate driver integration, extending its position into high-voltage traction inverter controls.
Automotive microcontrollers are integrated circuits designed for real-time embedded processing in vehicle subsystems, typically fabricated on 40nm to 28nm process nodes with lockstep cores, hardware security modules, and ASIL-D functional safety certification. Their primary purpose is to execute deterministic control loops for power conversion, sensor fusion, and actuator command under extreme temperature and vibration conditions. The 32-bit MCU category leads unit volume as automakers retire 8-bit and 16-bit legacy designs, while ARM-based MCU architectures capture the fastest-growing share of new electronic control unit designs. Safety Systems applications concentrate the highest margin pools due to ASIL certification barriers and long qualification cycles that lock in supplier relationships across vehicle generations.
FCC Part 15 emissions testing, UNECE WP.29 cybersecurity regulations, and ISO 26262 functional safety standards collectively shape MCU qualification timelines and barrier-to-entry economics for non-automotive-grade suppliers. The EPA's vehicle efficiency mandates and NHTSA crash avoidance requirements indirectly accelerate MCU content per vehicle through mandatory electronic stability control and automatic emergency braking. Stakeholders must monitor how software-defined vehicle architectures redistribute processing between centralized compute and edge MCUs.
Market Dynamics
OEM consolidation of electronic architectures into domain controllers and zone ECUs is redistributing MCU procurement power from Tier-2 module suppliers toward direct Tier-1 semiconductor sourcing, compressing traditional distribution hierarchies and lengthening qualification lock-in periods.
Growth Catalysts
- UNECE WP.29 Cybersecurity Mandates:The regulation mandates hardware security modules in vehicle ECUs, forcing automakers toward certified 32-bit MCUs with embedded cryptographic accelerators.
- Powertrain Electrification:Battery management systems and traction inverters require deterministic real-time control loops that legacy 8-bit architectures cannot execute.
- Germany's Automotive Corridor:Stuttgart and Munich concentrate R&D investment for ASIL-D certified silicon, drawing foundry partnerships and qualification laboratories.
Market Restraints
- Wafer Fab Concentration:Advanced automotive MCU fabrication clusters in Taiwan and South Korea create geographic single-point vulnerability for supply continuity.
- ISO 26262 Qualification Burden:ASIL-D certification cycles extend 18-36 months, freezing out fabless entrants lacking capitalized validation infrastructure.
- Silicon Carbide Displacement:Wide-bandgap power electronics in traction inverters reduce MCU pin-count requirements for gate-drive functions.
Strategic Opportunities
- Software-Defined Vehicle Architectures:Centralized compute platforms create demand for edge MCUs with deterministic Ethernet and Time-Sensitive Networking capabilities.
- EU F-Gas Regulation:Thermal management system redesigns for refrigerant compliance open socket opportunities for motor-control MCUs in electric compressors.
- India's Automotive PLI Scheme:Localization mandates for electronic components attract MCU packaging and test investment for domestic OEM supply.
Industry Challenges
- Functional Safety Engineering Talent:ASIL-certified firmware developers and failure modes analysts command premium compensation, constraining program scaling.
- Legacy 8-bit Migration Complexity:Retiring proven 16-bit powertrain controllers requires pin-compatible drop-in replacements to avoid recertification of entire subsystems.
- Supply Chain Reconfiguration Friction:OEM direct-sourcing models disrupt long-standing distributor relationships, creating inventory liability disputes during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Microcontrollers (MCU) Market |
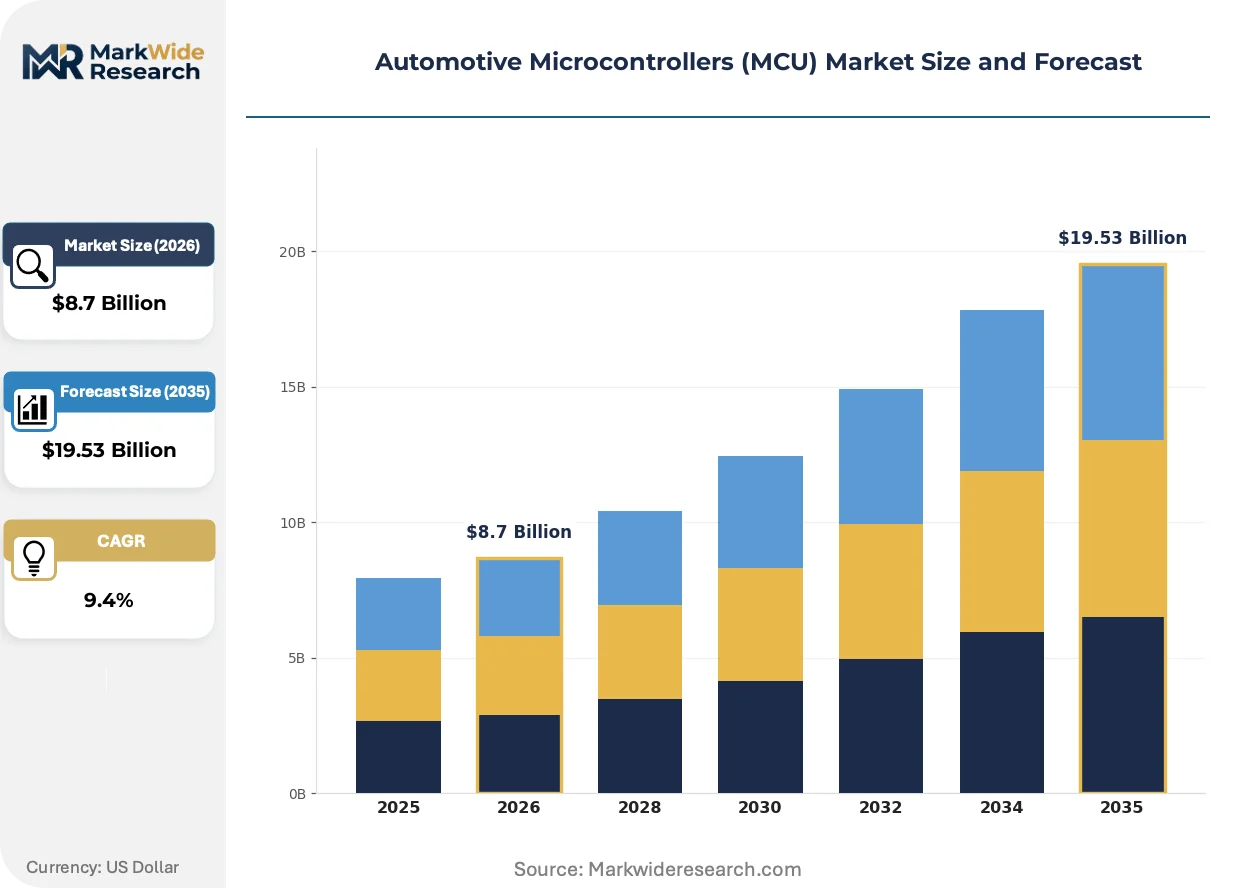
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
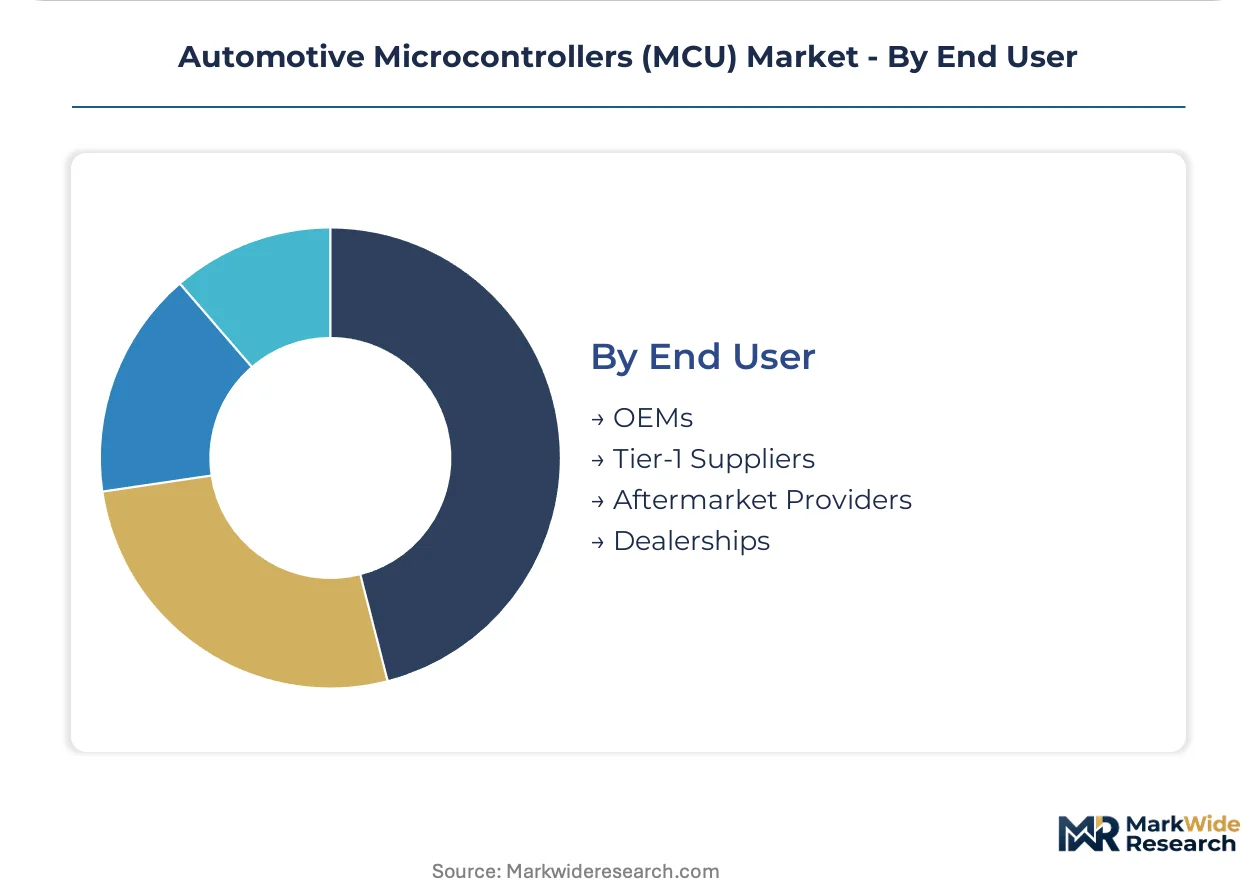
| Segmentation | Product Type: 16-bit MCU, 32-bit MCU, ARM-based MCU, DSP-based MCU Technology: Embedded Control, MEMS, Advanced Driver Assistance Systems, IoT Connectivity Application: Powertrain, Safety Systems, Infotainment, Chassis Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | Microchip Technology Inc., Texas Instruments Incorporated, STMicroelectronics N.V., ROHM Semiconductor, Toshiba Corporation, Infineon Technologies AG, NXP Semiconductors N.V., Analog Devices Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Microcontrollers (MCU) Market Trends and Innovations
Deterministic processing architectures are converging with embedded security and networking capabilities, compressing the traditional separation between real-time control and vehicle-level compute.
Lockstep multicore ARM Cortex-R52 designs are absorbing safety-critical functions previously distributed across redundant discrete controllers. Brake-by-wire and steer-by-wire suppliers in Germany and Japan are adopting these consolidated architectures for ASIL-D redundancy without duplicated silicon. The integration is absorbing margin from discrete safety MCU suppliers while reducing ECU count per vehicle.
EU F-Gas Regulation and accompanying CE marking requirements for refrigerant leak detection are mandating certified sensor interface MCUs in thermal management modules. The policy compresses design cycles for HVAC system suppliers who must integrate hardware security modules alongside analog front-ends. European OEMs are responding by pre-qualifying MCU platforms across multiple refrigerant transition scenarios.
Direct semiconductor procurement by Tier-1 module houses is displacing traditional authorized distributor channels for high-volume safety MCU programs. Continental and Bosch are establishing captive inventory positions with foundry partners, bypassing semiconductor distributors for AURIX and S32 platform devices. The shift concentrates most visibly in Germany's automotive electronics corridor, where qualification proximity to OEM engineering centers accelerates program ramps.
Automotive Microcontrollers (MCU) Market Segmentation

Automotive MCU segmentation reveals how procurement power, certification requirements, and electrification intensity concentrate value across different silicon categories. Understanding these divisions exposes where qualification lock-in and architecture consolidation reshape supplier relationships.
Product Type:
Bit-width selection directly determines functional safety certification eligibility and real-time processing capacity for vehicle subsystems.
- 32-bit MCU:Lockstep multicore architectures execute deterministic control loops for ASIL-D brake-by-wire and traction inverter management. Automakers in Germany's Stuttgart-Munich corridor specify these devices for consolidated domain controllers, compressing ECU counts while meeting UNECE WP.29 cybersecurity mandates through embedded hardware security modules.
- ARM-based MCU:Cortex-R52 derivatives absorb redundant safety functions previously distributed across discrete controllers, enabling steer-by-wire consolidation without duplicated silicon. Japanese and German suppliers are adopting these for ASIL-D redundancy, displacing margin from discrete safety MCU vendors while reducing per-vehicle controller counts.
- 16-bit MCU:Legacy powertrain controllers face pin-compatible replacement pressure to avoid subsystem recertification costs.
- DSP-based MCU:Specialized digital signal processing cores serve motor control and sensor fusion applications requiring floating-point arithmetic.
32-bit MCUs lead on scale; ARM-based variants lead on momentum.
Technology:
Integration depth separates premium socket opportunities from commodity controller replacement cycles.
- Advanced Driver Assistance Systems:Sensor fusion MCUs combine radar, lidar, and camera inputs through deterministic Ethernet backbones, requiring Time-Sensitive Networking capabilities for centralized compute architectures. These devices command extended qualification cycles and capture the highest margin pools due to ISO 26262 certification barriers.
- Embedded Control:Real-time operating system integration enables deterministic response for power conversion and actuator command under extreme thermal and vibration conditions.
- MEMS:Microelectromechanical system interface MCUs process inertial and pressure sensor data for chassis stabilization.
- IoT Connectivity:Cellular and V2X radio integration exposes attack surfaces that UNECE WP.29 regulations address through mandatory cryptographic accelerators.
ADAS technology concentrates the steepest expansion trajectory; Embedded Control maintains the broadest installed base.
Application:
Safety-critical intensity and electrification exposure determine per-vehicle MCU content and supplier switching costs.
- Safety Systems:Brake-by-wire, steer-by-wire, and automatic emergency braking controllers require ASIL-D lockstep cores with hardware redundancy. EPA crash avoidance mandates and NHTSA regulations indirectly accelerate content per vehicle, while 18-36 month qualification cycles freeze supplier relationships across vehicle generations.
- Powertrain:Battery management systems and traction inverters demand deterministic real-time control that legacy 8-bit architectures cannot execute, driving retirement of proven 16-bit designs.
- Chassis Control:Electronic stability control and adaptive suspension systems integrate sensor fusion with actuator response.
- Infotainment:Non-safety-critical processing faces margin compression as centralized compute platforms absorb cockpit functions.
Safety Systems leads on margin capture; Powertrain leads on electrification-driven volume expansion.
End User:
Procurement model transformation redistributes inventory risk and qualification authority across the supply hierarchy.
- Tier-1 Suppliers:Continental and Bosch are establishing captive inventory positions with foundry partners, bypassing semiconductor distributors for AURIX and S32 platform devices. This direct sourcing concentrates in Germany's automotive electronics corridor, where qualification proximity to OEM engineering centers accelerates program ramps.
- OEMs:Domain controller consolidation shifts MCU specification authority toward vehicle-level platform architects.
- Aftermarket Providers:Non-certified replacement controllers face regulatory exclusion from safety-critical applications.
- Dealerships:Service channel access depends on OEM diagnostic tool compatibility and software update authorization.
Tier-1 Suppliers leads on procurement volume; OEMs leads on architectural control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASIL-certified firmware engineers cluster in Germany's Stuttgart-Munich corridor, where OEM engineering centers and foundry partnerships compress qualification timelines. Taiwan and South Korea anchor advanced wafer fabrication for automotive-grade silicon. India's component localization mandates are drawing packaging and test investment.
Germany
Infineon Technologies AG and NXP Semiconductors N.V. anchor powertrain silicon production for brake-by-wire and traction inverter applications. The EU F-Gas Regulation mandates hardware security modules in thermal management ECUs, accelerating certified 32-bit MCU adoption. Stuttgart and Munich concentrate R&D investment and qualification laboratories, with Tier-1 suppliers establishing captive inventory positions directly with foundry partners.
United States
EPA vehicle efficiency mandates and NHTSA crash avoidance requirements indirectly expand MCU content per vehicle through mandatory electronic stability control. FCC Part 15 emissions testing shapes qualification timelines for connectivity-integrated controllers. Texas Instruments Incorporated leverages isolated gate driver expertise into high-voltage traction inverter segments, with development concentrated in Dallas and Silicon Valley engineering centers.
China
Domestic OEM platform consolidation drives demand for lockstep multicore architectures in domain controllers. MIIT cybersecurity standards and GB certification requirements parallel UNECE WP.29 mandates, forcing hardware security module integration. The Yangtze River Delta and Pearl River Delta cluster packaging and test capacity, though advanced node fabrication remains import-dependent.
Japan
Renesas Electronics Corporation and Toshiba Corporation anchor legacy 16-bit replacement programs with pin-compatible 32-bit successors. METI industrial policy supports automotive semiconductor supply chain resilience initiatives. The Nagoya-Tokyo corridor concentrates steer-by-wire and chassis control MCU development, with suppliers adopting ARM Cortex-R52 derivatives for ASIL-D redundancy consolidation.
India
The Automotive PLI Scheme localization mandates for electronic components attract MCU packaging and test investment to serve domestic OEM supply chains. BIS certification requirements create parallel qualification pathways for non-automotive-grade suppliers seeking entry. Tamil Nadu and Maharashtra cluster EMS operations, with Tier-1 module houses establishing direct semiconductor procurement relationships bypassing traditional distribution.
Automotive Microcontrollers (MCU) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across automotive MCU supply tiers. The vendor base concentrates around three strategic archetypes: integrated device manufacturers with captive fabrication, fabless designers relying on foundry partnerships, and diversified electronics conglomerates leveraging vertical integration. M&A activity targets safety-critical software capabilities and hardware security module IP. Strategic partnerships between Tier-1 module houses and foundry partners are displacing traditional distributor channels for high-volume programs.
Within the integrated fabrication tier, Infineon Technologies AG exemplifies European captive silicon production for AURIX multicore devices. NXP Semiconductors N.V. occupies a comparable position through S32 platform anchoring across brake-by-wire and steering systems. Texas Instruments Incorporated represents American competition in isolated gate driver integration extending into high-voltage traction controls. These three companies illustrate how geographic proximity to OEM engineering centers accelerates qualification lock-in across vehicle generations.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| ROHM Semiconductor |
| Toshiba Corporation |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Analog Devices Inc. |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
Migration from 8-bit to 32-bit lockstep architectures simultaneously inflates silicon die costs and compresses supplier margins through ASIL-D certification overhead, while concentrating procurement power with Tier-1 houses that negotiate direct foundry contracts.
Pricing Analysis
Bundled certification-and-software packages command premium positioning against unbundled silicon-only transactions. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and non-safety economy levels reflects ISO 26262 qualification investment recovery. Pricing pressure stems from silicon carbide gate-driver integration reducing MCU pin-count requirements in traction inverters. Tier-2 module suppliers exhibit highest price sensitivity due to margin compression from direct Tier-1 foundry bypass.
Supply Chain Analysis
ASIL-certified firmware engineering talent scarcity in Taiwan and South Korea constrains advanced node ramp velocity for automotive-grade silicon. Wafer fabrication draws from TSMC and Samsung foundry partnerships, while back-end test and packaging rests on Malaysian and Vietnamese EMS capacity. Single-source vulnerability concentrates in Taiwan strait logistics corridors. Distribution runs through diminishing authorized channels as Continental and Bosch establish captive inventory positions directly with foundry partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in safety-certified 32-bit sockets where ASIL-D qualification barriers protect pricing power against commoditization pressure from centralized compute displacement.
For Market Incumbents: Deepen captive foundry relationships in Germany's Stuttgart-Munich corridor to compress qualification timelines against emerging ARM-based competitors. Expand hardware security module IP portfolios to capture EU F-Gas Regulation thermal management redesign cycles. Lock in steer-by-wire consolidation programs before Japanese suppliers complete Cortex-R52 derivative adoption. For New Entrants and Emerging Players: India's Automotive PLI Scheme localization mandates open a window for packaging and test investment serving domestic OEM supply chains. Target BIS certification pathways for non-automotive-grade suppliers seeking tier-2 module house entry. Pursue pin-compatible 16-bit replacement sockets to avoid subsystem recertification friction. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless designers lacking capitalized validation infrastructure but holding hardware security module IP. Long-term viability favors acquisition targets with ASIL-certified firmware engineering teams and established foundry partnerships. Watch for Tier-1 direct procurement announcements as inflection indicators for distributor channel displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Domain controller consolidation reduces ECU counts while concentrating MCU specification authority with OEM architects. |
| Battery Supply Agreement | Long-term offtake contracts with cell manufacturers secure deterministic control loop silicon allocation for BMS programs. |
| Software-Defined Vehicle Investment | Edge MCU demand with Time-Sensitive Networking capabilities expands as centralized compute redistributes processing. |
| Geographic Manufacturing Footprint | India's Automotive PLI Scheme attracts packaging and test investment bypassing traditional distribution hierarchies. |
| Charging Infrastructure Partnership | High-voltage traction inverter control integration extends MCU content into power electronics thermal management. |
Research Methodology
Multiple input streams — primary interviews with Tier-1 supplier procurement, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and UNECE WP.29 regulatory documentation — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated ASIL certification cycle timelines and foundry capacity allocation disclosures from semiconductor capital expenditure reporting.
Revisions become necessary when foundry capacity reallocation, cybersecurity regulatory expansion, or silicon carbide displacement velocity materially shifts from baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Self-Learning Neuromorphic Chip Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
China Data Center Processor Market