
 China Semiconductor Diode Market | 2026-2036
China Semiconductor Diode Market Size, Share, and Industry Trends Forecast 2026-2036
China Semiconductor Diode Market Insights
New energy vehicle manufacturers are rotating procurement priority from standard silicon diodes toward high-efficiency Schottky and rectifier variants capable of handling elevated switching frequencies. Yangjie Technology leverages captive wafer capacity to anchor pricing power in discrete power devices. Silan Microelectronics sustains R&D intensity across analog-intensive process nodes. Infineon Technologies AG competes through module-level integration that bundles diodes with gate drivers and protection circuitry.
A semiconductor diode is a two-terminal electronic component formed at the junction of p-type and n-type semiconductor materials, exhibiting asymmetric current-voltage characteristics with forward threshold voltages typically ranging from 0.3V for Schottky types to 0.7V for standard silicon junctions. These devices perform rectification, voltage clamping, and signal demodulation functions essential to power electronics and communication systems. Silicon diodes retain volume leadership across industrial equipment and consumer electronics applications where cost sensitivity outweighs efficiency premiums. Schottky diodes capture expanding margin pools in automotive DC-DC converters and telecommunications base stations demanding minimal forward voltage drop. Rectifier diodes dominate power conversion segments tied to electric vehicle onboard chargers and grid-tied inverter architectures.
MIIT's semiconductor self-sufficiency directives, GB standards for automotive electronic components, and the National Integrated Circuit Industry Investment Fund collectively reshape qualification requirements and local content thresholds for diode suppliers operating in China. NMPA-equivalent automotive component certification and SAMR antitrust scrutiny on foreign pricing practices further constrain market access for non-domestic manufacturers. Stakeholders must monitor foundry capacity allocation between discrete power devices and advanced logic nodes as this trade-off determines diode lead times and contract pricing trajectories.
Market Dynamics
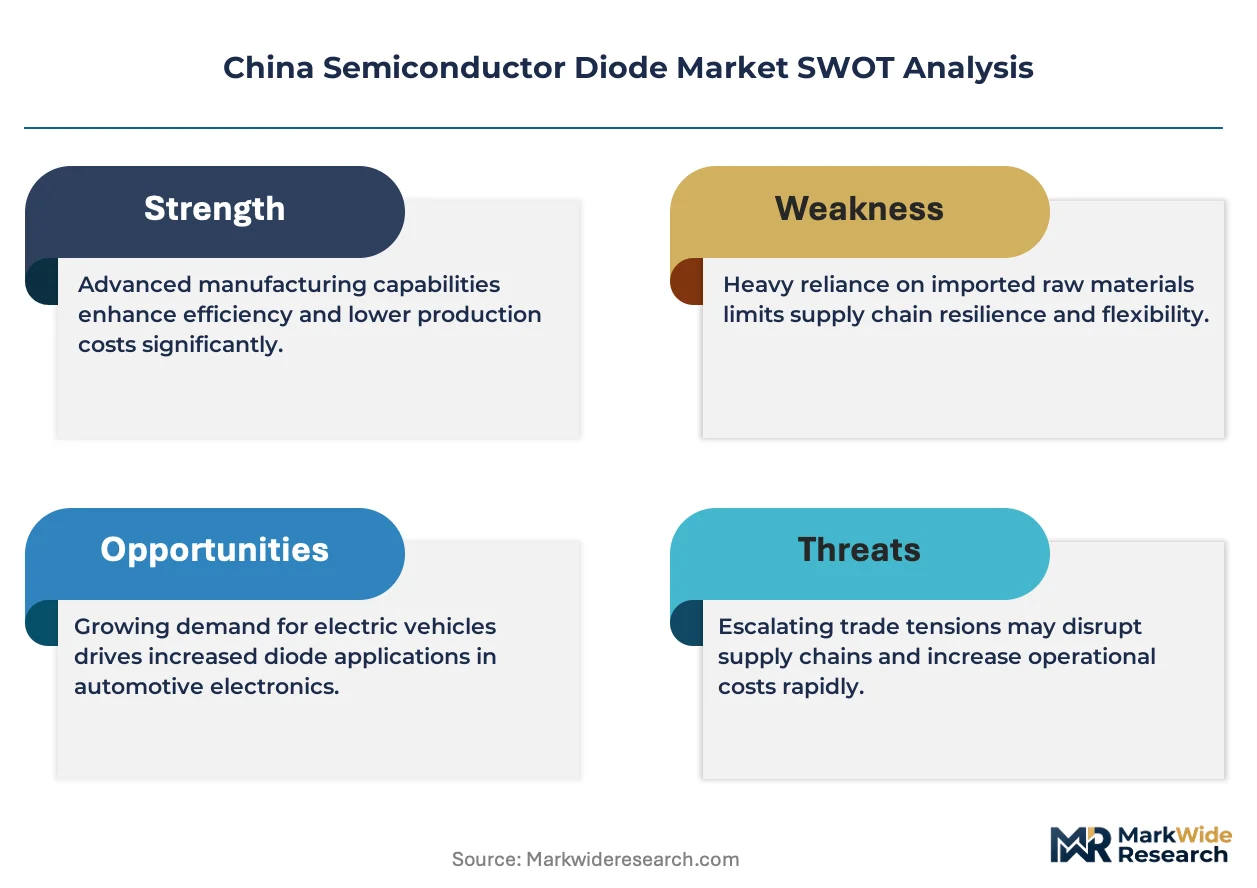
MIIT's domestic substitution mandates are rerouting procurement flows toward captive wafer foundries in the Yangtze River Delta, compressing lead times for silicon carbide-compatible rectifier diodes while elevating qualification barriers for foreign suppliers.
Growth Catalysts
- New Energy Vehicle Electrification:Onboard charger architectures demand Schottky diodes capable of elevated switching frequencies. Automotive OEMs are expanding silicon carbide procurement to meet efficiency targets under China's dual carbon goals.
- GB Standards Compliance:MIIT-mandated automotive electronic component certifications are redirecting supply chain sourcing toward domestic wafer foundries that have pre-qualified under national integrated circuit investment frameworks.
- Yangtze River Delta Cluster Concentration:Shanghai-Jiangsu-Zhejiang manufacturing density enables just-in-time delivery to power electronics assemblers. Foundry proximity is compressing logistics costs for high-volume rectifier diode contracts.
Market Restraints
- Epitaxial Wafer Supply Concentration:Silicon carbide substrate production concentrates among a limited set of global crystal growers. Bottlenecks in 6-inch and 8-inch wafer supply are extending diode lead times beyond 26 weeks.
- SAMR Pricing Scrutiny:State Administration for Market Regulation antitrust investigations into foreign semiconductor pricing practices are constraining margin flexibility for non-domestic manufacturers operating in China.
- Gallium Nitride Substitution Threat:GaN power devices are penetrating sub-650V applications previously served by silicon Schottky diodes. Consumer charger and telecom rectifier segments are exhibiting accelerated technology crossover.
Strategic Opportunities
- Western China Capacity Expansion:Chengdu-Chongqing semiconductor manufacturing corridors offer tax incentives and subsidized utilities under western development policies. Greenfield foundry investments can secure preferential wafer allocation.
- Module-Level Integration:Bundling rectifier diodes with gate drivers and protection circuitry addresses space-constrained electric vehicle powertrain designs. Tier-1 automotive suppliers are soliciting subsystem proposals.
- Energy Storage Inverter Demand:Grid-scale battery installations require high-current rectification. Utility procurement under National Energy Administration storage mandates is creating incremental volume pools for 100A+ diode variants.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Silicon carbide device physics expertise remains scarce. Foundries are competing for analog-intensive process engineers capable of managing defect densities in wide-bandgap epitaxy.
- NMPA-Equivalent Automotive Certification Timelines:Component qualification under harmonized GB/T standards requires 18-24 month validation cycles. Design-in windows for new vehicle platforms are compressing against regulatory submission deadlines.
- Legacy Silicon Line Depreciation:Mature-node diode manufacturers face stranded asset risk as automotive procurement pivots toward wide-bandgap alternatives. Conversion economics for 200mm silicon lines remain unfavorable.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Semiconductor Diode Market |
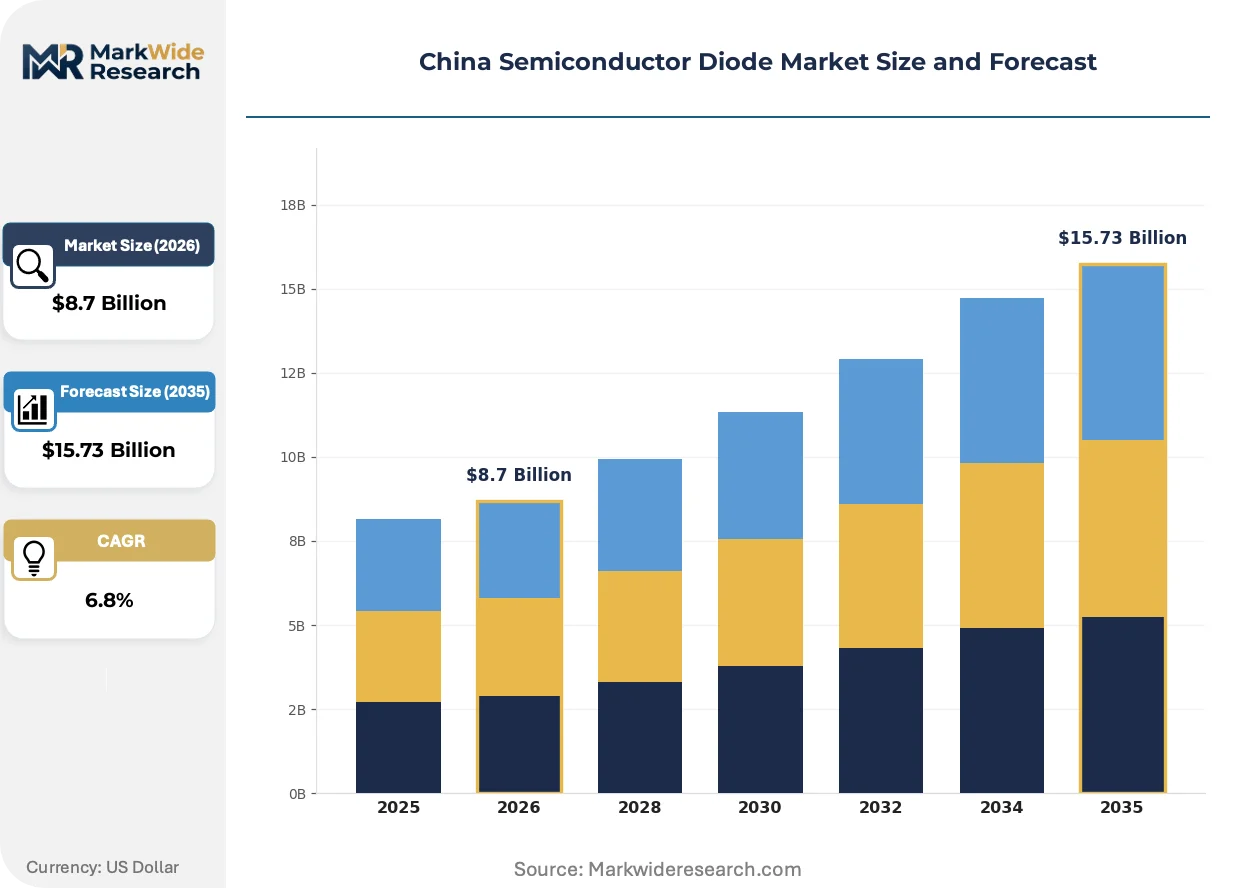
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Diodes, Schottky Diodes, Zener Diodes, Rectifier Diodes Application: Power Conversion, Signal Processing, Voltage Regulation, Switching End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: Thin-Film, High-Frequency, Digital, Analog |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors NV, Vishay Intertechnology Inc., Diodes Incorporated, ROHM Co. Ltd, Yangjie Technology, China Resources Microelectronics, Silan Microelectronics, Sanan Optoelectronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Semiconductor Diode Market Trends and Innovations
Silicon carbide Schottky barrier diodes are restructuring competitive positioning in power conversion applications, with device architecture choices determining foundry allocation priority and contract pricing trajectories across the forecast window.
Silicon carbide Schottky diodes deliver reverse recovery charge elimination critical for high-frequency DC-DC conversion. New energy vehicle manufacturers are adopting these devices for onboard chargers and traction inverter auxiliary supplies. Silicon carbide is supplanting silicon ultrafast recovery diodes in 650V-1200V automotive applications, compressing addressable market scope for legacy junction technologies.
MIIT's semiconductor self-sufficiency directives are tightening local content thresholds for critical electronic components. GB standards for automotive-grade discrete devices now mandate domestic wafer sourcing percentages for state-supported procurement. Foreign diode suppliers are establishing joint venture packaging facilities in Jiangsu to satisfy SAMR scrutiny on import dependency.
Automotive tier-1 suppliers are consolidating diode procurement through direct foundry relationships, bypassing traditional distribution channels. BYD and NIO have established captive semiconductor sourcing offices in Wuxi and Hefei. This concentration is most visible in the Yangtze River Delta, where power module assemblers are negotiating multi-year wafer supply agreements with Silan Microelectronics and Yangjie Technology.
China Semiconductor Diode Market Segmentation
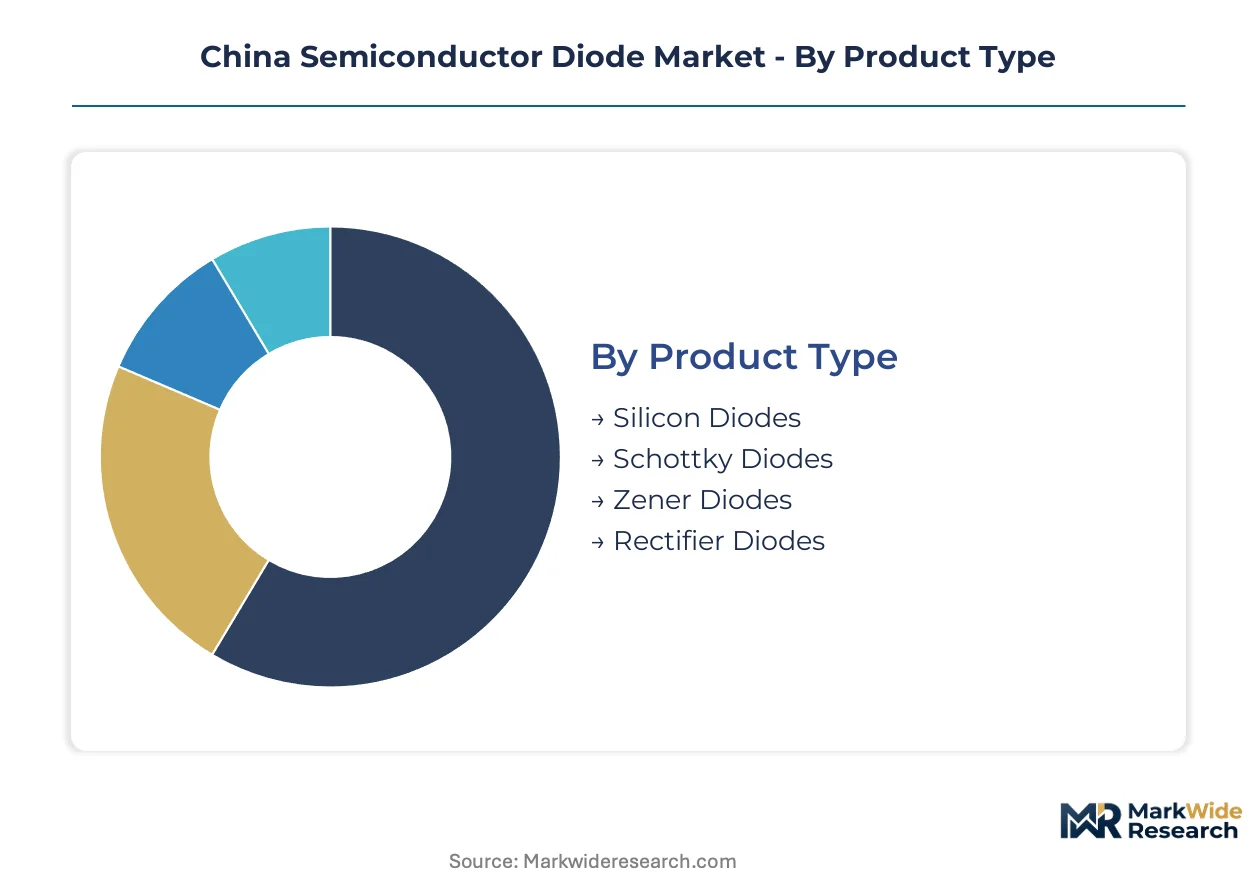
Diode procurement patterns across China diverge sharply between state-mandated domestic sourcing corridors and export-oriented manufacturing zones. Segment-level strategies must account for MIIT qualification requirements that privilege certain technologies and end-uses over others.
Product Type:
Domestic consumption concentrates in silicon and rectifier variants serving automotive and industrial bases in the Yangtze River Delta, while Schottky and Zener exports flow primarily through Shenzhen and Dongguan assembly channels.
- Silicon Diodes:Standard p-n junction devices with 0.7V forward threshold dominate mature industrial equipment and consumer electronics where cost sensitivity outweighs efficiency premiums. Demand clusters in Jiangsu province foundries serving legacy manufacturing equipment OEMs.
- Schottky Diodes:Metal-semiconductor junction architecture delivers 0.3V forward drop essential for high-frequency DC-DC conversion in new energy vehicle onboard chargers. Procurement from Yangjie Technology and Silan Microelectronics is accelerating under dual carbon efficiency mandates.
- Zener Diodes:Reverse breakdown voltage regulation devices anchor reference circuits in telecommunications infrastructure. Deployment concentrates in base station power supplies across Guangdong and Zhejiang provinces.
- Rectifier Diodes:High-current unidirectional conduction elements grid-tied solar inverters and EV charging modules. Silicon carbide-compatible variants are capturing priority wafer allocation from domestic foundries.
Silicon diodes command the established base. The steepest expansion runs through Schottky variants.
Application:
Cost tier stratification separates premium high-frequency designs from economy-grade power conversion, with margin compression most severe in voltage regulation segments.
- Power Conversion:AC-DC and DC-DC transformation circuits in EV onboard chargers and solar inverters demand 650V-1200V Schottky and rectifier devices. MIIT procurement directives favor domestic wafer sourcing for grid-tied installations.
- Signal Processing:Demodulation and detection circuits in telecommunications equipment utilize small-signal silicon and Schottky variants. 5G base station rollouts in Shanghai and Shenzhen are sustaining volume.
- Voltage Regulation:Zener and avalanche diode clamping circuits protect sensitive analog front-ends. Consumer electronics pricing pressure is compressing margins for standard-grade devices.
- Switching:Fast recovery diodes in motor drives and power supplies require minimal reverse recovery time. Industrial automation retrofits in Shandong and Hebei provinces are sustaining demand.
Power conversion anchors revenue concentration. Signal processing is climbing the fastest.
End User:
Automotive and industrial procurement operates through direct foundry relationships, while consumer electronics and telecommunications flow through distribution channels with higher price transparency.
- Consumer Electronics:Smartphone chargers, laptop adapters, and white goods utilize cost-optimized silicon rectifiers. GaN substitution is eroding Schottky share in sub-100W applications.
- Automotive:NEV manufacturers BYD and NIO have established captive sourcing offices in Wuxi and Hefei for silicon carbide-compatible rectifiers. GB standards compliance is mandatory for state-supported procurement.
- Telecommunications:Base station power supplies and data center rectifiers demand high-reliability Schottky and Zener devices. Huawei and ZTE procurement concentrates in Yangtze River Delta packaging facilities.
- Industrial Equipment:Motor drives, welding equipment, and UPS systems utilize high-current rectifier modules. State-owned enterprise procurement favors domestic content thresholds.
Industrial equipment commands the established base. Automotive is gaining share fastest.
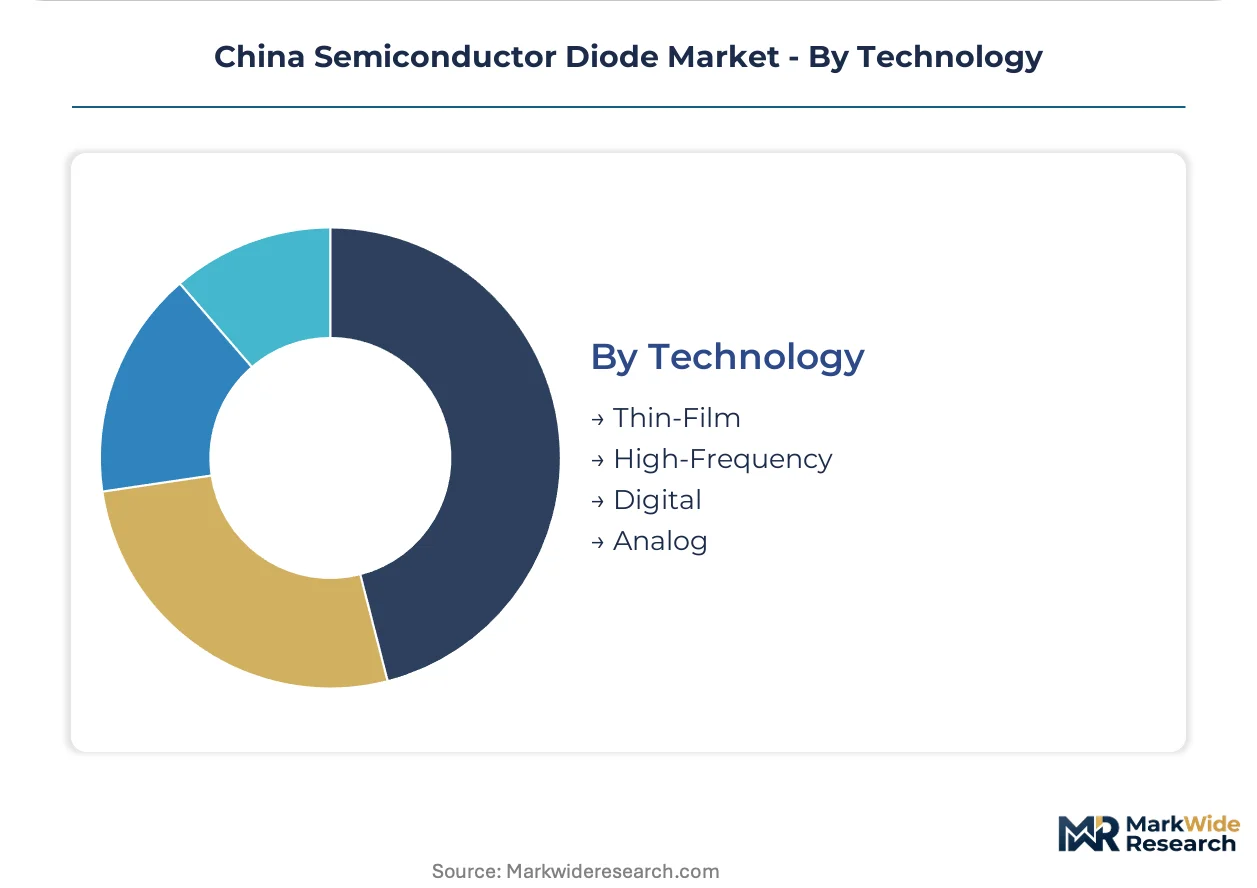
Technology:
Volume concentration sits with analog and high-frequency processes, while thin-film and digital variants occupy niche positioning with higher qualification barriers.
- Thin-Film:Sputtered metal layers on insulating substrates enable miniaturization for aerospace and medical applications. Limited domestic foundry capacity constrains supply.
- High-Frequency:Optimized junction geometries minimize switching losses in EV DC-DC converters and telecom rectifiers. Silan Microelectronics and Yangjie Technology compete for automotive design-ins.
- Digital:Integrated diode-transistor logic elements serve legacy industrial control systems. Replacement demand is plateauing as systems migrate to CMOS.
- Analog:Discrete junction devices for power management and signal conditioning dominate volume production. Mature-node foundries in Jiangsu and Zhejiang anchor supply.
Analog processes command the established base. High-frequency architectures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure and Shanghai Pudong International Airport cargo terminals underwrite China's semiconductor diode distribution dominance. High-speed rail corridors connect Jiangsu and Zhejiang foundry clusters to downstream power electronics assemblers. This logistics backbone enables just-in-time delivery contracts for automotive and industrial procurement.
Yangtze River Delta
Shanghai-Jiangsu-Zhejiang manufacturing density concentrates silicon carbide-compatible rectifier diode production. MIIT's domestic substitution mandates redirect wafer sourcing toward Silan Microelectronics and Yangjie Technology captive foundries. Wuxi packaging facilities process high-volume contracts for BYD and NIO captive sourcing offices.
Pearl River Delta
Shenzhen and Dongguan electronics assemblers export Schottky and Zener variants through Yantian Port. Consumer electronics pricing pressure compresses margins for standard-grade silicon diodes. Huawei and ZTE procurement concentrates in local packaging facilities serving telecommunications infrastructure.
Beijing-Tianjin-Hebei
State-owned enterprise procurement for industrial equipment favors domestic content thresholds. GB standards compliance mandates pre-qualification under national integrated circuit investment frameworks. Tianjin port facilities handle import substrate for wide-bandgap epitaxy processing.
Sichuan-Chongqing
Western development policies offer tax incentives for greenfield foundry investments. Chengdu semiconductor manufacturing corridors secure preferential wafer allocation under subsidized utility programs. Chongqing automotive OEMs are establishing direct foundry relationships for power module assembly.
Shandong Peninsula
Industrial automation retrofits in Qingdao and Yantai sustain demand for fast recovery diodes in motor drives. Legacy silicon line manufacturers face stranded asset risk as procurement pivots toward wide-bandgap alternatives. Provincial SOE procurement channels favor established domestic suppliers.
China Semiconductor Diode Market Competitive Landscape
Concentration sits with domestic captive foundries and foreign module-level integrators competing across divergent qualification pathways. Yangjie Technology and Silan Microelectronics anchor pricing power through vertical wafer capacity. Foreign suppliers navigate SAMR antitrust scrutiny through joint venture packaging arrangements. Strategic moves center on multi-year wafer supply agreements and subsystem bundling for electric vehicle powertrains.
Within the domestic foundry tier, Yangjie Technology and Silan Microelectronics exemplify analog-intensive process specialization. Among foreign module integrators, Infineon Technologies AG occupies a position bundling diodes with gate drivers and protection circuitry. NXP Semiconductors NV and Vishay Intertechnology Inc. represent diversified discrete component portfolios navigating GB standards compliance requirements.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Vishay Intertechnology Inc. |
| Diodes Incorporated |
| ROHM Co. Ltd |
| Yangjie Technology |
| China Resources Microelectronics |
| Silan Microelectronics |
| Sanan Optoelectronics |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for silicon carbide epitaxial wafers are compressing pricing power among module integrators while amplifying margin capture for domestic crystal growers with captive substrate supply. This inventory stress concentrates negotiation leverage in the Yangtze River Delta foundry cluster, where multi-year wafer supply agreements now command premium contract terms.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels dominates diode procurement. Price differentiation rests on MIIT qualification status and volume scale, with automotive OEMs absorbing premiums for GB-compliant domestic sourcing while consumer electronics buyers drive cost compression in standard silicon variants. Pricing pressure stems from SAMR antitrust scrutiny constraining foreign supplier margins. Consumer electronics procurement exhibits highest price sensitivity; automotive tier-1s demonstrate lowest sensitivity due to design-in switching costs.
Supply Chain Analysis
Silicon carbide substrate supply concentrates among crystal growers in the United States, Japan, and Germany, creating chokepoint vulnerability for Chinese foundry expansion. Raw material dependencies span high-purity silicon feedstock, refractory metals for Schottky barriers, and specialized packaging epoxies. Single-source vulnerability in 6-inch and 8-inch wide-bandgap epitaxy threatens production continuity. Distribution runs through direct foundry relationships with NEV manufacturers, bypassing traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's domestic substitution mandates are accelerating a technology transition that will reshape competitive positioning across the forecast window. Wide-bandgap device physics expertise scarcity compounds the disruption intensity.
For Market Incumbents: Shield automotive design-ins through backward integration into silicon carbide epitaxy capacity, securing wafer allocation priority as substrate bottlenecks intensify. Deepen captive foundry relationships with BYD and NIO sourcing offices to lock out module-level competitors. Prioritize GB/T certification maintenance as NMPA-equivalent timelines compress against platform deadlines.
For New Entrants and Emerging Players: GB standards fast-track partnerships with Silan Microelectronics or Yangjie Technology offer the most penetrable entry path for automotive qualification. Target western China greenfield corridors in Chengdu-Chongqing for subsidized capacity buildout. Lead with module-level integration proposals bundling rectifiers with gate drivers to bypass discrete component margin compression.
For Investors and Strategic Acquirers: Long-term, this sits as a compound semiconductor infrastructure play because domestic substrate self-sufficiency will determine foundry economics across the next technology cycle. Target acquisition archetypes include analog-intensive process engineering teams with silicon carbide defect density expertise. Watch for MIIT wafer allocation policy shifts as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Epitaxy Capacity Expansion | Captive substrate supply secures wafer allocation priority under MIIT domestic sourcing mandates. |
| GB/T Automotive Certification Investment | NMPA-equivalent qualification opens state-supported NEV procurement channels to foreign joint ventures. |
| Module-Level Integration Development | Subsystem bundling addresses space-constrained EV powertrain designs sought by tier-1 suppliers. |
| Western China Foundry Greenfield Investment | Chengdu-Chongqing tax incentives reduce utility costs for wide-bandgap device manufacturing. |
| Direct OEM Sourcing Office Establishment | Wuxi and Hefei proximity enables just-in-time delivery contracts with BYD and NIO procurement teams. |
Research Methodology
Initial hypotheses were tested against primary input from power module procurement managers, foundry process engineers, automotive platform architects, and SAMR regulatory consultants and refined through secondary validation. Semiconductor trade customs data, MIIT industry bulletins, GB standards documentation, and foundry capacity utilization disclosures anchored quantitative baselines. Bottom-up wafer allocation modeling and top-down automotive production forecasts were triangulated to reconcile volume estimates.
Variance decomposition across product type, application end-use, technology node, and regional manufacturing cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Foundry capacity allocation trade-offs between discrete power devices and advanced logic nodes, alongside silicon carbide substrate supply elasticity assumptions, informed trajectory projections across the modeling period.
Decision-makers should treat outputs as directional under sustained MIIT domestic substitution enforcement and stable wide-bandgap epitaxy supply expansion; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as gallium nitride substitution rates and western China foundry commissioning timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Europe Microcontroller (MCU) Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
China Power Transistor Market