
 Wire Rope Lubricants Market | 2026-2036
Wire Rope Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Rope Lubricants Market Outlook
A shift from single-source mineral oil procurement toward multi-source synthetic and biodegradable supply is repositioning how fleet operators and maintenance services manage inventory risk. ExxonMobil leverages its integrated base oil infrastructure to secure cost advantages across marine and mining channels. Klüber Lubrication differentiates through application-specific formulations for extreme-load industrial environments. Shell Global anchors its position with broad geographic coverage and technical service networks tied to contractor segments.
Wire rope lubricants are specialized protective coatings—typically comprising mineral oils, synthetic esters, or biodegradable bases combined with corrosion inhibitors and tackifiers—applied to cable strands to reduce friction, prevent moisture ingress, and extend service life in tension-bearing systems. Cable grease formulations dominate volume due to their adhesion properties in high-load construction and mining winch systems, while biodegradable options represent the fastest-expanding margin pool as environmental compliance tightens across European and Asia-Pacific ports. Penetrating oil holds mature positioning in routine maintenance protocols, whereas spray lubricants gain traction among contractors requiring rapid field application without disassembly.
REACH in Europe, OSHA in the United States, and China's MEE environmental standards collectively restrict mineral oil discharges and mandate biodegradability testing for marine and industrial applications, forcing reformulation investments and reshaping supplier qualification criteria. ISO 4344 and national wire rope maintenance codes further specify lubricant performance thresholds for elevator, crane, and hoist systems, creating compliance barriers for non-certified entrants. Stakeholders must monitor evolving chemical registration requirements and synthetic base oil supply availability to align procurement with tightening performance and environmental specifications.
Market Dynamics
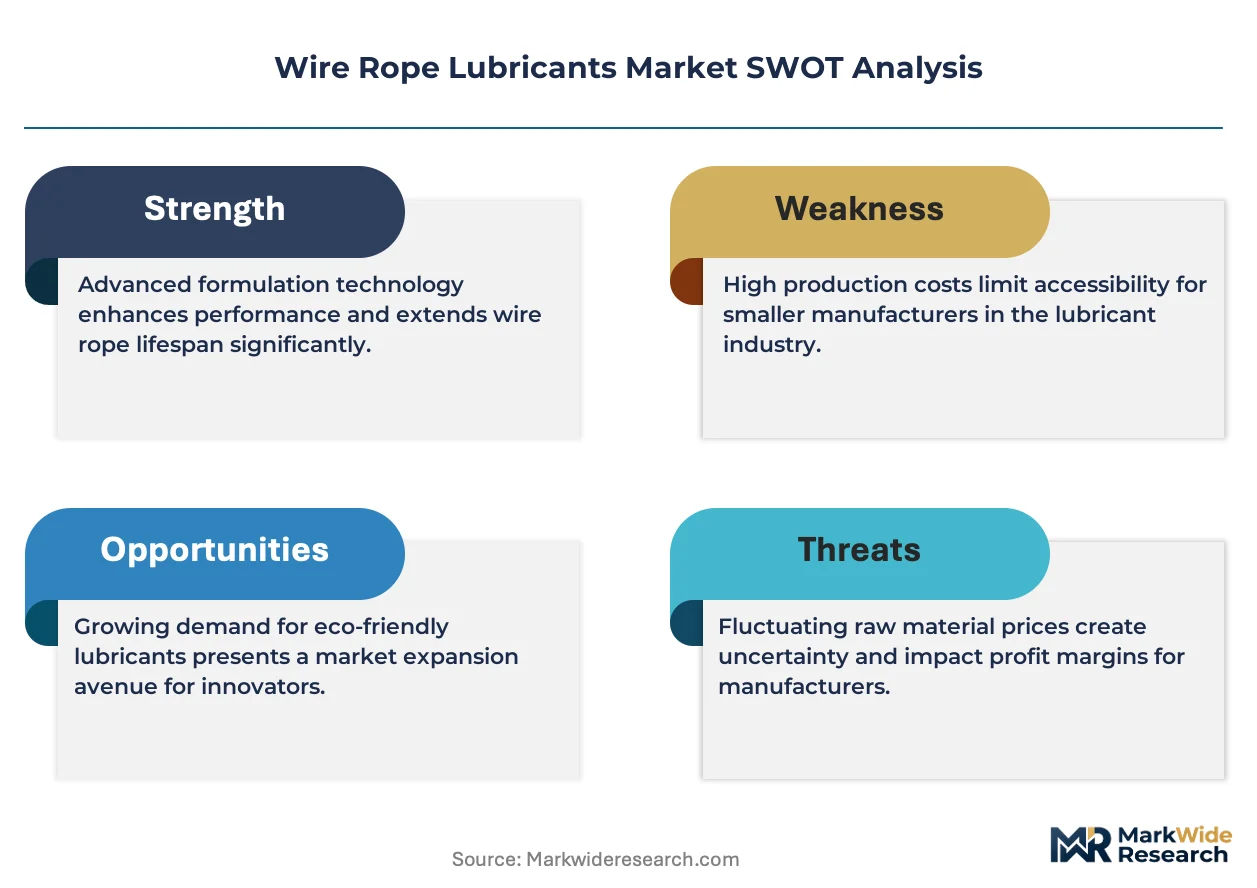
REACH compliance deadlines and China's MEE environmental standards are forcing simultaneous reformulation across mineral oil and synthetic ester supply chains, compressing supplier margins while opening certification premiums for early movers.
Growth Catalysts
- Port electrification mandates:European dock authorities under EU Green Deal timelines require biodegradable lubricants for shore-power crane systems, redirecting fleet procurement toward ester-based formulations.
- MEE enforcement waves:China's environmental ministry intensifies discharge inspections at Yangtze River port clusters, accelerating biodegradable adoption among state-owned terminal operators.
- Deep-shaft mining depths:Chilean and Australian copper-gold operations below 1,500 meters deploy heavy-duty cable grease with corrosion inhibitors to combat humidity and load stress in hoisting systems.
Market Restraints
- Base oil supply concentration:Synthetic ester feedstocks cluster with specialty chemical producers in Germany and Japan, exposing formulators to input volatility and allocation limits.
- REACH registration costs:ECHA substance evaluation fees and testing protocols for new biodegradable actives impose six-figure barriers for mid-scale entrants seeking EU market access.
- Mineral oil price anchoring:Construction contractors in price-sensitive markets resist ester premiums despite performance advantages, slowing segment conversion.
Strategic Opportunities
- Indian port modernization:Sagarmala infrastructure investments at Visakhapatnam and Mundra create demand for marine-grade biodegradable lubricants as environmental clearances tighten.
- Elevator service unbundling:Independent maintenance providers in aging urban building stocks seek spray-format rapid-application products for high-rise hoist systems without OEM service contracts.
- ISO 4344 certification premiums:Elevator and crane safety code compliance creates price-tier separation between certified and non-certified lubricant suppliers in contractor procurement.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in biodegradable tackifier compatibility and corrosion inhibitor stability concentrates with aging technical staff at established suppliers.
- Multi-standard certification timelines:Simultaneous pursuit of REACH registration, ISO 4344 performance validation, and national wire rope codes extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Rope Lubricants Market |
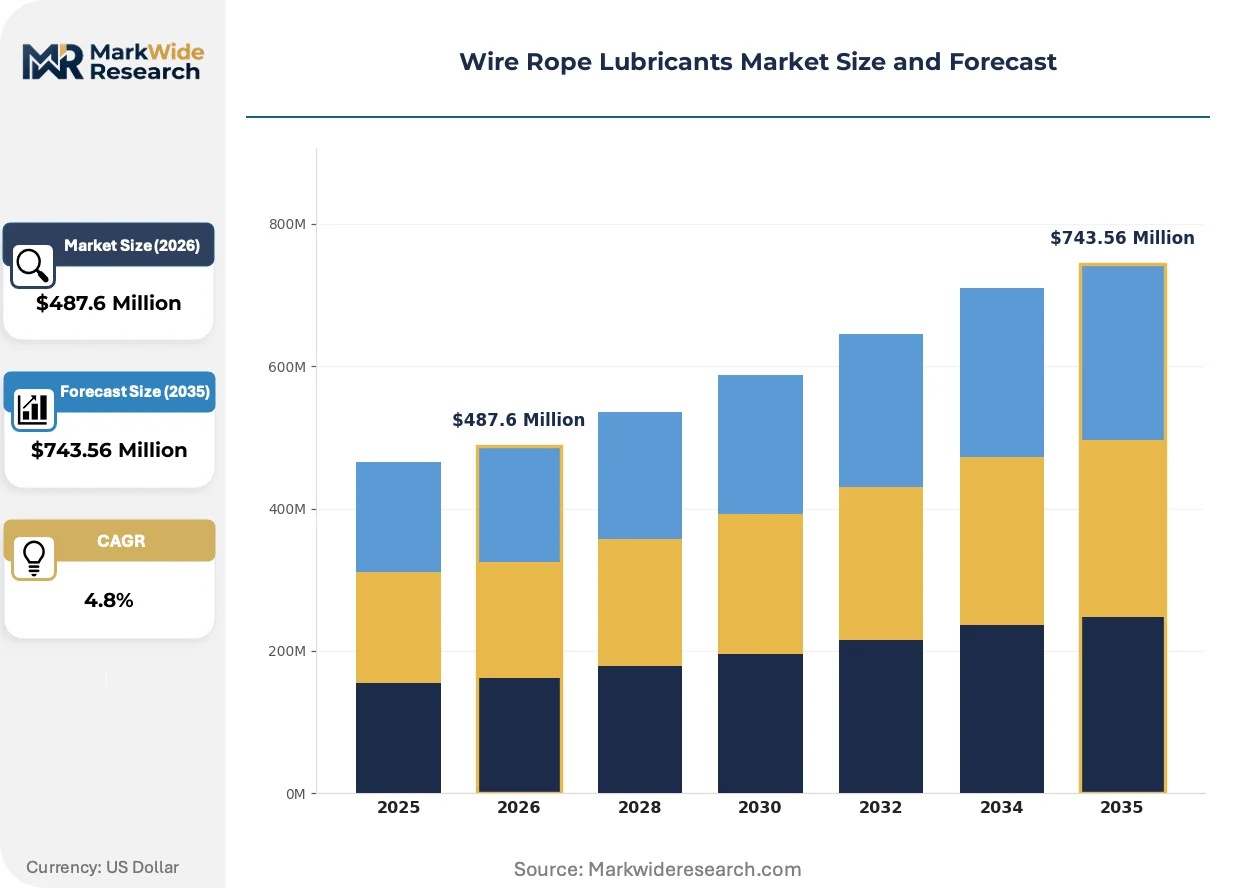
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Grease, Penetrating Oil, Spray Lubricants, Solid Lubricants Application: Construction, Marine, Mining, Industrial End User: Manufacturers, Contractors, Fleet Operators, Maintenance Services Formulation: Biodegradable, Synthetic, Mineral Oil, Clay-Based |
| Companies Covered | ExxonMobil Corporation, Shell Global, Chevron Corporation, Klüber Lubrication, Castrol Limited, Fuchs Petrolub SE, Total S.A., Lubrication Engineers, Inc., Bel-Ray Company, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Rope Lubricants Market Strategic Shifts
Formulation chemistry and application methods are diverging sharply as environmental compliance tightens in parallel with performance demands from deeper mining and taller lifting operations.
Synthetic ester base stocks with tailored viscosity indexes and oxidation stability are overtaking mineral oil dominance in high-load industrial winch systems. Mining contractors in Chile's Escondida and Australia's Olympic Dam operations specify these formulations for shaft depths exceeding 1,500 meters. The shift is compressing commodity lubricant margins while expanding certified-premium pricing tiers.
REACH authorization requirements for persistent, bioaccumulative, and toxic substances are eliminating certain corrosion inhibitors from marine cable grease formulations. ECHA sunset date enforcement forces reformulation investments across European port maintenance contracts. Suppliers with pre-registered biodegradable alternatives capture contractor qualification advantages as 2026 deadlines approach.
Maintenance crews at Chinese rail depots and Australian iron ore ports now specify spray-application lubricants for rapid field treatment of running ropes without disassembly. Distributor technical service networks displace direct bulk purchasing for these specialized formats. The pattern concentrates procurement influence with regional stocking partners who inventory application equipment alongside lubricant SKUs.
Wire Rope Lubricants Market Segmentation
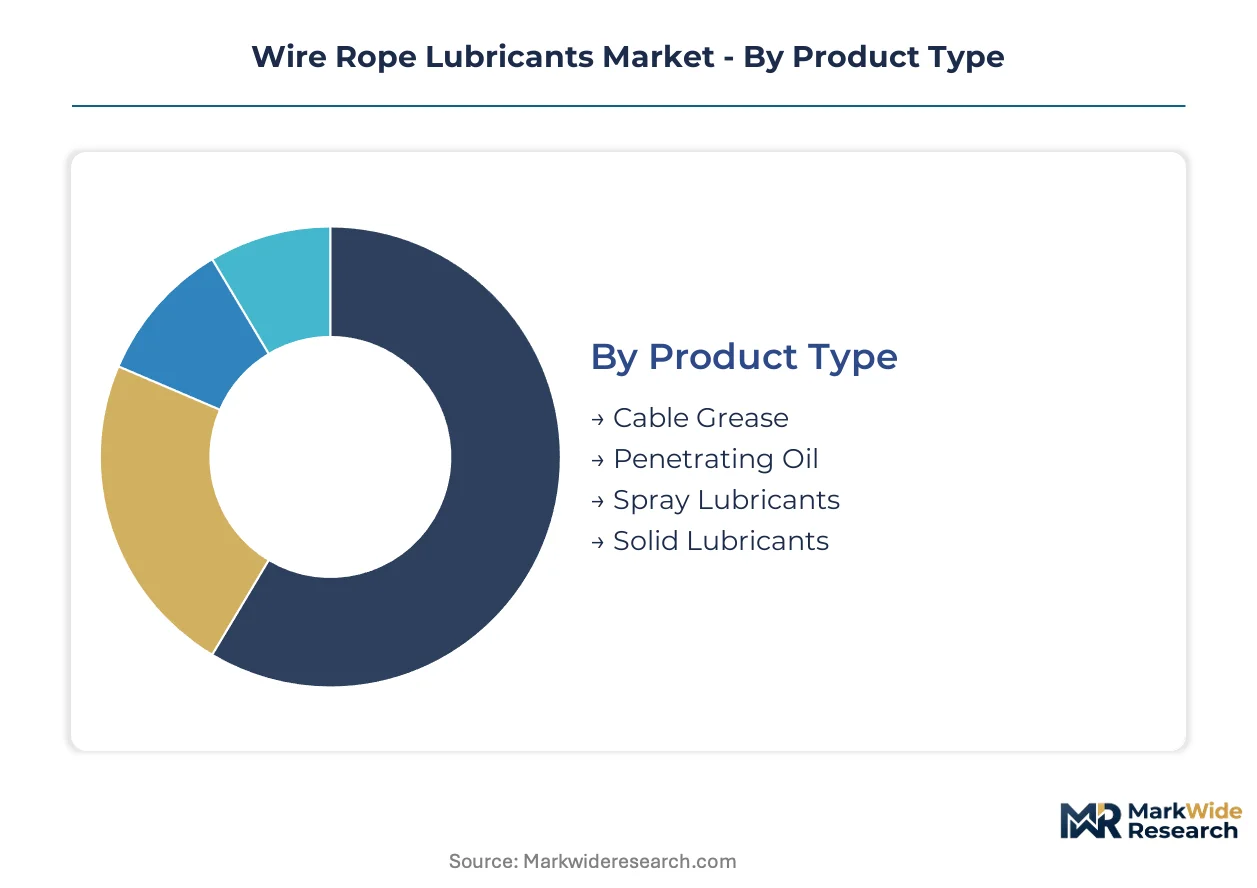
Wire rope lubricant procurement varies sharply by operational intensity and regulatory exposure. Segment selection determines formulation investment, certification burden, and margin structure for suppliers.
Product Type:
Capital intensity peaks with cable grease manufacturing, where heavy-duty tackifier systems and corrosion inhibitor packages require specialized compounding equipment.
- Cable Grease:Thick, adhesive formulations combining mineral or synthetic base stocks with metallic soap thickeners and extreme-pressure additives. Mining contractors in Chile's Escondida complex and Australia's Olympic Dam specify these for shaft depths exceeding 1,500 meters where humidity and load stress concentrate.
- Penetrating Oil:Low-viscosity formulations designed to wick between wire strands for internal lubrication and corrosion protection. Fleet operators in China's state-backed rail depots deploy these in routine maintenance protocols for running ropes.
- Spray Lubricants:Aerosol or pump-dispensed formats enabling rapid field application without disassembly. Contractors favor these for high-rise elevator maintenance where OEM service contracts have lapsed.
- Solid Lubricants:Dry-film coatings and lubricant-impregnated polymers for extreme-temperature or contamination-sensitive environments. Specialized applications in steel mill continuous casting lines.
Cable grease absorbs the bulk of installed capacity; spray lubricants are expanding most quickly.
Application:
Volume distribution tracks infrastructure capital cycles and commodity extraction intensity across end-use sectors.
- Mining:Underground and open-pit hoisting systems demand heavy-duty cable grease with load-bearing capacity and moisture resistance. Australian copper-gold operations and Chilean deep-shaft mines anchor procurement volume for this segment.
- Marine:Port crane systems, offshore mooring lines, and shipboard winches require biodegradable formulations meeting EU Green Deal timelines and China's MEE discharge standards. European dock authorities under shore-power mandates redirect procurement toward ester-based options.
- Construction:Tower cranes, piling rigs, and material hoists consume commodity-grade mineral oil lubricants where price sensitivity dominates contractor selection.
- Industrial:Elevator hoist systems, overhead cranes, and manufacturing line equipment fall under ISO 4344 safety code compliance, creating certified-premium pricing tiers.
Mining commands the largest share of formulation R&D investment; marine applications face the steepest regulatory-driven reformulation pressure.
End User:
Procurement authority concentrates with entities managing large installed rope fleets under performance-based maintenance contracts.
- Fleet Operators:State-owned port terminals, mining houses, and rail infrastructure managers purchase through annual supply agreements with technical service requirements. China's Yangtze River port clusters and Australian iron ore export terminals exemplify this pattern.
- Maintenance Services:Independent elevator and crane service providers seek rapid-application formats and distributor technical support. Aging urban building stocks in Europe and North America sustain this channel.
- Contractors:Construction and mining subcontractors purchase spot volumes with price-driven selection, slowing conversion to premium formulations.
- Manufacturers:OEM wire rope producers apply initial lubrication during production, representing a stable but lower-margin supply relationship.
Fleet operators direct the majority of specification authority; maintenance services are gaining procurement influence fastest.
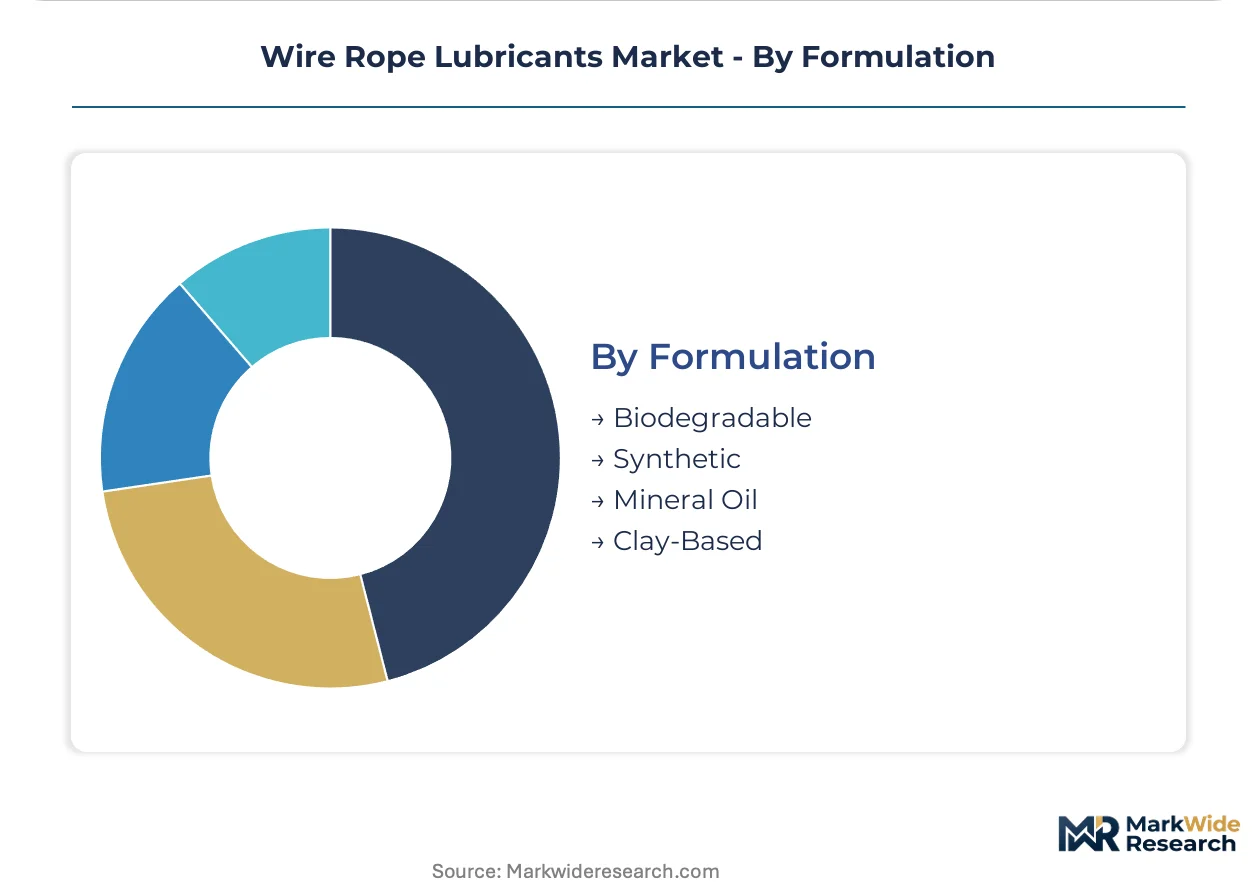
Formulation:
Base stock selection determines regulatory compliance trajectory and margin structure across supplier portfolios.
- Biodegradable:Synthetic ester and vegetable oil base stocks with tailored oxidation stability and marine toxicity profiles. REACH authorization deadlines and China's MEE enforcement waves are eliminating competing mineral oil options in European and Asia-Pacific ports.
- Synthetic:Polyalphaolefin and synthetic ester formulations with extended service intervals and extreme-temperature performance. Mining contractors specify these for deep-shaft hoisting systems where equipment access is limited.
- Mineral Oil:Conventional petroleum-derived base stocks with established supply chains but tightening discharge restrictions. Construction contractors in price-sensitive markets continue procurement despite environmental compliance risks.
- Clay-Based:Non-soap thickeners for high-temperature applications where metallic soap degradation occurs. Niche positioning in steel production and foundry operations.
Mineral oil retains volume leadership; biodegradable formulations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wire rope lubricants clusters in mining-intensive economies and port modernization corridors where fleet operators manage large installed cable bases under tightening environmental protocols.
China
Yangtze River port terminals and state-backed rail depots drive volume procurement for running rope maintenance. MEE discharge inspections at Shanghai and Ningbo-Zhoushan port clusters accelerate biodegradable formulation adoption among state-owned terminal operators. Infrastructure maintenance fleets in the Beijing-Tianjin-Hebei corridor sustain purchasing for elevator and crane systems.
Australia
Deep-shaft copper-gold mining at Olympic Dam and iron ore export terminals at Port Hedland anchor heavy-duty cable grease consumption. The country's national environmental regulator enforces marine toxicity standards for port lubricant discharge. Mining contractors in Western Australia's Pilbara region specify synthetic ester formulations for hoisting systems below 1,500 meters.
Chile
The Escondida copper complex and state-owned Codelco operations deploy corrosion-inhibited cable grease for extreme-load hoisting in Atacama Desert and Andean shaft conditions. Chile's environmental ministry applies progressively stricter discharge limits to mining concessions. Port maintenance at Antofagasta and Valparaíso redirects procurement toward biodegradable options under Latin American green port initiatives.
Germany
Industrial elevator maintenance in aging urban building stocks and port crane modernization at Hamburg and Bremerhaven sustain formulation R&D investment. ECHA REACH authorization deadlines for persistent substances force reformulation across marine cable grease portfolios. Specialty chemical producers in the Rhine-Ruhr industrial cluster concentrate synthetic ester feedstock supply.
United States
Construction crane fleets in Texas and Florida energy corridors consume mineral oil lubricants where price sensitivity dominates contractor selection. OSHA workplace safety standards and EPA discharge regulations create compliance layering for port and marine applications. Independent elevator service providers in New York and Chicago metro areas seek rapid-application spray formats for high-rise maintenance.
Wire Rope Lubricants Market Competitive Environment
Portfolio diversification dominates the current landscape as established suppliers reposition around biodegradable certification premiums and synthetic base stock integration. The market structure consolidates around integrated petroleum majors, specialty chemical formulators, and regional blending operations. Three archetypes define competitive positioning: upstream-integrated base oil producers, application-specific formulation specialists, and distributor-aligned regional blenders. M&A activity targets biodegradable technology assets while capacity expansion concentrates in Asia-Pacific port corridors.
Among integrated petroleum majors, ExxonMobil Corporation and Shell Global occupy positions anchored by captive base oil infrastructure and broad geographic coverage networks. Klüber Lubrication represents the formulation specialist archetype with concentrated expertise in extreme-load industrial environments. These three companies exemplify how supplier qualification advantages flow from pre-registered REACH alternatives and ISO 4344 certification portfolios as regulatory deadlines compress competitor entry timelines.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell Global |
| Chevron Corporation |
| Klüber Lubrication |
| Castrol Limited |
| Fuchs Petrolub SE |
| Total S.A. |
| Lubrication Engineers, Inc. |
| Bel-Ray Company, LLC |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal shore-power mandates for port crane systems gate both qualified biodegradable supply and premium-tier pricing access, compressing mineral oil margins while elevating certified ester formulations. Fleet operators in Hamburg and Rotterdam now face procurement bifurcation: qualified suppliers capture contract premiums while non-compliant blenders exit marine segments entirely.
Pricing Analysis
Volume concentrates in mineral oil cable grease serving price-sensitive construction contractors, while margin pools shift toward synthetic ester and biodegradable formulations carrying REACH registration premiums. Three-tier pricing structure separates ISO 4344-certified elevator lubricants from standard industrial grades and commodity construction products. Pricing pressure stems from synthetic base oil allocation limits at German and Japanese specialty chemical producers. Construction contractors in Texas and Florida energy corridors exhibit highest price sensitivity, whereas mining houses in Chile's Escondida complex accept premium positioning for deep-shaft performance guarantees.
Supply Chain Analysis
Single-source vulnerability sits with synthetic ester feedstock concentration in Germany and Japan, exposing formulators to input volatility and quarterly allocation constraints. Base oil production draws from integrated petroleum infrastructure in the United States and Gulf states, while corrosion inhibitor packages source from Chinese and Indian specialty chemical manufacturers. Tariff exposure runs through REACH-registered additive imports into European compounding facilities. Distribution runs through regional stocking partners who inventory application equipment alongside lubricant SKUs, displacing direct bulk purchasing for spray-format products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic base oil capacity constraints at Rhine-Ruhr specialty chemical producers prop pricing premiums, creating supply-constrained conditions that favor incumbents with pre-registered formulations and locked-in feedstock agreements.
For Market Incumbents: Deploy backward integration into captive ester feedstock production to secure margin stability against allocation volatility from German and Japanese suppliers. Lock in multi-year supply agreements with Yangtze River port terminals before MEE enforcement waves accelerate biodegradable procurement. Counter formulation chemist scarcity by acquiring regional blending operations with retained technical staff in Australia and Chile mining corridors.
For New Entrants and Emerging Players: Rapid-cure spray application technology offers the most penetrable wedge for contractor segments seeking field-application efficiency without OEM service dependencies. Target independent elevator maintenance providers in aging European and North American urban building stocks where ISO 4344 certification barriers remain surmountable. Pursue distributor-aligned go-to-market partnerships rather than direct fleet operator engagement to bypass incumbent technical service networks.
For Investors and Strategic Acquirers: ECHA sunset date enforcement for persistent corrosion inhibitors is the leading indicator that biodegradable formulation assets will command scarcity premiums. Five-to-ten year viability favors suppliers with integrated REACH registration, ISO 4344 certification, and established port authority relationships. Watch for MEE inspection intensity at Ningbo-Zhoushan as the signal for accelerated Asia-Pacific procurement conversion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Feedstock | Captive synthetic base oil supply secures margin stability against German and Japanese allocation limits. |
| REACH Pre-Registration Acceleration | Early biodegradable formulation registration captures contractor qualification advantages before sunset deadlines. |
| Regional Blending Capacity Expansion | Asia-Pacific port corridor presence reduces logistics costs for Yangtze River terminal operators. |
| ISO 4344 Certification Investment | Elevator safety code compliance creates price-tier separation in high-rise maintenance procurement. |
| Distributor Technical Service Partnerships | Application equipment bundling displaces direct bulk purchasing for spray-format contractor segments. |
Study Parameters
Independent corroboration across procurement directors at Australian mining houses, technical service managers at European port authorities, and formulation chemists at specialty chemical producers underwrites the qualitative findings. Primary fieldwork engaged maintenance supervisors at Chinese rail depots, aftermarket directors at elevator service providers, and blending plant managers in the Rhine-Ruhr cluster. Secondary validation drew from ECHA substance registration databases, ISO 4344 certification registries, and customs trade data for synthetic ester imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for mining and infrastructure capital cycles.
Comparable-period anchoring to historical procurement patterns at Escondida and Olympic Dam mining operations established baseline demand elasticity for heavy-duty cable grease. The analytical framework modeled formulation type, application intensity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level demand build-ups incorporating MEE enforcement trajectory and EU Green Deal implementation pace. Industry-specific inputs included shaft depth expansion rates at Chilean copper-gold operations and Yangtze River port modernization investment flows.
Several conditions sit outside the modeled scope, including unannounced reformulation breakthroughs altering biodegradable performance thresholds and abrupt shifts in mineral oil price volatility. Forecasts reflect documented assumptions about REACH authorization timelines and MEE inspection intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Industrial Gear Oil Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Biolubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
France Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
Israel Lubricants Market