
 Polyetherketone Market | 2026-2036
Polyetherketone Market Size, Share, and Industry Trends Forecast 2026-2036
Polyetherketone Market Analytics
Material certification and long-term supply agreements is expanding as the dominant commercial layer in polyetherketone commerce. Victrex anchors the high-performance medical and aerospace segments through its concentrated PEEK production in the United Kingdom. Celanese Corporation leverages its global acetyl and engineered materials infrastructure to compete across automotive and electronics applications. SABIC differentiates through its specialty chemicals portfolio and positions its PEKK offerings for next-generation aerostructures.
Polyetherketone denotes a family of semi-crystalline aromatic thermoplastics containing alternating ether and ketone linkages in the polymer backbone, with PEEK exhibiting a glass transition temperature near 143°C and melting point around 343°C. These materials serve primarily as metal replacements in load-bearing components requiring chemical resistance, dimensional stability, and flame retardancy. Aerospace applications command premium positioning due to stringent qualification protocols and long certification cycles, while medical-grade PEEK sustains above-average margins through biocompatibility requirements for spinal implants and dental devices. Electronics demand for PEEK films is accelerating as miniaturization trends intensify thermal management needs in connectors and insulation layers.
FDA 21 CFR 177.2415 governs food-contact PEEK in the United States, while EMA and EU MDR frameworks regulate medical device polymers across European markets. China's NMPA and GB standards increasingly shape import requirements for implantable grades sold into domestic hospitals. REACH authorization processes and evolving per- and polyfluoroalkyl substance restrictions in Europe are forcing reformulation strategies among compounders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
Material qualification protocols and thermoplastic composite manufacturing scale-up are restructuring competitive advantage in polyetherketone commerce, concentrating procurement power among aerospace OEMs with multi-year certification pipelines.
Growth Catalysts
- Aerospace thermoplastic adoption:Boeing and Airbus qualification of PEKK-based fuselage structures creates pull-through demand for certified resin grades. Tier-1 suppliers in Germany and Japan are expanding autoclave capacity to match.
- EU MDR implantable device rules:Stricter biocompatibility documentation requirements favor established medical-grade PEEK producers with existing master files. Spinal implant manufacturers in Switzerland and Ireland are consolidating supplier bases.
- Fluoropolymer substitution:Per- and polyfluoroalkyl substance restrictions under REACH are redirecting semiconductor fabrication equipment demand toward PEEK for wafer handling components.
Market Restraints
- Monomer supply concentration:Difluorobenzophenone and hydroquinone precursors depend on Chinese and Indian specialty chemical producers, exposing compounders to freight cost volatility and customs processing delays.
- Energy-intensive polymerization:Nucleophilic aromatic substitution requires sustained high-temperature processing, making European producers vulnerable to natural gas price fluctuations and carbon border adjustment mechanisms.
- Polyaryletherketone intergrade competition:PEK and PEEKK variants with higher ketone ratios offer superior thermal performance for select aerospace applications, fragmenting specification standards.
Strategic Opportunities
- India medical device manufacturing:CDSCO harmonization with EU MDR and production-linked incentive schemes for orthopedic implants create first-mover advantages for PEEK compounders establishing local compounding operations.
- Continuous fiber 3D printing:Laser-assisted tape placement and automated fiber placement systems are converging with PEKK prepreg formats to enable non-autoclave wing rib production.
- Japan hydrogen infrastructure:METI roadmaps for fuel cell vehicle scaling specify PEEK seals and bipolar plates, opening demand channels outside traditional aerospace and medical verticals.
Industry Challenges
- Polymer physicist talent scarcity:Expertise in semi-crystalline morphology control and melt rheology for high-performance thermoplastics concentrates in aging workforces at Victrex and Solvay legacy sites.
- FAA/EASA concurrent certification:Dual jurisdiction qualification for flight-critical PEKK components requires parallel test matrices, extending program timelines and straining engineering resources.
- Recyclate requalification:Aerospace OEMs resist accepting mechanically recycled PEEK in load-bearing structures due to molecular weight degradation concerns, limiting circular economy progress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyetherketone Market |
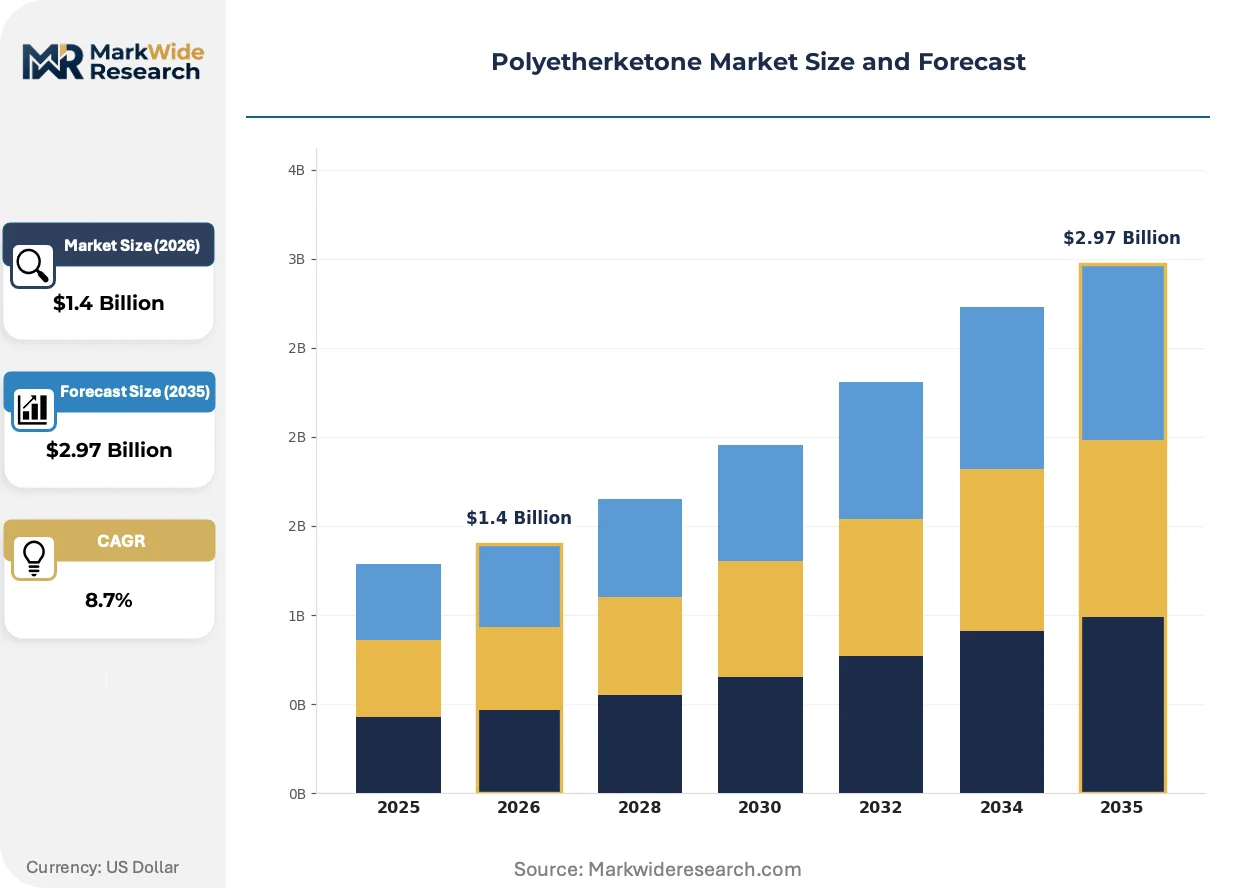
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEEK, PEKK, PEEKK, PEEK-HT Application: Aerospace, Automotive, Medical, Electronics End User: Manufacturers, OEMs, Research Institutions, Service Providers Form: Sheets, Rods, Powder, Films |
| Companies Covered | Pan Jin Zhongrun High Performance Polymer Co., Ltd., Celanese Corporation, Victrex, Ensinger GmbH, SABIC, Evonik Industries AG, DuPont, Jilin Joinature Polymer Co., Ltd., Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyetherketone Market Evolving Landscape
Processing technology maturation and regulatory chemistry restrictions are converging to reposition polyetherketone grades across metal replacement and incumbent polymer substitution strategies.
PEKK copolymer formulations with tailored crystallization kinetics are expanding into out-of-autoclave aerospace manufacturing. Tier-1 aerostructures suppliers in France and Italy are adopting these grades for wing access panel production. The shift is compressing tooling capital requirements and enabling smaller production runs for next-generation narrowbody programs.
REACH authorization processes for diaryl ether intermediates are forcing reformulation investments among European compounders. ECHA's 2024 updated substance evaluation work program targets specific chlorinated precursors used in legacy PEEK synthesis. German and Belgian resin producers are accelerating bio-based diphenyl ether pilot programs to secure supply continuity.
Long-term resin supply agreements are displacing spot market purchasing in medical device procurement. Orthopedic OEMs in Warsaw and Dublin are locking five-year PEEK pellet contracts with volume guarantees. The practice concentrates supplier relationships and reduces qualification overhead for spinal cage and dental abutment manufacturers.
Polyetherketone Market Segmentation
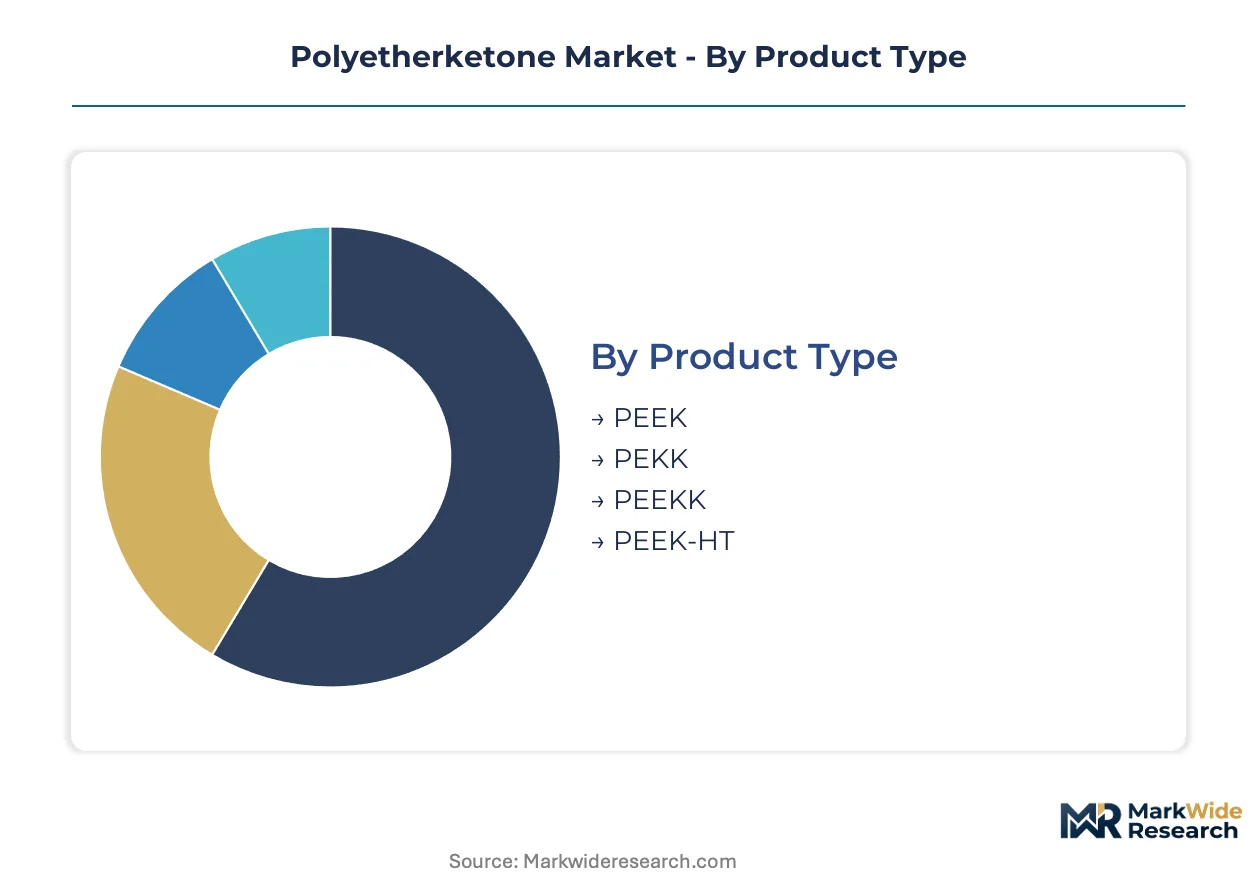
Polyetherketone specifications diverge sharply across end-use requirements, with aerospace qualification protocols and medical biocompatibility standards creating rigid segment boundaries that resist cross-grade substitution. Manufacturers configure melt viscosity, crystallization kinetics, and filler loadings to match specific processing windows and performance thresholds.
Product Type:
Upgrade cycles in aerospace thermoplastic composites are accelerating demand migration toward higher-temperature grades with tailored crystallization behavior.
- PEEK:The reference polyetheretherketone grade exhibits glass transition near 143°C and melting point around 343°C, serving as the default specification for spinal implants and semiconductor wafer handling components. German automotive belt manufacturers and Swiss orthopedic device producers anchor procurement volumes for unfilled and carbon-fiber-reinforced variants.
- PEKK:Copolymer formulations with adjustable ketone-to-ether ratios enable slower crystallization kinetics critical for out-of-autoclave aerospace manufacturing. French and Italian Tier-1 aerostructures suppliers are qualifying these grades for wing rib and access panel production to reduce tooling capital requirements.
- PEEKK:Higher ketone content delivers elevated thermal performance for select engine-adjacent aerospace applications, though narrower processing windows limit adoption outside specialized defense programs.
- PEEK-HT:Modified crystallization profiles target continuous-use temperatures above standard PEEK limits, finding traction in downhole oilfield equipment and advanced motor insulation systems.
Volume placements concentrate in PEEK; the faster expansion belongs to PEKK.
Application:
Cost tier differentiation separates qualification-intensive aerospace and medical segments from price-sensitive automotive and electronics volumes.
- Aerospace:Thermoplastic composite primary structures command premium resin pricing due to FAA and EASA concurrent certification requirements. Boeing and Airbus qualification programs for fuselage and wing components are pulling through demand for certified PEKK prepreg formats.
- Medical:Implantable-grade PEEK sustains above-average margins through FDA 21 CFR 177.2415 and EU MDR biocompatibility documentation requirements. Spinal cage and dental abutment manufacturers in Switzerland and Ireland are consolidating supplier bases to reduce qualification overhead.
- Automotive:Metal replacement in transmission components and thermal management modules drives volume demand, though specification tolerance is wider than aerospace or medical tiers.
- Electronics:Miniaturization trends in connectors and insulation films are intensifying demand for thin-gauge PEEK with precise thickness control.
Revenue concentration sits with aerospace; medical delivers the steepest margin expansion trajectory.
End User:
Customer type determines procurement modality, with OEMs and research institutions driving specification development while manufacturers and service providers execute volume production.
- Manufacturers:Compounders and injection molders process virgin and recycled resin into semifinished shapes and finished components for downstream industrial supply chains.
- OEMs:Boeing, Airbus, Stryker, and Zimmer Biomet anchor demand through multi-year resin supply agreements with volume guarantees and qualification continuity clauses.
- Research Institutions:Universities and national laboratories in Germany, Japan, and the United States advance continuous fiber 3D printing and laser-assisted tape placement process development.
- Service Providers:Machining shops and sterilization facilities add value through precision finishing and regulatory-compliant packaging for medical device supply chains.
Contract structures favor OEMs; research institutions are gaining influence fastest in process innovation.
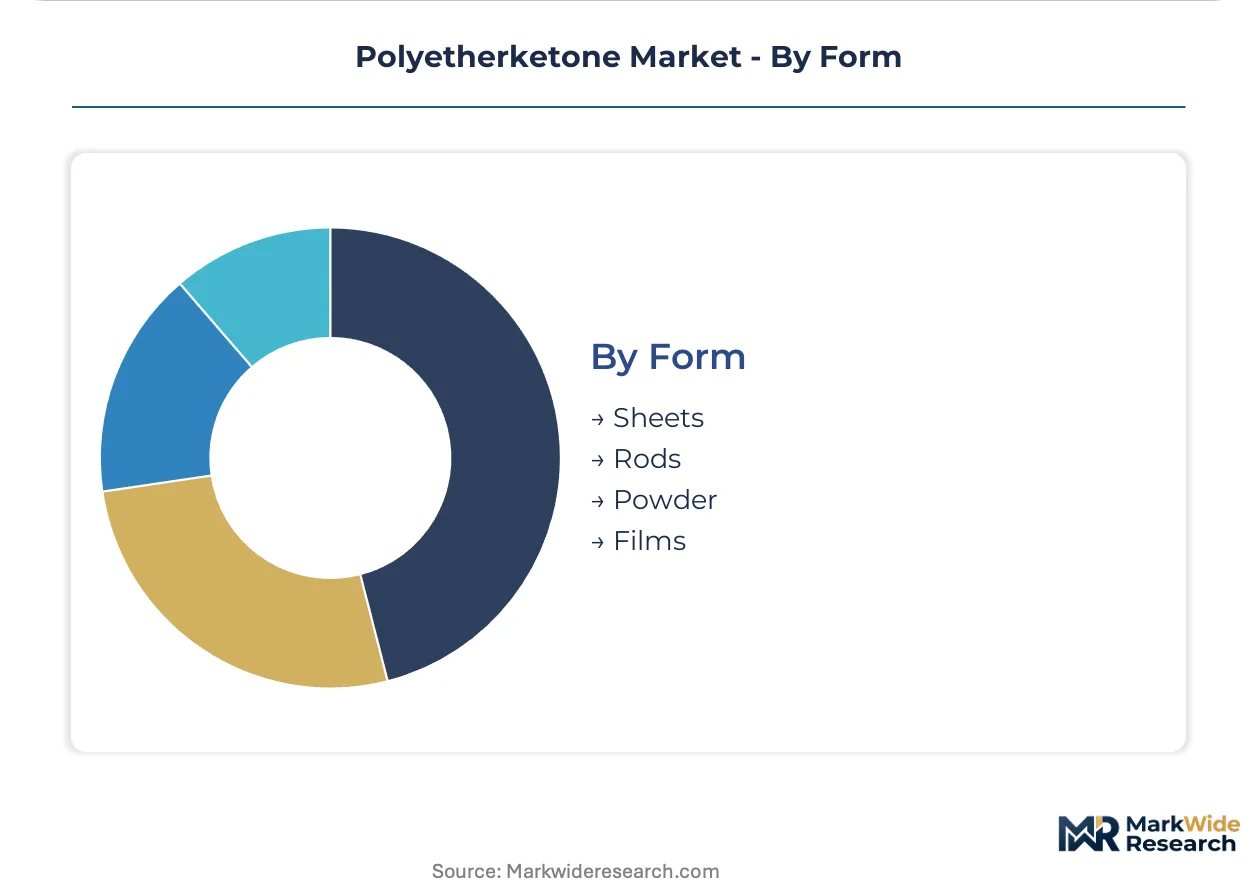
Form:
Supply concentration in extruded and compression-molded formats reflects capital intensity barriers that powder and film production have not yet overcome.
- Sheets:Compression-molded plate stock serves aerospace tooling, chemical processing equipment, and semiconductor fabrication fixtures requiring dimensional stability across thermal cycles.
- Rods:Extruded and compression-molded bar stock feeds precision machining operations for bearings, seals, and structural connectors in automotive and industrial applications.
- Powder:Fine particle grades enable compression molding, coating, and additive manufacturing feedstock, though handling requirements limit adoption outside specialized processors.
- Films:Thin-gauge extruded and cast formats target wire insulation, capacitor dielectrics, and flexible circuit substrates where dielectric strength and thermal resistance converge.
Sheet and rod formats dominate current placements; films are climbing fastest as electronics miniaturization intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive belt around Stuttgart and Munich anchors European polyetherketone demand, with the Yangtze River Delta manufacturing corridor in China and the US aerospace clusters in Washington and California completing the triad of dominant consumption centers.
United States
Boeing's thermoplastic composite qualification programs in Everett and Charleston pull through certified PEKK resin volumes for next-generation narrowbody structures. FAA concurrent certification requirements with EASA extend program timelines and concentrate supplier relationships among established compounders. The Pacific Northwest aerospace cluster and Southern California defense corridor host Tier-1 autoclave operations scaling PEKK prepreg capacity.
Germany
Automotive OEMs in Stuttgart and Munich specify carbon-fiber-reinforced PEEK for transmission components and thermal management modules requiring metal replacement. REACH authorization processes for chlorinated precursors force reformulation investments among compounders in the Rhine-Ruhr chemical belt. Baden-Württemberg's automotive belt and Bavaria's industrial machinery corridor concentrate injection molding and machining operations for high-performance components.
China
NMPA harmonization with international medical device standards accelerates import substitution for implantable-grade PEEK in spinal and dental applications. GB standards and dual carbon goals shape domestic qualification requirements for semiconductor fabrication equipment suppliers. The Yangtze River Delta manufacturing corridor and Pearl River Delta electronics clusters drive powder and film demand for wafer handling and connector insulation.
Japan
METI hydrogen infrastructure roadmaps specify PEEK seals and bipolar plates for fuel cell vehicle scaling beyond traditional aerospace and medical verticals. JIS standards and PMDA medical device frameworks maintain rigorous biocompatibility documentation requirements. The Kanto region around Tokyo and the Chubu industrial belt near Nagoya host precision compounders serving automotive electronics and industrial equipment manufacturers.
Switzerland
Swissmedic and EU MDR alignment enable spinal implant manufacturers in Warsaw and Dublin to consolidate supplier bases around established medical-grade PEEK producers with existing master files. Swiss orthopedic device clusters in the Lake Geneva region and Zurich maintain above-average margin positions through biocompatibility qualification continuity. Precision machining operations in the Jura arc supply finished spinal cages and dental abutments to European hospital networks.
Polyetherketone Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the polyetherketone value chain, with polymerization-scale manufacturers maintaining cost advantages in virgin resin while specialized compounders capture premium positioning in medical and aerospace grades. The vendor base stratifies into three tiers: integrated resin producers with captive monomer supply, independent compounders serving qualification-intensive segments, and regional distributors managing inventory for price-sensitive automotive and electronics volumes. Dominant competitive moves include backward integration into difluorobenzophenone precursors and long-term supply agreements with orthopedic OEMs locking five-year volume guarantees.
Among UK-based polymer specialists, Victrex exemplifies the integrated resin producer archetype through concentrated PEEK production serving medical and aerospace segments. Celanese Corporation occupies a position leveraging global acetyl and engineered materials infrastructure across automotive and electronics applications. SABIC represents the specialty chemicals portfolio approach, positioning PEKK offerings for next-generation aerostructures qualification programs. These three anchors illustrate the strategic divergence between polymerization-scale efficiency and qualification-intensive premium positioning.
| Leading Market Players |
|---|
| Pan Jin Zhongrun High Performance Polymer Co., Ltd. |
| Celanese Corporation |
| Victrex |
| Ensinger GmbH |
| SABIC |
| Evonik Industries AG |
| DuPont |
| Jilin Joinature Polymer Co., Ltd. |
| Solvay |
| Others |
Value Network & Pricing Analysis
EU Green Deal emissions mandates gate both qualified supply and premium-tier pricing access, as REACH authorization processes for chlorinated precursors force compounders to absorb reformulation costs or surrender aerospace certification continuity. Carbon border adjustment mechanisms and natural gas price volatility in Europe further compress margins for nucleophilic aromatic substitution operations, concentrating pricing power among producers with captive monomer supply or Asian manufacturing footprints.
Pricing Analysis
Certification-linked value pricing anchors aerospace and medical tiers, where FAA and EASA concurrent qualification cycles and EU MDR master file continuity command resin premiums far above automotive spot markets. Price differentiation separates implantable-grade PEEK with biocompatibility documentation from unfilled industrial grades, while volume-scale contracts for orthopedic OEMs compress per-kilogram rates. Cost compression in standard PEEK runs through Chinese powder imports, though medical device manufacturers in Switzerland and Ireland show minimal price sensitivity due to qualification switching costs.
Supply Chain Analysis
Freight cost volatility from Chinese and Indian difluorobenzophenone producers exposes European compounders to customs processing delays and maritime rate swings. Raw material sourcing draws from hydroquinone and chlorinated aromatic feedstocks concentrated in the Yangtze River Delta and Gujarat chemical corridors. Single-source vulnerability in specialty monomer supply chains intensifies as REACH restrictions shrink European precursor capacity. Distribution runs through long-term resin supply agreements with Boeing, Airbus, and Stryker locking five-year volume guarantees, displacing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH authorization timelines and qualification switching costs force sub-scale compounders toward exit or acquisition by integrated resin producers.
For Market Incumbents: Cement aerospace certification continuity through parallel FAA and EASA test matrix investments, defending against PEKK copolymer substitution by Tier-1 autoclave suppliers in France and Italy. Deepen backward integration into difluorobenzophenone precursors to offset carbon border exposure and monomer supply concentration in China and India.
For New Entrants and Emerging Players: Regional distributors serving price-sensitive automotive electronics clusters in the Yangtze River Delta offer lower qualification barriers than direct OEM engagement. Target thin-gauge PEEK film production for connector insulation and capacitor dielectrics, where miniaturization trends outpace incumbent capacity expansion. Pursue CDSCO harmonization pathways for orthopedic implant compounding operations in India ahead of EU MDR-aligned production-linked incentive schemes.
For Investors and Strategic Acquirers: Boeing or Airbus PEKK fuselage qualification announcements are the leading indicator that certified resin supply will tighten, favoring acquisition targets with existing master files and autoclave partnerships. Mid-cap compounders with medical-grade PEEK documentation and spare nucleophilic aromatic substitution capacity represent the optimal target archetype. Monitor ECHA substance evaluation work program updates for chlorinated precursor restrictions that would strand legacy synthesis assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Difluorobenzophenone | Captive precursor supply insulates Victrex and Solvay from REACH authorization disruptions. |
| Long-term Supply Agreement with Orthopedic OEM | Five-year volume guarantees with Stryker or Zimmer Biomet reduce qualification overhead. |
| PEKK Copolymer Formulation Investment | Tailored crystallization kinetics enable out-of-autoclave wing rib production for Airbus. |
| CDSCO-Aligned Compounding Facility in India | Local production captures spinal implant demand under EU MDR-harmonized PLI schemes. |
| Continuous Fiber 3D Printing Process Development | Laser-assisted tape placement partnerships with French Tier-1 suppliers bypass autoclave bottlenecks. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings, ECHA substance evaluation registers, and FDA 510(k) filings, complemented by interviews with plant managers at European resin producers, procurement leads at German automotive OEMs, biomedical engineers at Swiss orthopedic device manufacturers, and distribution channel partners serving the Yangtze River Delta electronics corridor. Bottom-up resin volume estimates triangulated against top-down aerospace and medical device production forecasts.
Segment-level value outputs across product type, application, and form dimensions were derived through elasticity-adjusted price projections over the analysis window, with CAGRs calibrated to qualification cycle timelines and thermoplastic composite adoption curves in Boeing and Airbus programs. Industry-specific inputs included autoclave capacity expansion announcements, EU MDR master file continuity rates, and NMPA import substitution trajectories for implantable grades.
Several conditions sit outside the modeled scope, including abrupt REACH authorization withdrawals for diaryl ether intermediates, natural gas price spikes exceeding carbon border adjustment thresholds, and FAA certification delays for flight-critical PEKK components. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market