
 High Temperature Sealants Market | 2026-2036
High Temperature Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Sealants Market Analysis
Specialized polymer chemist availability is rotating toward Asia-Pacific contract manufacturers, constraining formulation capacity at Western facilities. 3M leverages its fluorosilicone patent estate to dominate aerospace gasket applications. Henkel AG & Co. KGaA anchors European automotive OEM supply chains through captive distribution networks. Momentive Performance Materials Inc. specializes in phenyl silicone technologies for extreme thermal cycling environments.
High temperature sealants are formulated polymer compounds—typically silicone, epoxy, or hybrid resin systems—that maintain adhesion and elasticity above 150°C, often incorporating ceramic fillers or boron nitride for thermal stability and oxidation resistance. These materials function primarily to prevent gas or fluid leakage under thermal stress in engines, exhaust systems, and industrial furnaces. Silicone formulations command the widest application footprint across aerospace and electronics sectors due to their flexibility retention at sustained operating temperatures. Epoxy systems occupy higher-margin niches in industrial equipment where compressive strength and chemical resistance outweigh elasticity requirements. Acrylic chemistries compete on cost in lower-temperature automotive sealing applications where thermal ceiling demands remain moderate.
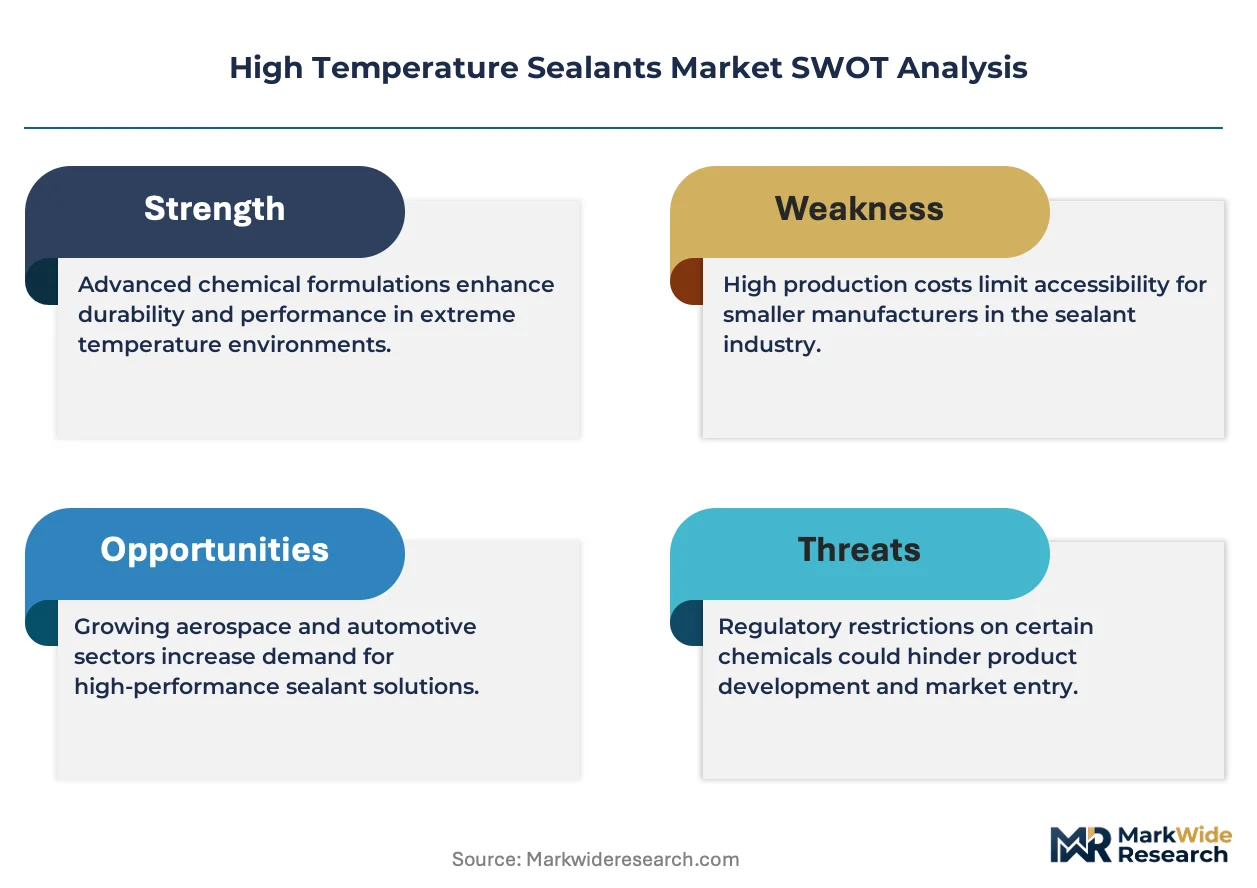
FDA food-contact regulations, EPA National Emission Standards for Hazardous Air Pollutants, and REACH substance restrictions collectively constrain permissible base chemistries and curing agent selections across manufacturing jurisdictions. Compliance with these frameworks necessitates reformulation investments that favor suppliers with dedicated regulatory affairs teams and centralized testing laboratories. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in the European Union and corresponding state-level actions in California and Michigan, as these will determine which silicone backbone architectures remain commercially viable across the next product development cycle.
Market Dynamics
REACH substance restrictions and EPA National Emission Standards for Hazardous Air Pollutants are forcing simultaneous reformulation across silicone, epoxy, and hybrid resin architectures, compressing development timelines while elevating compliance costs for Western manufacturers.
Growth Catalysts
- Aerospace propulsion thermal management:Next-generation turbine and scramjet programs require sealants maintaining elasticity above 300°C, pulling specialized fluorosilicone and phenyl silicone volumes into defense and commercial aviation supply chains.
- REACH chemical safety protocols:Tightening volatile organic compound thresholds in industrial formulations are disqualifying legacy solvent-based systems, creating replacement demand for advanced thermal barrier products in automotive and power equipment manufacturing.
- Ceramic filler integration:Boron nitride and aluminum oxide loading technologies are extending service temperature ceilings in electronics packaging, opening high-margin niches in semiconductor fabrication equipment and electric vehicle power modules.
Market Restraints
- Specialized polymer chemist scarcity:Formulation expertise is rotating toward Asia-Pacific contract manufacturers, constraining capacity expansion at Western facilities and elongating product qualification timelines.
- Per- and polyfluoroalkyl substance restrictions:Evolving EU regulatory frameworks and corresponding state-level actions in California and Michigan threaten commercial viability of fluorinated silicone backbone architectures.
- Raw material concentration:High-purity silicone precursors and specialty ceramic fillers depend on concentrated supply bases in China and Germany, exposing formulators to input volatility and geopolitical disruption.
Strategic Opportunities
- India automotive thermal management:Domestic electric vehicle and commercial vehicle manufacturing expansion under PLI scheme incentives is creating localized demand for heat-resistant bonding materials previously imported from Europe.
- Dual carbon goals compliance:China's MEE emissions reduction mandates are accelerating industrial furnace retrofit cycles, opening specification windows for oxidation-resistant sealant systems in steel and cement processing equipment.
- Additive manufacturing convergence:Integration of high-temperature sealant deposition with directed energy deposition and binder jetting processes is enabling in-situ sealing of complex geometries in aerospace and energy sector components.
Industry Challenges
- Regulatory affairs talent scarcity:Dedicated compliance teams capable of navigating simultaneous FDA food-contact, EPA emissions, and REACH substance restrictions command premium compensation, stretching mid-tier formulator resources.
- Centralized testing laboratory capex:Validation of thermal cycling performance and oxidation resistance requires specialized furnace and analytical equipment investments that strain R&D budgets.
- Legacy system integration friction:New low-VOC curing chemistries often exhibit incompatibility with established automotive and aerospace application equipment, necessitating costly process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Sealants Market |
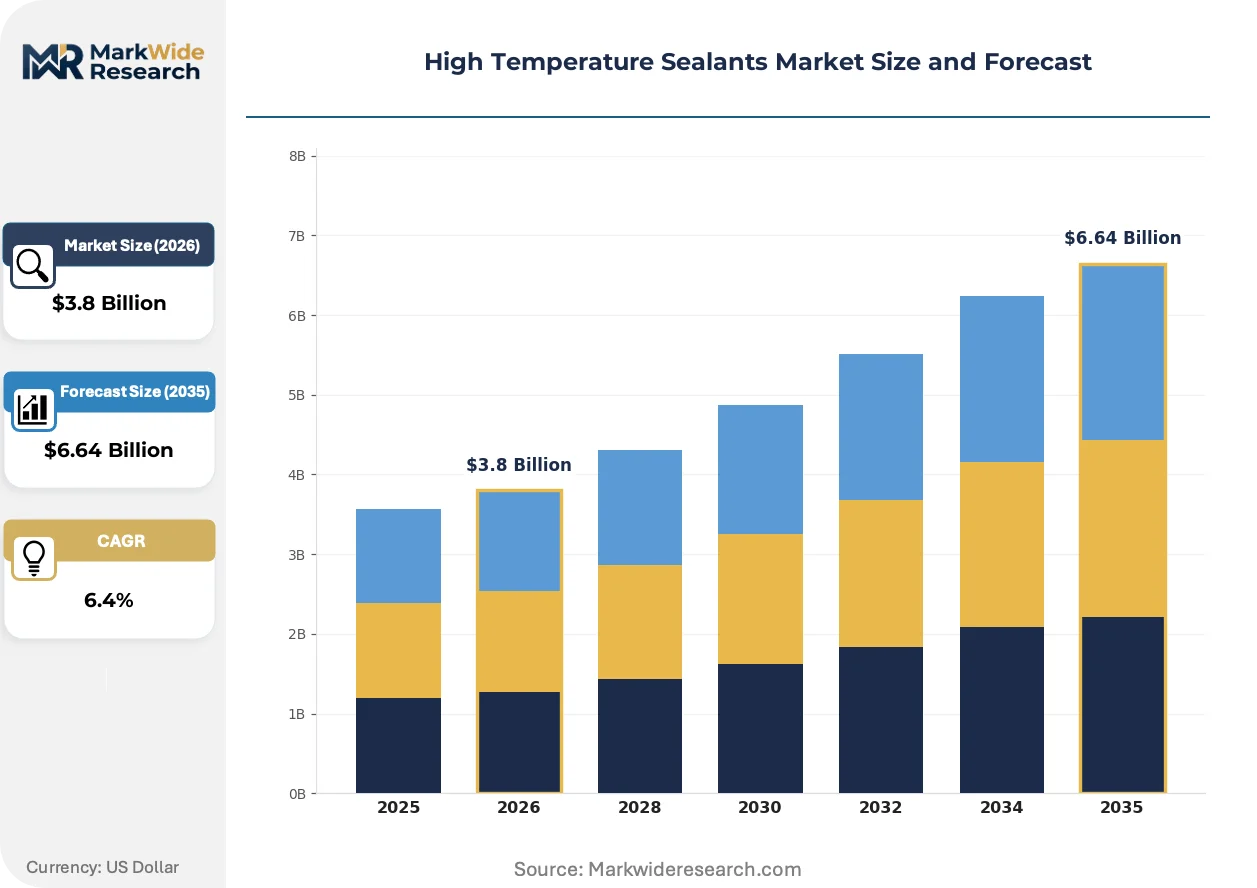
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Epoxy, Acrylic Application: Aerospace, Automotive, Electronics, Industrial Equipment End User: Manufacturing, Construction, Automotive OEMs, Marine Installation Method: Manual, Automated, Spray, Dispensing |
| Companies Covered | 3M, Sika AG, H.B. Fuller Company, Momentive Performance Materials Inc., Dow Corning Corporation, Wacker Chemie AG, Henkel AG & Co. KGaA, Hylomar Ltd., CSL Silicones Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Sealants Market Emerging Trajectories
Formulation architectures are actively fragmenting along thermal performance and regulatory compliance axes, with silicone, epoxy, and hybrid systems diverging toward distinct end-use specializations rather than converging on universal solutions.
Hybrid resin systems incorporating ceramic nanofillers and silicone-epoxy copolymers are bifurcating the market between premium aerospace specifications and cost-optimized automotive applications. Tier-one suppliers in Germany and the United States are qualifying these materials for next-generation propulsion systems at compressed development cycles. The technology is bifurcating procurement patterns, separating buyers demanding 5000-hour thermal aging guarantees from those accepting 1000-hour performance thresholds at substantially lower price points.
REACH per- and polyfluoroalkyl substance restrictions and corresponding EPA state-level actions are eliminating fluorinated backbone chemistries from food-contact and consumer-facing applications. Formulators are pivoting toward phenyl silicone and non-fluorinated hybrid architectures, accepting modest thermal performance trade-offs. European automotive OEMs and appliance manufacturers are most affected, accelerating supplier qualification timelines for alternative chemistries ahead of 2025 enforcement milestones.
Specification consolidation among tier-one automotive and aerospace OEMs is compressing approved vendor lists and elongating qualification cycles for new sealant formulations. Distributors and contract manufacturers are absorbing inventory risk as direct procurement relationships concentrate around captive supply agreements with Henkel and 3M. Germany's automotive supply cluster exhibits this pattern most acutely, where powertrain and exhaust system manufacturers now demand multi-year supply commitments with embedded price escalation clauses.
High Temperature Sealants Market Segmentation
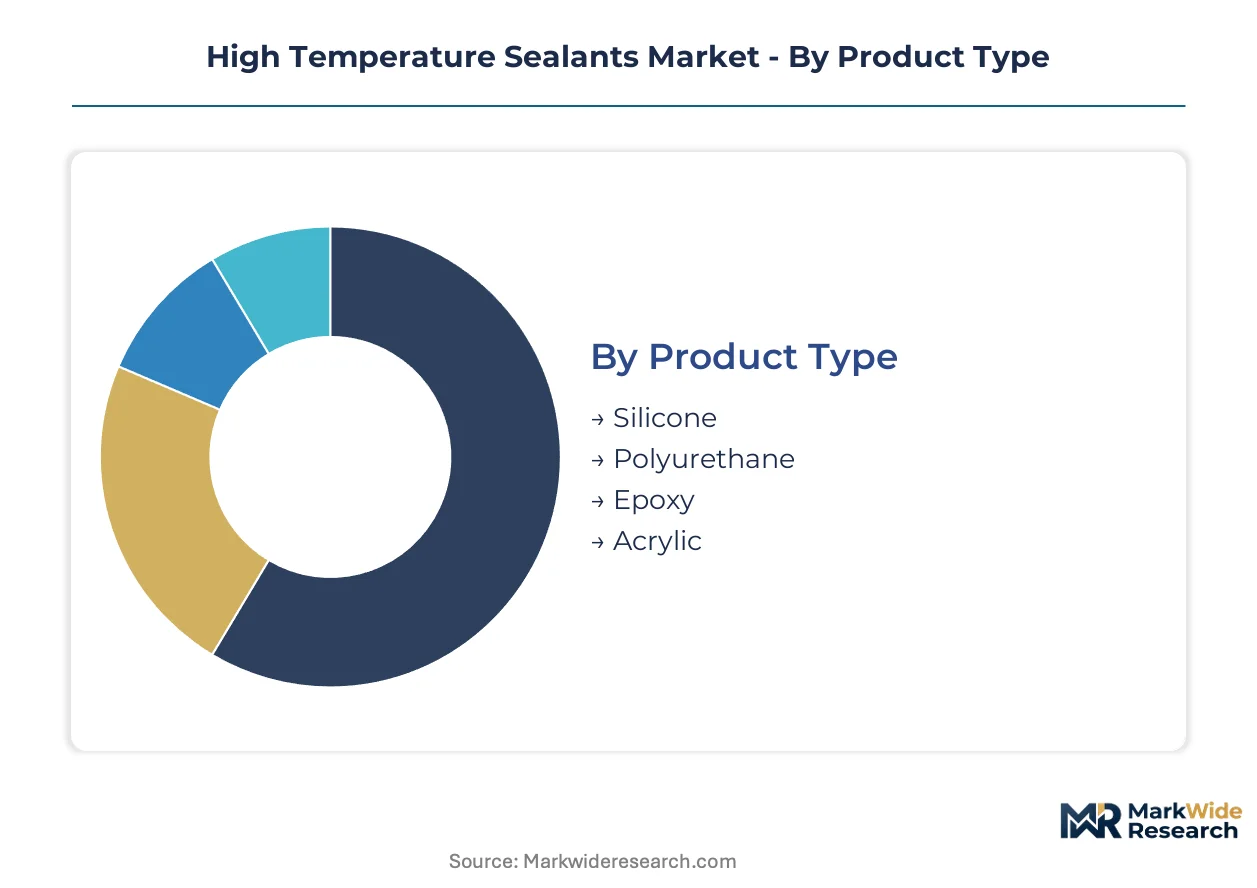
High temperature sealant procurement patterns diverge sharply across product chemistries and installation methods, with aerospace and automotive OEMs demanding qualification-heavy supply chains while industrial buyers prioritize volume flexibility. Channel configuration directly shapes margin capture, as specialized distributors control formulation access for premium specifications.
Product Type:
Channel mix varies by thermal ceiling, with silicone formulations flowing through aerospace-focused distributors and epoxy systems concentrating in industrial equipment direct procurement.
- Silicone:Fluorosilicone and phenyl silicone backbones deliver elasticity retention above 300°C, serving turbine engine manufacturers and scramjet propulsion programs. Demand concentrates in Germany and the United States, where REACH compliance investments and EPA emissions standards are disqualifying legacy solvent-based alternatives.
- Epoxy:Ceramic-filled rigid systems provide compressive strength and chemical resistance for industrial furnaces and exhaust components. Procurement clusters around power equipment manufacturers in Germany, with China's MEE emissions mandates accelerating retrofit specification windows.
- Polyurethane:Cost-optimized formulations compete in moderate-temperature automotive sealing where thermal ceilings remain below 200°C. Automotive OEMs in India source these materials under PLI scheme localization incentives.
- Acrylic:Lower-cost chemistries serve consumer appliance and construction applications with limited thermal stress requirements. Distribution runs through construction supply retailers with minimal technical support.
Silicone dominates installed base in aerospace and electronics packaging. Epoxy is where expansion concentrates in industrial furnace retrofit cycles.
Application:
Margin structure stratifies across application tiers, with aerospace commanding qualification premiums and automotive segmenting by thermal performance tier.
- Aerospace:Next-generation turbine and hypersonic propulsion systems require 5000-hour thermal aging guarantees at sustained temperatures exceeding 300°C. Defense and commercial aviation OEMs in the United States and Germany are compressing development timelines for specialized fluorosilicone volumes.
- Automotive:Powertrain and exhaust system sealing demands span from economy-grade acrylics to premium silicone-epoxy hybrids. European OEMs are accelerating supplier qualification for phenyl silicone alternatives ahead of per- and polyfluoroalkyl substance enforcement milestones.
- Electronics:Semiconductor fabrication equipment and electric vehicle power modules drive boron nitride-loaded formulations. China's dual carbon goals are expanding specification windows for oxidation-resistant systems in battery thermal management.
- Industrial Equipment:Steel and cement processing equipment retrofit cycles create demand for ceramic-filled systems with extended service intervals. MEE emissions reduction mandates in China are accelerating furnace sealing replacement rates.
Automotive anchors volume concentration. Aerospace is climbing the fastest on value per kilogram metrics.
End User:
Customer type determines technical service intensity, with manufacturing and automotive OEMs requiring embedded formulation support versus construction buyers prioritizing price transparency.
- Manufacturing:Industrial equipment producers demand multi-year supply commitments with embedded price escalation clauses. Germany's automotive supply cluster exhibits captive distribution relationships with dedicated regulatory affairs support.
- Automotive OEMs:Powertrain and exhaust system manufacturers specify thermal cycling performance validated through centralized testing laboratory protocols. Approved vendor list compression is elongating qualification cycles for new formulations.
- Construction:Building envelope and HVAC applications favor manual installation methods with moderate thermal requirements. Procurement concentrates through distributor networks with inventory risk absorption.
- Marine:Offshore and shipbuilding applications require salt-spray corrosion resistance combined with thermal stability. Specification windows remain narrower than aerospace or automotive verticals.
Automotive OEMs dominate qualification-heavy premium tiers. Manufacturing is where mid-tier expansion concentrates.
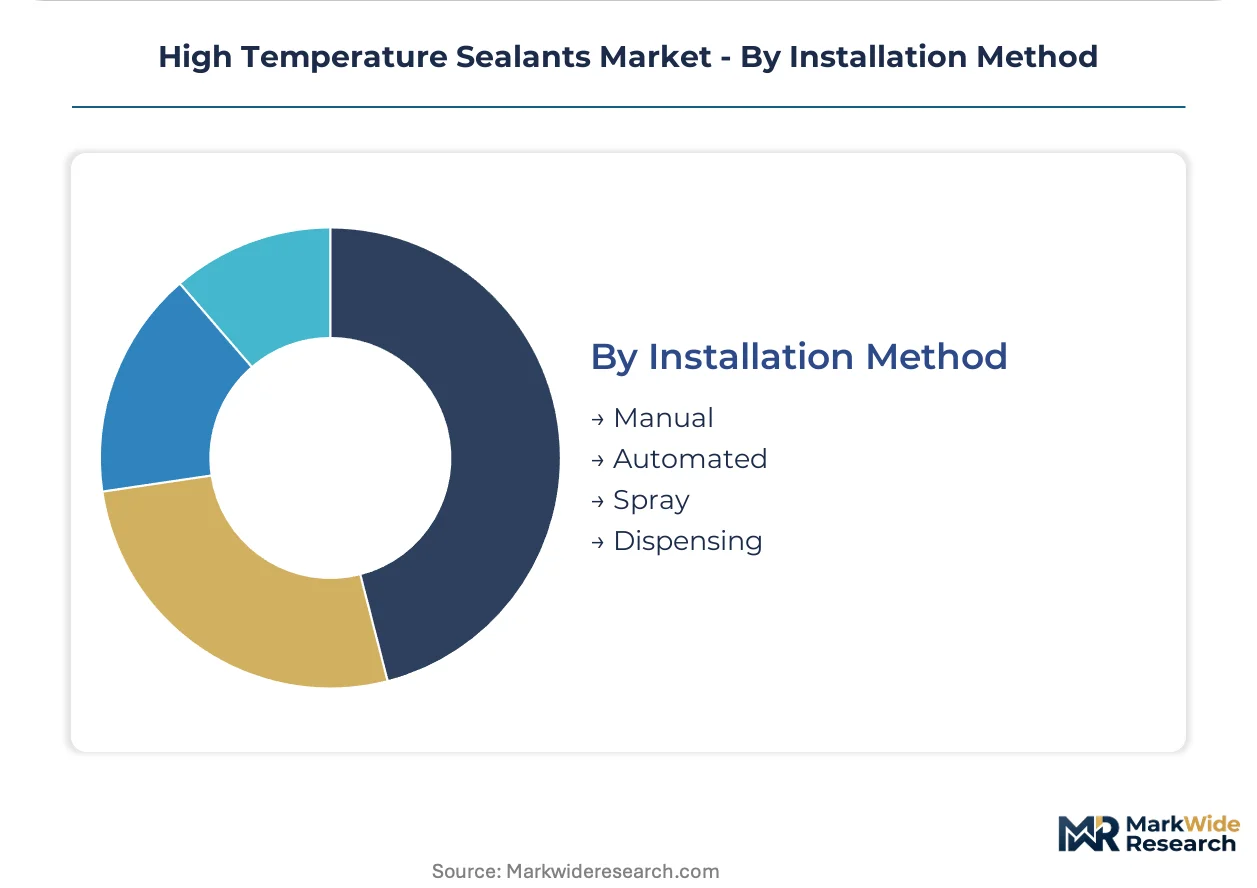
Installation Method:
Application equipment compatibility shapes method selection, with automated systems requiring process revalidation investment and manual methods preserving flexibility.
- Manual:Brush and trowel application persists in construction and maintenance contexts where geometry variability precludes automation. Labor cost arbitrage favors this method in emerging manufacturing clusters.
- Automated:Robotic dispensing systems integrate with automotive and aerospace production lines, requiring curing chemistry compatibility with established equipment. New low-VOC formulations often exhibit friction with legacy system integration.
- Spray:Large-surface industrial applications favor spray deposition for furnace linings and exhaust ductwork. Film thickness control demands skilled application supervision.
- Dispensing:Precision meter-mix systems serve electronics packaging and aerospace component sealing with tight bead placement requirements. Equipment capex concentrates procurement among tier-one suppliers.
Manual methods dominate installed base in construction and maintenance. Automated dispensing is gaining share fastest in OEM manufacturing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive supply clusters while Chinese manufacturers compete on volume through state-backed localization incentives. This asymmetry shapes procurement patterns across aerospace, automotive, and industrial equipment verticals. Regulatory divergence between EPA emissions frameworks and China's MEE mandates is fragmenting formulation standards by geography.
Germany
Automotive powertrain and exhaust system manufacturers anchor European demand for phenyl silicone and fluorosilicone formulations. REACH substance restrictions and KBA vehicle certification protocols are accelerating supplier qualification timelines for PFAS-free alternatives ahead of enforcement milestones. The Stuttgart-Munich corridor hosts captive distribution relationships with embedded regulatory affairs support.
United States
Defense and commercial aviation OEMs compress development cycles for next-generation turbine and scramjet propulsion sealants. FAA certification requirements and EPA National Emission Standards for Hazardous Air Pollutants constrain permissible curing chemistries in industrial applications. The aerospace manufacturing cluster in Washington state and California pulls specialized fluorosilicone volumes through qualification-heavy supply chains.
China
Steel and cement processing equipment retrofit cycles create demand for ceramic-filled epoxy systems with extended service intervals. MEE emissions reduction mandates under dual carbon goals are accelerating furnace sealing replacement rates. The Yangtze River Delta manufacturing belt concentrates domestic electric vehicle power module production requiring boron nitride-loaded thermal management materials.
India
Domestic commercial vehicle and electric vehicle manufacturing expansion drives localized procurement of heat-resistant bonding materials. PLI scheme incentives for automotive component production are displacing European imports with domestic formulation capacity. The Tamil Nadu and Maharashtra industrial corridors host emerging sealant fabrication facilities serving OEM qualification programs.
High Temperature Sealants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with patent-protected fluorosilicone specialists commanding aerospace premiums while Asian contract manufacturers compete on formulation scale. The market structure concentrates around three tiers: multinational chemical conglomerates with captive distribution networks, mid-tier regional specialists with regulatory compliance capabilities, and emerging Asia-Pacific fabricators leveraging polymer chemist availability. Dominant competitive moves include backward integration into high-purity silicone precursors and strategic partnerships with tier-one automotive OEMs for multi-year supply commitments.
Among diversified chemical conglomerates, 3M and Henkel AG & Co. KGaA exemplify archetypes with established aerospace and automotive supply chain positions. Momentive Performance Materials Inc. occupies a specialist tier focused on phenyl silicone technologies. These anchors reflect broader market segmentation between patent-protected premium formulations and cost-optimized regional production.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| H.B. Fuller Company |
| Momentive Performance Materials Inc. |
| Dow Corning Corporation |
| Wacker Chemie AG |
| Henkel AG & Co. KGaA |
| Hylomar Ltd. |
| CSL Silicones Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German phenyl silicone facilities runs above regional peers, compressing price floors for aerospace-grade formulations while elevating entry barriers for mid-tier competitors serving REACH-compliant automotive specifications. This scale asymmetry concentrates margin capture among incumbents with captive precursor supply and centralized testing infrastructure, forcing smaller formulators toward cost-optimized polyurethane segments or Asia-Pacific contract manufacturing partnerships.
Pricing Analysis
Configured-to-order pricing for 5000-hour thermal aging guarantees commands spreads exceeding standard catalog formulations by certification grade and volume commitment. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal ceiling and regulatory compliance tier, with aerospace fluorosilicone specifications carrying brand premiums tied to FAA validation protocols. Cost compression in automotive phenyl silicone alternatives is intensifying because European OEMs are consolidating approved vendor lists ahead of per- and polyfluoroalkyl substance enforcement milestones. Construction and appliance segments exhibit highest price sensitivity, while defense propulsion programs demonstrate lowest elasticity due to qualification lock-in and multi-year supply commitments.
Supply Chain Analysis
Strategic stockpile preferences dominate among German automotive OEMs buffering against REACH reformulation disruptions, while just-in-time inventory governs electronics packaging procurement of boron nitride-loaded formulations. High-purity silicone precursors and specialty ceramic fillers draw from concentrated supply bases in China and Germany, exposing formulators to input volatility and geopolitical disruption. Single-source vulnerability concentrates around fluorosilicone monomer production, where patent-protected processes limit qualified suppliers. Distribution runs through aerospace-focused distributors for premium specifications and captive networks for automotive tier-one relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high temperature sealants market is entering a cyclical recovery phase driven by industrial furnace retrofit cycles under China's MEE emissions mandates, creating replacement demand for oxidation-resistant ceramic-filled systems.
For Market Incumbents: Compound regulatory affairs capabilities through centralized testing laboratory investments that compress qualification timelines for phenyl silicone alternatives ahead of EU enforcement milestones. Backward integration into high-purity silicone precursors defends margin position against raw material volatility from China and Germany supply concentration. Channel control through captive distribution networks in the Stuttgart-Munich corridor locks in automotive OEM multi-year commitments with embedded price escalation clauses. For New Entrants and Emerging Players: Technical regulatory support gaps in India's PLI scheme localization incentives offer white-space entry points for domestic electric vehicle power module sealant qualification. Target mid-tier industrial equipment retrofit specifications where 1000-hour thermal aging thresholds substitute for premium aerospace guarantees at substantially lower price points. Partner with Tamil Nadu and Maharashtra fabrication facilities to bypass European import dependencies and accelerate OEM qualification programs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among phenyl silicone specialists with aerospace and automotive captive supply agreements spanning multi-year horizons. Five-to-ten year viability favors acquisition targets with dedicated regulatory affairs teams navigating simultaneous FDA food-contact, EPA emissions, and REACH substance restrictions. Watch for inflection when per- and polyfluoroalkyl substance enforcement milestones trigger accelerated supplier qualification timelines for fluorinated backbone alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Captive supply of high-purity monomers insulates margin from China and Germany input volatility. |
| Centralized Testing Laboratory Investment | FAA and KBA validation protocols compress qualification cycles for aerospace and automotive specifications. |
| Long-term Supply Agreement with OEMs | Multi-year commitments with embedded price escalation clauses lock in volume through cyclical downturns. |
| Regulatory Affairs Team Expansion | Dedicated compliance capabilities navigate REACH, EPA, and FDA restrictions that disqualify mid-tier competitors. |
| Joint Venture with Asia-Pacific Fabricators | Polymer chemist availability in contract manufacturing hubs addresses Western formulation capacity constraints. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with aerospace procurement directors, automotive tier-one supplier technical leads, industrial equipment maintenance managers, and polymer formulation chemists at Western and Asia-Pacific facilities. Secondary validation drew from EPA National Emission Standards for Hazardous Air Pollutants filings, REACH substance restriction updates, ECHA registration dossiers, and customs trade data for high-purity silicone precursor flows. Bottom-up segment sizing triangulated against top-down industry association aggregates from chemical manufacturing federations.
Across the analysis window, volume and value projections were derived from modeled interactions between product chemistry segmentation, installation method adoption curves, and end-user qualification intensity. Segmentation dimensions spanned silicone-epoxy-polyurethane-acrylic chemistries, aerospace-automotive-electronics-industrial equipment applications, and manual-automated-spray-dispensing installation methods. CAGRs were computed from year-over-year growth rate trajectories adjusted for regulatory reformulation cycle impacts and raw material input cost movements.
Underlying assumptions cover sustained aerospace propulsion thermal management demand and REACH compliance investment continuity, with deviation risk concentrated in per- and polyfluoroalkyl substance restriction acceleration or China-Germany precursor supply disruptions. Forecasts reflect these conditions without scenario-weighted probability adjustments. Revision becomes warranted when MEE emissions mandate enforcement intensity or PLI scheme incentive structures cross threshold levels that materially alter retrofit cycle timing or localization economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Isobornyl Acrylate Market