
 Polyurethane (PU) Hot-Melt Adhesive Market | 2026-2036
Polyurethane (PU) Hot-Melt Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Hot-Melt Adhesive Market Analytics
Specialty chemical distribution channels serving European automotive tier suppliers is reconfiguring around consolidated logistics networks and technical service bundling. Henkel AG & Co. KGaA leverages its captive supply of polyester polyols to control formulation consistency across regional blending sites. H.B. Fuller Company anchors its position through direct technical sales teams embedded at major woodworking OEMs in North America. Sika AG competes by specializing in moisture-cure reactive systems for construction membrane bonding where application speed determines contractor selection.
Polyurethane hot-melt adhesive denotes a thermoplastic bonding material formulated from isocyanate-terminated prepolymers that crosslink upon exposure to atmospheric moisture, typically exhibiting open times of 30–120 seconds and final bond strengths exceeding 1,000 psi. These adhesives serve industrial assembly by eliminating solvent emissions while delivering structural bonds across dissimilar substrates including plastics, metals, and coated wood. Reactive hot-melt formulations command premium positioning due to their hybrid thermoplastic-thermoset performance profile and superior heat resistance relative to conventional EVA systems. The automotive end use industry generates concentrated margin pools as OEMs specify PUR systems for lightweight panel bonding to meet fuel efficiency mandates. Solvent-free technology dominates volume production lines where VOC regulations have eliminated solvent-based alternatives.
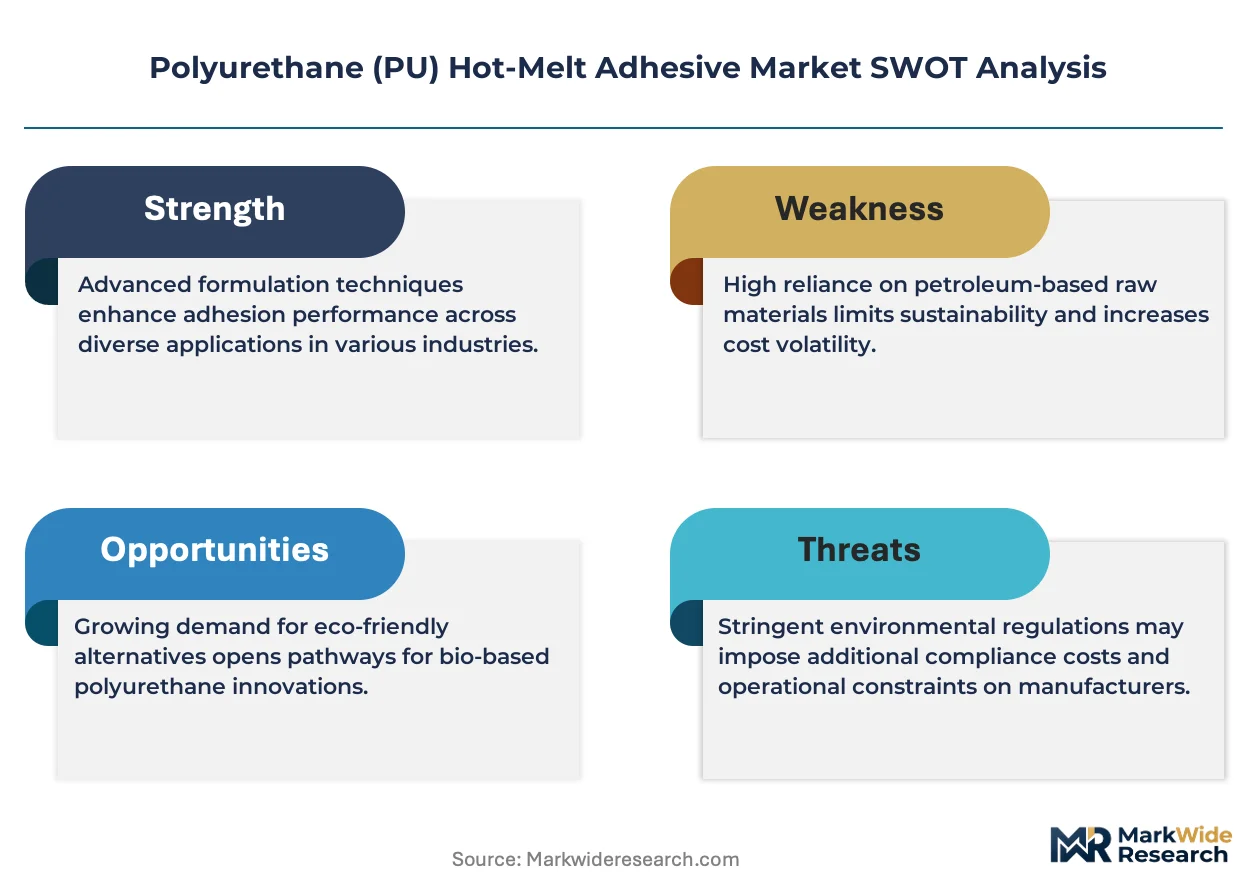
EPA air quality standards and OSHA workplace exposure limits in the United States restrict isocyanate handling protocols, compelling manufacturers to invest in enclosed application equipment and worker monitoring systems. REACH registration requirements and the EU Green Deal carbon border adjustments in Europe elevate compliance costs for imported prepolymer feedstocks while favoring regional producers with certified circular content streams. ISO 9001 and IATF 16949 quality frameworks govern supplier qualification across automotive and electronics value chains, creating documentation barriers for new entrants. Stakeholders must weigh capital allocation between moisture-cure capacity expansion and next-generation bio-based polyol development as regulatory thresholds tighten.
Market Dynamics
Automotive OEMs are consolidating adhesive specifications around moisture-cure reactive systems to eliminate solvent-based alternatives from lightweight panel assembly lines. This specification tightening concentrates procurement power among tier suppliers capable of documenting REACH-compliant feedstock chains and IATF 16949 quality frameworks.
Growth Catalysts
- EPA air quality standards:VOC restrictions in the United States are eliminating solvent-based bonding alternatives from industrial production lines. Manufacturers are converting to reactive hot-melt systems to maintain throughput without emissions controls.
- Lightweighting mandates:Automotive assembly operations specify PUR systems for dissimilar substrate bonding to meet fuel efficiency requirements. Panel bonding applications now dominate high-margin formulation demand.
- Germany manufacturing concentration:The country's automotive tier supply base anchors European demand for certified circular content streams. Regional prepolymer producers leverage REACH registration advantages over imported feedstocks.
Market Restraints
- Isocyanate input volatility:MDI and TDI pricing fluctuations compress formulation margins unpredictably. Manufacturers lack pass-through mechanisms with long-term automotive supply contracts.
- Prepolymer supply concentration:Asian producers dominate merchant isocyanate-terminated feedstock supply. European and North American blenders face extended lead times and currency exposure.
- Moisture-cure latency:Open times of 30–120 seconds restrict application automation speeds. High-volume assembly lines require parallel station investment to match EVA system throughput.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for domestic manufacturing are creating first-mover advantages for adhesive suppliers establishing technical service presence. Woodworking and packaging machinery OEMs represent underpenetrated demand.
- Bio-based polyol convergence:Castor oil and soybean-derived polyols are reaching performance parity with petroleum-based alternatives. Formulators combining renewable content with moisture-cure chemistry access EU Green Deal procurement preferences.
- Construction membrane bonding:Roofing and waterproofing contractors prioritize application speed for labor cost control. Specialized reactive systems command premium positioning where rapid green strength reduces crew sizing.
Industry Challenges
- Formulation chemistry expertise scarcity:Moisture-cure system design requires cross-disciplinary knowledge of isocyanate reactivity, substrate surface energy, and atmospheric moisture kinetics. Technical talent competition intensifies between adhesive suppliers and upstream chemical producers.
- Worker exposure compliance:OSHA isocyanate handling protocols mandate enclosed application equipment and medical surveillance programs. Capital requirements for compliant production facilities exclude smaller regional blenders from automotive qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Hot-Melt Adhesive Market |
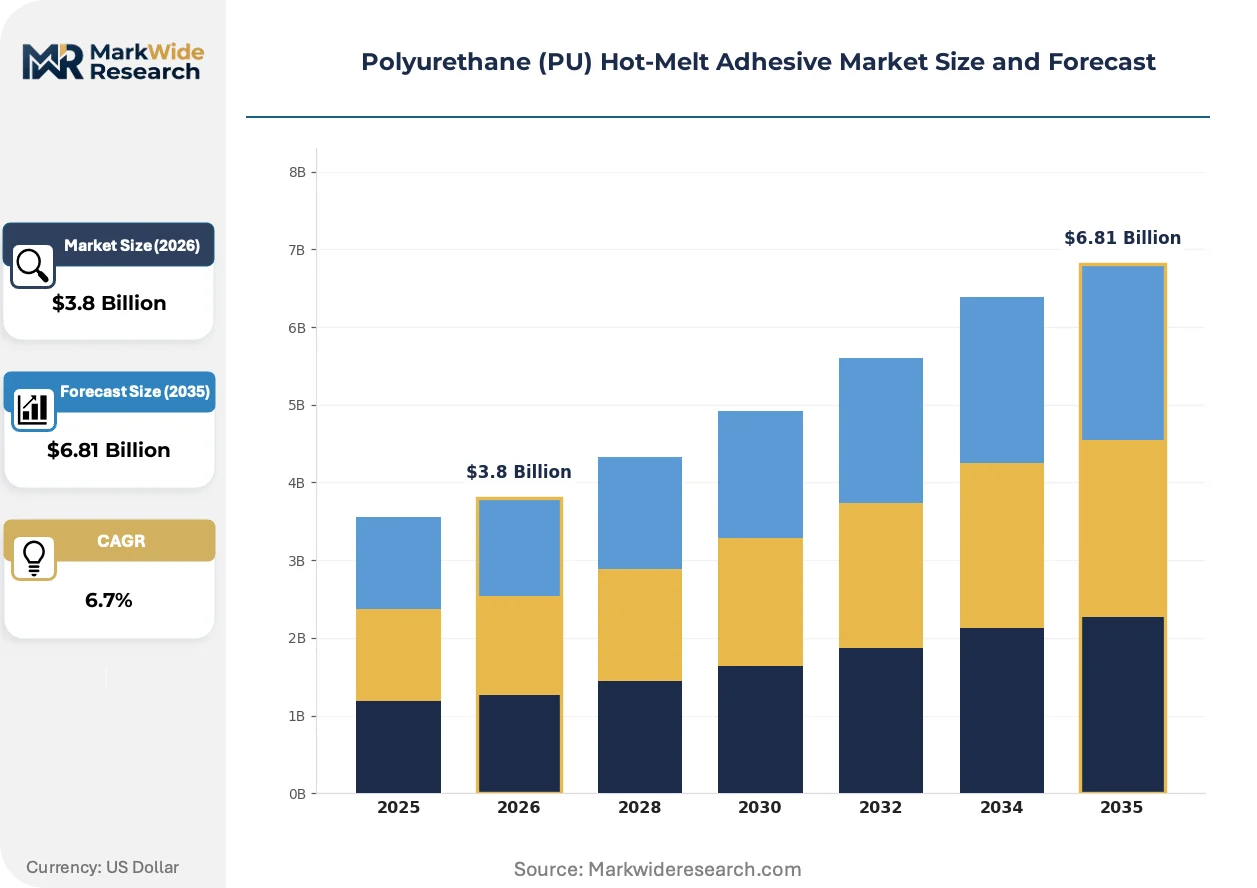
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Hot-Melt, Multi-Functional, Conventional Hot-Melt, Specialty Adhesives End Use Industry: Automotive, Construction, Electronics, Furniture Technology: Solvent-Free, Water-Based, Solvent-Based, Cold Application Application: Packaging, Footwear, Woodworking, Automotive Assembly |
| Companies Covered | 3M, Arkema, Henkel AG & Co. KGaA, H.B. Fuller Company, BASF, Jowat SE, Sika AG, DIC Corporation, Collano Adhesives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Hot-Melt Adhesive Market Evolving Landscape
Reactive polyurethane chemistry is displacing conventional adhesive technologies across industrial assembly applications. Three concurrent developments are reconfiguring competitive positioning and procurement patterns.
Moisture-cure reactive hot-melt technology is migrating from automotive panel bonding into electronics assembly and medical device manufacturing. Original equipment manufacturers in Germany and China are specifying these systems for heat-sensitive component attachment where reworkability conflicts with structural integrity requirements. The technology is migrating from premium automotive tiers toward mid-volume industrial equipment producers seeking solvent-free alternatives without full thermoset commitment.
REACH registration requirements and EU Green Deal carbon border adjustments are elevating compliance documentation burdens for imported prepolymer feedstocks. European formulators with certified circular content streams gain procurement preference from automotive OEMs facing Scope 3 emissions accounting pressure. The regulatory friction most affects small and mid-sized blenders dependent on Asian merchant isocyanate supply without captive backward integration.
Direct technical sales embedding is replacing distributor-led specification development in North American woodworking and packaging machinery sectors. OEM engineering teams now demand application-specific formulation support during equipment design phases rather than post-installation troubleshooting. This pattern concentrates most visibly among mid-cap furniture manufacturers in the United States seeking to differentiate through bonded joint performance warranties.
Polyurethane (PU) Hot-Melt Adhesive Market Segmentation
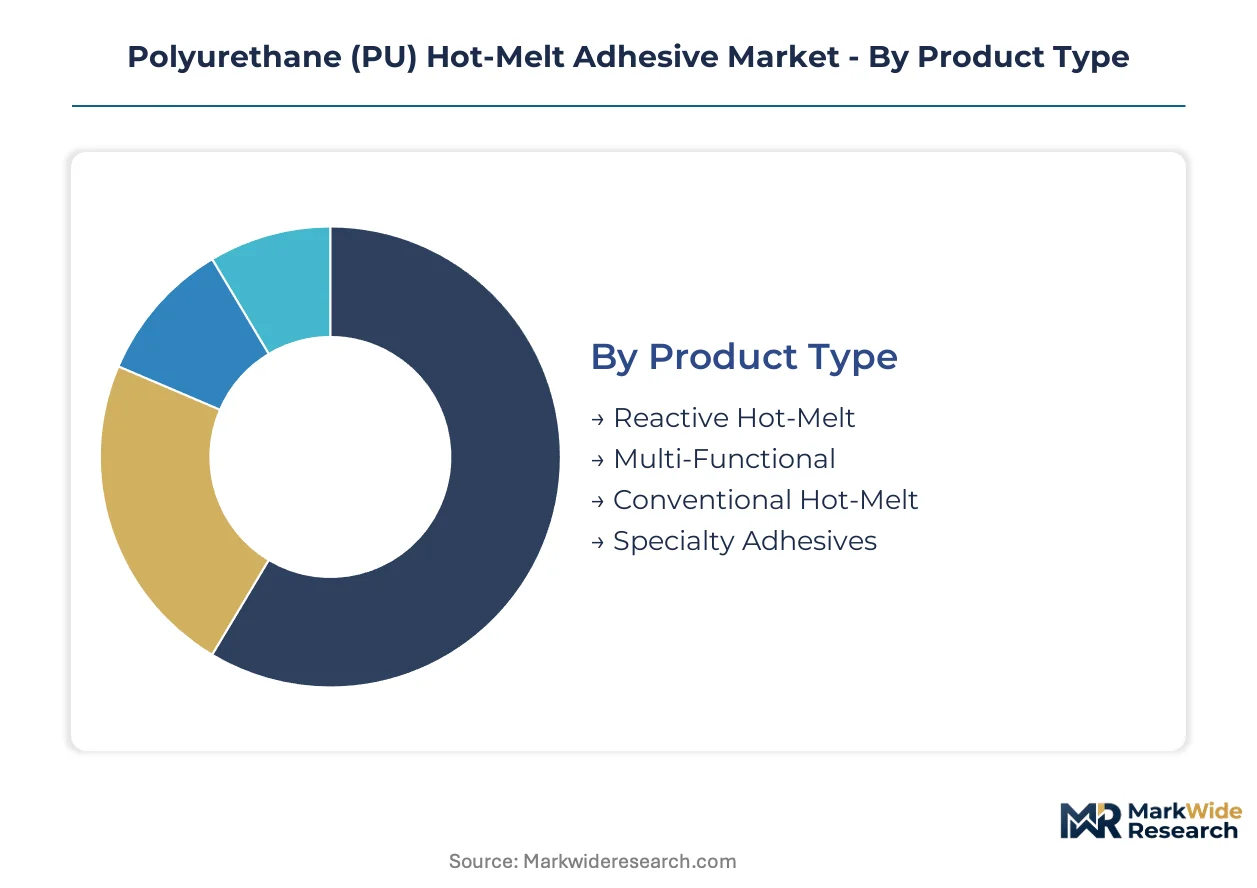
Segmentation in polyurethane hot-melt adhesives reveals how formulation chemistry, regulatory compliance, and application requirements partition procurement decisions. Each dimension exposes distinct margin structures and technical service intensities that shape supplier competitive strategy.
Product Type:
After-sales technical support intensity varies dramatically across product categories, with reactive systems demanding embedded field engineers for moisture-cure optimization while conventional grades require minimal post-sale intervention.
- Reactive Hot-Melt:Isocyanate-terminated prepolymers crosslink via atmospheric moisture to deliver thermoset-grade heat resistance exceeding 1,000 psi final bond strength. Automotive OEMs in Germany specify these systems for lightweight panel bonding to satisfy fuel efficiency mandates under EU Green Deal carbon accounting frameworks.
- Multi-Functional:Hybrid formulations combine rapid green strength development with extended open times for automated assembly lines. Electronics manufacturers in China specify these grades for heat-sensitive component attachment where reworkability conflicts with structural integrity requirements.
- Conventional Hot-Melt:Thermoplastic EVA-based systems dominate high-volume packaging lines where 30–120 second open times match throughput requirements without moisture-cure latency.
- Specialty Adhesives:Medical-grade and optical-bonding formulations serve FDA-regulated device assembly and display lamination with ultra-low outgassing specifications.
Reactive Hot-Melt holds the largest share; momentum sits with Multi-Functional as electronics assembly specifications migrate toward hybrid performance profiles.
End Use Industry:
Cost tier stratification separates premium formulation demand in automotive from price-sensitive volume procurement in furniture, with construction occupying a mid-tier technical service bandwidth.
- Automotive:OEM panel bonding specifications concentrate procurement power among tier suppliers documenting REACH-compliant feedstock chains and IATF 16949 quality frameworks. Moisture-cure reactive systems command formulation premiums for dissimilar substrate bonding in lightweight vehicle architectures.
- Construction:Roofing and waterproofing membrane contractors prioritize application speed for labor cost control, driving specification of rapid green strength systems that reduce crew sizing requirements.
- Electronics:Heat-sensitive component attachment demands low-temperature application combined with structural bond integrity.
- Furniture:Woodworking OEMs in North America seek bonded joint performance warranties to differentiate mid-cap manufacturing output.
Automotive generates the highest formulation margins; construction applications are climbing fastest as building energy efficiency codes tighten membrane performance requirements.
Technology:
Volume concentration in solvent-free production lines reflects regulatory elimination of VOC-emitting alternatives across industrial manufacturing geographies.
- Solvent-Free:Zero-emission reactive hot-melt systems dominate automotive and electronics assembly where EPA air quality standards and OSHA workplace exposure limits have eliminated solvent-based handling. Manufacturers convert existing lines to maintain throughput without emissions control capital investment.
- Water-Based:Low-VOC alternatives serve porous substrate applications in furniture and packaging where moisture sensitivity permits extended drying cycles.
- Solvent-Based:Niche applications persist in specialty coating and primer layers where substrate compatibility demands organic carrier systems.
- Cold Application:Ambient-temperature dispensing systems reduce energy consumption in high-volume packaging operations.
Solvent-Free technology commands dominant volume share; Water-Based formulations are gaining share fastest as furniture manufacturers seek middle-ground regulatory compliance without full reactive system investment.
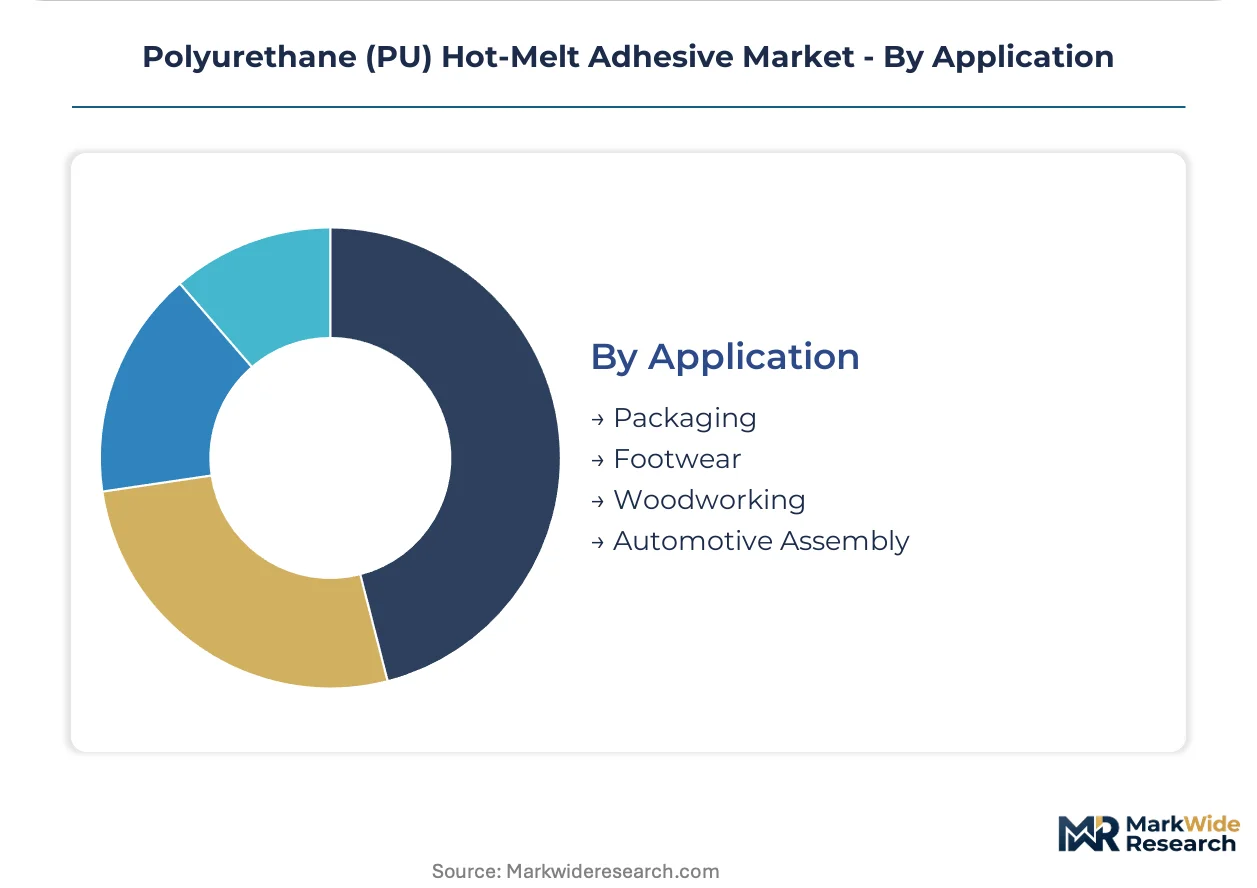
Application:
Customer type differentiation separates specification-driven automotive assembly from procurement-led packaging operations, with woodworking occupying a hybrid technical sales territory.
- Packaging:High-speed carton sealing and case erecting operations demand consistent 30–120 second open times matched to automated line speeds. Volume procurement through distributor channels prioritizes price stability over technical service bundling.
- Automotive Assembly:Tier supplier qualification requires captive backward integration into polyester polyol supply and documented circular content streams for Scope 3 emissions accounting.
- Footwear:Upper-to-sole bonding applications combine flexibility requirements with abrasion resistance for athletic and safety shoe categories.
- Woodworking:Edgebanding and lamination operations in mid-cap furniture manufacturing seek application-specific formulation support during equipment design phases.
Packaging holds the largest volume share; Automotive Assembly represents the steepest expansion trajectory as lightweighting mandates proliferate across OEM specification sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Northwestern Europe's role as a prepolymer formulation hub, connecting German automotive clusters to global isocyanate feedstock flows.
Germany
Automotive tier suppliers in Baden-Württemberg and Bavaria specify moisture-cure reactive systems for lightweight panel bonding under EU Green Deal carbon accounting mandates. REACH registration requirements elevate compliance costs for imported feedstocks while favoring regional producers with certified circular content streams. The Stuttgart automotive cluster anchors formulation demand as OEMs consolidate procurement around documented Scope 3 emissions chains.
China
Electronics manufacturers in the Yangtze River Delta and Pearl River Delta specify multi-functional grades for heat-sensitive component attachment where reworkability conflicts with structural integrity. MIIT industrial standards and dual carbon goals accelerate solvent-free system conversion across high-volume assembly lines. Shenzhen's electronics corridor drives specification migration toward hybrid thermoplastic-thermoset performance profiles.
United States
Woodworking OEMs in the Southeast and Midwest seek bonded joint performance warranties to differentiate mid-cap furniture manufacturing output. EPA air quality standards and OSHA isocyanate handling protocols compel investment in enclosed application equipment and worker monitoring systems. The Carolina furniture belt concentrates technical sales embedding as direct specification development replaces distributor-led procurement.
India
PLI scheme incentives for domestic manufacturing create first-mover advantages for adhesive suppliers establishing technical service presence across woodworking and packaging machinery sectors. BIS quality certification requirements and DGFT import substitution policies favor regional blending capacity over merchant prepolymer dependence. The Maharashtra-Gujarat industrial corridor concentrates emerging demand as automotive component localization accelerates.
Japan
Precision electronics and medical device manufacturers in Kanto and Kansai specify ultra-low outgassing specialty grades for FDA-regulated assembly applications. METI carbon neutrality roadmaps and JIS quality standards tighten allowable chemical content in adhesive formulations. The Nagoya automotive supply cluster maintains specification discipline around IATF 16949 quality frameworks for bonded component exports.
Polyurethane (PU) Hot-Melt Adhesive Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in prepolymer supply and formulation chemistry. The vendor base organizes around three archetypes: captive backward-integrated chemical producers controlling polyester polyol supply, independent blenders competing on technical service intensity, and regional distributors consolidating logistics networks with application engineering support. Dominant competitive moves include capacity expansion in moisture-cure reactive systems and strategic partnerships bundling formulation supply with automated dispensing equipment.
Among European chemical conglomerates, Henkel AG & Co. KGaA and BASF exemplify the captive supply archetype through in-house control of key feedstock streams. H.B. Fuller Company anchors the technical service-intensive tier among North American independents. Sika AG occupies a specialized position in moisture-cure reactive systems for construction applications. These three represent distinct competitive vectors: upstream chemical integration, embedded OEM engineering support, and application-specific formulation depth.
| Leading Market Players |
|---|
| 3M |
| Arkema |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| BASF |
| Jowat SE |
| Sika AG |
| DIC Corporation |
| Collano Adhesives |
| Others |
Value Network & Pricing Analysis
Rotterdam's chemical handling infrastructure anchors European prepolymer formulation capacity, concentrating pricing power among regional blenders with REACH-registered circular content streams while Asian merchant isocyanate suppliers compete on volume scale. This geographic asymmetry creates tiered procurement economics where automotive OEMs absorb premium pricing for documented Scope 3 compliance while packaging converters optimize for spot-market feedstock costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified automotive grades from industrial packaging formulations and generic woodworking adhesives. Price differentiation rests on certification grade and volume scale, with REACH-compliant reactive systems commanding substantial premiums over conventional EVA alternatives. Pricing pressure stems from MDI and TDI input volatility that compresses formulation margins unpredictably. Packaging converters exhibit highest price sensitivity due to commodity-grade procurement patterns, while automotive tier suppliers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Upstream isocyanate-terminated prepolymer production concentrates in China, Germany, and South Korea, with Asian merchant suppliers dominating feedstock flows to European and North American blenders. Raw material dependencies center on MDI, TDI, and polyester polyol streams where pricing fluctuations transmit directly to formulation economics. Supply chain risk manifests as extended lead times and currency exposure for blenders lacking captive backward integration. Distribution runs through consolidated logistics networks serving automotive tier suppliers and technical service bundles embedded at woodworking OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification consolidation around moisture-cure reactive systems is reconfiguring this market toward platform-economics dynamics, where IATF 16949 qualification and REACH-compliant feedstock chains function as interoperability standards that lock in tier supplier relationships.
For Market Incumbents: Pre-empt margin compression from Asian merchant isocyanate suppliers by deepening captive polyester polyol production and securing circular content certification ahead of EU Green Deal carbon border adjustments. Accelerate technical service embedding at mid-cap furniture OEMs before distributor-led procurement fully displaces. Priority levers include moisture-cure capacity expansion in Germany and direct specification development teams at North American woodworking clusters.
For New Entrants and Emerging Players: Build out technical service presence in India's Maharashtra-Gujarat industrial corridor where PLI scheme incentives concentrate emerging demand across woodworking and packaging machinery sectors. Target electronics assembly specifications in Shenzhen's manufacturing corridor where multi-functional grade demand outpaces established supplier coverage. Go-to-market angle should emphasize application-specific formulation support during equipment design phases rather than post-installation troubleshooting.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical service-intensive independents with embedded OEM engineering relationships and documented IATF 16949 quality frameworks. Long-term viability favors acquisition targets combining moisture-cure formulation expertise with backward integration into polyol supply. Signal to watch: automotive OEM Scope 3 emissions accounting mandates accelerating preference for certified circular content streams over merchant isocyanate dependence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Captive polyester polyol production insulates Henkel and BASF from MDI price volatility. |
| Moisture-Cure Capacity Expansion | Reactive system buildout in Germany captures automotive lightweighting specification demand. |
| Technical Service Embedding | Direct OEM engineering support at H.B. Fuller replaces distributor-led procurement in woodworking. |
| Certified Circular Content Investment | REACH-registered feedstock chains secure EU Green Deal procurement preference. |
| Regional Blending Joint Venture | India PLI corridor partnerships localize supply for automotive component manufacturing. |
Research Methodology
Operator-level perspectives from adhesive plant managers, automotive tier supplier procurement leads, woodworking OEM technical directors, and distribution channel partners anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and IHS Markit vehicle production databases. Bottom-up formulation volume estimates triangulated against top-down end-use industry demand modeling.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions covering product type tier, end-use industry, technology format, and regional production hub. CAGRs derived from regression analysis of historical volume trajectories against automotive production forecasts and construction membrane installation trends. Industry-specific inputs included EPA air quality standard implementation timelines and REACH registration compliance burdens.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian merchant prepolymer producers or accelerated bio-based polyol substitution would shift outcomes beyond modeled ranges. Cross-checking against customs data on isocyanate-terminated prepolymer import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market