
 South America Contact Adhesives Market | 2026-2036
South America Contact Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Contact Adhesives Market Analytics
Specialty chemical distribution channels across the Andean region and Southern Cone is reconfiguring as multinational suppliers consolidate regional warehousing partnerships. Henkel AG & Co. KGaA leverages its São Paulo technical center to sustain localized formulation services for furniture manufacturers. Bostik SA anchors its position through dedicated bulk supply contracts with Brazilian automotive tier-one suppliers. Dow competes by extending water-based polymer portfolios tailored to Argentina's tightening environmental protocols.
Contact adhesives are one-part or two-part bonding systems formulated with polychloroprene, polyurethane, or natural rubber resins dissolved in organic solvents or dispersed in aqueous media, achieving immediate tack and high green strength upon solvent evaporation at room temperature. Their primary industrial purpose is permanent bonding of decorative laminates, elastomeric foams, and polymer sheets where clamping is impractical. Solvent-based formulations still dominate value pools in high-performance footwear and automotive interior assembly, while water-based systems capture the fastest expansion as Brazilian and Argentine manufacturers retrofit spray booths to meet volatile organic compound limits. Hot melt contact adhesives occupy a narrower niche in packaging and disposable product lines where rapid set speed outweighs ultimate bond durability.
Brazil's national environmental council and Argentina's secretariat of environment enforce volatile organic compound thresholds that directly determine which resin technologies gain market access. ANVISA's industrial chemical notification requirements add registration costs that favor established suppliers with dedicated regulatory affairs staff. Stakeholders must monitor how Chile's advancing chemical inventory legislation reshapes cross-border formulation trade before committing to regional production assets.
Market Dynamics
Argentina's tightening volatile organic compound emission rules are forcing wholesale reformulation across solvent-based adhesive portfolios, compressing technology timelines and redistributing competitive advantage toward aqueous polymer capabilities.
Growth Catalysts
- Water-based system mandates:Argentina's Secretariat of Environment enforces VOC thresholds that redirect footwear and furniture manufacturers toward aqueous polychloroprene and polyurethane dispersions, opening formulation service contracts to compliant suppliers.
- Brazilian footwear cluster expansion:São Paulo's industrial corridor concentrates decorative laminate bonding demand for athletic and casual shoe production, sustaining solvent-based value pools while hybrid systems penetrate mid-tier segments.
- ANVISA chemical notification alignment:Brazil's industrial chemical registry requirements favor established suppliers with dedicated regulatory affairs infrastructure, consolidating market access around pre-registered resin portfolios.
Market Restraints
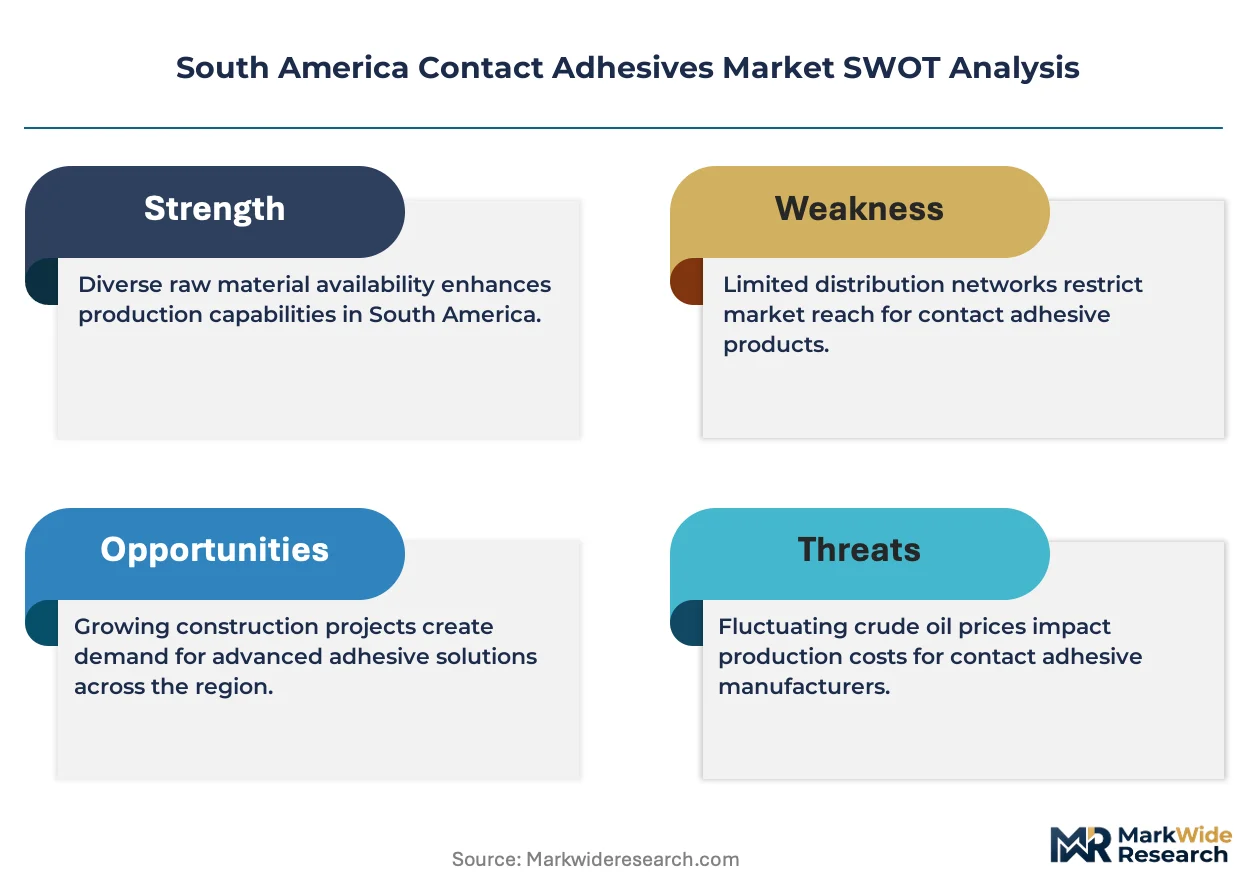
- Solvent feedstock cost volatility:Aromatic hydrocarbon and ketone solvent prices fluctuate with petrochemical refining margins in Brazil's southeast, compressing formulation margins for high-tack polychloroprene systems.
- Technical performance gaps in water-based systems:Aqueous polyurethane dispersions exhibit inferior green strength and open time versus solvent equivalents in automotive interior assembly, limiting full substitution in Brazilian tier-one supply contracts.
- Cross-border formulation trade friction:Chile's advancing chemical inventory legislation creates registration uncertainty for Argentine and Brazilian suppliers exporting formulated adhesives into Santiago's packaging and construction markets.
Strategic Opportunities
- Andean distribution channel reconfiguration:Multinational suppliers consolidating regional warehousing partnerships around Lima and Bogotá create entry points for technical service differentiation in Peru and Colombia's underpenetrated furniture sectors.
- Hot melt niche expansion:Disposable product and e-commerce packaging lines in São Paulo and Buenos Aires prioritize rapid set speed over ultimate bond durability, opening narrow but defensible volume positions for reactive polyurethane hot melts.
- Retrofit equipment bundling:Brazilian spray booth operators facing ANVISA enforcement timelines seek integrated aqueous system conversions combining adhesive supply with application equipment, enabling service-led revenue models.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in aqueous polymer stabilization and spray rheology remains concentrated among legacy solvent-based technical staff, creating recruitment bottlenecks for expanding Brazilian water-based production lines.
- Certification timeline compression:ANVISA's industrial chemical notification requirements impose 18-24 month registration windows that delay new resin introductions, favoring incumbents with existing dossiers.
- Legacy equipment integration:Argentine furniture manufacturers operate solvent-optimized spray systems with limited aqueous compatibility, requiring capital-intensive booth retrofits that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Contact Adhesives Market |
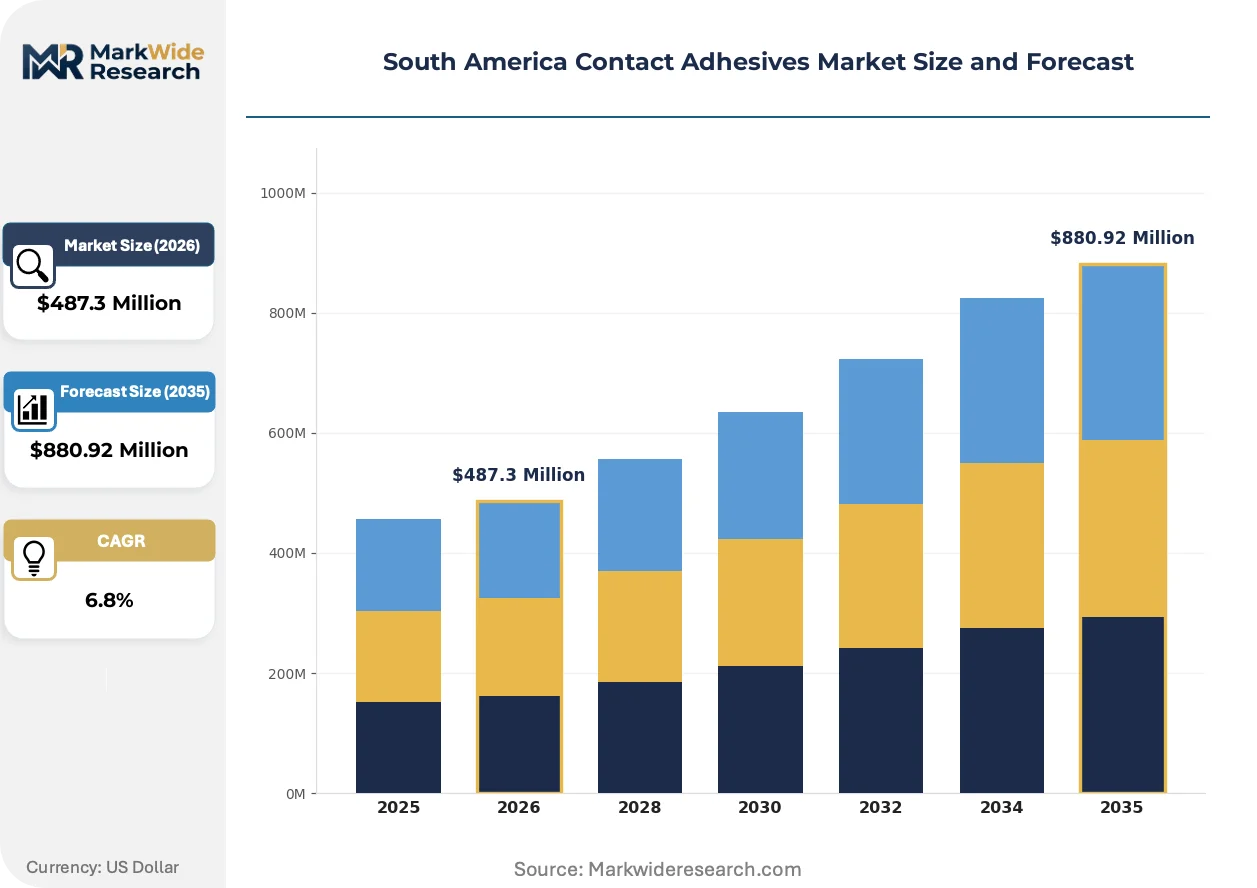
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Reactive, Hot Melt End Use Sector: Construction, Automotive, Furniture, Footwear Application: Bonding, Coating, Sealing, Assembly Packaging Format: Aerosol, Tube, Canister, Bulk |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Arkema Group, H.B. Fuller Company, Sika AG, Avery Dennison Corporation, Dow, Bostik SA, Huntsman International LLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Contact Adhesives Market Evolving Landscape
Formulation digitization and environmental compliance automation are compressing product development cycles while redrawing competitive boundaries between integrated multinationals and regional specialists.
Automated rheology monitoring is digitizing quality control protocols across Brazilian adhesive manufacturing. São Paulo-based producers deploy inline viscosity and tack measurement systems that reduce batch-to-batch variation. This sensor integration is digitizing specification compliance for automotive interior assembly contracts, compressing rejection rates and accelerating supplier qualification timelines.
Argentina's Secretariat of Environment VOC protocols are tightening maximum permissible solvent content in decorative laminate and foam bonding applications. Industrial users in Buenos Aires and Córdoba face equipment retrofit deadlines that accelerate aqueous system trials. Footwear manufacturers with export exposure to European markets are responding fastest, driven by overlapping REACH compliance requirements in their downstream supply chains.
Technical service unbundling is reshaping buyer-supplier relationships across the Southern Cone. Brazilian furniture manufacturers increasingly separate adhesive procurement from application engineering support, sourcing formulations through distributors while contracting independent equipment specialists. This disintermediation is most visible in São Paulo's mid-tier panel processing sector, where price transparency pressures compress distributor margins and favor suppliers with standalone technical consulting capabilities.
South America Contact Adhesives Market Segmentation
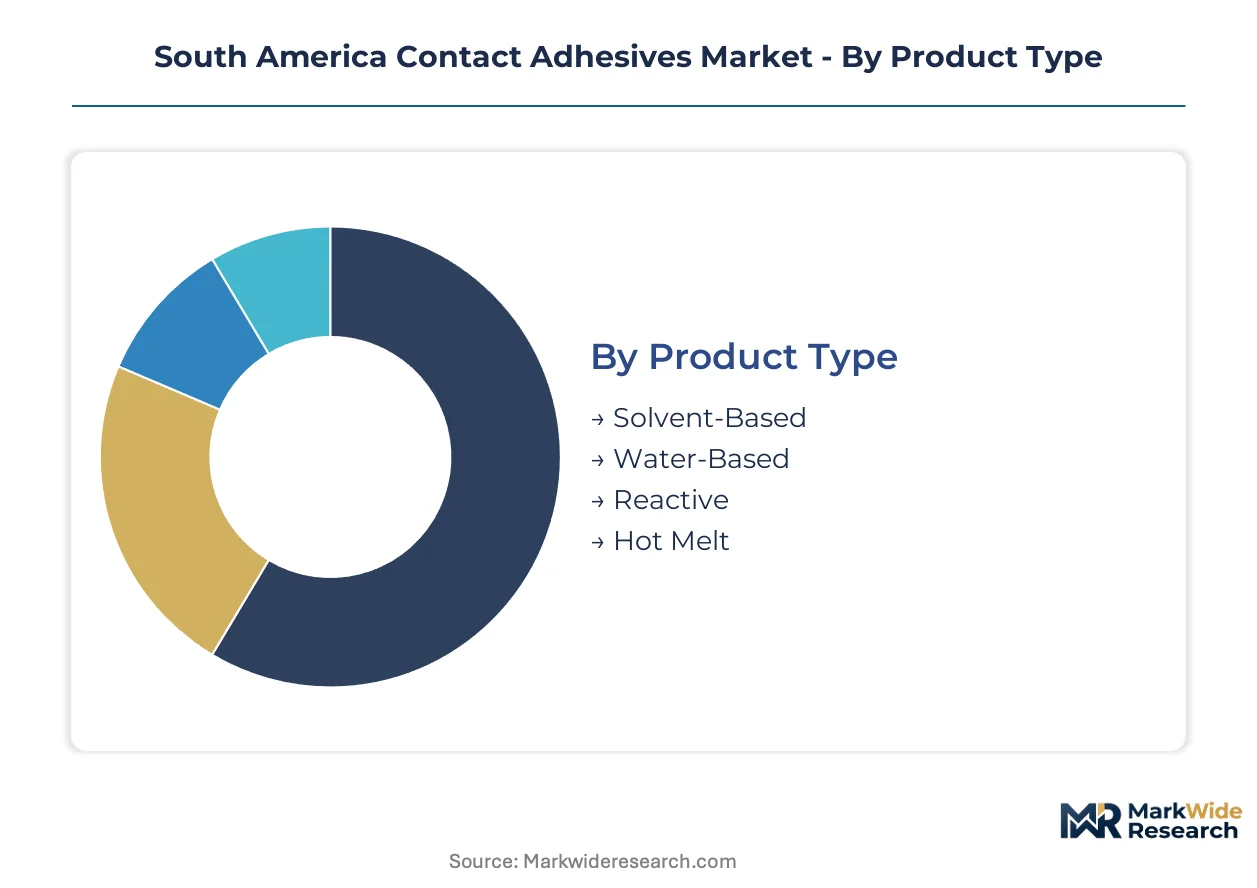
Contact adhesive segmentation across South America reflects divergent technical requirements between high-performance industrial assembly and compliance-driven reformulation. Product chemistry, end-use specifications, and packaging logistics each create distinct competitive arenas with unique margin structures and regulatory exposure.
Product Type:
Solvent-based systems dominate Brazilian footwear and automotive interior bonding where immediate green strength justifies VOC exposure, while water-based alternatives capture reformulation mandates in Argentina's tightening regulatory environment.
- Solvent-Based:Formulations dissolve polychloroprene or polyurethane resins in aromatic hydrocarbons and ketones, delivering aggressive tack and open time control for São Paulo's athletic shoe manufacturers. Brazilian tier-one automotive suppliers specify these systems for decorative laminate bonding despite ANVISA notification burdens and feedstock cost volatility.
- Water-Based:Aqueous polychloroprene and polyurethane dispersions serve Buenos Aires furniture manufacturers retrofitting spray booths to meet Secretariat of Environment VOC thresholds. Green strength limitations restrict penetration in high-speed automotive assembly lines.
- Reactive:Two-part polyurethane systems cure through moisture or catalyst activation, serving specialized construction membrane bonding in Chile's mining infrastructure sector.
- Hot Melt:Reactive polyurethane formulations target disposable product packaging lines in São Paulo and Buenos Aires where rapid set speed outweighs ultimate bond durability requirements.
The dominant share belongs to Solvent-Based formulations, while Water-Based alternatives are closing the gap fastest.
End Use Sector:
Volume concentration tracks industrial corridor geography, with São Paulo's manufacturing belt generating disproportionate demand against regulatory pressure in Argentina's furniture clusters.
- Construction:Membrane bonding and decorative surface installation drive specification-grade solvent and reactive system demand across Brazilian commercial building projects.
- Automotive:Interior trim assembly and seating fabrication in São Paulo's tier-one supplier network specify high-tack polychloroprene systems with digitized rheology compliance protocols.
- Furniture:Buenos Aires and Córdoba panel processors face equipment retrofit deadlines accelerating aqueous system trials, while mid-tier manufacturers strain under capital-intensive booth conversion costs.
- Footwear:Athletic and casual shoe production clusters in São Paulo sustain solvent-based value pools, with export-oriented manufacturers responding fastest to overlapping REACH and domestic VOC requirements.
Footwear commands the largest volume position, though Furniture exhibits the steepest technology transition trajectory.
Application:
Functional differentiation separates permanent structural assembly from protective surface treatment, with bonding applications carrying the strictest performance certification requirements.
- Bonding:Permanent adhesion of decorative laminates, elastomeric foams, and polymer sheets where clamping is impractical, dominating footwear and furniture manufacturing specifications.
- Coating:Protective surface treatments and primer applications in construction and automotive refinishing with distinct viscosity and solids content requirements.
- Sealing:Gap-filling and environmental barrier applications in building envelope and transportation equipment assembly.
- Assembly:Multi-component joining operations in automotive interior and industrial equipment manufacturing with defined open-time windows.
Bonding generates the highest specification intensity, while Assembly applications are diversifying fastest across customer tiers.
Packaging Format:
Format selection balances application scale, equipment compatibility, and distribution economics across fragmented regional supply chains.
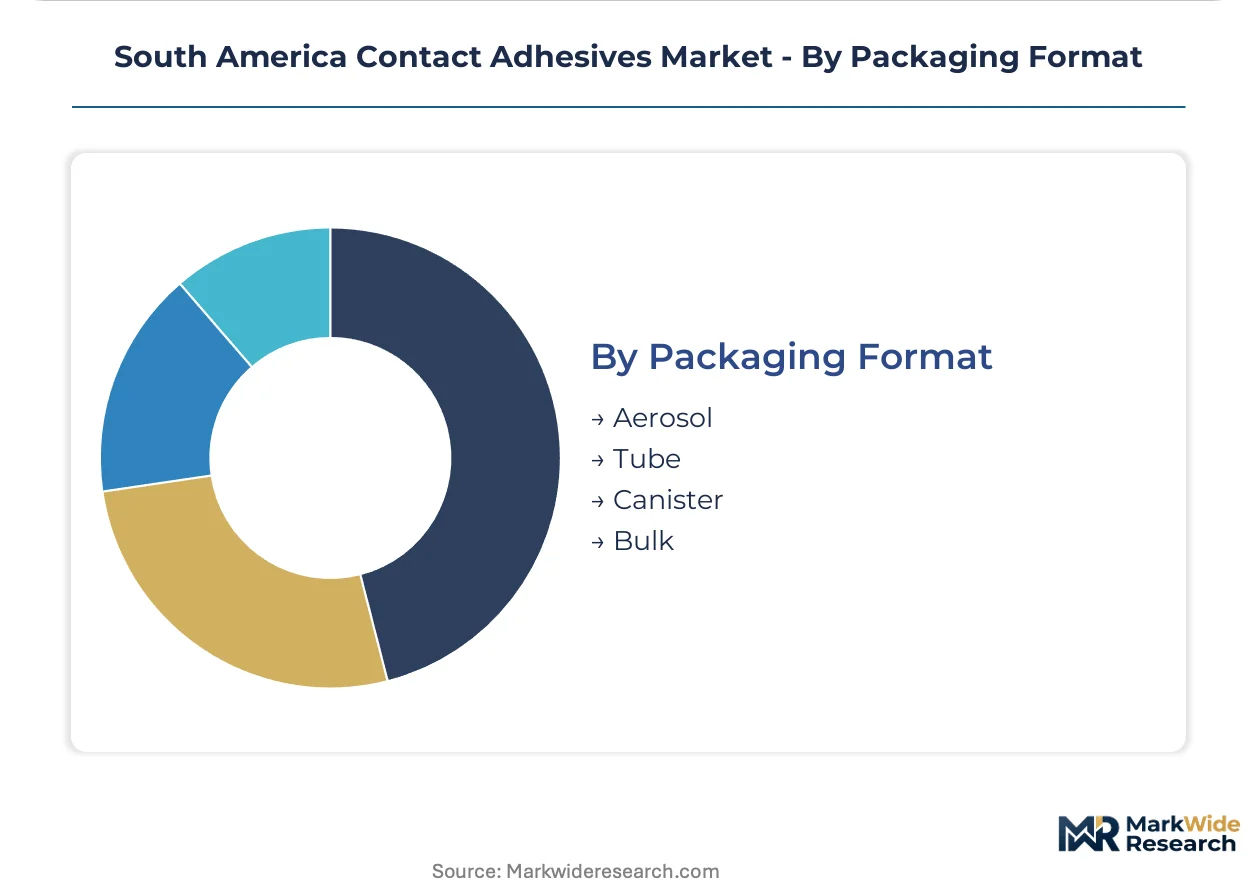
- Aerosol:Portable solvent-based systems serve on-site construction touch-up and small-batch furniture repair operations with immediate tack requirements.
- Tube:Consumer and light industrial applications in hardware retail channels, concentrated in Argentine and Chilean distribution networks.
- Canister:Mid-volume professional use in furniture workshops and automotive refinishing with controlled dispensing requirements.
- Bulk:Tanker and drum supply contracts anchor Bostik's position with Brazilian automotive tier-one suppliers and São Paulo footwear manufacturers with dedicated spray line infrastructure.
Bulk packaging captures the highest volume concentration, though Aerosol formats are penetrating fastest in construction field applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos serves as the primary entry corridor for resin feedstocks and formulated adhesives entering Brazil's southeastern manufacturing belt, anchoring South America's contact adhesives trade infrastructure.
Brazil
São Paulo's industrial corridor concentrates decorative laminate bonding demand for athletic footwear production, while ANVISA's industrial chemical notification requirements favor established suppliers with pre-registered resin portfolios. Automotive tier-one suppliers in the ABC Paulista region specify high-tack polychloroprene systems despite volatile aromatic hydrocarbon feedstock costs.
Argentina
Buenos Aires furniture manufacturers face compressed equipment retrofit timelines as the Secretariat of Environment tightens volatile organic compound thresholds for spray booth operations. Export-oriented footwear producers in Córdoba respond fastest to overlapping REACH compliance requirements in European downstream supply chains.
Chile
Mining infrastructure membrane bonding drives specialized reactive polyurethane demand in Santiago and Antofagasta, though advancing chemical inventory legislation creates registration uncertainty for cross-border formulation trade. Construction sector specification-grade adhesive procurement concentrates in the capital's commercial building projects.
Colombia
Bogotá's underpenetrated furniture sector attracts multinational distribution channel consolidation as regional warehousing partnerships reconfigure around Andean logistics hubs. Mid-volume professional adhesive use grows in panel processing workshops serving domestic construction markets.
Peru
Lima functions as an emerging distribution node for specialty chemical flows into Pacific coastal manufacturing, with technical service differentiation creating entry points in furniture sectors previously served through Argentine and Chilean intermediaries. Limited domestic formulation capacity sustains import-dependent supply structures.
South America Contact Adhesives Market Competitive Landscape
On the supply side, the industry is consolidating around multinational integrated suppliers with dedicated regulatory affairs infrastructure and regional technical service capabilities. Three strategic archetypes dominate: integrated chemical conglomerates with aqueous polymer portfolios, specialty adhesive specialists with bulk supply contracts, and diversified materials science companies with cross-selling synergies. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players retrofit spray line infrastructure and bundle equipment conversions with formulation supply.
Among diversified materials science companies, 3M and Avery Dennison Corporation occupy positions exemplifying cross-sector adhesive technology leverage, while Henkel AG & Co. KGaA anchors the integrated multinational tier with localized formulation services. Dow and Bostik SA represent the aqueous polymer and bulk supply contract archetypes respectively, reflecting divergent responses to environmental compliance pressures across Brazilian and Argentine manufacturing clusters.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Arkema Group |
| H.B. Fuller Company |
| Sika AG |
| Avery Dennison Corporation |
| Dow |
| Bostik SA |
| Huntsman International LLC |
| Others |
Value Network & Pricing Analysis
ANVISA registration chokepoints concentrate regulatory burden on Brazilian formulation imports, compressing margin structures for non-compliant suppliers while amplifying pricing power for incumbents with pre-registered resin portfolios and established São Paulo warehousing networks.
Pricing Analysis
Volume-discount tiering separates bulk tanker contracts for São Paulo automotive tier-one suppliers from mid-volume drum sales to Argentine furniture manufacturers and aerosol premiums for Chilean construction field applications. Price differentiation rests on certification grade—REACH-compliant formulations command premiums from export-oriented footwear producers—and geographic delivery cost spreads widen for Andean distribution nodes. Cost compression in water-based tiers is intensifying because aqueous polymer feedstock volatility outpaces solvent-based equivalent stability. Mid-tier Argentine panel processors exhibit highest price sensitivity due to capital-intensive spray booth retrofit requirements, while Brazilian automotive OEMs demonstrate lowest sensitivity given specification-locked supply contracts.
Supply Chain Analysis
Tariff exposure between Argentine formulation exporters and Chilean chemical inventory registration uncertainty dominates cross-border supply chain risk assessment for Southern Cone adhesive flows. Geographic supply concentration centers on Brazil's southeastern petrochemical corridor, Argentina's Buenos Aires industrial belt, and U.S. Gulf Coast aromatic hydrocarbon feedstock sources. Raw material dependencies draw from polychloroprene rubber imports, polyurethane prepolymer streams, and ketone solvent refining outputs. Single-source vulnerability persists in specialized aqueous dispersion polymer supply for Argentine VOC-compliant reformulation. Distribution runs through São Paulo-based multinational technical centers serving direct automotive contracts, with Lima and Bogotá emerging as Andean consolidation nodes for mid-tier furniture sector penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story: ANVISA notification requirements and Argentina's Secretariat of Environment VOC protocols create switching costs that cement incumbent positions while raising capital barriers for unregistered competitors.
For Market Incumbents: Pre-empt aqueous polymer capability gaps by acquiring Argentine formulation specialists with established water-based spray rheology expertise before Secretariat of Environment retrofit deadlines consolidate buyer relationships. Secure backward integration into Brazilian ketone solvent refining to dampen feedstock margin volatility threatening polychloroprene system profitability. Channel control through bundled equipment conversion contracts represents the priority defensive lever against independent technical service disintermediation. For New Entrants and Emerging Players: Establish a beachhead in Peru's Lima distribution corridor where multinational warehousing partnerships are reconfiguring and domestic formulation capacity remains absent. Target Colombia's Bogotá furniture sector through technical service differentiation rather than price competition, as mid-tier panel processors seek aqueous system guidance without incumbent relationship lock-in. A go-to-market angle anchored to Chilean mining infrastructure membrane bonding specifications—where reactive polyurethane demand outstrips qualified supplier coverage—opens defensible niche positioning. For Investors and Strategic Acquirers: The market sits at a compliance-transition phase that favors aqueous polymer specialists with ANVISA pre-registration dossiers and Argentine regulatory affairs infrastructure. Long-term viability over the projection horizon hinges on water-based formulation share capture as Brazilian and Argentine VOC thresholds tighten further. Acquisition target archetype: regional distributors with technical service capabilities in underpenetrated Andean markets. The signal to watch is Chilean chemical inventory legislation finalization, which would clarify cross-border registration requirements and either accelerate consolidation or freeze export-dependent supplier strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ketone Solvent Refining | Captive supply of aromatic hydrocarbon feedstocks insulates Brazilian polychloroprene margins from petrochemical volatility. |
| Aqueous Polymer R&D Partnership | Collaboration with São Paulo technical centers closes green strength gaps blocking automotive interior substitution. |
| Andean Distribution Channel Consolidation | Regional warehousing partnerships around Lima and Bogotá create technical service differentiation entry points. |
| Equipment Conversion Bundling | Integrated spray booth retrofit contracts lock in Brazilian furniture manufacturer switching costs. |
| ANVISA Registration Dossier Acquisition | Pre-registered resin portfolios compress 18-24 month notification timelines for new market entrants. |
Research Methodology
The analysis maps solvent-based, water-based, reactive, and hot melt formulation sub-sectors, each validated through technical directors at Brazilian automotive tier-one suppliers, Argentine furniture manufacturer procurement leads, and Peruvian distribution channel partners. Primary interview intelligence combined with secondary validation from ANVISA industrial chemical registries, Argentina Secretariat of Environment VOC protocol documentation, and Brazilian customs trade flow data. Bottom-up adhesive volume estimation by end-use sector triangulates against top-down petrochemical feedstock consumption patterns reported by regional industry associations.
Assumption sets held Brazilian footwear export demand and Argentine environmental enforcement timelines fixed while varying aqueous polymer substitution rates and Chilean chemical inventory registration outcomes across scenario branches. Segmentation dimensions modeled include product chemistry tier, end-use sector concentration, packaging format scale, and regional production hub regulatory cluster. CAGRs derived from adhesive consumption intensity ratios applied to downstream sector output projections, with cross-reference to polychloroprene and polyurethane resin import volumes as validation anchors.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine capital control severity, or regional petrochemical refining margins would shift the trajectory of formulation cost structures and import substitution patterns. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology transition pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Applicator Tips Market