
 Elastic Bonding Adhesive and Sealant Market | 2026-2036
Elastic Bonding Adhesive and Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Elastic Bonding Adhesive and Sealant Market Foresight
Silicone is hardening its position against solvent-based alternatives in high-performance bonding applications as environmental compliance costs reshape formulation economics. Henkel Corporation leverages its automotive OEM relationships to sustain premium positioning in structural glazing and direct glazing systems. Sika AG anchors its construction segment dominance through specialized distribution networks across European infrastructure projects. Dow competes on manufacturing scale, operating integrated siloxane supply chains that control raw material cost volatility for sealant production.
Elastic bonding adhesive and sealant denotes a class of polymeric materials formulated with elongation-at-break exceeding 100 percent, typically comprising silane-terminated polyethers, polyurethanes, or silyl-modified polymers cured via moisture-crosslinking mechanisms; these formulations absorb dynamic stresses across dissimilar substrates while maintaining cohesive strength in joints subject to thermal cycling, vibration, or structural movement. Polyurethane formulations lead volume in automotive applications where crash-resistant bonding of mixed-material body-in-white assemblies commands premium pricing, while silicone dominates construction facade sealing given its UV stability and 50-year service life ratings. Acrylate segments occupy faster-growing renovation and DIY channels where water-based delivery modes reduce application complexity for non-professional end users.
EPA VOC regulations under 40 CFR Part 59 constrain architectural sealant formulations in the United States, while REACH Annex XVII restrictions on isocyanate content reshape polyurethane product development across Europe. ECHA classification of certain siloxanes as substances of very high concern is forcing reformulation investments among manufacturers serving electronics and medical device bonding applications. Stakeholders must monitor evolving substance restrictions and decide between proactive reformulation or geographic portfolio rebalancing before compliance deadlines tighten market access.
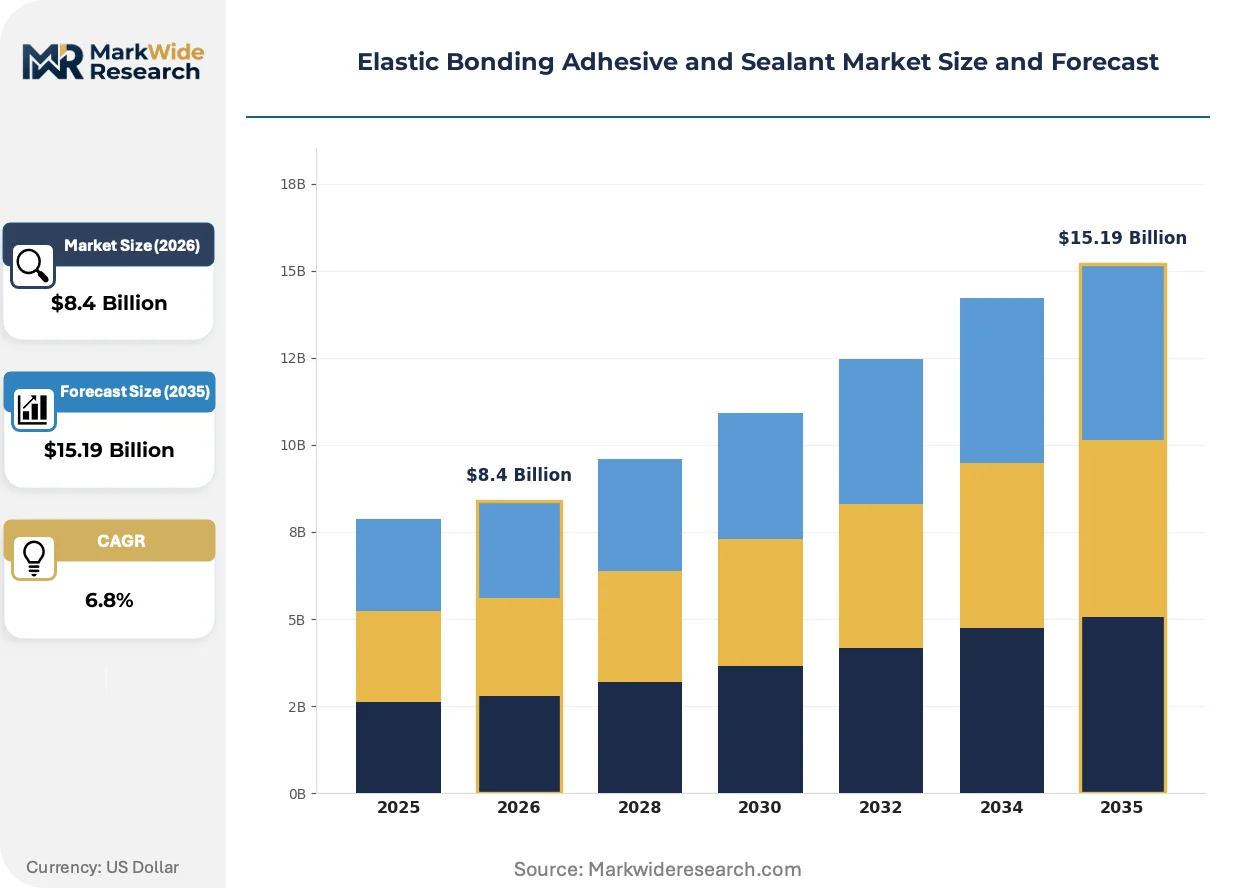
Market Dynamics
REACH Annex XVII restrictions on isocyanate content and EPA 40 CFR Part 59 VOC thresholds are forcing simultaneous reformulation across polyurethane and silicone product lines, compressing R&D timelines while elevating compliance costs as a competitive filter.
Growth Catalysts
- Lightweight Vehicle Assembly Mandates:Automotive OEMs in Germany are accelerating polyurethane-based elastic bonding for mixed-material body-in-white construction to meet fleet emission targets.
- REACH Compliance Deadlines:Tightening VOC emission thresholds across Europe are disqualifying solvent-based alternatives and redirecting specification authority toward compliant formulation suppliers.
- Electronics Manufacturing Clusters:China's eastern manufacturing corridor is driving bulk procurement of silicone and acrylate formulations for device assembly and protection.
Market Restraints
- Siloxane Feedstock Concentration:Integrated siloxane supply chains controlled by a limited set of chemical conglomerates create input cost volatility for non-integrated sealant manufacturers.
- ECHA SVHC Classification:Certain cyclic siloxanes designated as substances of very high concern are forcing costly reformulation in electronics and medical device bonding segments.
- Acrylate Performance Ceiling:Water-based acrylate formulations face durability limitations in exterior facade applications where 50-year service life ratings are specified.
Strategic Opportunities
- Renovation Channel Expansion:DIY and professional renovation segments in France and Italy present underpenetrated demand for water-based acrylate systems with reduced application complexity.
- EU Green Deal Procurement Mandates:Public infrastructure projects are embedding low-carbon material specifications that favor silyl-modified polymer formulations with reduced petrochemical content.
- Medical Device Convergence:Combination product regulations are creating specification windows for biocompatible elastic bonding in wearable diagnostic assemblies.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Moisture-cure polymer expertise sits concentrated among aging specialist chemists, constraining R&D velocity for mid-tier manufacturers.
- Dual Certification Timelines:Simultaneous EPA and ECHA compliance pathways for new formulations extend commercialization cycles by 18-24 months.
- Legacy Equipment Retrofit Costs:Automotive assembly lines require capital-intensive tooling modifications to accommodate new adhesive rheology profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastic Bonding Adhesive and Sealant Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylate, Epoxy Application: Construction, Automotive, Electronics, Aerospace End User: Manufacturers, Contractors, DIY Consumers, Distributors Delivery Mode: Tube, Cartridge, Bulk, Spray |
| Companies Covered | Dow, Wacker Chemie AG, Henkel Corporation, Sika AG, H.B. Fuller, 3M Company, Arkema S.A., Threebond Group, Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastic Bonding Adhesive and Sealant Market Shifts & Advancements
Silyl-modified polymer platforms are fragmenting traditional technology boundaries between polyurethanes and silicones, enabling hybrid formulations that trade off cost against performance in application-specific ways.
Silane-terminated polyether technology is modularizing adhesive system architecture by separating base polymer properties from cure kinetics and adhesion promotion functions. Tier-one automotive suppliers in Stuttgart and Wolfsburg are adopting these platforms to standardize inventory while customizing performance through additive packages. This modularity is compressing formulation development cycles and enabling rapid regional specification adjustments without polymer plant retooling.
EPA 40 CFR Part 59 architectural sealant regulations are tightening VOC content ceilings and expanding testing protocols for commercial construction applications. Formulators serving the US market are eliminating aromatic solvent carriers and accelerating water-borne polyurethane development. The specification community is responding by elevating certified low-VOC products to preferred status in federal and state-funded infrastructure projects.
Buyer consolidation among European construction distributors is compressing supplier negotiation cycles and unbundling technical service from material procurement. Large merchant distributors in the DACH region are displacing traditional manufacturer-direct relationships with private-label sourcing and centralized specification influence. This channel restructuring is most visible in commercial facade projects where distributor certification programs now gate access to project bid lists.
Elastic Bonding Adhesive and Sealant Market Segmentation
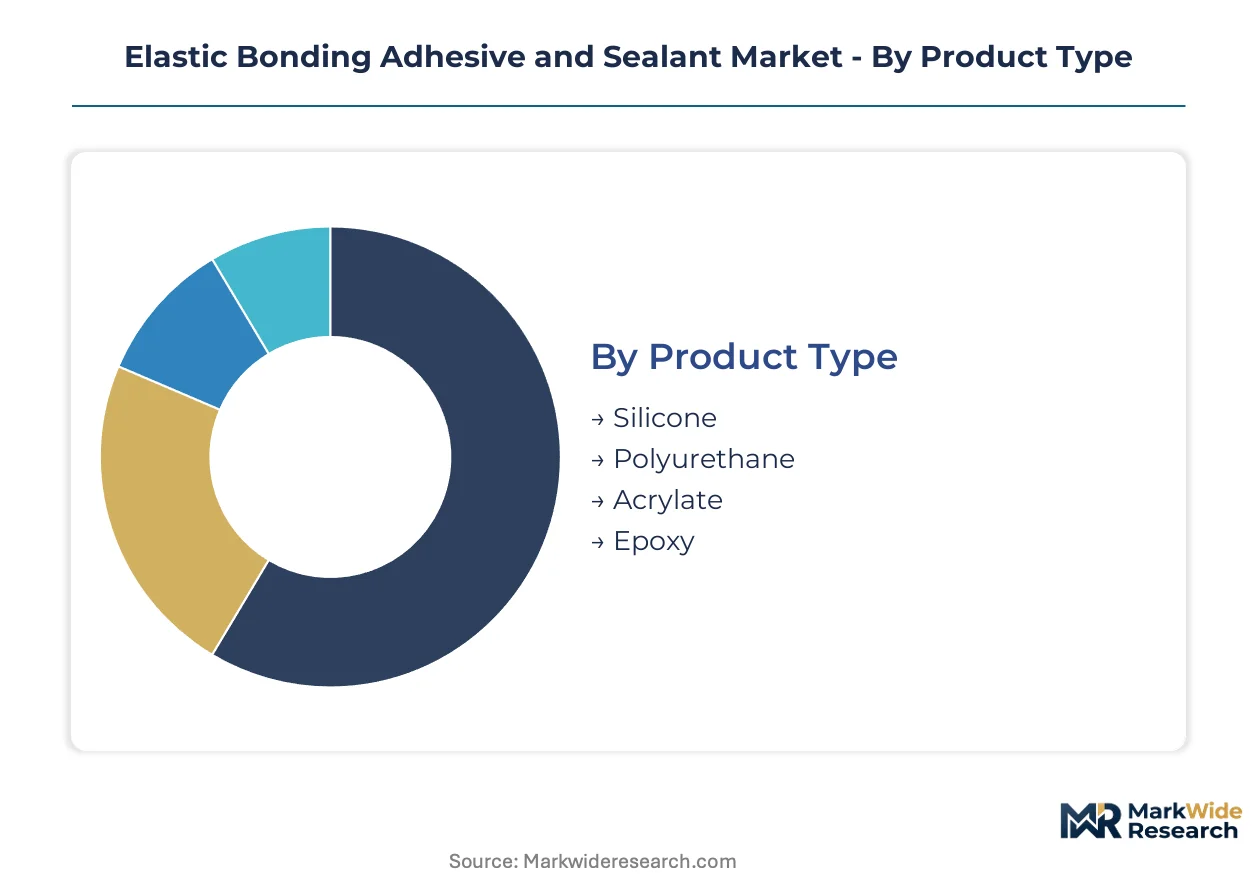
Elastic bonding adhesive and sealant formulations diverge sharply in performance economics across substrates and cure mechanisms. Specification authority flows differently through construction tender processes versus automotive tier-one supply chains versus electronics contract manufacturing.
Product Type:
Buyers in this category differentiate primarily by thermal stability requirements and environmental compliance exposure rather than unit cost.
- Silicone:Formulated from siloxane backbones with moisture-cure crosslinking delivering UV resistance and 50-year service life ratings. Demand concentrates in German and Chinese construction facade sealing where REACH VOC thresholds and GB standards disqualify solvent-bearing alternatives.
- Polyurethane:Isocyanate-terminated prepolymers cure through atmospheric moisture to form elastomeric bonds with high cohesive strength. German automotive OEMs in Stuttgart and Wolfsburg specify these for mixed-material body-in-white assembly to meet fleet emission mandates.
- Acrylate:Water-borne emulsions with free-radical cure mechanisms serve renovation channels where application complexity must remain minimal for non-professional users.
- Epoxy:Two-part thermoset systems with rigid cure profiles occupy structural anchoring applications where elongation requirements fall below elastic bonding thresholds.
Volume sits with silicone; growth tilts toward polyurethane as automotive lightweighting mandates expand.
Application:
Application selection tracks capital intensity of the downstream assembly process and the cost of bond failure.
- Construction:Facade sealing, structural glazing, and expansion joint filling across commercial and residential builds. Specification authority in Germany and France flows through distributor certification programs that gate project bid access.
- Automotive:Direct glazing, body-in-white bonding, and trim attachment where crash-resistant adhesion commands premium positioning. Stuttgart-based tier-one suppliers standardize on modular silane-terminated polyether platforms to compress inventory SKUs.
- Electronics:Device assembly, conformal coating, and display bonding in China's eastern manufacturing corridor where bulk procurement concentrates.
- Aerospace:Fuel tank sealing, cabin pressure boundary maintenance, and composite primary structure bonding subject to FAA and EASA certification timelines.
Construction commands installed volume; electronics represents the steepest expansion trajectory as device manufacturing migrates toward bonded architectures.
End User:
End user type determines technical service intensity and pricing power distribution in the channel.
- Manufacturers:Automotive OEMs and electronics contract manufacturers with in-house formulation testing capabilities and long-term supply agreements.
- Contractors:Professional installation firms in commercial construction where distributor relationships and specification influence determine material selection.
- DIY Consumers:Residential renovation participants in France and Italy driving water-based acrylate demand through retail hardware channels.
- Distributors:Merchant distributors in the DACH region consolidating procurement and displacing manufacturer-direct relationships with private-label sourcing.
Manufacturers capture value through specification lock-in; distributors are gaining share fastest via channel consolidation.
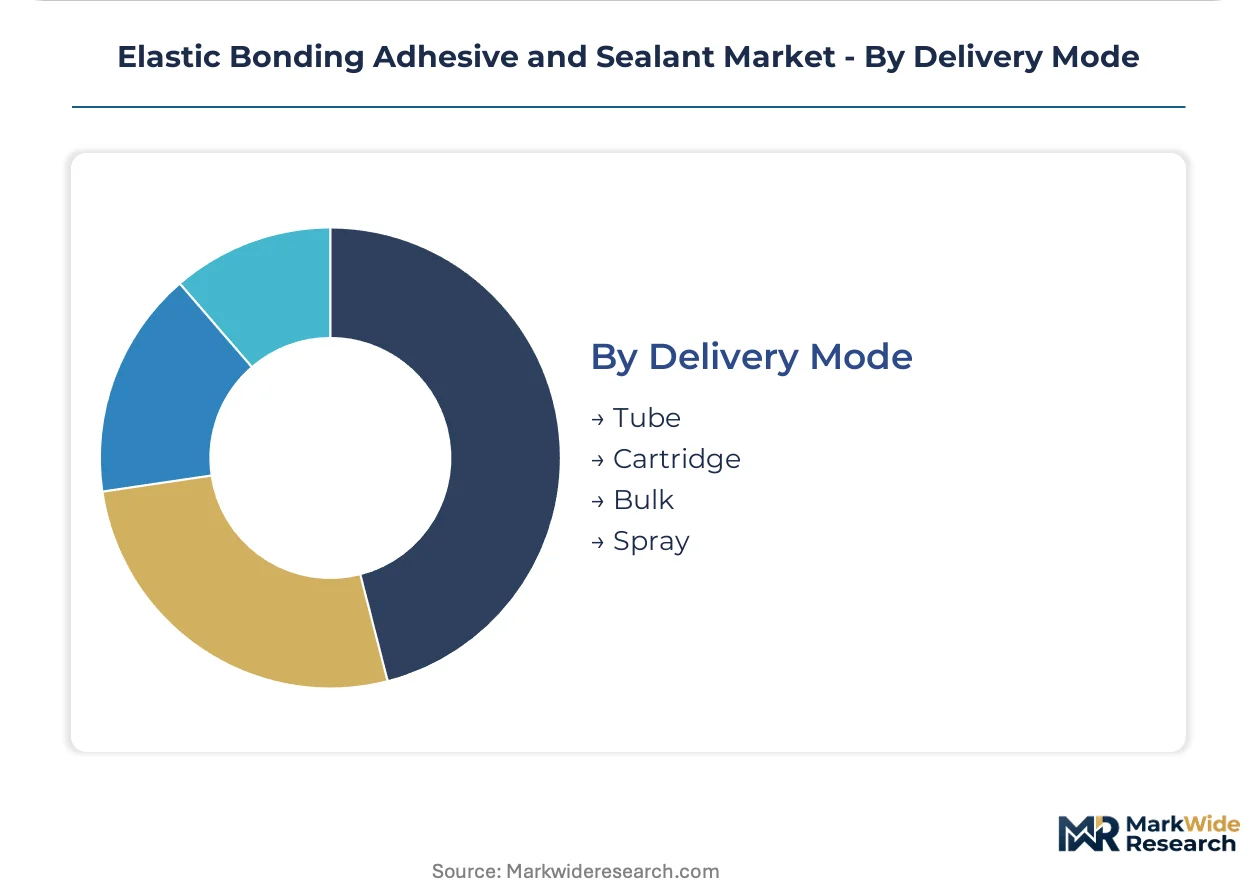
Delivery Mode:
Delivery format selection reflects scale economics and application equipment capital requirements.
- Tube:Small-format packaging for DIY and spot repair applications where per-unit convenience outweighs bulk pricing.
- Cartridge:Standard 310ml and 600ml formats compatible with manual and pneumatic caulking guns across professional construction.
- Bulk:Drum and tote deliveries to automotive assembly lines and electronics manufacturing facilities with automated dispensing systems.
- Spray:Aerosol and pump-spray formats for conformal coating and large-area coverage in specialty industrial applications.
Bulk deliveries dominate automotive and electronics procurement; cartridge formats maintain construction channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor functions as a special economic zone magnet for elastic bonding procurement. Germany's automotive belt concentrates polyurethane specification authority. The United States enforces VOC thresholds that reshape formulation economics.
China
Electronics contract manufacturers in Suzhou and Shenzhen drive bulk silicone procurement for device assembly. GB standards on VOC emissions tighten formulation requirements for construction sealants. The Yangtze River Delta anchors acrylate demand from renovation contractors serving residential retrofit markets.
Germany
Stuttgart and Wolfsburg automotive OEMs specify polyurethane systems for mixed-material body-in-white bonding. REACH Annex XVII isocyanate restrictions compress R&D timelines for compliant formulations. The DACH distribution corridor consolidates procurement influence through merchant distributor certification programs.
United States
EPA 40 CFR Part 59 architectural sealant regulations eliminate aromatic solvent carriers from commercial construction specifications. Federal infrastructure procurement elevates certified low-VOC products to preferred status. The Southeast automotive assembly belt retools lines for new adhesive rheology profiles.
Japan
METI carbon neutrality roadmaps accelerate lightweight vehicle assembly mandates for elastic bonding adoption. JIS standards on sealant durability reshape specification criteria for facade applications. The Kansai industrial corridor concentrates electronics manufacturing demand for conformal coating formulations.
India
PLI scheme incentives for electronics manufacturing attract silicone and acrylate procurement to contract assembly facilities. BIS certification requirements extend commercialization timelines for imported formulations. The Delhi-Mumbai Industrial Corridor anchors construction sealant demand from commercial infrastructure projects.
Elastic Bonding Adhesive and Sealant Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates commanding raw material supply chains while formulation specialists dominate specification-intensive applications. The vendor base organizes around three archetypes: siloxane-integrated producers controlling feedstock economics, automotive-facing specialists leveraging OEM relationships, and construction-channel players building distributor certification networks. M&A activity concentrates among mid-tier manufacturers seeking geographic coverage, while technology licensing agreements accelerate silyl-modified polymer platform adoption.
Within the integrated producer tier, Dow and Wacker Chemie AG occupy positions defined by captive siloxane supply chains. Henkel Corporation and Sika AG exemplify specification-locked specialists with entrenched automotive and construction channel relationships. These four anchors represent divergent competitive vectors: feedstock control versus formulation expertise versus distributor network depth.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Henkel Corporation |
| Sika AG |
| H.B. Fuller |
| 3M Company |
| Arkema S.A. |
| Threebond Group |
| Kaneka Corporation |
| Others |
Supply & Pricing Matrix
Captive siloxane production anchors both supply security and margin protection for integrated chemical conglomerates serving sealant markets. Dow and Wacker Chemie AG leverage backward integration into siloxane monomers to buffer formulation divisions from raw material volatility while commanding premium positioning in specification-intensive automotive and electronics segments.
Pricing Analysis
Volume concentrates in bulk polyurethane deliveries to German automotive assembly lines where long-term offtake agreements stabilize unit economics; margins concentrate in silicone formulations for construction facade sealing where REACH compliance certification and 50-year service life ratings justify premium positioning. Price differentiation separates REACH-certified formulations from commodity alternatives, with distributor certification programs in the DACH region gating access to project bid lists. Cost compression in water-based acrylate segments is intensifying as DIY channel competition expands in France and Italy. Small-format cartridge buyers in renovation channels exhibit highest price sensitivity; automotive OEMs with specification lock-in demonstrate lowest sensitivity.
Supply Chain Analysis
Freight costs from German chemical manufacturing clusters to Chinese electronics assembly corridors shape regional pricing spreads for silicone formulations. Raw material supply concentrates in Germany, China, and the United States, with siloxane feedstock anchored in the Rhine-Ruhr chemical belt and Yangtze River Delta manufacturing zones. Formulation chemistry draws from isocyanate precursors, silane coupling agents, and polyether polyols. Single-source vulnerability sits with cyclic siloxane feedstocks designated as substances of very high concern under ECHA classification. Distribution runs through merchant distributors in the DACH region consolidating procurement influence via private-label sourcing and centralized specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as mid-tier manufacturers pursue captive siloxane supply or downstream specification lock-in to defend margin erosion from feedstock volatility and compliance cost compression.
For Market Incumbents: Hedge against ECHA SVHC reformulation mandates by accelerating silyl-modified polymer platform investments before compliance deadlines tighten market access. Deepen automotive OEM relationships through modular silane-terminated polyether inventory standardization that compresses customer switching costs. Acquire regional formulation specialists in China's eastern manufacturing corridor to secure electronics contract manufacturing procurement channels before distributor consolidation forecloses direct access. For New Entrants and Emerging Players: DIY renovation contractors in France and Italy represent an underserved buyer archetype with fragmented procurement and minimal specification loyalty. Target water-based acrylate formulations with simplified application protocols that reduce technical service intensity. Pursue private-label partnerships with consolidating merchant distributors in the DACH region to bypass capital-intensive specification development cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier manufacturers with regional formulation expertise but lacking captive feedstock supply. Long-term viability favors targets with established distributor certification networks and automotive OEM qualification status. Watch ECHA substance restriction announcements as inflection indicators for reformulation investment cycles and portfolio rebalancing pressures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Dow's captive siloxane supply chains insulate margin structures from raw material volatility in sealant production. |
| Modular Platform Standardization | Silane-terminated polyether architecture enables Stuttgart-based tier-one suppliers to compress inventory SKUs while customizing performance. |
| Distributor Certification Program Expansion | Sika AG's merchant distributor networks in the DACH region gate project bid access and displace manufacturer-direct relationships. |
| REACH Compliance Reformulation Investment | Proactive isocyanate-content reduction ahead of Annex XVII deadlines preserves market access across European construction segments. |
| Electronics Manufacturing Cluster Proximity | Bulk procurement concentration in Suzhou and Shenzhen anchors silicone and acrylate demand for device assembly applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with automotive OEM procurement leads, construction distributor category managers, formulation R&D directors, and electronics contract manufacturing supply chain heads validated demand assumptions. ECHA restriction proposals, EPA 40 CFR Part 59 compliance databases, and GB standards documentation provided regulatory trajectory inputs. Bottom-up volume modeling across product type, application, and delivery mode dimensions triangulated against top-down chemical industry production aggregates.
Granularity-level modeling tracked silicone, polyurethane, acrylate, and epoxy formulations separately by cure mechanism and substrate compatibility. Automotive applications disaggregated by body-in-white bonding, direct glazing, and trim attachment; construction applications by facade sealing, structural glazing, and expansion joint filling. CAGRs derived from elasticity-adjusted demand curves incorporating fleet emission mandates, REACH compliance deadlines, and electronics manufacturing migration patterns across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction expansions, automotive lightweighting mandate accelerations, and distributor consolidation trajectories in European construction channels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Tile Adhesive Market