
 Optically Clear Adhesives Market | 2026-2036
Optically Clear Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Optically Clear Adhesives Market Intelligence
Modular display bonding kits are pivoting how panel assemblers procure optically clear adhesives, shifting from bulk resin contracts to pre-measured, substrate-specific modules. 3M Company leverages its film adhesive portfolio to dominate the display lamination tier. Henkel AG & Co. KGAA sustains R&D intensity in UV curing chemistries for automotive touchscreens. Dow Inc. anchors silicone adhesive supply for optical encapsulation in medical imaging devices.
Optically clear adhesives are transparent bonding formulations, typically acrylic or silicone-based, engineered to transmit over 90 percent of visible light while eliminating refractive index mismatch between substrates. These adhesives cure via UV, heat, or moisture mechanisms to deliver permanent optical coupling in display stacks, sensor windows, and lens assemblies. UV curing adhesives occupy the premium tier due to their rapid processing and low yellowing index in electronics applications. Acrylic adhesives compete aggressively on cost in automotive infotainment bonding, while silicone adhesives capture margin pools in medical optical encapsulation where biocompatibility standards are stringent. Film adhesives lead the technology dimension for high-volume display lamination, whereas liquid adhesives dominate precision coating in optical device manufacturing.
FDA biocompatibility requirements govern medical adhesive formulations, while REACH and RoHS frameworks in Europe restrict hazardous substance content in electronics-grade products. EPA regulations in the United States shape volatile organic compound limits for adhesive manufacturing facilities. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or region-specific product lines offer superior compliance economics.
Market Dynamics
Automotive OEMs are consolidating display real estate behind single curved glass surfaces, forcing adhesive suppliers to engineer formulations that bond dissimilar substrates under thermal cycling stress without optical degradation.
Growth Catalysts
- Automotive display bonding:OEM integration of pillar-to-pillar screens in electric vehicles is pulling UV-curable acrylic formulations into high-volume production lines.
- REACH compliance deadlines:ECHA restrictions on halogenated flame retardants are accelerating reformulation of electronics-grade adhesives toward silicone-urethane hybrids.
- China panel manufacturing:Domestic OLED and LCD fabs in Shenzhen and Hefei are scaling captive adhesive consumption, compressing import dependency.
Market Restraints
- Silicone feedstock volatility:Precipitated silica and silane monomer prices fluctuate with energy costs in Zhejiang province, squeezing margin pools for optical-grade silicone adhesives.
- UV initiator supply concentration:Photoinitiator production clusters in Germany and Japan create single-source vulnerability for rapid-cure electronics formulations.
- Refractive index matching limits:Acrylic adhesives cannot achieve the sub-0.001 delta-n precision required for automotive head-up display waveguides, ceding that tier to specialty epoxies.
Strategic Opportunities
- India display assembly:PLI scheme incentives for mobile phone manufacturing in Noida and Chennai are creating first-mover openings for localized adhesive kit suppliers.
- Medical optical encapsulation:FDA biocompatibility pathways for Class II diagnostic imaging devices are opening margin-rich niches for platinum-cure silicone adhesives.
- Modular bonding kits:Pre-measured, substrate-specific adhesive modules are displacing bulk resin contracts in Korean panel assembly lines, enabling just-in-time procurement.
Industry Challenges
- Optical metrology talent scarcity:Formulation chemists with dual expertise in polymer rheology and interferometric testing command premium compensation, constraining R&D scaling.
- ISO 10993 certification timelines:Medical adhesive qualification cycles extend 18-24 months, locking working capital and delaying revenue recognition.
- Legacy solvent-based inventory:EPA VOC enforcement is forcing manufacturers to absorb write-downs on non-compliant acrylic stockpiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optically Clear Adhesives Market |
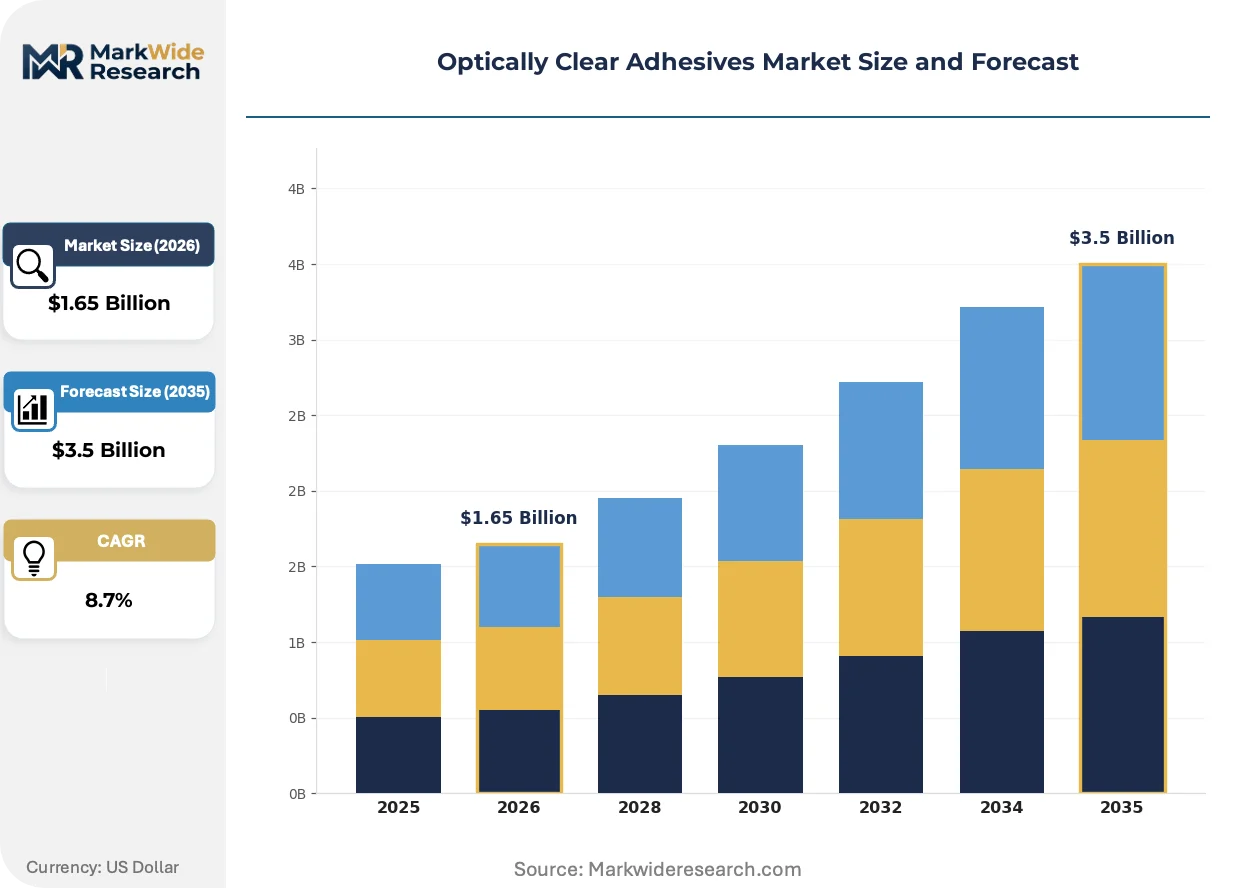
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.5 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Curing Adhesives, Epoxy Adhesives, Acrylic Adhesives, Silicone Adhesives End Use Industry: Electronics, Automotive, Optical Devices, Medical Application: Bonding, Coating, Encapsulation, Sealing Technology: Liquid Adhesives, Film Adhesives, Pressure Sensitive Adhesives, Hot Melt Adhesives |
| Companies Covered | 3M Company, Henkel AG & Co. KGAA, Dow Inc., Nitto Denko Corporation, Lintec Corporation, Dymax Corporation, Delo Industrial Adhesives LLC, H.B. Fuller Company, Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optically Clear Adhesives Market Strategic Shifts & Innovations
Formulation chemistry and procurement architecture are undergoing simultaneous transformation, with curing mechanisms and supply contracts both compressing toward faster, more standardized execution.
UV-LED curing systems are consolidating control over high-throughput display lamination. These systems replace mercury arc lamps with semiconductor emitters at 365 nm and 395 nm wavelengths, cutting energy consumption and eliminating warm-up delays. Korean and Chinese panel fabs are retrofitting existing lines at pace, compressing the installed base of thermal-cure equipment and forcing adhesive suppliers to reformulate around narrower spectral windows.
REACH authorization requirements for Substances of Very High Concern are tightening purity specifications for optical adhesives sold into European electronics supply chains. ECHA's 2024 updates to candidate list screening now capture residual monomers below 0.1 percent thresholds, compelling formulators to invest in supercritical CO2 extraction for acrylic purification. Medical device manufacturers in Germany and France are responding by dual-qualifying silicone alternatives to hedge against supply interruption.
Automotive Tier 1 suppliers are unbundling adhesive procurement from display module contracts, creating direct purchasing relationships with specialty chemical firms. This disintermediation strips margin from systems integrators and exposes adhesive makers to annual price renegotiation cycles. The pattern is most visible in Bavaria and Baden-Württemberg, where BMW and Mercedes-Benz purchasing teams are consolidating vendor lists for curved screen bonding programs.
Optically Clear Adhesives Market Segmentation
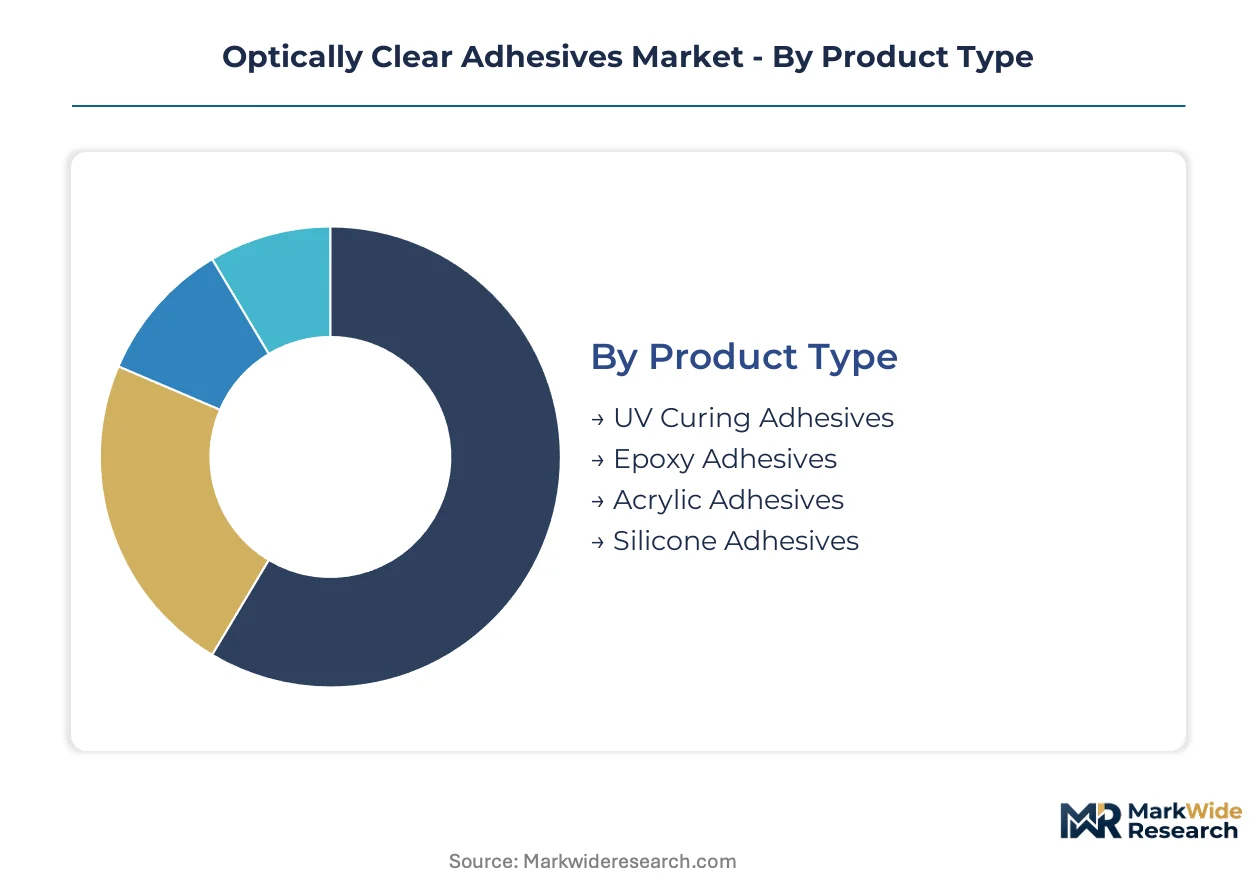
Optically clear adhesives fragment across curing chemistry, substrate compatibility, and processing speed requirements. Each segmentation axis reveals distinct margin pools and technical barriers that determine supplier positioning across electronics, automotive, and medical end-uses.
Product Type:
Volume concentrates in fast-cure acrylics for display lamination, while premium pricing attaches to precision-cure formulations for optical waveguides.
- UV Curing Adhesives:These formulations incorporate photoinitiators activated at 365-405 nm wavelengths, enabling sub-30-second cure cycles in high-throughput panel lines. Korean and Chinese display fabs in Gumi and Suzhou are standardizing UV-curable acrylic platforms for OLED bonding, driven by pillar-to-pillar automotive screen demand.
- Silicone Adhesives:Platinum-cure and condensation-cure silicones deliver thermal stability from -50°C to 200°C with refractive indices tunable to 1.41-1.43. Medical device manufacturers in Germany and Massachusetts specify these for endoscope lens encapsulation, constrained by ISO 10993-5 cytotoxicity testing timelines.
- Acrylic Adhesives:Cost-optimized formulations dominate automotive infotainment bonding where optical clarity requirements are less stringent than medical applications.
- Epoxy Adhesives:High Tg thermosets capture aerospace and military optical assemblies requiring resistance to thermal cycling stress.
Today's leader: UV Curing Adhesives. Tomorrow's challenger: Silicone Adhesives.
End Use Industry:
Application maturity separates established electronics demand from emerging medical volume.
- Electronics:Smartphone, tablet, and monitor display stacks consume the majority of optically clear adhesive volume, with bonding layers between cover glass and touch sensors representing standard procurement.
- Automotive:Curved instrument panels and head-up displays in electric vehicles from Bavaria to California are pulling specialized low-outgassing formulations into qualification cycles.
- Medical:Diagnostic imaging devices and surgical cameras require biocompatible encapsulants meeting FDA and EMA pathways, with qualification cycles extending 18-24 months.
- Optical Devices:Camera modules, LiDAR sensors, and AR/VR headsets demand sub-0.001 refractive index matching precision.
Electronics commands current volume. Medical offers the steepest expansion trajectory.
Application:
Functional requirements split between structural bonding and protective encapsulation.
- Bonding:Lamination of dissimilar substrates—glass to plastic, glass to metal—drives the majority of adhesive consumption in consumer electronics assembly.
- Encapsulation:Complete optical isolation of sensitive components from moisture and mechanical shock, critical for medical endoscopes and automotive LiDAR modules.
- Coating:Thin-film application for anti-reflective and protective optical surfaces in precision instruments.
- Sealing:Perimeter sealing of display modules and sensor housings against environmental ingress.
Bonding anchors present revenue. Encapsulation is gaining share fastest.
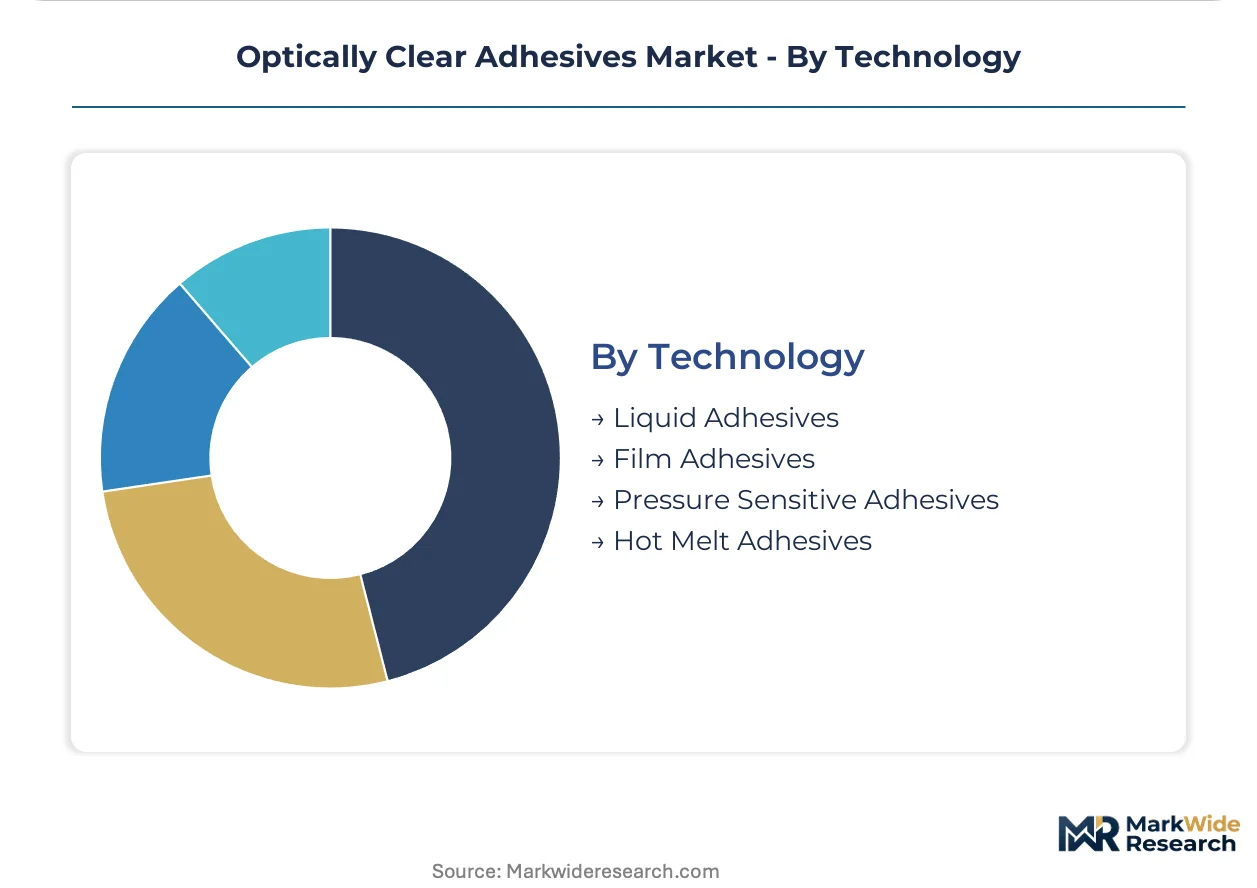
Technology:
Form factor determines equipment compatibility and processing economics.
- Film Adhesives:Pre-cast sheets with controlled thickness enable cleanroom-friendly lamination without dispensing equipment, dominating Korean and Chinese panel fab lines.
- Liquid Adhesives:Precision dispensing systems allow variable thickness and complex geometries for optical device manufacturing.
- Pressure Sensitive Adhesives:Room-temperature tack enables repositioning during assembly, common in prototype and repair applications.
- Hot Melt Adhesives:Thermoplastic formulations offer reworkability and rapid processing for cost-sensitive consumer goods.
Film Adhesives lead display integration. Liquid Adhesives challenge in precision optics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optically clear adhesive manufacturing first scaled in Japan and Germany during the 1990s display revolution, then migrated production gravity toward Korean and Chinese panel ecosystems. Today's demand geography reflects that lineage: East Asian fabs consume the majority of volume, while European and North American markets anchor premium formulation development.
China
Domestic OLED and LCD manufacturers in Shenzhen and Hefei are scaling captive adhesive consumption for display lamination. MIIT's GB standards for electronic materials are tightening purity specifications for imported formulations. The Yangtze River Delta cluster around Suzhou hosts the highest concentration of optical-grade silicone adhesive blending facilities.
South Korea
Display panel producers in Gumi and Paju are standardizing UV-curable acrylic platforms for automotive screen bonding. The country's national technology regulator aligns adhesive qualification protocols with automotive OEM requirements. Seoul Capital Area headquarters anchor R&D investment in next-generation film adhesive technologies.
Germany
Automotive Tier 1 suppliers in Bavaria and Baden-Württemberg are consolidating vendor lists for curved instrument panel programs. ECHA's REACH authorization requirements are accelerating reformulation toward silicone-urethane hybrids. The Stuttgart industrial corridor concentrates precision dispensing equipment manufacturing for adhesive application systems.
United States
Medical device manufacturers in Massachusetts and Minnesota are qualifying platinum-cure silicones for diagnostic imaging encapsulation. FDA biocompatibility pathways under ISO 10993 govern 18-24 month qualification cycles. The Pacific Northwest hosts specialty chemical R&D focused on low-outgassing formulations for aerospace optical assemblies.
Japan
Camera module and LiDAR sensor producers in the Chubu region around Nagoya demand sub-0.001 refractive index matching precision. METI's industrial standards for optical materials influence regional procurement specifications. The Kansai corridor around Osaka maintains legacy expertise in epoxy-based precision bonding for military optical systems.
Optically Clear Adhesives Market Key Industry Players
The competitive structure tilts toward diversified materials conglomerates with film adhesive portfolios. Three to five multinational chemical groups control the majority of formulated product supply, while mid-scale specialists occupy niche curing chemistry segments. Strategic archetypes separate film-based display laminators from liquid precision coaters and medical-grade silicone formulators. Capacity expansion and strategic partnerships dominate competitive moves, with Korean and Chinese panel fabs driving co-development relationships.
Among diversified materials conglomerates, 3M Company and Henkel AG & Co. KGAA represent the film adhesive and UV curing archetypes respectively, while Dow Inc. anchors the silicone formulation tier. These three entities exemplify how scale-driven players occupy distinct technology vectors without direct product overlap. Nitto Denko Corporation and Lintec Corporation sit within the Japanese specialist tier, reflecting geographic concentration in precision film manufacturing. Dymax Corporation and Delo Industrial Adhesives LLC occupy positions in the mid-scale UV curing segment, illustrating how regional specialists maintain relevance through application-specific expertise rather than portfolio breadth.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGAA |
| Dow Inc. |
| Nitto Denko Corporation |
| Lintec Corporation |
| Dymax Corporation |
| Delo Industrial Adhesives LLC |
| H.B. Fuller Company |
| Tesa SE |
| Others |
Cost & Logistics Intelligence
Automotive OEM consolidation of curved display procurement is forcing adhesive suppliers to absorb qualification costs while maintaining optical-grade purity standards, compressing margin pools for non-specialized formulators. This buyer-driven specification tightening is reshaping how suppliers structure volume commitments and regional pricing.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Korean panel fabs and adhesive suppliers, with pricing stratifying across medical-grade silicone, automotive UV-acrylic, and economy display film tiers. Price differentiation centers on ISO 10993 certification status and REACH Substances of Very High Concern compliance, with uncertified formulations facing cost compression from EPA VOC enforcement. Price erosion runs through standard display grades as Chinese domestic blending capacity expands. Tier 1 automotive suppliers exhibit lowest price sensitivity due to liability exposure, while consumer electronics assemblers prioritize unit cost reduction.
Supply Chain Analysis
Dual-sourcing mandates from BMW and Mercedes-Benz purchasing teams in Bavaria are compelling adhesive suppliers to qualify secondary photoinitiator streams beyond German and Japanese production clusters. Geographic supply concentration centers on China for precipitated silica and silane monomers, Germany for precision dispensing equipment, and South Korea for UV-curable acrylic resin blending. Raw material dependencies include silane monomers, photoinitiators, and optical-grade acrylic polymers. Single-source vulnerability in photoinitiator supply creates qualification bottlenecks for rapid-cure formulations. Distribution runs through direct relationships with panel fabs and automotive Tier 1 suppliers, displacing systems integrator intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in optically clear adhesives rests on medical-grade silicone certification premiums and the shift toward pre-measured modular bonding kits that capture value from bulk resin commoditization.
For Market Incumbents: Anticipate REACH authorization expansion for residual monomer thresholds by investing in supercritical CO2 extraction capacity for acrylic purification in European blending facilities. Defend margin position through backward integration into photoinitiator supply relationships and captive silicone polymer production in Zhejiang province. Prioritize ISO 10993-5 cytotoxicity pre-certification for platinum-cure platforms to shorten medical device qualification cycles. For New Entrants and Emerging Players: Enter via India's PLI scheme mobile phone manufacturing clusters in Noida and Chennai, where localized adhesive kit supply remains underdeveloped relative to assembly capacity expansion. Target medical optical encapsulation for diagnostic imaging devices, where 18-24 month qualification cycles deter incumbent reallocation from display volumes. Pursue co-development partnerships with emerging panel fabs rather than spot supply relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale silicone formulators possessing FDA master file documentation and untapped capacity for platinum-cure expansion. Long-term viability favors specialists with dual competence in polymer rheology and interferometric testing, as optical metrology talent scarcity constrains R&D scaling across the analysis window. Monitor ECHA candidate list updates for Substances of Very High Concern as inflection indicators for reformulation-driven supply disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Reduces single-source vulnerability from German and Japanese production concentration. |
| Supercritical CO2 Extraction Capacity Addition | Enables REACH compliance for residual monomer thresholds in European electronics supply chains. |
| ISO 10993-5 Pre-Certification Investment | Compresses medical device qualification timelines from 18-24 months toward competitive benchmarks. |
| Modular Bonding Kit Product Launch | Captures procurement shift from bulk resin contracts to just-in-time substrate-specific modules in Korean panel lines. |
| Joint Venture with India PLI Scheme Beneficiaries | Establishes localized supply position in Noida and Chennai mobile phone assembly clusters. |
Research Approach
Coverage spans East Asian panel manufacturing clusters, European automotive supply corridors, and North American medical device production hubs, with primary inputs from each. Formulation chemists, automotive Tier 1 procurement directors, and biomedical engineers at diagnostic imaging manufacturers provided qualitative inputs through structured interviews. Secondary validation drew from ECHA REACH authorization databases, FDA 510(k) filings for adhesive-containing devices, MIIT GB standards documentation, and SEC filings of diversified materials conglomerates. Bottom-up volume estimates from substrate-level consumption combined with top-down market sizing from chemical trade associations.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion through price-mix effects. Segmentation dimensions modeled include curing chemistry, end-use industry, application function, and technology form factor, with additional granularity on regulatory compliance tier. CAGRs were derived from fitted trend extrapolation against historical capacity utilization and announced fab expansion schedules. Forecast inputs incorporated UV-LED curing line retrofit timelines in Korean and Chinese panel facilities and ECHA candidate list revision schedules.
Inputs from FDA pre-submission meetings and ECHA stakeholder consultations were available through the study window; gaps in real-time photoinitiator inventory data introduce uncertainty bands around rapid-cure formulation supply assumptions. Deviation in REACH authorization timelines or UV-LED equipment deployment rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
South America Reactive Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Spray Glue Market