
 Asia-Pacific Contact Adhesives Market | 2026-2036
Asia-Pacific Contact Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Contact Adhesives Market Outlook
Multi-source procurement among Asia-Pacific contact adhesives buyers is broadening as manufacturers diversify supply risk across domestic and international resin suppliers. Henkel AG & Co. KGaA anchors its position through deep distribution networks across Southeast Asian manufacturing hubs. Sika AG competes on construction-specialized formulations that serve high-rise building projects from Singapore to Sydney. Pidilite Industries Ltd. dominates India's domestic market through brand strength in woodworking and decorative applications.
Asia-Pacific contact adhesives comprise synthetic polymer systems—typically neoprene rubber, polyurethane prepolymers, or acrylic dispersions dissolved or dispersed in solvent or water carriers—that cure through solvent evaporation to form flexible, high-tack bonds between substrates. These formulations achieve immediate handling strength without clamping, making them essential for bonding decorative laminates, automotive interior trim, and shoe sole attachment where production speed matters. Rubber-based formulations retain the largest volume share across the region due to their proven performance in furniture lamination and footwear assembly, though water-based polyurethane systems are gaining fastest as environmental compliance tightens. Solvent-based products still command premium pricing in automotive OEM specifications where heat resistance and bond durability are non-negotiable, while hot melt contact adhesives occupy a narrowing niche in packaging and textile applications.
China's MEE enforces GB standards limiting VOC emissions from adhesive formulations, pushing manufacturers toward water-based and reactive system development. India's BIS certification requirements for construction chemicals create compliance barriers that favor established domestic producers with testing infrastructure. Japan's METI oversees chemical substance reporting under its industrial safety framework, affecting import protocols for foreign adhesive suppliers. Stakeholders must monitor how REACH-aligned regulatory convergence across ASEAN trading partners reshapes formulation portfolios and local production licensing requirements.
Market Dynamics
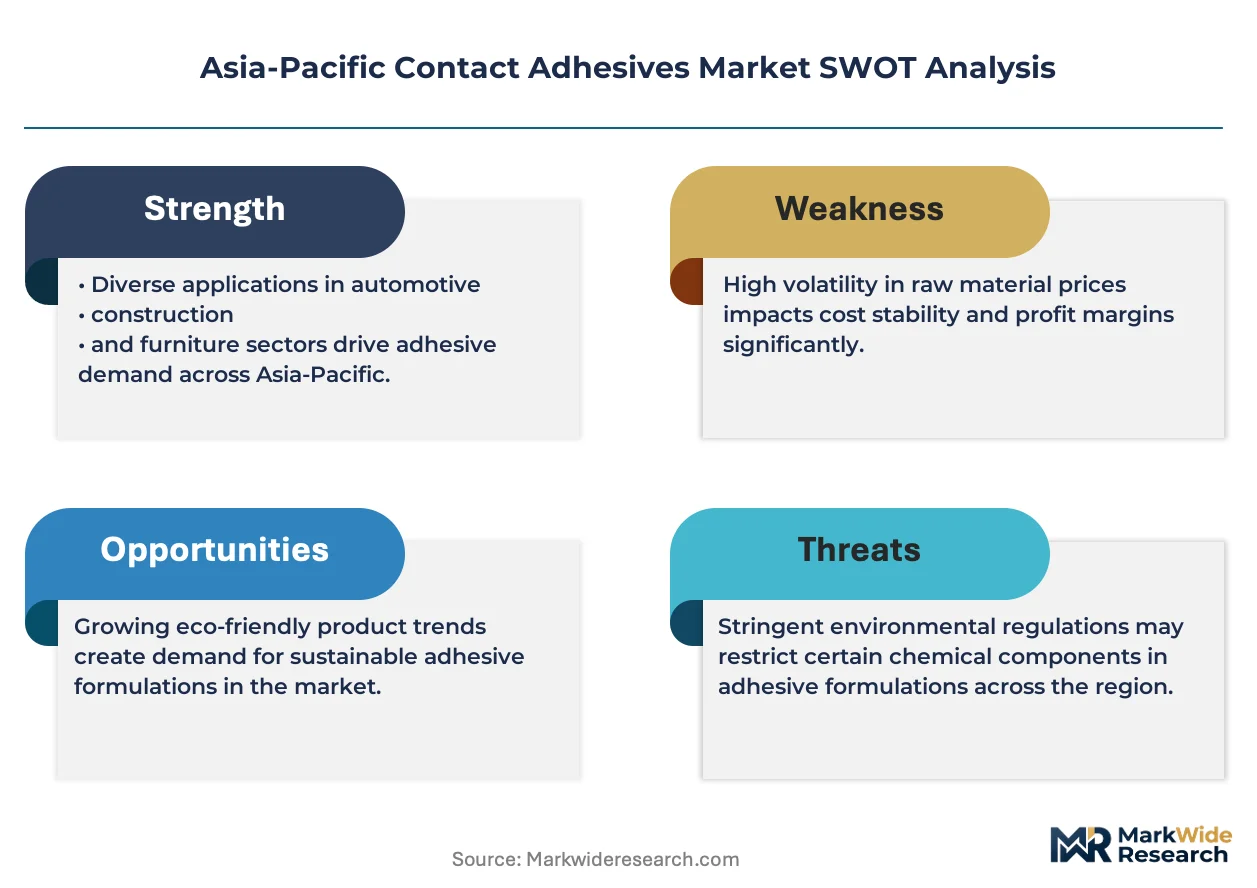
China's MEE enforcement of GB VOC emission standards is forcing solvent-based contact adhesive manufacturers toward water-based and reactive system reformulation across the Asia-Pacific region. This regulatory pressure is compressing legacy formulation margins while rewarding early movers in low-emission chemistry.
Growth Catalysts
- Automotive Interior Bonding:Thailand and Indonesia assembly plants are expanding polyurethane contact adhesive purchases for dashboard lamination and trim attachment as regional vehicle production scales.
- GB Standards Compliance:China's tightening VOC limits under MEE oversight are creating mandated demand pull for compliant water-based and hot-melt contact adhesive alternatives.
- Furniture Manufacturing Clusters:Gujarat and Maharashtra woodworking hubs are driving concentrated water-based adhesive adoption through scaled decorative laminate bonding operations.
Market Restraints
- Petrochemical Feedstock Volatility:Neoprene rubber and polyurethane prepolymer input costs fluctuate with crude oil derivatives, compressing formulation margins unpredictably.
- Domestic Resin Supply Concentration:Key polymer intermediates concentrate among limited Southeast Asian and Northeast Asian chemical producers, exposing buyers to single-source risk.
- Heat Resistance Trade-Off:Water-based contact adhesives face technical performance ceilings in automotive OEM specifications where solvent-based systems retain non-negotiable durability advantages.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Footwear and electronics assembly migration into northern Vietnamese industrial zones creates underpenetrated demand for high-tack bonding solutions.
- BIS Certification Tailwinds:India's construction chemical certification requirements favor established domestic producers with testing infrastructure, creating compliance moats.
- Reactive System Convergence:Moisture-cure polyurethane and UV-activated contact adhesive technologies are opening specification opportunities in premium furniture and automotive tier-one supply chains.
Industry Challenges
- Formulation Chemistry Expertise Gap:Water-based system development requires polymer science capabilities scarce among traditional solvent-based adhesive compounders.
- Dual Certification Timelines:Simultaneous BIS, GB standard, and METI compliance processes extend product launch cycles by 18-24 months for multi-country suppliers.
- Legacy Equipment Retrofit Costs:Converting solvent-based production lines to handle water-based viscosity profiles demands capital-intensive drying system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Contact Adhesives Market |
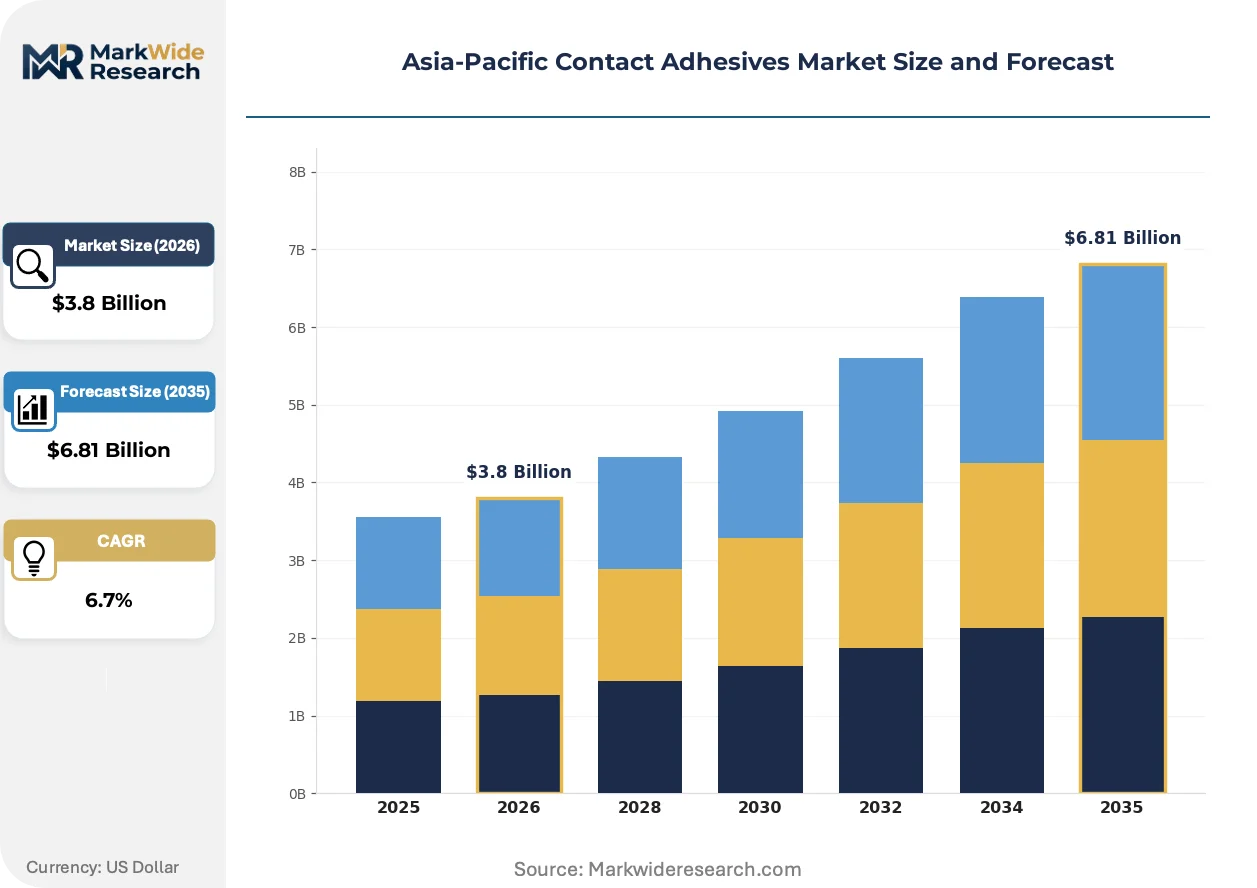
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber-Based, Polyurethane, Acrylic, Silicone End User: Furniture, Automotive, Construction, Footwear Formulation: Solvent-Based, Water-Based, Hot Melt, Reactive Application: Bonding, Assembly, Laminating, Coating |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Arkema Group, H.B. Fuller, Sika AG, Bostik, Pidilite Industries Ltd., NANPAO Resins Chemical Group, Huntsman International LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Contact Adhesives Market Strategic Shifts
Water-based polyurethane dispersion technology is rewriting competitive positioning in Asia-Pacific contact adhesives. Formulation advances are compressing the performance gap with solvent-based systems while satisfying tightening environmental mandates across manufacturing hubs.
Reactive hot-melt contact adhesives combining polyurethane prepolymers with moisture-cure mechanisms are rewriting durability expectations in high-humidity climates. Malaysian and Indonesian furniture manufacturers are adopting these systems at accelerating pace for outdoor and kitchen applications. The technology is rewriting specification standards by eliminating clamping requirements while delivering structural bond strength previously reserved for two-part systems.
China's MEE GB standards on VOC emissions are tightening formulation requirements with industrial consequences rippling through regional supply chains. Solvent-based product portfolios face phased compliance deadlines forcing R&D redirection toward water-carrier and 100% solids systems. Automotive OEM specifications in Thailand and China represent the most affected segments, with tier-one suppliers accelerating reactive system qualification programs.
Direct procurement from adhesive compounders is displacing traditional distributor intermediaries among large-scale furniture and automotive manufacturers. Volume buyers in India's western industrial corridor are consolidating supplier relationships to secure technical service and formulation customization. This channel compression is most visible in Gujarat and Maharashtra, where manufacturing clusters negotiate annual framework contracts bypassing regional chemical distributors.
Asia-Pacific Contact Adhesives Market Segmentation
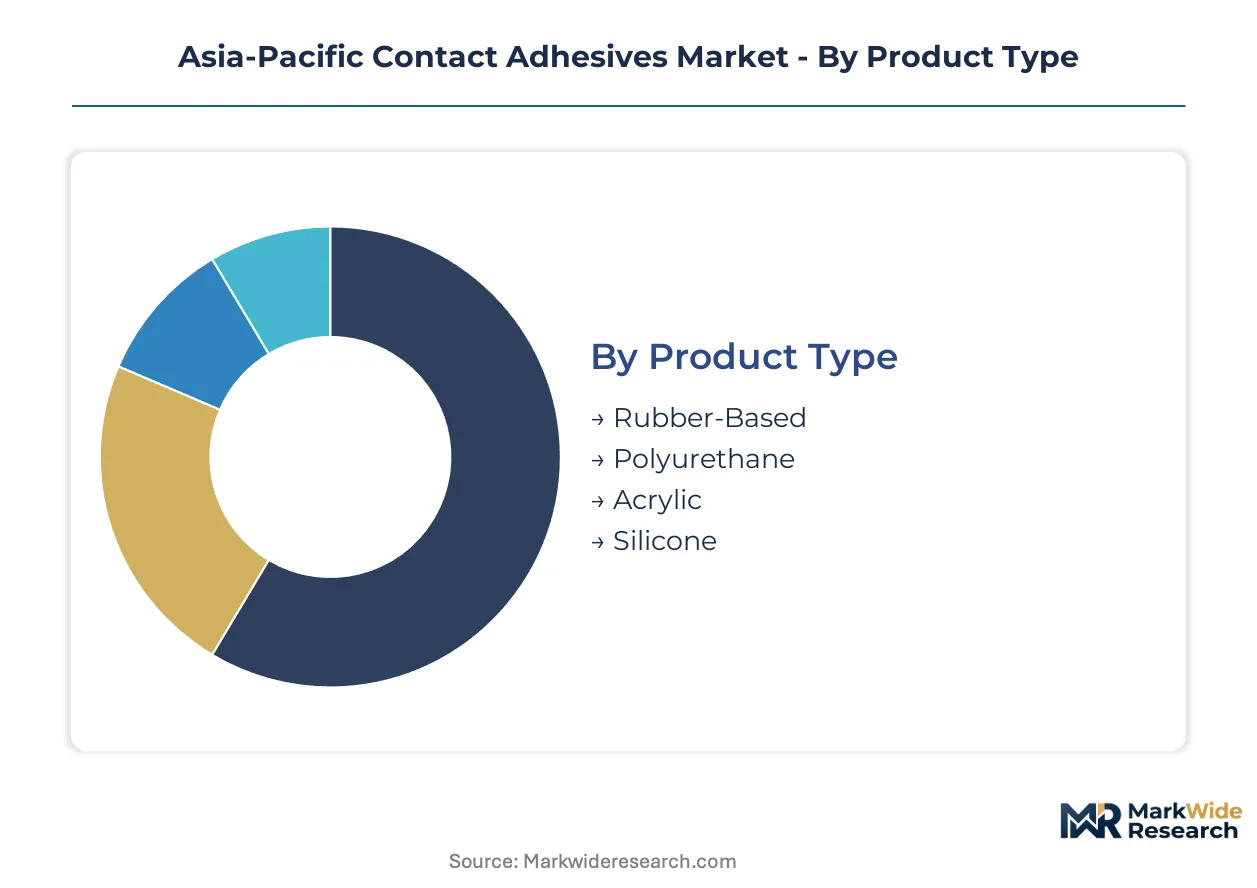
Asia-Pacific contact adhesives manufacturers align product portfolios against distinct performance specifications and regulatory compliance tiers. Each segmentation dimension carries different margin profiles and capital requirements, shaping how suppliers allocate technical resources across the forecast window.
Product Type:
Supply concentration among polymer feedstock producers in Northeast Asia and Southeast Asia determines competitive access to each chemistry family.
- Rubber-Based:Neoprene and nitrile rubber dispersions in aromatic or aliphatic solvent carriers deliver immediate tack and high peel strength. Demand concentrates in Gujarat and Maharashtra furniture clusters where decorative laminate bonding requires proven performance at production speed. Heat resistance limitations constrain automotive specification penetration.
- Polyurethane:Prepolymer systems cure through moisture reaction or solvent evaporation to form flexible structural bonds. Thailand and Indonesia automotive assembly plants are scaling purchases for dashboard lamination and interior trim attachment as regional vehicle production expands.
- Acrylic:Aqueous dispersion polymers offer low-VOC compliance with moderate durability for light-duty applications.
- Silicone:Specialty formulations serve high-temperature and weathering-resistant bonding in construction and electronics assembly.
Today's leader: Rubber-Based. Tomorrow's challenger: Polyurethane.
End User:
Customer scale and technical service requirements split the market between fragmented craft producers and consolidated OEM procurement.
- Furniture:Decorative laminate bonding, edge banding, and veneer attachment drive volume across woodworking clusters. Water-based system adoption is climbing the fastest in Gujarat and Maharashtra as environmental compliance tightens and production scales.
- Automotive:Interior trim lamination, headliner attachment, and seat assembly demand heat-resistant formulations. Solvent-based polyurethane retains specification dominance despite MEE pressure due to non-negotiable durability requirements.
- Construction:Flooring installation, wall panel bonding, and insulation attachment create specification-driven demand.
- Footwear:Sole attachment and upper construction require high-tack, flexible bonds in high-humidity climates.
Furniture commands current volume. Automotive captures premium pricing.
Formulation:
Capital intensity and drying infrastructure requirements separate incumbent compounders from new entrants.
- Solvent-Based:Traditional systems using toluene, acetone, or hexane carriers deliver maximum bond strength and heat resistance. China's MEE GB standards are compressing legacy margins while rewarding early movers in compliant chemistry.
- Water-Based:Acrylic and polyurethane dispersions satisfy tightening VOC mandates with reduced flammability. India's western industrial corridor is driving concentrated adoption through scaled decorative laminate bonding operations.
- Hot Melt:Thermoplastic formulations offer solvent-free application with limited heat resistance.
- Reactive:Moisture-cure and UV-activated systems combine handling convenience with structural strength.
Water-Based shows the steepest expansion trajectory. Reactive systems open premium specifications.
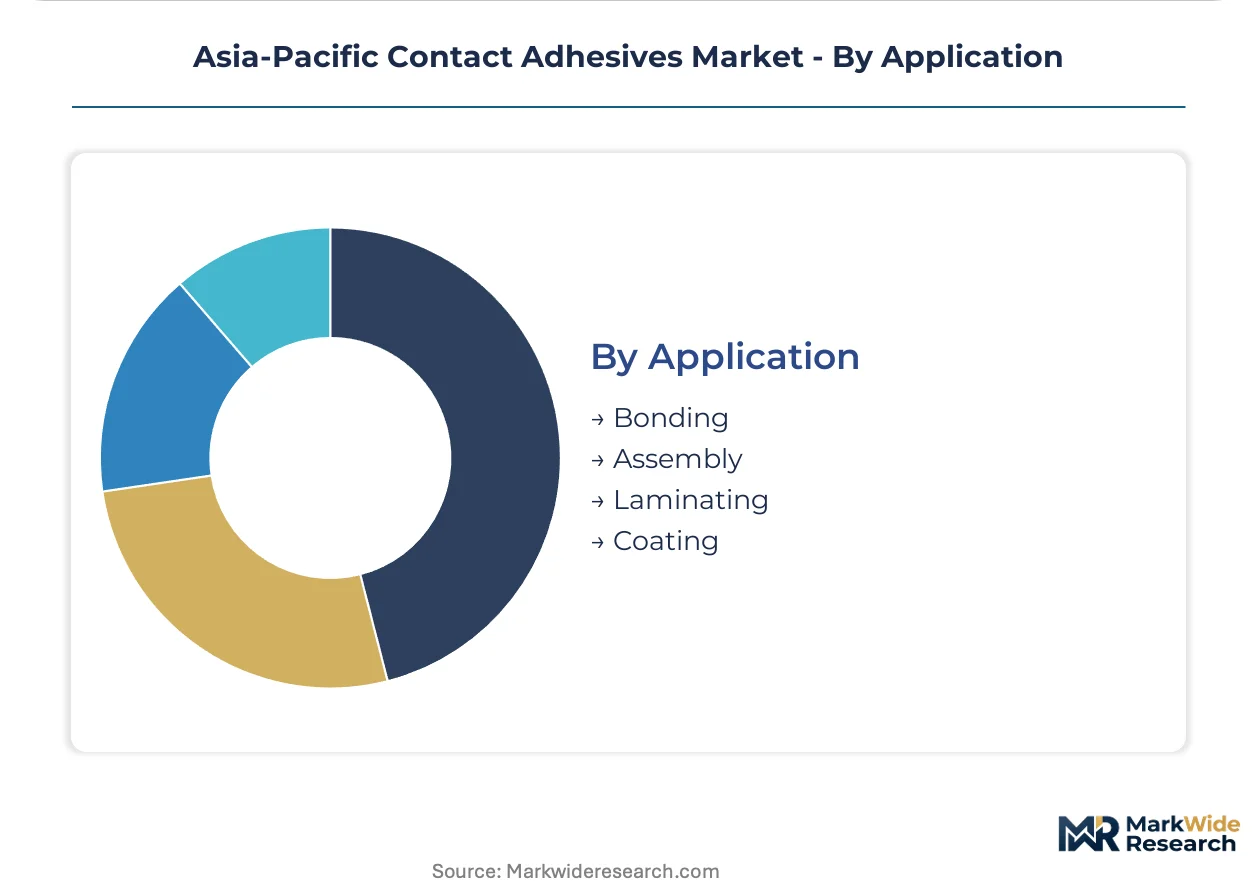
Application:
Process speed requirements and substrate compatibility dictate formulation selection across manufacturing workflows.
- Bonding:Immediate handling strength without clamping defines contact adhesive value in decorative laminate and trim applications. Malaysian and Indonesian furniture manufacturers are adopting moisture-cure systems at accelerating pace for outdoor and kitchen applications.
- Assembly:Component attachment in automotive and electronics manufacturing demands consistent viscosity and open time control.
- Laminating:Multi-layer substrate construction requires uniform wetting and minimal telegraphing.
- Coating:Protective and functional surface treatments use adhesive formulations for grip enhancement and barrier properties.
Bonding anchors volume. Assembly captures technical differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat and Maharashtra furniture manufacturing clusters anchor Asia-Pacific contact adhesive demand through scaled decorative laminate bonding operations. China's MEE GB standards on VOC emissions are redirecting formulation portfolios across regional supply chains. Thailand and Indonesia automotive assembly plants are expanding polyurethane adhesive procurement for interior trim applications.
China
Yangtze River Delta chemical producers are retooling solvent-based lines to water-based polyurethane dispersions under MEE enforcement timelines. GB standards limiting VOC emissions from adhesive formulations are compressing legacy product margins while rewarding compliant chemistry investments. Guangdong Province manufacturing hubs face phased compliance deadlines that accelerate reactive system development programs.
India
BIS certification requirements for construction chemicals are creating compliance barriers that favor established domestic producers with testing infrastructure. Maharashtra woodworking clusters in Mumbai-Pune corridor are consolidating water-based adhesive procurement through annual framework contracts. Gujarat furniture manufacturers in Ahmedabad-Surat belt are scaling decorative laminate bonding operations with direct compounder relationships.
Thailand
Automotive OEM assembly plants in Rayong and Chonburi provinces are expanding polyurethane contact adhesive purchases for dashboard lamination and headliner attachment. Board of Investment incentives for EV component manufacturing are pulling tier-one suppliers into localized adhesive qualification programs. Eastern Economic Corridor industrial zones are concentrating demand for heat-resistant interior bonding formulations.
Indonesia
Footwear manufacturing migration into West Java and Banten provinces is generating concentrated demand for high-tack neoprene rubber systems in sole attachment applications. Ministry of Industry regulations on chemical substance reporting are affecting import protocols for foreign adhesive suppliers. Bekasi and Tangerang industrial zones are emerging as procurement consolidation points for multinational footwear brands.
Vietnam
Electronics assembly expansion into Bac Ninh and Hai Phong industrial zones is creating underpenetrated demand for precision bonding solutions. Ministry of Natural Resources and Environment circulars on industrial emissions are beginning to shape formulation preferences among foreign-invested manufacturers. Northern Vietnamese provinces are attracting adhesive compounders seeking proximity to Samsung and Apple supplier ecosystems.
Asia-Pacific Contact Adhesives Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue water-based and reactive chemistry specializations. The Asia-Pacific contact adhesives market structures around three player tiers: multinational chemical conglomerates with regional distribution networks, domestic champions leveraging regulatory compliance advantages, and mid-scale compounders serving niche industrial applications. Strategic differentiation concentrates on formulation chemistry capabilities, BIS and GB standard certification portfolios, and direct technical service relationships with large-scale furniture and automotive manufacturers. Competitive moves center on reactive system R&D partnerships and production line retrofits for water-based viscosity handling.
Within the multinational tier, Henkel AG & Co. KGaA and Sika AG exemplify divergent specialization strategies. Henkel anchors its position through deep distribution networks across Southeast Asian manufacturing hubs. Sika occupies a construction-specialized position serving high-rise building projects from Singapore to Sydney. Pidilite Industries Ltd. represents the domestic champion archetype, sitting within India's market through brand strength in woodworking and decorative applications.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Arkema Group |
| H.B. Fuller |
| Sika AG |
| Bostik |
| Pidilite Industries Ltd. |
| NANPAO Resins Chemical Group |
| Huntsman International LLC |
| Others |
Value Chain & Pricing Dynamics
China's MEE GB VOC emission standards gate qualified supply and premium-tier pricing access across Asia-Pacific contact adhesives. Manufacturers achieving compliant water-based and reactive system certifications command pricing premiums from automotive OEMs and export-oriented furniture clusters, while legacy solvent-based compounders face margin compression from reformulation costs and restricted market participation.
Pricing Analysis
Input-cost pass-through from neoprene rubber and polyurethane prepolymer feedstock volatility shapes pricing dynamics across formulation tiers. Contract-based long-term offtake agreements dominate procurement between large automotive assemblers and qualified adhesive suppliers, with price differentiation driven by GB standard certification tier and volume scale. Cost compression in solvent-based segments is intensifying because MEE compliance deadlines force stranded asset write-downs. Tier-one automotive buyers exhibit lowest price sensitivity due to non-negotiable durability specifications, while commodity furniture manufacturers in Gujarat and Maharashtra drive hard volume negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Thailand and Indonesia automotive OEMs mandate multi-supplier qualification across Northeast Asian and Southeast Asian resin producers. Geographic supply concentrates in China, South Korea, and Japan for polymer intermediates, with formulation compounders drawing from Malaysian and Indonesian petrochemical derivatives. Single-source vulnerability persists in specialty polyurethane prepolymers where Japanese and Korean chemical producers dominate technical specifications. Distribution runs through direct compounder relationships with large-scale manufacturers, displacing traditional regional chemical distributors in India's western industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific contact adhesives function as a stable compounder market. Automotive interior bonding specifications and tightening MEE environmental mandates generate predictable replacement demand and compliance-driven premium capture.
For Market Incumbents: Deploy reactive system R&D partnerships to capture specification upgrades in Thailand and Indonesia automotive supply chains. Accelerate water-based production line retrofits before MEE phased compliance deadlines strand solvent-based capacity. Defend against emerging Chinese domestic compounders by securing BIS certification moats in India's construction chemical segments. For New Entrants and Emerging Players: Launch via direct technical service models targeting Vietnam's underpenetrated electronics assembly zones in Bac Ninh and Hai Phong. Concentrate initial penetration on moisture-cure polyurethane formulations for Malaysian and Indonesian outdoor furniture applications where incumbent coverage remains thin. Establish formulation partnerships with regional resin distributors to bypass capital-intensive captive production. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale water-based compounders with GB standard certification portfolios because regulatory barriers prevent rapid new entrant scaling. Five-to-ten year viability hinges on reactive system technology access and direct OEM relationships rather than distributor-dependent revenue. Monitor MEE enforcement intensity in Guangdong Province as the inflection indicator for accelerated solvent-based displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Prepolymers | Captures margin from Korean and Japanese chemical suppliers while securing supply continuity for Thailand automotive programs. |
| GB Standard Certification Investment | Unlocks premium pricing from China-based automotive OEMs facing MEE compliance deadlines. |
| Direct Technical Service Deployment | Bypasses distributor intermediaries in Gujarat and Maharashtra furniture clusters to capture formulation customization revenue. |
| Moisture-Cure System Joint Venture | Combines regional humidity expertise with European reactive chemistry IP for Indonesian outdoor furniture specifications. |
| Long-term Supply Agreement with EV Component Suppliers | Locks in volume commitments from Thailand's Eastern Economic Corridor as EV manufacturing scales. |
Study Parameters
Coverage spans China, India, Thailand, Indonesia, and Vietnam, with primary inputs from each market's adhesive compounders and downstream manufacturers. Primary interviews with plant managers at automotive assembly facilities, procurement leads at furniture manufacturing clusters, distribution channel partners, and technical R&D directors at resin suppliers combined with secondary validation from customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from multinational suppliers, and GB standard documentation from China's MEE. Bottom-up volume modeling triangulated against top-down industry association estimates.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry family, end-use industry vertical, compliance certification tier, and regional production hub clustering. CAGRs derived from fitted growth curves applied to segment-level baseline volumes, incorporating automotive production forecasts, furniture manufacturing capacity expansion announcements, and regulatory phase-in schedules as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement acceleration or petrochemical feedstock price spikes. Deviation in China's dual carbon policy implementation timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market