
 Mullite Market | 2026-2036
Mullite Market Size, Share, and Industry Trends Forecast 2026-2036
Mullite Market Foresight
Chinese refractory producers is pivoting toward synthetic mullite output to serve electric-arc furnace upgrades across East Asian steelworks. Imerys Fused Minerals leverages its European raw-material base to sustain long-haul supply contracts for fused grades. Saint-Gobain anchors premium product positioning through controlled thermal-processing capabilities. Washington Mills competes on volume scale in North American abrasive-grade segments.
Mullite denotes an aluminosilicate ceramic phase with nominal composition near 3Al₂O₃·2SiO₂, exhibiting thermal stability above 1800°C and low thermal expansion that suits refractory linings, kiln furniture, and investment casting shells. Synthetic mullite leads value generation due to tighter chemistry control and superior creep resistance in power-generation turbines. Refractories remains the mature volume anchor while aerospace-directed insulation shapes the fastest-growing margin pool. Powder and granule forms dominate processing flexibility across casting and ceramics applications.
China's MEE enforces emissions caps on refractory sintering operations, redirecting capacity toward cleaner synthetic routes. REACH compliance in Europe restricts crystalline silica content in imported mullite powders, filtering market access for non-certified suppliers. India's BIS certification mandates thermal-shock performance benchmarks for domestic refractory consumption. Stakeholders must track how carbon-border adjustments and evolving furnace efficiency standards reshape procurement criteria across steel and power end users.
Market Dynamics
Steel decarbonization across East Asian blast furnaces is compressing demand for traditional fireclay linings while elevating synthetic mullite specifications for electric-arc furnace retrofits and hydrogen-direct-reduction trials.
Growth Catalysts
- China's dual carbon mandates:MIIT emissions caps on refractory sintering operations redirect capacity toward cleaner synthetic mullite routes, tightening supply discipline for high-alumina grades.
- India's foundry expansion:BIS certification mandates for thermal-shock performance in domestic steel casting accelerate specification upgrades from bauxite-based to engineered mullite linings.
- Turbine blade investment casting:Aerospace OEMs specify creep-resistant synthetic mullite for directional solidification shells, displacing fused silica in single-crystal superalloy applications.
Market Restraints
- Bauxite supply concentration:Guinean and Indonesian ore export restrictions elevate feedstock volatility for fused mullite producers dependent on specific alumina grades.
- REACH crystalline silica thresholds:ECHA restrictions on respirable silica content in imported powders filter market access for non-certified Chinese suppliers to European refractory blenders.
- Silicon carbide substitution:Non-oxide ceramics penetrate kiln furniture segments above 1600°C, compressing mullite's addressable range in advanced ceramics firing.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM implementation creates first-mover advantage for synthetic mullite producers with verified low-carbon process heat and renewable electricity sourcing.
- Thailand's ceramics cluster:Underpenetrated investment casting foundries serving Japanese automotive transplant supply chains offer greenfield specification adoption without legacy refractory lock-in.
- Sol-gel nanostructured mullite:Convergence of colloidal processing with additive manufacturing enables complex near-net-shape kiln furniture geometries impossible via conventional slip casting.
Industry Challenges
- Refractory engineer scarcity:Retiring expertise in high-temperature materials specification at steel mills and foundries outpaces university training programs in ceramics engineering.
- ISO 9001:2015 transition timelines:Certification body backlogs delay supplier qualification for aerospace casting shell contracts, extending sales cycles by 12-18 months.
- Legacy furnace compatibility:Synthetic mullite thermal expansion coefficients mismatch existing firebrick expansion joints, requiring costly rebuilds rather than drop-in lining replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mullite Market |
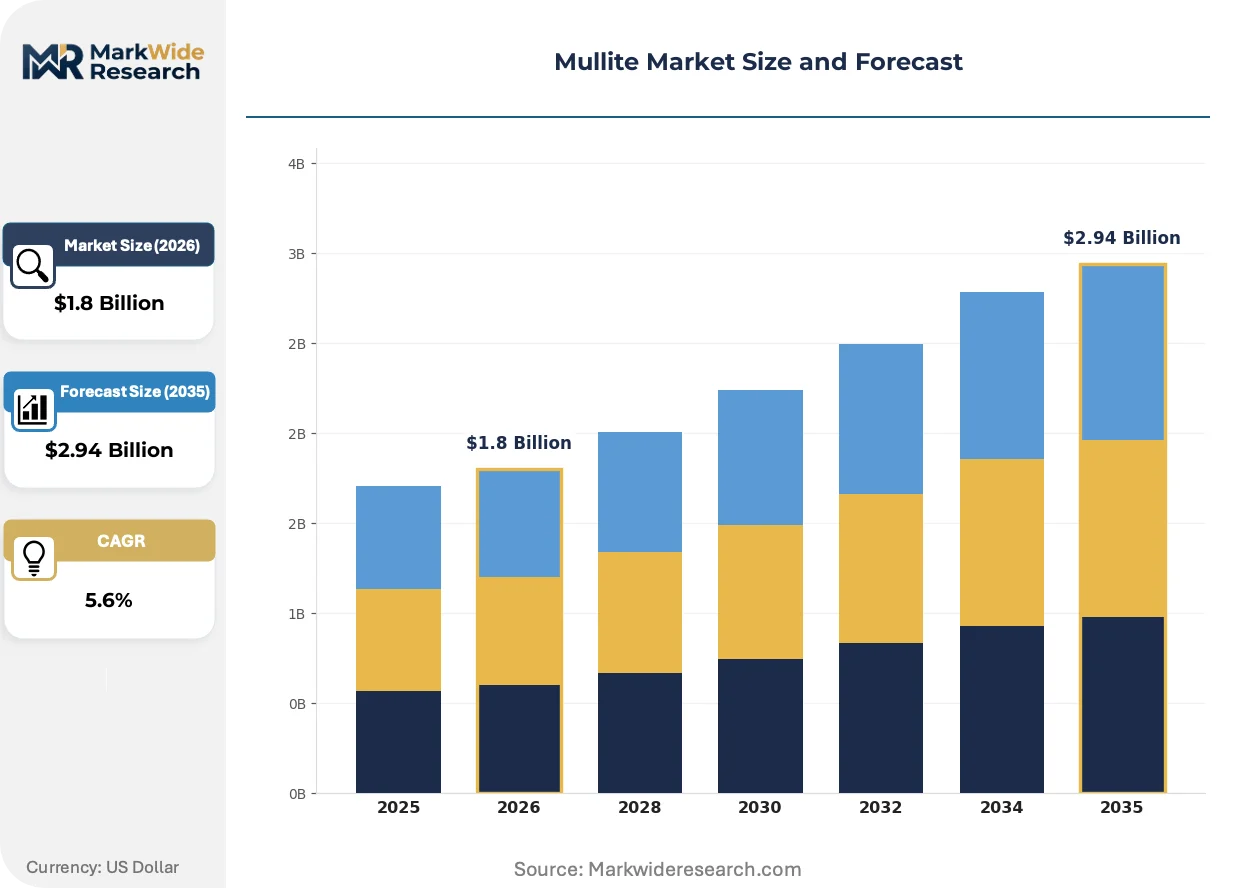
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Mullite, Synthetic Mullite, High Alumina Mullite, Fused Mullite Application: Refractories, Ceramics, Casting, Insulation End User: Aerospace, Automotive, Power Generation, Construction Form: Powder, Granule, Block, Tile |
| Companies Covered | Imerys Fused Minerals, TAM Ceramics, Washington Mills, Saint-Gobain, Cumi Murugappa, Electro Abrasives, Doral, Monofrax LLC, Cera Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mullite Market Shifts & Advancements
Process intensification in refractory manufacturing is collapsing batch cycle times while digital thermal monitoring rewrites quality assurance protocols across the supply base.
Flash calcination of kaolin-alumina precursors is rewriting energy economics for synthetic mullite production. European refractory producers pilot plasma-assisted sintering to cut process heat requirements by half. This thermal efficiency leap is compressing the cost gap between fused and sintered grades, enabling specification upgrades in cost-sensitive Indian and Vietnamese steel mills.
REACH authorization timelines for crystalline silica are forcing reformulation of investment casting shell systems. German foundry suppliers accelerate development of engineered mullite flour below 5 micron with sub-detectable respirable silica. Aerospace precision casters in Bavaria and Saxony now specify these pre-certified blends to preempt 2026 authorization deadlines.
Steel procurement departments consolidate refractory spend through outcome-based performance contracts rather than tonnage-based purchasing. Japanese integrated mills lead this shift, tying supplier payments to lining campaign life and energy efficiency metrics. Korean and Taiwanese foundries now replicate these models, displacing traditional distributor relationships with direct technical partnerships.
Mullite Market Segmentation
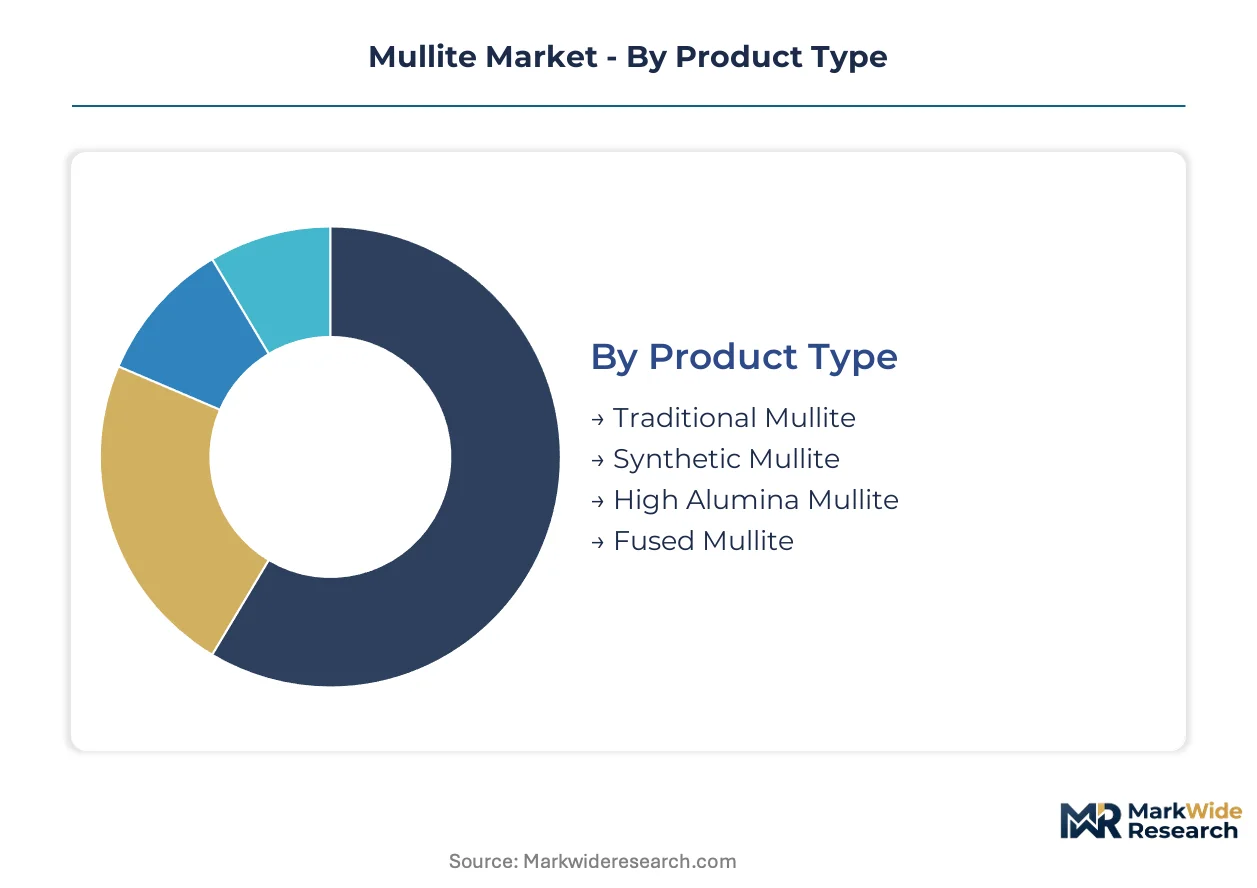
Mullite's performance characteristics vary sharply across grades and forms, forcing procurement teams to match thermal expansion coefficients and creep resistance to specific furnace operating windows. Specification misalignment between product type and end-use application drives premature lining failure and unplanned shutdown costs.
Product Type:
Upgrade cycles from traditional to engineered grades dominate capital planning as steelmakers replace fireclay with higher-performance alternatives.
- Synthetic Mullite:Engineered from controlled kaolin-alumina ratios with sub-5% impurity bands, delivering creep resistance above 1600°C. Demand concentrates in China's electric-arc furnace retrofits where MIIT emissions caps mandate cleaner synthetic routes over sintered bauxite alternatives.
- Fused Mullite:Electric-arc furnace melting produces dense, low-porosity grains with exceptional thermal shock resistance. Indian foundries specify fused grades for BIS-certified investment casting shells as domestic casting output rises and quality benchmarks tighten.
- Traditional Mullite:Natural aluminosilicate deposits serve cost-sensitive kiln furniture in Vietnam's ceramics cluster.
- High Alumina Mullite:Al₂O₃-rich formulations above 70% alumina content target gas turbine transition sections in US power plants.
Volume placements concentrate in Traditional Mullite; the faster expansion belongs to Synthetic Mullite.
Application:
Application selection tracks furnace peak temperature and thermal cycling frequency, with margin pools diverging between mature refractory tonnage and precision casting value.
- Refractories:Kiln linings, furnace walls, and ladle covers absorb 60%+ of mullite consumption across steel and cement sectors. Japanese integrated mills now tie supplier payments to lining campaign life metrics rather than tonnage delivered.
- Casting:Investment casting shells for directional solidification of superalloy turbine blades demand sub-micron synthetic mullite flour. Aerospace OEMs in Bavaria and Saxony specify engineered grades below 5 micron with sub-detectable respirable silica to preempt ECHA authorization deadlines.
- Ceramics:Kiln furniture and saggars for advanced ceramic firing face silicon carbide substitution above 1600°C.
- Insulation:Low-density mullite fiber boards serve backup linings in hydrogen-direct-reduction trial furnaces.
Refractories anchor volume scale; Casting claims the steepest margin expansion trajectory.
End User:
End-user procurement sophistication separates specification-driven aerospace programs from price-sensitive construction tenders.
- Power Generation:Combined-cycle gas turbines specify creep-resistant synthetic mullite for transition duct linings and combustor tiles. Korean and Taiwanese foundries replicate Japanese outcome-based contracting models for refractory performance.
- Aerospace:Precision investment casting of single-crystal superalloy blades drives the highest purity requirements. German foundry suppliers accelerate development of pre-certified mullite flour blends to serve Bavarian and Saxony precision casters.
- Automotive:Thai investment casting foundries serving Japanese automotive transplant supply chains offer greenfield specification adoption without legacy refractory lock-in.
- Construction:Fire-rated building materials and ceramic tiles consume standard-grade granules with minimal chemistry control.
Construction absorbs volume tonnage; Aerospace generates the fastest value-per-kilogram gains.
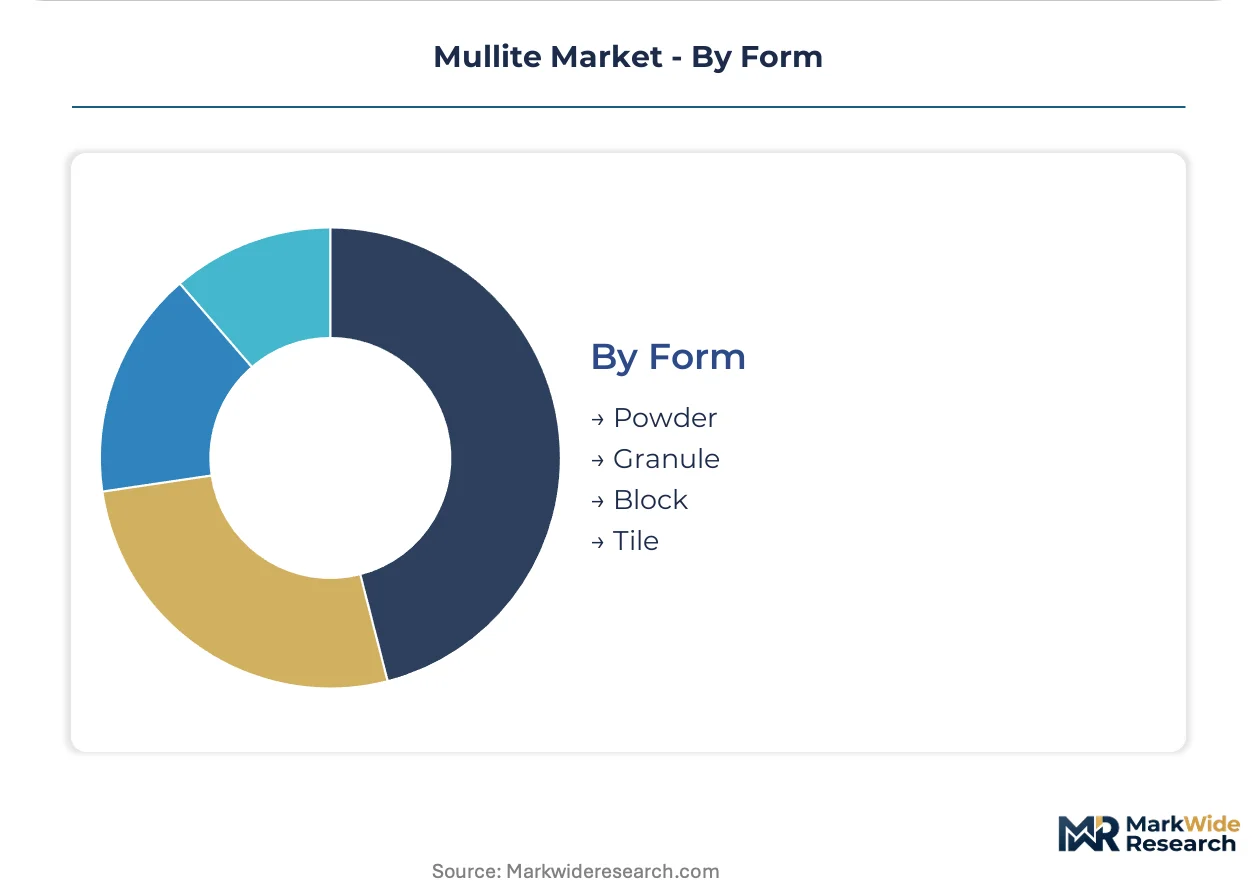
Form:
Form selection determines processing flexibility and final part geometry capability across casting and ceramics workflows.
- Powder:Sub-45 micron flour enables slurry-based investment casting shell buildup and ceramic injection molding. REACH crystalline silica thresholds force reformulation toward engineered low-silica grades for European refractory blenders.
- Granule:Controlled particle size distributions optimize packing density in monolithic refractory gunning and ramming mixes. Indian BIS certification mandates thermal-shock performance benchmarks that elevate granule specification grades in domestic steel casting.
- Block:Pre-fired shapes reduce installation time for steel ladle linings and glass furnace crowns.
- Tile:Precision-ground kiln furniture plates support advanced ceramic firing with minimal thermal mass.
Granule shipments dominate refractory volume; Powder forms are expanding most quickly in aerospace-directed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guinean bauxite deposits anchor the alumina feedstock chain that supplies fused mullite producers across East Asian steel corridors. Regional demand patterns diverge sharply between mature refractory replacement cycles and greenfield specification upgrades in emerging casting clusters.
China
Electric-arc furnace retrofits in Hebei and Shandong provinces drive synthetic mullite consumption for high-alumina kiln linings. MIIT emissions caps on refractory sintering operations redirect capacity toward cleaner synthetic routes with lower particulate discharge. Tangshan steel clusters now specify engineered mullite grades for hydrogen-direct-reduction trial furnaces.
India
Domestic foundry output expansion in Tamil Nadu and Maharashtra accelerates specification upgrades from bauxite-based to engineered mullite investment casting shells. BIS certification mandates thermal-shock performance benchmarks that filter substandard imports from Southeast Asian suppliers. Coimbatore's precision casting cluster adopts fused mullite grades for aerospace-directed superalloy applications.
Germany
Bavarian and Saxony precision foundries specify sub-5 micron engineered mullite flour with sub-detectable respirable silica to preempt ECHA authorization deadlines. REACH crystalline silica thresholds force reformulation of investment casting shell systems for single-crystal turbine blade production. Leipzig's ceramics research institutes pilot plasma-assisted sintering to halve process heat requirements.
United States
Combined-cycle gas turbine operators in Texas and Louisiana specify creep-resistant synthetic mullite for transition duct linings above 70% alumina content. EPA stationary source emissions rules tighten refractory manufacturing permits in Ohio and Pennsylvania. Pittsburgh-based refractory blenders consolidate procurement through outcome-based performance contracts tied to lining campaign life.
Japan
Integrated steel mills in Chiba and Kanagawa prefectures tie supplier payments to energy efficiency metrics rather than tonnage delivered. METI efficiency standards accelerate synthetic mullite adoption in blast furnace relining programs. Nagoya's automotive casting foundries replicate outcome-based contracting models for investment shell procurement.
Mullite Market Competitive Landscape
Global majors compete with regional champions across raw-material access and thermal processing capabilities. The vendor base separates into fused mineral specialists, engineered ceramics developers, and diversified refractory conglomerates with captive mining positions. Three archetypes dominate: European fused-grade producers leveraging bauxite-alumina integration, Asian synthetic mullite specialists serving steel decarbonization, and North American abrasive-grade volume players. Consolidation pressure concentrates in mid-cap refractory blenders seeking backward integration into alumina feedstock security.
Among European fused mineral producers, Imerys Fused Minerals and Saint-Gobain occupy positions anchored by controlled thermal-processing capabilities and long-haul supply contract relationships. Washington Mills represents the North American volume-scale archetype in abrasive-grade segments. These three exemplify the competitive tension between premium specification control and cost-position defense across Atlantic and Pacific basin markets.
| Leading Market Players |
|---|
| Imerys Fused Minerals |
| TAM Ceramics |
| Washington Mills |
| Saint-Gobain |
| Cumi Murugappa |
| Electro Abrasives |
| Doral |
| Monofrax LLC |
| Cera Industries |
| Others |
Supply & Pricing Matrix
China's dual carbon mandates gate both qualified supply and premium-tier pricing access for synthetic mullite producers, as MIIT emissions caps redirect capacity toward cleaner routes while steelmakers absorb cost premiums for certified low-carbon grades. This regulatory filter compresses margins for non-compliant suppliers while rewarding verified process heat decarbonization with long-haul contract premiums from East Asian electric-arc furnace operators.
Pricing Analysis
Warranty-backed lining campaign guarantees separate premium synthetic mullite contracts from transactional spot purchases in abrasive-grade segments. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with aerospace-directed sub-5 micron flour commanding substantial premiums over refractory granules. Pricing pressure stems from silicon carbide substitution above 1600°C in kiln furniture applications. Steel procurement departments exhibit highest price sensitivity through outcome-based contracting models, while aerospace OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
Spent refractory collection and refractory-grade alumina recovery flows remain underdeveloped across the mullite value chain, though European pilot programs demonstrate closed-loop feasibility for fused mineral residues. Primary production concentrates in China, India, and Germany, with Guinean and Indonesian bauxite deposits feeding fused mullite electric-arc furnace operations. Kaolin-alumina precursor chemistry and controlled thermal processing equipment constitute critical input dependencies. Single-source vulnerability runs through concentrated Guinean ore export channels. Distribution runs through direct technical partnerships with steel mills and precision foundries, displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mullite market sits in a technology-transition phase as flash calcination and plasma-assisted sintering displace conventional batch kiln processing, collapsing energy intensity benchmarks and rewriting cost structures for synthetic grade production.
For Market Incumbents: Anchor premium positioning through captive control over low-carbon process heat verification for EU CBAM compliance, while consolidating backward integration into alumina feedstock security to defend against Guinean export restriction volatility. Invest in ISO 9001:2015 certification body relationships to preempt aerospace qualification delays.
For New Entrants and Emerging Players: Refractory engineering consultancies offer specification influence without legacy furnace compatibility constraints, enabling greenfield synthetic mullite adoption in Thailand's underpenetrated investment casting cluster serving Japanese automotive transplants. Target sol-gel nanostructured processing capabilities for additive manufacturing partnerships.
For Investors and Strategic Acquirers: Tangshan steel cluster hydrogen-direct-reduction trial announcements are the leading indicator that synthetic mullite demand inflection is imminent for high-alumina transition sections. Mid-cap refractory blenders with BIS certification traction in India represent prime acquisition targets. Monitor ECHA REACH crystalline silica authorization timelines for European market access disruption signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstock | Guinean export restrictions elevate captive bauxite-alumina conversion as risk mitigation priority. |
| Plasma-Assisted Sintering Scale-Up | Leipzig ceramics institutes demonstrate 50% process heat reduction, compressing synthetic-fused grade cost gaps. |
| Sub-5 Micron Low-Silica Flour Certification | Bavarian precision foundries preempt ECHA deadlines with pre-certified shell system formulations. |
| Outcome-Based Performance Contracting | Japanese integrated mills tie payments to lining campaign life, displacing tonnage-based purchasing. |
| Thailand Greenfield Specification Adoption | Japanese automotive transplant supply chains enable engineered mullite penetration without legacy refractory lock-in. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with refractory plant managers, steel procurement leads, precision foundry technical directors, and ceramics R&D heads. MIIT emissions cap disclosures, ECHA REACH authorization timelines, BIS certification registries, and Indian customs import data provided triangulation points. Bottom-up capacity assessments across Tangshan, Coimbatore, and Bavarian production clusters reconciled with top-down end-use consumption models.
Data-stream reconciliation across product type, application, end-user industry, and form factor dimensions enabled segmentation-level modeling across the projection horizon. CAGRs derived from weighted capacity expansion pipelines, furnace retrofit timelines, and specification upgrade elasticity estimates. Hydrogen-direct-reduction trial announcements and electric-arc furnace retrofit commitments served as demand inflection inputs.
Several conditions sit outside the modeled scope, including unforeseen bauxite export embargoes, breakthrough silicon carbide cost reductions, and disruptive colloidal processing patent expirations. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and steel decarbonization capital commitment levels. Practitioners should monitor Tangshan hydrogen pilot scale-up decisions and ECHA silica authorization final rulings for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ball Clay Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Ceramic Substrate Market
Ceramics
Global Industrial Clay Market
Ceramics
Pottery Ceramics Market
Ceramics
Alumina Slurry Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Cerium Carbonate Market
Ceramics
Global Ceramic Tube Market
Ceramics
Clay Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Calcite Market
Ceramics
North America Ceramic Coatings Market
Ceramics
China Clay Market
Ceramics
Europe Activated Alumina Market
Ceramics
Fire Clay Market