
 Global Magnesium Silicate Market | 2026-2036
Global Magnesium Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnesium Silicate Market Foresight
Pharmaceutical formulators are gaining share as the fastest-expanding buyer archetype, while construction additive purchasers retain volume dominance, so demand is bifurcating across high-purity and cost-optimized grades. Imerys S.A. leverages its vertical integration from mining to micronization to control talc supply chains for European personal care customers. Minerals Technologies Inc. anchors North American supply through specialized precipitation processes that yield consistent batch chemistry for rubber compounding. Nippon Talc Co., Ltd. dominates high-aspect-ratio flake production serving Japanese ceramics manufacturers with exacting thermal expansion specifications.
Magnesium silicate denotes a family of hydrated magnesium silicate minerals including talc, steatite, and sepiolite, characterized by layered or fibrous crystal structures with Mohs hardness ranging from 1 to 2.5 and theoretical magnesium oxide content between 28% and 32% depending on hydration state; these minerals function primarily as functional fillers, rheology modifiers, and processing aids across industrial formulations. Talc occupies the largest revenue pool in personal care and paper manufacturing where lamellar particle shape delivers barrier properties and surface smoothness. Sepiolite represents the fastest-growing product category driven by its exceptional adsorption capacity in agricultural carrier applications and specialized construction additives requiring high surface area.
EPA oversight of talc purity in the United States and REACH registration requirements for magnesium silicate substances in Europe are elevating analytical certification costs while restricting unverified supply sources from entering formulated product value chains. China's SAMR enforces GB standards for industrial mineral grades that diverge from ISO test methods, creating dual compliance burdens for exporters serving both domestic Chinese and international customers. Stakeholders must monitor divergence between regional purity protocols and position testing investments where certification gaps create supply discontinuities.
Market Dynamics
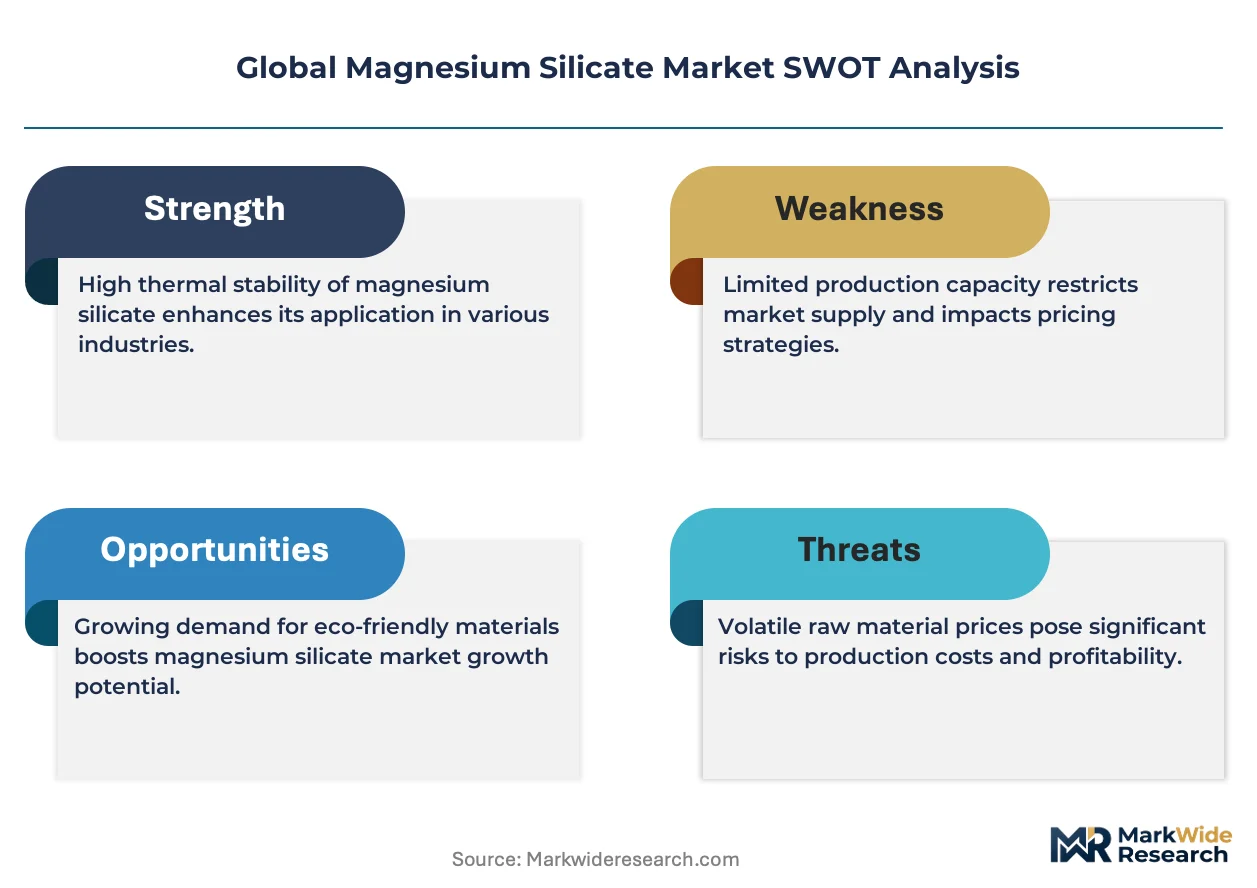
Pharmaceutical formulators are forcing grade bifurcation across the magnesium silicate supply base, splitting procurement between high-purity excipient specifications and cost-optimized industrial filler tolerances.
Growth Catalysts
- REACH registration mandates:European ECHA compliance requirements for magnesium silicate substances are filtering unverified suppliers from formulated product value chains, consolidating demand around certified producers.
- Sepiolite adsorption technology:Agricultural carrier applications exploit sepiolite's exceptional surface area for controlled-release fertilizer formulations, expanding volume pull from precision farming sectors.
- China's ceramics scaling:Domestic rubber and ceramics manufacturers are concentrating consumption of locally mined talc and sepiolite grades, reducing import dependency for standard industrial specifications.
Market Restraints
- Talc purity verification costs:EPA oversight of asbestos contamination thresholds in the United States has elevated analytical certification expenditures, compressing margins for smaller mining operations.
- Input energy volatility:Micronization and calcination processes depend on natural gas and electricity pricing, exposing processors to European energy market fluctuations.
- Substitute mineral competition:Precipitated calcium carbonate and kaolin clay are displacing magnesium silicate in select paper coating and paint applications where brightness specifications dominate over barrier properties.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO regulatory alignment with ICH guidelines is opening formulation-grade magnesium silicate demand from domestic generic drug manufacturers seeking excipient diversification.
- Bio-based carrier convergence:Sepiolite-mineral hybrid composites combining organic matrices with inorganic scaffolding are penetrating biodegradable agricultural film applications.
- Japan's thermal expansion specifications:High-aspect-ratio flake production for advanced ceramics offers premium positioning for producers meeting exacting JIS standards.
Industry Challenges
- Dual compliance burden:Exporters serving both Chinese domestic and international customers must maintain parallel testing protocols under divergent GB and ISO methodologies.
- Specialized precipitation capex:Consistent batch chemistry for rubber compounding demands capital-intensive controlled precipitation infrastructure.
- Geologist-mineralogist scarcity:Deposit characterization and grade optimization require expertise in hydrated magnesium silicate mineralogy that outpaces current training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnesium Silicate Market |
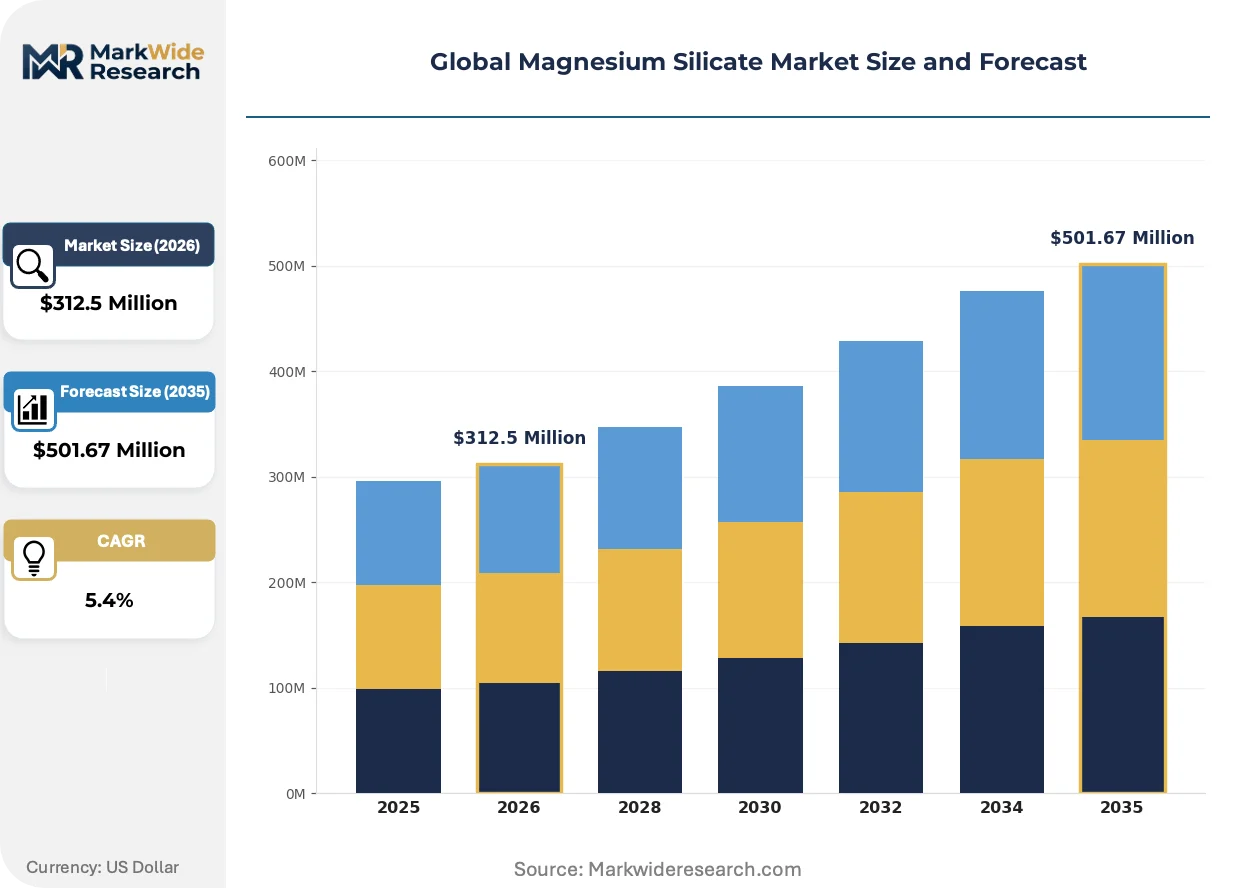
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Talc, Steatite, Sepiolite, Trioctahedral Micas Application: Construction Additives, Paints & Coatings, Personal Care, Paper Manufacturing End User Industry: Pharmaceuticals, Rubber Manufacturing, Ceramics, Agriculture Form: Powder, Granules, Flakes, Sheets |
| Companies Covered | Imerys S.A., Minerals Technologies Inc., Mondo Minerals, IMI Fabi S.p.A., Huber Engineered Materials, Nippon Talc Co., Ltd., SCR-Sibelco NV, PQ Corporation, Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnesium Silicate Market Shifts & Advancements
Process intensification and analytical sophistication are redefining competitive differentiation across magnesium silicate value chains, compressing the gap between mining output and formulated product performance requirements.
Surface functionalization chemistry is displacing unmodified magnesium silicate in high-performance polymer nanocomposites. Automotive underhood component manufacturers are adopting silane-treated talc grades at accelerating rates to achieve thermal stability and dimensional precision. This modification capability is displacing conventional filler loadings in engineering thermoplastic applications.
EU F-Gas Regulation phase-down schedules are indirectly pressuring magnesium silicate producers serving refrigeration sealant and gasket compounds. Manufacturers are reformulating to eliminate fluorinated blowing agents while maintaining compression set resistance. European appliance OEMs are most affected, driving collaborative R&D between compounders and mineral processors.
Specification-driven procurement consolidation is compressing supplier bases across personal care and pharmaceutical verticals. Brand owners are reducing approved vendor lists from regional sourcing to single-global-supplier arrangements with full traceability documentation. This concentration pattern is most visible in North American and Western European cosmetics manufacturing, where batch record integrity requirements exceed mineral filler commodity conventions.
Global Magnesium Silicate Market Segmentation
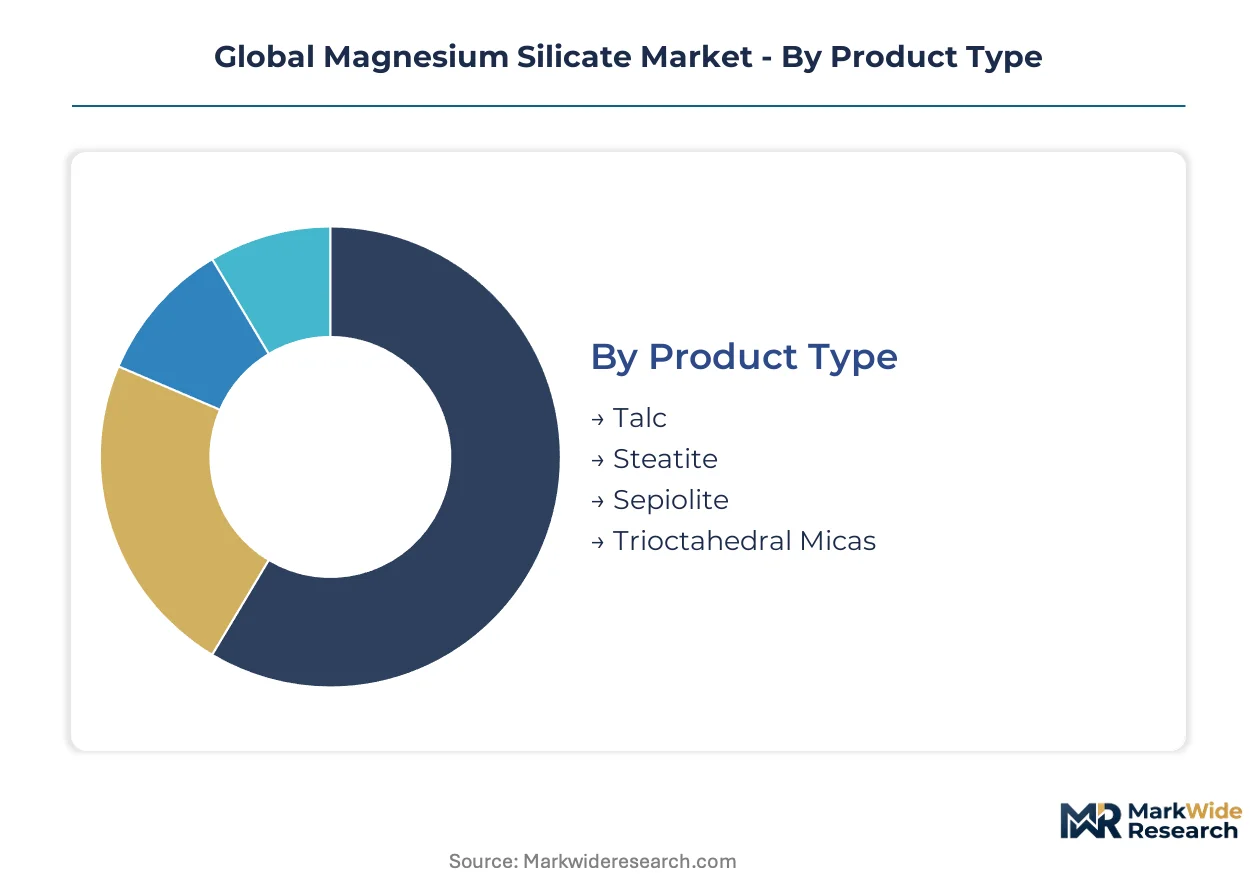
Magnesium silicate supply chains route through distinct channel configurations depending on particle morphology and purity grade. Channel specialization creates procurement friction points that segment-specific strategies must address.
Product Type:
Channel mix varies sharply by mineralogy—lamellar talc flows through personal care distributors while fibrous sepiolite concentrates in agricultural formulation channels.
- Talc:Lamellar hydrated magnesium silicate with Mohs hardness of 1 delivers barrier properties in cosmetics and surface smoothness in paper coatings. European REACH-registered talc concentrates in pharmaceutical excipient channels where ECHA compliance documentation commands premium positioning.
- Sepiolite:Fibrous magnesium silicate with exceptional surface area (200-300 m²/g) enables controlled-release fertilizer carriers. Chinese precision farming sectors are scaling sepiolite procurement through domestic mineral trading platforms, bypassing traditional import channels.
- Steatite:Dense, low-porosity magnesium silicate ceramic feedstock serving electrical insulator manufacturers.
- Trioctahedral Micas:Sheet silicates with interlayer cation exchange capacity for specialty polymer composites.
Talc dominates installed base. Sepiolite is where expansion concentrates.
Application:
Cost tier stratification separates specification-grade applications from commodity filler markets, with certification burden driving margin dispersion.
- Construction Additives:Rheology modifiers and anti-shrink agents in cementitious systems exploit sepiolite's high water retention. Chinese infrastructure stimulus is concentrating volume through state-contractor procurement frameworks with GB standard compliance requirements.
- Personal Care:Talc-based powders and pressed formulations demand asbestos-free certification under FDA oversight in the United States. Brand owners are consolidating approved supplier lists to single-source arrangements with full batch traceability.
- Paints & Coatings:Lamellar talc provides barrier properties and corrosion resistance in marine protective coatings.
- Paper Manufacturing:Filler and coating applications where brightness specifications increasingly favor precipitated calcium carbonate substitutes.
Construction additives anchor volume throughput. Personal care commands the steepest expansion trajectory.
End User Industry:
Customer type determines specification intensity—pharmaceutical formulators impose excipient-grade protocols while rubber compounders prioritize batch consistency.
- Pharmaceuticals:Magnesium silicate functions as glidant, anti-caking agent, and tablet diluent requiring USP-NF or EP monograph compliance. Indian CDSCO alignment with ICH guidelines is opening formulation-grade demand from domestic generic manufacturers.
- Rubber Manufacturing:Talc and steatite serve as processing aids and reinforcing fillers in tire and industrial rubber compounds. North American tire producers specify controlled-precipitation grades with tight particle size distribution.
- Ceramics:Steatite and talc provide thermal shock resistance in electrical insulators and sanitaryware.
- Agriculture:Sepiolite-based carriers for pesticides and slow-release fertilizers exploit fibrous mineralogy for active ingredient retention.
Rubber manufacturing holds the largest installed consumption base. Pharmaceuticals is climbing the fastest.
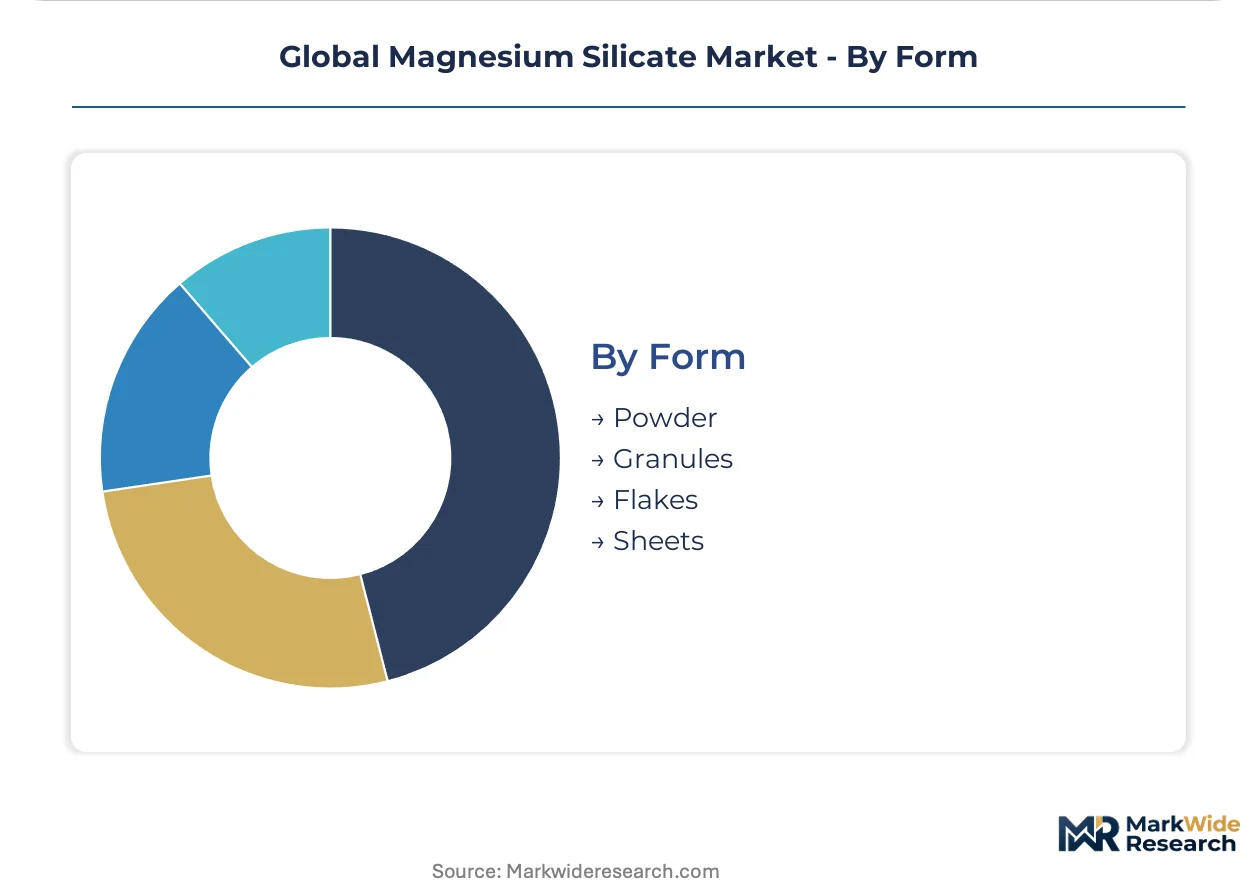
Form:
Supply concentration by form factor reflects micronization infrastructure distribution and end-use handling requirements.
- Powder:Micronized grades below 10 microns dominate personal care and pharmaceutical applications where surface area drives performance. Japanese cosmetics manufacturers specify high-aspect-ratio talc powders meeting JIS standards.
- Granules:Intermediate particle sizes for agricultural carriers and construction additives where dust suppression matters. European compounders favor granulated sepiolite for automated blending systems.
- Flakes:High-aspect-ratio talc serving advanced ceramics and polymer nanocomposites.
- Sheets:Massive steatite blocks for machining into electrical insulator components.
Powder form commands the broadest application footprint. Granules are gaining share fastest in precision agriculture channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese mining operations control the majority of sepiolite and talc feedstock extraction, while European and North American processors dominate high-purity refinement for regulated applications. National standards divergence is fragmenting certification requirements across major consumption centers.
China
Domestic ceramics and rubber manufacturers are scaling consumption of locally mined sepiolite and talc grades. SAMR enforces GB standards for industrial mineral grades that diverge from ISO test methods. Shandong Province hosts the largest concentration of sepiolite mining and primary processing infrastructure serving construction additive channels.
United States
Pharmaceutical formulators and personal care brand owners are consolidating approved supplier lists to single-source arrangements with full traceability documentation. EPA oversight of talc purity has elevated analytical certification expenditures for asbestos contamination thresholds. The Southeast industrial corridor concentrates rubber compounding operations specifying controlled-precipitation grades.
Germany
European REACH registration mandates are filtering unverified magnesium silicate suppliers from formulated product value chains. ECHA compliance requirements for magnesium silicate substances are consolidating demand around certified producers. The North Rhine-Westphalia chemicals cluster anchors precipitation-process capacity serving tire manufacturing specifications.
Japan
Advanced ceramics manufacturers are specifying high-aspect-ratio flake production with exacting thermal expansion requirements. METI oversees alignment with JIS standards for mineral fillers in precision manufacturing applications. The Nagoya industrial zone concentrates electrical insulator fabrication demanding steatite ceramic feedstock.
India
Domestic generic drug manufacturers are opening formulation-grade magnesium silicate demand from excipient diversification initiatives. CDSCO regulatory alignment with ICH guidelines is enabling pharmaceutical-grade import substitution. The Gujarat pharmaceutical manufacturing belt is scaling glidant and anti-caking agent procurement for tablet formulations.
Global Magnesium Silicate Market Competitive Landscape
Concentration sits with vertically integrated mining-to-micronization specialists and precipitation-process technologists serving specification-grade channels. The supplier base splits between consolidated multinational mineral processors and regional mining operations focused on cost-optimized industrial grades. Two strategic archetypes dominate: integrated resource holders controlling deposit access and specialized precipitators delivering consistent batch chemistry. Competitive moves center on backward integration into mining assets and geographic expansion of micronization infrastructure.
Among European integrated resource holders, Imerys S.A. and IMI Fabi S.p.A. occupy positions exemplifying deposit-controlled supply chain architecture. Minerals Technologies Inc. represents the North American precipitation-specialist archetype, anchoring controlled-process capacity for rubber compounding consistency. Nippon Talc Co., Ltd. sits within the high-aspect-ratio flake specialization tier serving exacting ceramics specifications.
| Leading Market Players |
|---|
| Imerys S.A. |
| Minerals Technologies Inc. |
| Mondo Minerals |
| IMI Fabi S.p.A. |
| Huber Engineered Materials |
| Nippon Talc Co., Ltd. |
| SCR-Sibelco NV |
| PQ Corporation |
| Tokuyama Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at Chinese sepiolite mining clusters shapes both supply concentration and price floors across industrial-grade magnesium silicate channels. European pharmaceutical-grade talc processors leverage ECHA-registered status to command premiums that offset REACH compliance analytical costs, while construction additive buyers in Asia source cost-optimized grades through domestic mineral trading platforms.
Pricing Analysis
Volume-discount tiering structures stratify across excipient-grade, industrial-grade, and mining-run-of-mine levels. Pharmaceutical formulators purchasing USP-NF or EP monograph-compliant talc face the least price sensitivity due to batch record integrity requirements, while construction additive procurement through state-contractor frameworks in China exerts the strongest downward pressure. Cost compression in industrial-grade channels intensifies because precipitated calcium carbonate substitutes are displacing magnesium silicate in brightness-dominated paper coating applications. Certification-grade differentiation separates REACH-registered European supply from unverified import sources, with after-sales technical support bundling further widening spreads between premium and economy tiers.
Supply Chain Analysis
Inbound logistics costs from Shandong Province sepiolite mines to European compounding facilities hinge on container availability through Shanghai-Ningbo port complexes and Red Sea transit reliability. Mining concentration centers on China, Spain, and Finland for talc feedstock, while high-purity precipitation processing anchors in the United States and Germany. Raw material dependencies encompass natural gas for calcination energy, specialized grinding media for micronization, and analytical reagents for asbestos contamination verification. Single-source vulnerability runs through Chinese domestic ceramics manufacturers scaling consumption of locally mined grades. Distribution runs through personal care distributors for lamellar talc and agricultural formulation channels for fibrous sepiolite.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration mandates and EPA asbestos oversight are accelerating grade bifurcation, creating asymmetric returns for certified producers versus commodity miners. Sepiolite adsorption technology for controlled-release fertilizers represents the fastest-expanding white-space opportunity.
For Market Incumbents: Compound backward integration into sepiolite mining assets in Shandong Province to secure feedstock for agricultural carrier expansion. Invest in precipitation-process capacity additions in North Rhine-Westphalia to defend rubber compounding relationships against Minerals Technologies' North American anchor position. Certification investment in dual GB-ISO testing protocols protects against supply discontinuities for exporters serving both Chinese domestic and international customers. For New Entrants and Emerging Players: CDSCO fast-track alignment for Indian pharmaceutical-grade excipient registration opens formulation-grade demand from domestic generic manufacturers. Precision farming sectors in China's interior provinces represent the most penetrable geography, bypassing established import channels through domestic mineral trading platforms. Joint development agreements with European compounders seeking fluorinated blowing agent elimination in refrigeration sealant applications provide technical credibility acceleration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precipitation-process specialists delivering consistent batch chemistry to tire manufacturing specifications. Long-term viability over the five-to-ten year window favors deposit-controlled supply chain architectures with captive micronization infrastructure. Acquisition targets should demonstrate ECHA-registered status and single-source arrangements with North American personal care brand owners. The signal to watch is EPA enforcement intensity on asbestos contamination thresholds, which would accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive sepiolite supply secures agricultural carrier volume commitments from precision farming distributors. |
| Dual Certification Investment (GB/ISO) | Parallel testing protocols enable uninterrupted export flows to Chinese domestic and international customers. |
| Precipitation Process Capacity Expansion | Controlled batch chemistry meets North American tire producer specifications for particle size distribution. |
| Surface Functionalization R&D Partnership | Silane-treated talc grades penetrate automotive underhood component manufacturers seeking thermal stability. |
| Sepiolite-Agricultural Formulator Joint Venture | Controlled-release fertilizer carriers exploit fibrous mineralogy for active ingredient retention in precision farming. |
Research Methodology
A standing panel of pharmaceutical formulation scientists, rubber compounding technical directors, ceramics manufacturing engineers, and agricultural input procurement managers provided ongoing calibration throughout the study. Primary interviews with mineral trading platform operators and REACH registration consultants combined with secondary validation from ECHA substance databases, USP-NF monograph repositories, CDSCO regulatory circulars, and Chinese customs trade statistics. Bottom-up volume modeling across grade tiers triangulated against top-down value estimates from processor financial disclosures.
Consistency checks validated segment-level outputs against external benchmarks from industrial mineral associations and precipitation-process equipment manufacturer order backlogs. The analytical framework modeled demand across product type, application, end-use industry, and form factor dimensions throughout the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories incorporated sepiolite adsorption technology adoption curves, EPA enforcement intensity scenarios, and Chinese infrastructure stimulus disbursement patterns.
Underlying assumptions cover regulatory compliance cost trajectories, natural gas pricing for calcination energy, and substitute mineral displacement rates, with deviation risk concentrated in EPA asbestos threshold revisions and SAMR GB standard harmonization initiatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Methyl Silicate Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Titanates Market
Ceramics
Zirconia Ceramics Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Lithium Zirconate Market
Ceramics
Zirconium Dioxide Market
Ceramics
USA and Canada Alumina Market
Ceramics
Activated Alumina Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Graphite Crucibles Market
Ceramics
Cement Castables Market