
 North America Specialty Gas Market | 2026-2036
North America Specialty Gas Market Size, Share, and Industry Trends Forecast 2026-2036
North America Specialty Gas Market Analytics
Carbon dioxide is hardening its position as a cost-competitive supercritical fluid substitute in food processing and pharmaceutical extraction, altering the economics of legacy solvent-based systems. Air Products and Chemicals, Inc. leverages its Gulf Coast hydrogen infrastructure to dominate merchant gas supply for regional refiners. Linde plc sustains technology leadership through proprietary cylinder management and telemetry systems that reduce downtime for healthcare customers. MESA Specialty Gases & Equipment specializes in rare and calibration gas blends, occupying a defensible niche below the tier-one merchant volumes.
North America specialty gases comprise high-purity and ultra-high-purity gases — typically exceeding 99.999% purity for electronic-grade helium and nitrogen — manufactured through cryogenic distillation, pressure swing adsorption, and membrane separation, then delivered via compressed cylinders, bulk tanks, or pipeline for process-critical applications where contamination tolerance approaches parts-per-billion levels. Electronics application leads in value intensity due to wafer fabrication demand for argon and nitrogen in deposition and annealing chambers, while hydrogen for pharmaceutical synthesis and fuel cell precursor chemistry represents the fastest-expanding application pool. Direct sales channels control the largest margin pools by locking in long-term take-or-pay contracts with semiconductor fabs and petrochemical operators, though distributor networks retain relevance for fragmented research institution and small manufacturing accounts.
FDA current Good Manufacturing Practice standards govern pharmaceutical-grade gas purity documentation, while EPA Clean Air Act provisions restrict venting of fluorinated and ozone-depleting process gases, redirecting investment toward recovery and reclamation systems. OSHA 29 CFR 1910.101 cylinder handling regulations shape workplace safety compliance costs and training burdens for end users across manufacturing and healthcare settings. Stakeholders must monitor how NHTSA fuel cell vehicle deployment timelines and DOE hydrogen hub funding decisions reshape regional hydrogen demand geography before committing fixed capital to production assets.
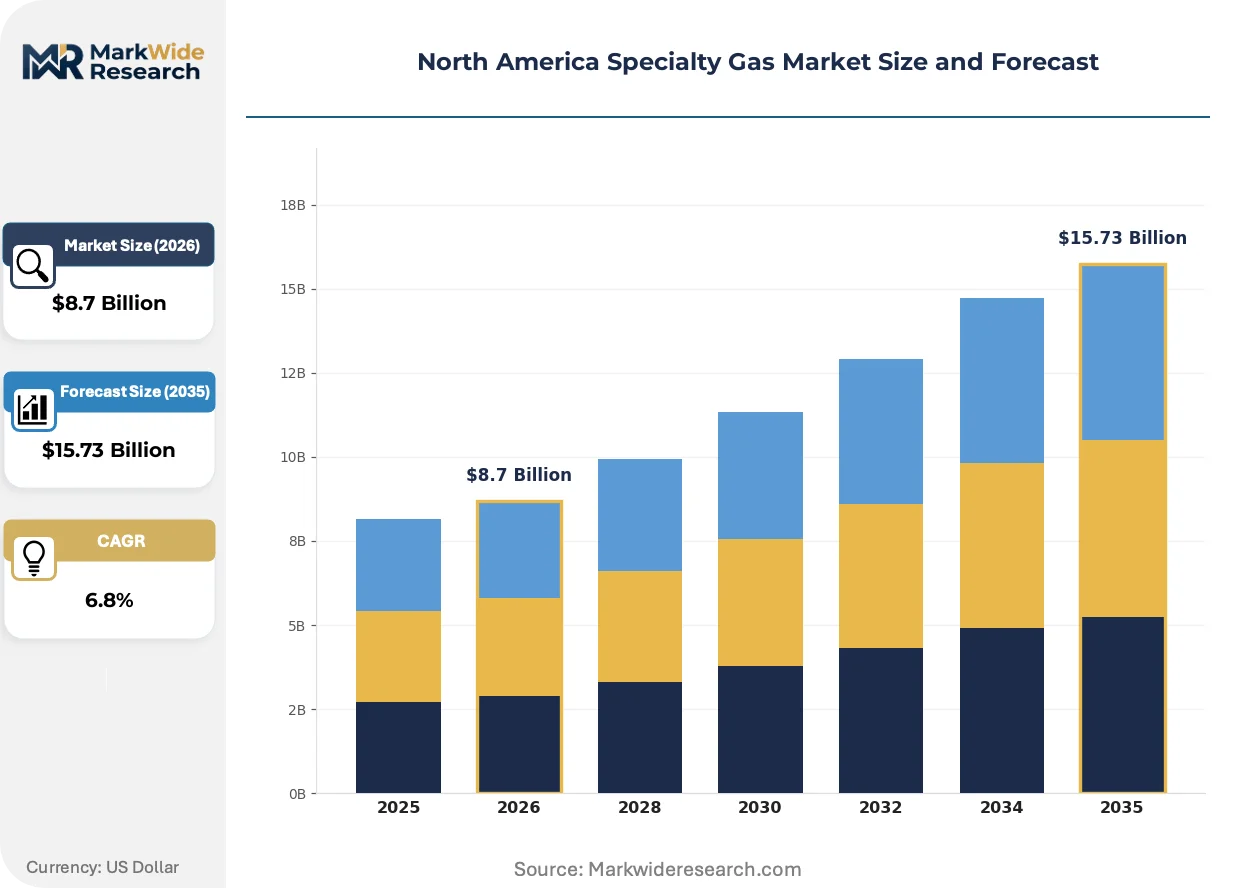
Market Dynamics
Semiconductor fabs in Texas and Arizona are pulling unprecedented volumes of electronic-grade argon and helium, compressing regional supply buffers and forcing merchant gas suppliers to prioritize long-term take-or-pay contracts over spot sales.
Growth Catalysts
- CHIPS Act capital flows:Federal subsidies for domestic wafer fabrication are locking in decade-long gas supply agreements with purity specifications exceeding 99.999%.
- EPA fluorinated gas restrictions:The Clean Air Act's tightening venting limits are redirecting investment toward recovery and reclamation infrastructure for sulfur hexafluoride and nitrogen trifluoride.
- Texas petrochemical expansion:Corpus Christi and Port Arthur complexes are consuming merchant hydrogen at scale for hydrocracking and desulfurization units.
Market Restraints
- Helium supply concentration:The Federal Helium Reserve's depletion and Qatar's export dominance leave North American buyers exposed to geopolitical disruption.
- Cryogenic distribution cost structure:Liquid nitrogen and argon require specialized tanker fleets and vaporization equipment that inflate delivered costs for inland customers.
- OSHA cylinder handling compliance:29 CFR 1910.101 mandates drive recurring training and inspection burdens for healthcare and manufacturing end users.
Strategic Opportunities
- DOE hydrogen hub funding:The Bipartisan Infrastructure Law's regional clean hydrogen allocations are catalyzing dedicated production assets in Texas, California, and the Midwest.
- Supercritical CO2 extraction:Food processing and pharmaceutical manufacturers are substituting legacy solvents with carbon dioxide for botanical oil and active ingredient recovery.
- Telemetry-enabled cylinder management:IoT pressure monitoring and predictive refill scheduling are reducing downtime for critical care facilities and research laboratories.
Industry Challenges
- Cryogenic engineering talent scarcity:The specialized workforce for air separation unit operation and maintenance is aging faster than training pipeline output.
- FDA cGMP certification timelines:Pharmaceutical-grade gas qualification requires 18-24 month validation cycles that delay new product commercialization.
- Legacy SCADA integration:Older production facilities face friction retrofitting digital monitoring systems without disrupting continuous operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Specialty Gas Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helium, Hydrogen, Nitrogen, Argon Application: Electronics, Pharmaceuticals, Food Processing, Welding End User: Manufacturing, Healthcare, Research Institutions, Chemical Industry Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Air Liquide, Air Products and Chemicals, Inc., Linde plc, Messer Group GmbH, Matheson Tri-Gas, Inc., MESA Specialty Gases & Equipment, Showa Denko K.K., Taiyo Nippon Sanso Corporation, Praxair Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Specialty Gas Market Evolving Landscape
Digital telemetry and predictive logistics are compressing inventory cycles while regulatory pressure on fluorinated process gases accelerates reclamation technology deployment across the value chain.
Membrane separation for on-site nitrogen generation is overtaking delivered liquid supply for mid-scale industrial users. Food packaging operations and electronics assembly plants are installing pressure swing adsorption units to bypass cylinder logistics entirely. This distributed production model is compressing merchant gas margins in the 5,000-50,000 scf/day consumption band.
EPA enforcement of the American Innovation and Manufacturing Act is phasing down hydrofluorocarbon production and consumption quotas. Semiconductor fabs must now document recovery rates for process gases or face permit restrictions. Texas and Arizona fabrication clusters are investing in centralized reclamation infrastructure to maintain operating licenses.
Buyers are consolidating procurement under master service agreements that bundle gas supply with equipment maintenance and safety training. Hospital networks and university research consortia are displacing fragmented cylinder orders with enterprise contracts spanning multiple sites. This concentration is most visible in the Northeast and Midwest, where healthcare system mergers have reduced supplier touchpoints by half.
North America Specialty Gas Market Segmentation
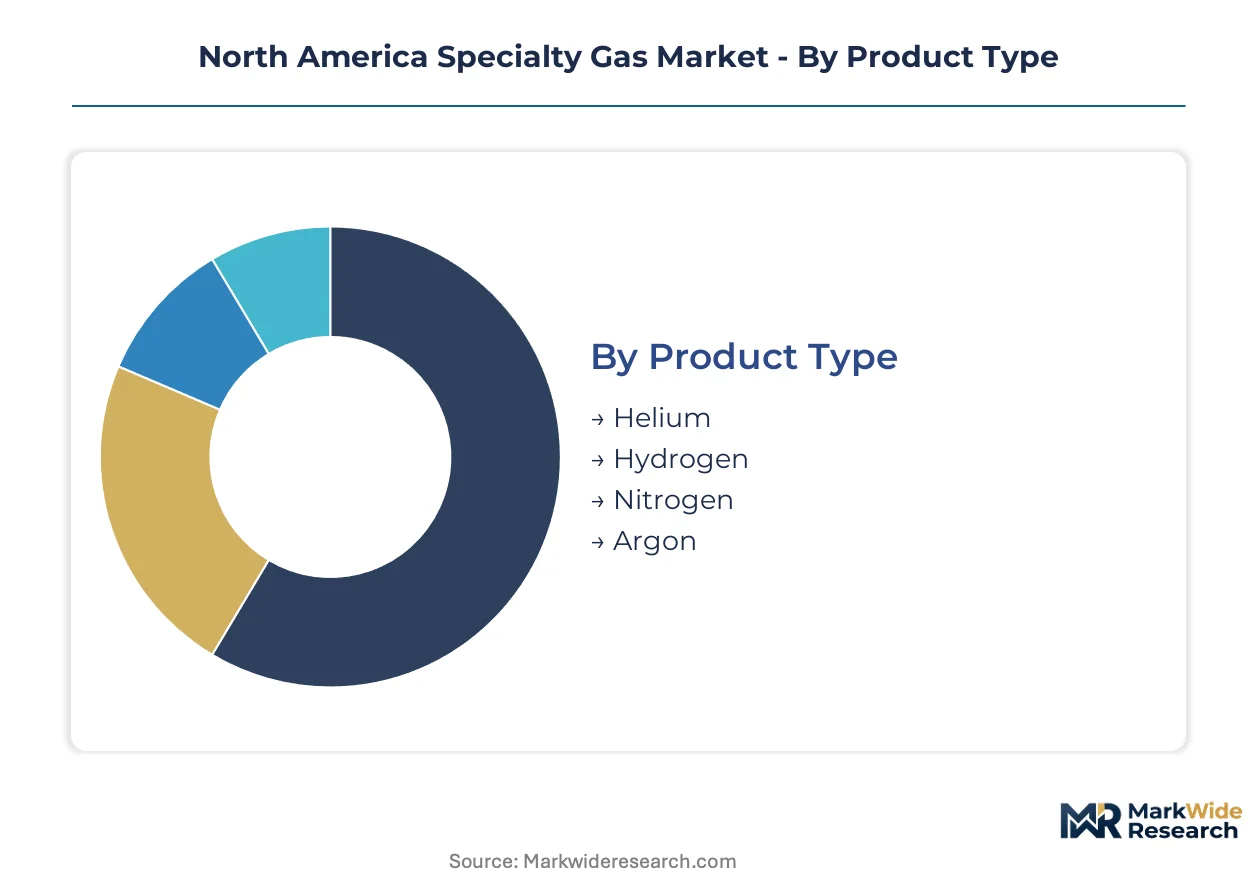
Specialty gas procurement patterns diverge sharply between high-volume commodity flows and precision-grade premium segments. Understanding where volume concentrates versus where margins thicken enables suppliers to align production assets with contract structures.
Product Type:
Volume leadership sits with atmospheric gases produced through cryogenic air separation, while helium and hydrogen command premium positioning through supply scarcity and energy transition demand.
- Helium:Ultra-high-purity grades exceeding 99.999% serve semiconductor lithography and MRI cooling in Texas and Arizona fabrication clusters. Federal Helium Reserve depletion and Qatar export dominance expose North American buyers to supply interruption risk.
- Hydrogen:Merchant supply for Gulf Coast refineries dominates current offtake, with PEM electrolysis capacity scaling for mobility and power-to-X applications. DOE hub funding is catalyzing dedicated production assets in Texas and California.
- Nitrogen:Electronic-grade specifications for wafer annealing chambers and inerting applications across pharmaceutical packaging lines.
- Argon:High-purity demand concentrates in metal fabrication and semiconductor deposition processes requiring plasma stability.
Mature deployment sits with nitrogen across legacy manufacturing. Newer deployment is concentrated in hydrogen for clean energy chemistry.
Application:
End-use economics separate process-critical specifications with contamination tolerance at parts-per-billion from industrial-grade tolerances measured in parts-per-million.
- Electronics:Wafer fabrication consumes electronic-grade argon and helium in deposition and annealing chambers where purity thresholds exceed 99.999%. CHIPS Act subsidies are locking in decade-long take-or-pay contracts with merchant suppliers.
- Pharmaceuticals:FDA cGMP documentation requirements govern nitrogen for sterile manufacturing and carbon dioxide for supercritical fluid extraction of active pharmaceutical ingredients.
- Food Processing:Modified atmosphere packaging and supercritical CO2 extraction for botanical oils are displacing legacy solvent systems in processing facilities.
- Welding:Shielding gas blends for precision fabrication in automotive and aerospace supply chains.
Volume concentration rests with welding across metal fabrication networks. Value expansion is accelerating fastest in electronics purity specifications.
End User:
Customer scale determines contract structure, with consolidated manufacturing accounts commanding direct supply relationships while fragmented research users flow through distribution.
- Manufacturing:Semiconductor fabs and petrochemical complexes anchor regional demand in Texas and Arizona, pulling merchant hydrogen and electronic-grade noble gases through pipeline and bulk tank delivery.
- Healthcare:Hospital networks and home care providers consume medical oxygen and nitrous oxide, with telemetry-enabled cylinder management reducing critical care downtime.
- Research Institutions:University consortia and national laboratories require rare and calibration gas blends in cylinder quantities below tier-one merchant thresholds.
- Chemical Industry:Hydrogen feedstock for ammonia synthesis and hydrocracking units in Gulf Coast complexes.
Procurement maturity clusters with chemical industry volume contracts. Emerging demand is reshaping fastest around healthcare system consolidation.
Distribution Channel:
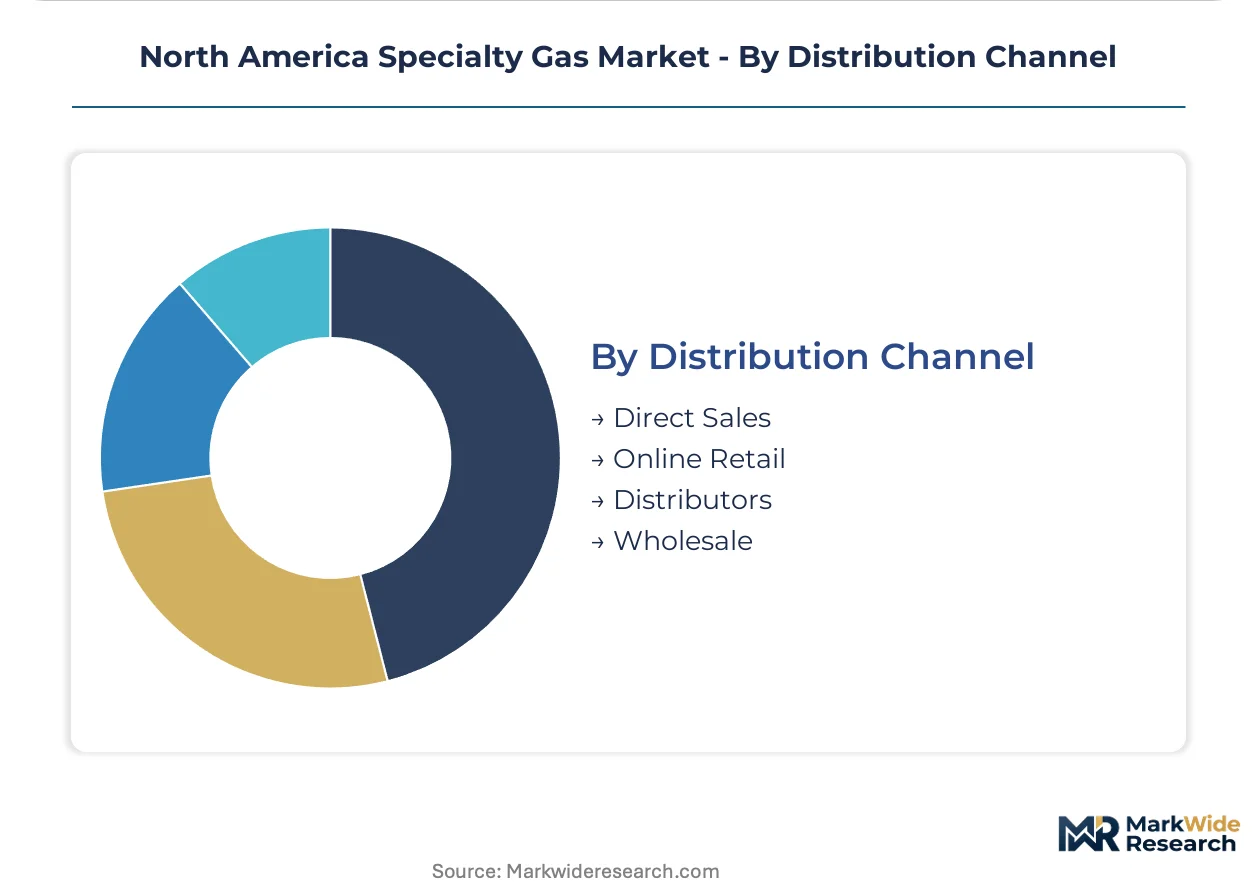
Channel selection tracks customer consolidation, with direct sales capturing integrated manufacturing accounts and distributor networks retaining fragmented research and small manufacturing access.
- Direct Sales:Long-term take-or-pay contracts with semiconductor fabs and petrochemical operators control the largest margin pools, bundling gas supply with equipment maintenance and safety training.
- Online Retail:Digital procurement portals for standardized cylinder specifications in research and small manufacturing segments.
- Distributors:Regional networks serve fragmented healthcare and research accounts with cylinder logistics and localized inventory.
- Wholesale:Bulk liquid and gas transfers between merchant producers and packaged gas repackagers.
Established infrastructure concentrates with direct sales to integrated manufacturers. Channel experimentation is expanding most quickly through online retail for standardized specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electronic-grade specialty gases concentrates in the United States, where CHIPS Act subsidies are reshaping regional supply geography. Texas and Arizona fabrication clusters pull merchant hydrogen and noble gases through dedicated pipeline infrastructure, while Canadian and Mexican markets serve distinct industrial bases with cross-border logistics dependencies.
United States
Texas anchors domestic demand through Corpus Christi and Port Arthur petrochemical complexes consuming merchant hydrogen at scale for hydrocracking units. EPA Clean Air Act fluorinated gas restrictions redirect investment toward sulfur hexafluoride recovery systems in Arizona and Texas wafer fabrication facilities. The CHIPS Act locks in decade-long take-or-pay contracts exceeding 99.999% purity specifications with merchant suppliers across Phoenix and Austin metro clusters.
Canada
Alberta's oil sands operations and Ontario automotive supply chains drive industrial gas consumption across welding and inerting applications. Health Canada pharmaceutical-grade standards govern nitrogen documentation for sterile manufacturing in Toronto and Montreal facilities. The Sarnia-Lambton petrochemical corridor maintains hydrogen pipeline networks serving regional refiners and chemical producers.
Mexico
Nuevo León's manufacturing expansion and Mexico City metro healthcare networks concentrate specialty gas demand across welding and medical oxygen segments. Mexican environmental regulations under SEMARNAT tighten venting protocols for industrial process gases in Monterrey industrial parks. Querétaro's aerospace supplier base consumes precision shielding gas blends for aluminum fabrication in growing tier-one operations.
North America Specialty Gas Market Competitive Landscape
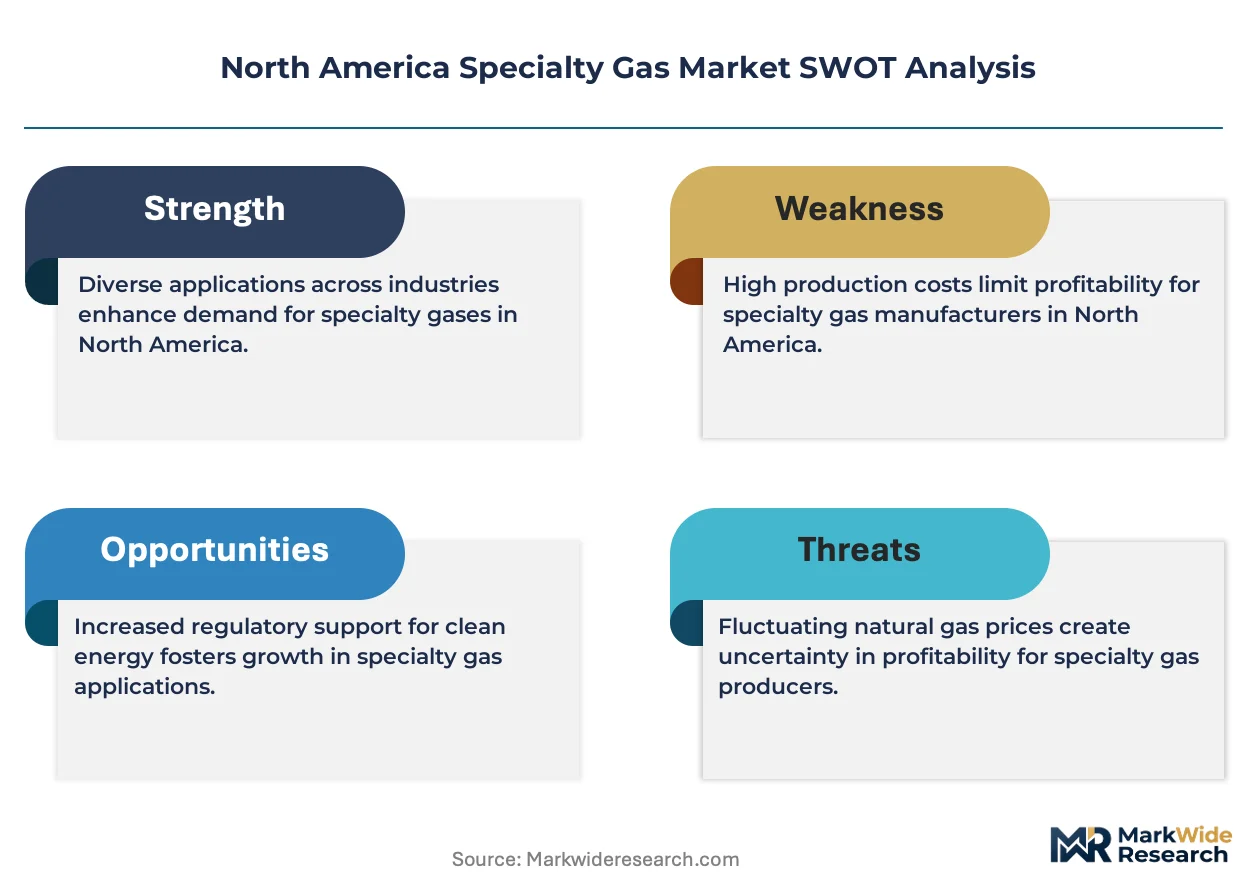
Long-term take-or-pay contracting dominates the current landscape as suppliers lock in semiconductor fab offtake before capacity comes online. The vendor base stratifies across three tiers: integrated multinational merchants controlling pipeline infrastructure, regional packaged gas distributors serving fragmented accounts, and niche calibration gas specialists occupying precision segments below merchant scale. Two competitive vectors shape positioning: geographic expansion through hydrogen hub proximity, and technology differentiation via telemetry-enabled cylinder management systems.
Within the integrated multinational tier, Air Products and Chemicals, Inc. and Linde plc occupy positions defined by Gulf Coast hydrogen infrastructure and proprietary logistics platforms respectively. MESA Specialty Gases & Equipment represents the niche calibration specialist archetype, occupying defensible volume bands below tier-one merchant thresholds where rare gas blend precision commands premium positioning.
| Leading Market Players |
|---|
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Linde plc |
| Messer Group GmbH |
| Matheson Tri-Gas, Inc. |
| MESA Specialty Gases & Equipment |
| Showa Denko K.K. |
| Taiyo Nippon Sanso Corporation |
| Praxair Technology, Inc. |
| Others |
Value Network & Pricing Analysis
Cryogenic liquefaction energy costs cascade through three distinct pricing tiers, with Gulf Coast electricity rates compressing margins on bulk liquid hydrogen while inland vaporization logistics inflate delivered prices for Arizona semiconductor fabs. Merchant suppliers pass through natural gas feedstock volatility via indexed contract clauses, locking in margin protection for air separation unit operators while exposing petrochemical buyers to spot market swings.
Pricing Analysis
Volume-margin splits separate commodity atmospheric gases from scarcity-premium helium and hydrogen. Electronic-grade specifications exceeding 99.999% purity command certification-driven premiums over industrial grades, with FDA cGMP documentation adding 15-20% cost layers for pharmaceutical nitrogen. Price pressure intensifies in the 5,000-50,000 scf/day consumption band where on-site membrane generators displace delivered liquid supply. Small research institutions exhibit highest price sensitivity due to fragmented procurement, while semiconductor fabs prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Texas and Arizona fabrication clusters require merchant suppliers to qualify backup production assets across Louisiana and Oklahoma air separation facilities. Qatar, Algeria, and Russia concentrate global helium feedstock through liquefied natural gas extraction byproduct streams. Feedstock dependency on natural gas processing and cryogenic equipment fabrication in Germany and Japan creates single-source vulnerability for turboexpander components. Distribution runs through dedicated tanker fleets with vaporization skids at customer sites, compressing inventory cycles through telemetry-enabled refill scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive hydrogen production assets determine contract win rates for semiconductor fab offtake. Players are pursuing upstream control over cryogenic distribution infrastructure to lock in regional demand clusters.
For Market Incumbents: Acquire Gulf Coast hydrogen pipeline networks and air separation unit capacity to preempt DOE hub competitors. Defend position by embedding telemetry-enabled cylinder management systems into hospital network contracts, creating switching costs against distributor rivals. Prioritize sulfur hexafluoride reclamation technology investment ahead of EPA enforcement timelines.
For New Entrants and Emerging Players: Digital procurement portals for standardized research-grade cylinder specifications offer lowest barrier to customer acquisition. Target university consortia and national laboratories with rare gas blend capabilities below tier-one merchant scale. Pursue supercritical CO2 extraction equipment bundling with gas supply to capture food processing verticals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale membrane separation specialists in the Midwest with stranded manufacturing customer bases. Long-term viability hinges on hydrogen electrolysis asset positioning ahead of fuel cell vehicle deployment inflection. Watch NHTSA zero-emission vehicle mandates as signal for regional hydrogen demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Production | Captive supply from PEM electrolysis secures semiconductor fab contracts ahead of DOE hub allocations. |
| Telemetry-Enabled Cylinder Management Deployment | IoT pressure monitoring reduces critical care downtime for hospital networks in consolidated healthcare systems. |
| Sulfur Hexafluoride Recovery Infrastructure Investment | EPA Clean Air Act compliance protects Arizona and Texas fabrication operating licenses from permit restrictions. |
| Supercritical CO2 Extraction Equipment Bundling | Integrated solvent-substitute systems capture food processing and pharmaceutical active ingredient recovery demand. |
| Rare Gas Blend Precision Capacity Addition | Calibration gas specialization below merchant scale defends margin position in research institution procurement. |
Research Methodology
Multi-period observation of CHIPS Act capital deployment, EPA enforcement actions, and hydrogen hub funding allocations anchored the trend analysis, supplemented by interviews with merchant gas procurement directors, semiconductor fab supply chain managers, cryogenic equipment engineers, and healthcare system materials managers. Secondary validation drew from SEC 10-K filings, EIA natural gas price data, DOE hydrogen program announcements, and OSHA incident reports. Bottom-up consumption modeling across end-use segments triangulated against top-down production capacity assessments.
Input-output matrices mapped cryogenic distillation capacity, pipeline infrastructure, and cylinder logistics costs against regional demand clusters over the projection horizon. Segmentation dimensions spanned purity grade tiers, application criticality, delivery mode, and customer consolidation levels. CAGRs were derived from demand elasticity modeling against semiconductor capital expenditure cycles and petrochemical utilization rates. Forecast inputs incorporated Federal Helium Reserve depletion trajectories and membrane separation technology substitution curves.
Inputs from regulatory filing databases and merchant supplier contract disclosures were available through the study window; gaps in real-time fab construction timelines and hydrogen electrolysis commissioning schedules introduce uncertainty bands around capacity-absorption timing. Forecasts reflect documented assumptions regarding CHIPS Act disbursement velocity and EPA enforcement intensity. Deviation in NHTSA fuel cell vehicle deployment timelines or DOE hydrogen hub funding allocations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Krypton Gas Market
Industrial Gases
High Purity Gas Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Global Industrial Gas Market