
 Portable Butane Gas Cartridge Market | 2026-2036
Portable Butane Gas Cartridge Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Butane Gas Cartridge Market Insights
East Asian butane canister manufacturers is repositioning capacity toward higher-grade sealing technologies and automated fill lines. Iwatani Corporation leverages its century-long gas distribution infrastructure to dominate Japan's retail channel. Taeyang Corporation anchors South Korean production with specialized valve systems for camping stoves. Marina Corporation competes across Southeast Asian markets through cost-optimized 230g formats.
A portable butane gas cartridge is a sealed, pressurized metal vessel containing liquefied petroleum gas, typically n-butane or isobutane blends, engineered to deliver controlled vapor release through a standardized Lindal valve interface for portable combustion applications. The 230g size segment sustains the highest volume turnover due to its optimal weight-to-burn-time ratio for weekend camping trips. Disposable cartridges dominate hospitality procurement channels where sanitation protocols prohibit refillable systems. Standard cartridges lead retail consumer segments, while multi-use formats with integrated safety shutoffs are gaining traction among outdoor enthusiasts seeking extended backcountry use.
FDA oversight of food-contact heating applications in the United States and Japan's METI pressure vessel certification create divergent compliance pathways that shape product design and market access requirements. The EU F-Gas Regulation and REACH chemical restrictions increasingly scrutinize butane sourcing and cylinder recyclability, forcing manufacturers to document supply chain carbon intensity. Stakeholders must monitor evolving refrigerant-phase-down schedules that could redirect technical butane flows and compress cartridge feedstock availability.
Market Dynamics
East Asian safety standards for pressurized metal vessels are tightening valve specifications and mandating automated fill-line documentation, forcing manufacturers to absorb compliance costs or exit hospitality procurement channels entirely.
Growth Catalysts
- Camping stove penetration:Weekend recreational users in Japan and South Korea favor 230g formats for weight-to-burn-time efficiency, sustaining volume turnover in retail channels.
- Urban heating demand:Dense metropolitan populations across East Asia rely on compact butane solutions for space-constrained residential warming, creating year-round consumption baseload.
- GB standards alignment:China's national standards for pressurized container safety are harmonizing export specifications, reducing certification friction for cross-border cartridge shipments.
Market Restraints
- Feedstock volatility:Technical butane supply faces compression from refrigerant-phase-down schedules redirecting petrochemical flows toward alternative uses.
- Recyclability mandates:EU REACH chemical restrictions and F-Gas Regulation scrutiny force manufacturers to document cylinder carbon intensity, raising documentation overhead.
- Substitution pressure:Electric induction cooktops and rechargeable battery systems displace butane in food-service applications where grid access is reliable.
Strategic Opportunities
- Vietnam outdoor retail expansion:Underdeveloped camping infrastructure in Southeast Asian markets offers first-mover positioning for safety-certified cartridge distribution.
- Integrated shutoff systems:Multi-use formats with embedded valve safety mechanisms command premium positioning among backcountry enthusiasts seeking extended trip reliability.
- Dual carbon incentives:China's national carbon neutrality targets subsidize energy-efficient heating appliances, indirectly supporting butane cartridge adoption in compliant portable units.
Industry Challenges
- Valve engineering talent scarcity:Specialized Lindal valve design expertise concentrates in Japanese and South Korean engineering clusters, limiting rapid capacity scaling elsewhere.
- METI certification timelines:Japan's pressure vessel approval processes extend product launch cycles, compressing margin recovery windows for seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Butane Gas Cartridge Market |
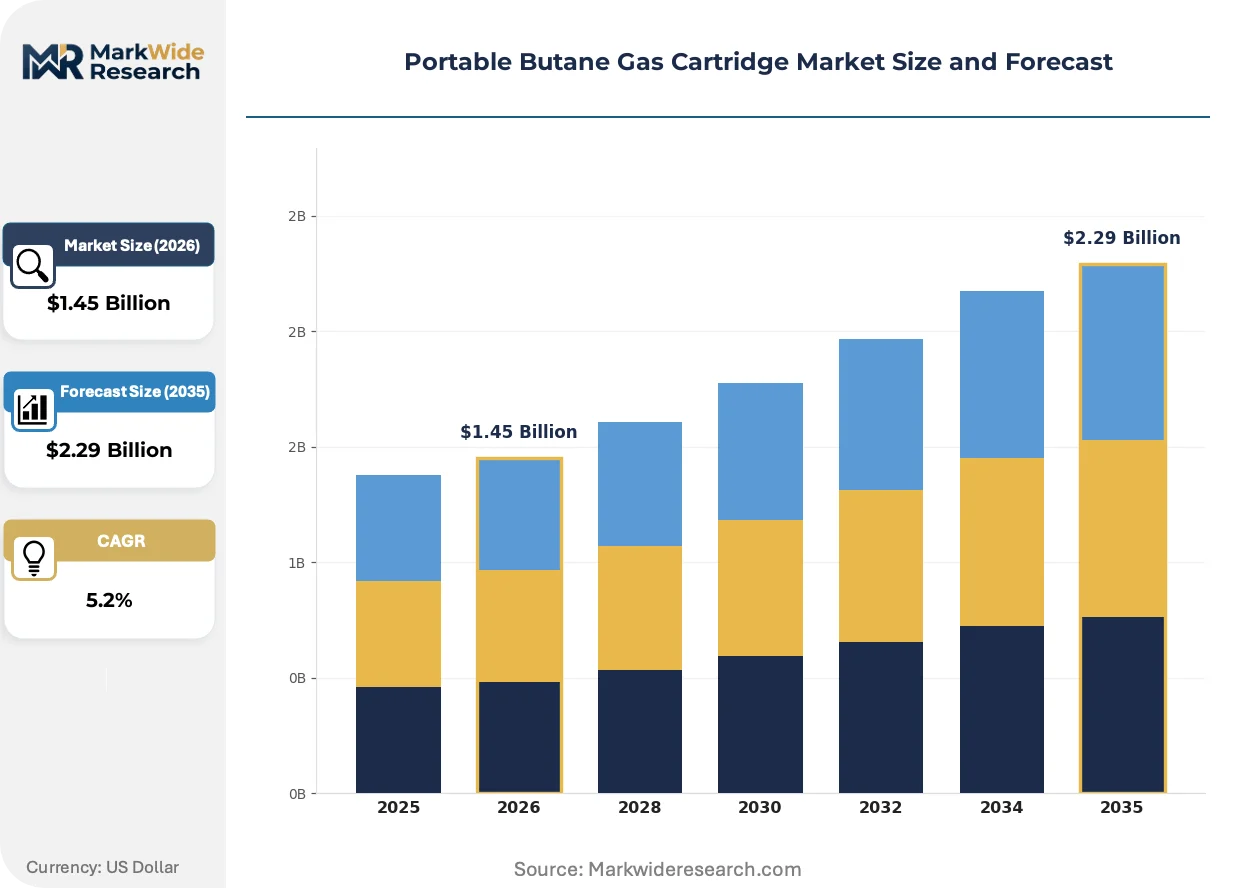
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartridges, Refill Cartridges, Disposable Cartridges, Multi-Use Cartridges Application: Camping, Cooking, Heating, Recreational End User: Retail Consumers, Outdoor Enthusiasts, Catering Services, Hospitality Size: 100g, 230g, 450g, 1000g |
| Companies Covered | Marina Corporation, Balkan Gasovi, Taeyang Corporation, Gasmate, Kampa, Coleman, Iwatani Corporation, Ultracare Products, Maxsun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Butane Gas Cartridge Market Trends and Innovations
Sealing technology evolution and automated manufacturing protocols are compressing defect rates while regulatory documentation requirements reshape competitive differentiation around traceability rather than price alone.
Advanced polymer gasket formulations are absorbing vibration stresses in multi-use cartridge designs, extending seal integrity across repeated connection cycles. Expedition-grade outdoor equipment buyers in Japan's alpine regions prioritize these enhanced formats despite 40-60% cost premiums over disposable alternatives. The technology is absorbing market share from standard single-use cartridges in segments where failure consequences include backcountry isolation.
Japan's METI pressure vessel certification now mandates batch-level digital traceability for all commercial butane cartridges, creating compliance moats for integrated manufacturers with captive fill-line automation. Smaller Southeast Asian assemblers lacking ERP-linked production systems face exclusion from institutional procurement channels. Hospitality chains in Tokyo and Osaka now require METI-compliant documentation as a non-negotiable vendor qualification threshold.
Specialty outdoor retailers are consolidating cartridge assortment authority, displacing general merchandise distributors in camping equipment channels. Independent mountaineering shops in South Korea's Gangwon Province now specify direct manufacturer relationships, bypassing traditional wholesale intermediaries. This channel compression is most visible in premium 230g segments where technical consultation and safety training accompany product sales.
Portable Butane Gas Cartridge Market Segmentation
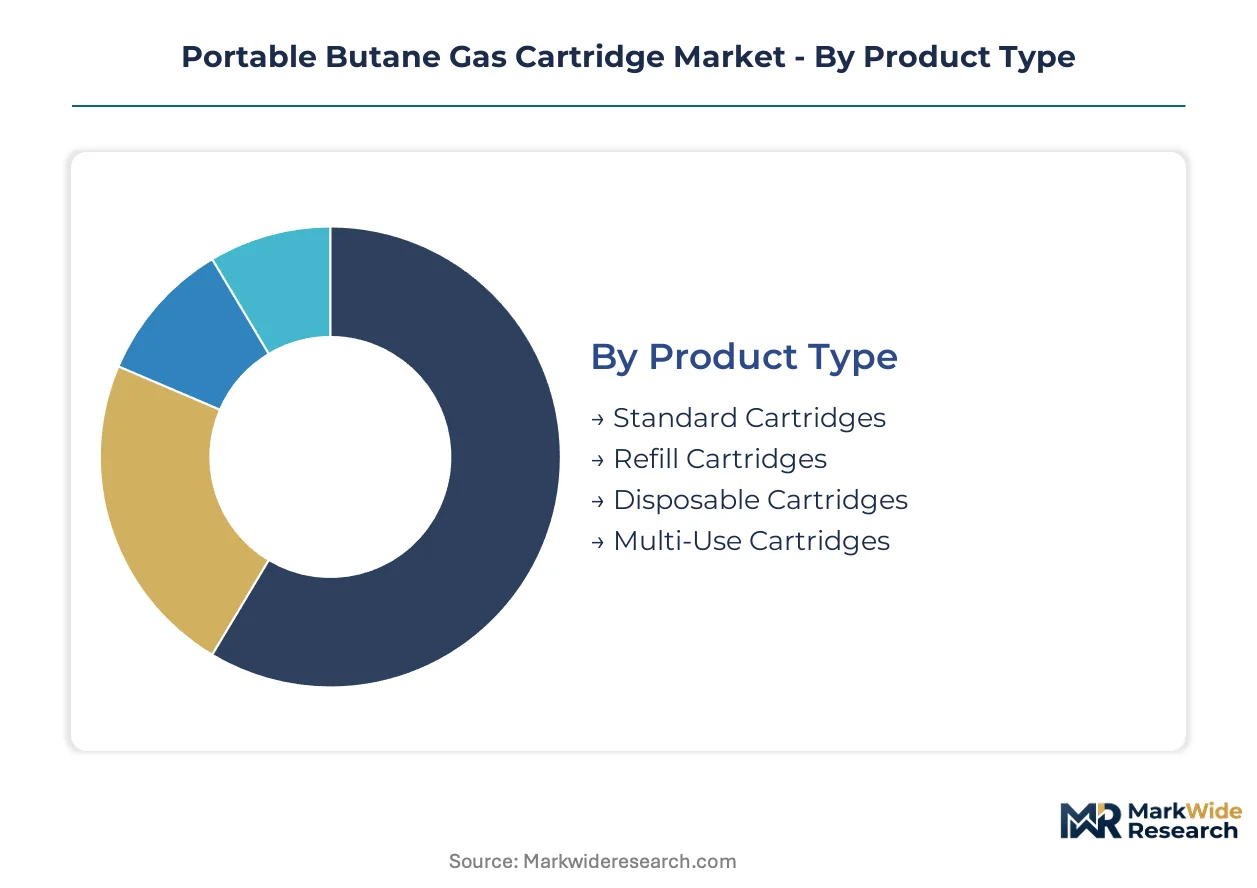
Segmentation in the portable butane gas cartridge market reveals how buyer priorities diverge across recreational, commercial, and residential use cases. Distinct product specifications, size preferences, and procurement channels shape competitive positioning for manufacturers targeting specific customer profiles.
Product Type:
Cost tier determines channel access and margin structure for cartridge manufacturers competing across consumer and institutional markets.
- Standard Cartridges:Single-use metal vessels with basic Lindal valve interfaces dominate mass-market retail distribution. Weekend campers in Japan and South Korea drive volume through convenience stores and outdoor specialty chains.
- Disposable Cartridges:Non-refillable formats with simplified valve mechanisms target food-service applications where sanitation protocols prohibit reusable systems. METI certification requirements in Japan restrict supply to integrated manufacturers with automated fill-line documentation.
- Refill Cartridges:Reusable vessels designed for commercial-grade refilling infrastructure serve catering operations with centralized procurement. Cost-per-use economics favor high-volume hospitality accounts in dense urban markets.
- Multi-Use Cartridges:Advanced polymer gasket systems enable repeated connection cycles for extended backcountry expeditions. Premium positioning among alpine enthusiasts in Japan's mountain regions absorbs 40-60% price premiums over disposable alternatives.
Standard cartridges lead on scale; multi-use cartridges lead on momentum.
Application:
Seasonal intensity and safety requirements fragment demand across outdoor recreation, commercial food preparation, and residential heating functions.
- Camping:Portable stove fuel for recreational outdoor cooking concentrates in East Asian markets with established weekend trekking culture. 230g formats optimize weight-to-burn-time ratios for overnight trips.
- Cooking:Commercial and residential food preparation applications demand consistent vapor pressure delivery across temperature ranges. FDA oversight of food-contact heating in the United States shapes product design for export-bound manufacturers.
- Heating:Space-constrained residential warming in dense metropolitan areas creates year-round consumption baseload. China's dual carbon incentives subsidize energy-efficient portable heating appliances using compliant cartridges.
- Recreational:Backyard grilling and patio heating applications compete with electric alternatives where grid access is reliable. Substitution pressure from induction cooktops compresses growth in developed urban markets.
Heating leads on scale; camping leads on momentum.
End User:
Procurement authority and volume concentration determine whether manufacturers prioritize retail distribution or direct institutional sales.
- Retail Consumers:Individual purchasers selecting cartridges for personal camping and emergency heating needs. Convenience store networks in Japan and South Korea capture impulse purchases through seasonal promotional placement.
- Outdoor Enthusiasts:Technical buyers prioritizing seal integrity and safety certification for backcountry isolation scenarios. Direct manufacturer relationships displace wholesale intermediaries in South Korea's Gangwon Province specialty shops.
- Catering Services:Mobile food vendors requiring portable fuel for off-grid cooking operations. GB standards alignment in China reduces certification friction for cross-border supply to Southeast Asian event markets.
- Hospitality:Hotels and restaurants with centralized procurement mandating METI-compliant documentation. Tokyo and Osaka hospitality chains exclude non-compliant vendors from approved supplier lists.
Hospitality leads on scale; outdoor enthusiasts lead on momentum.
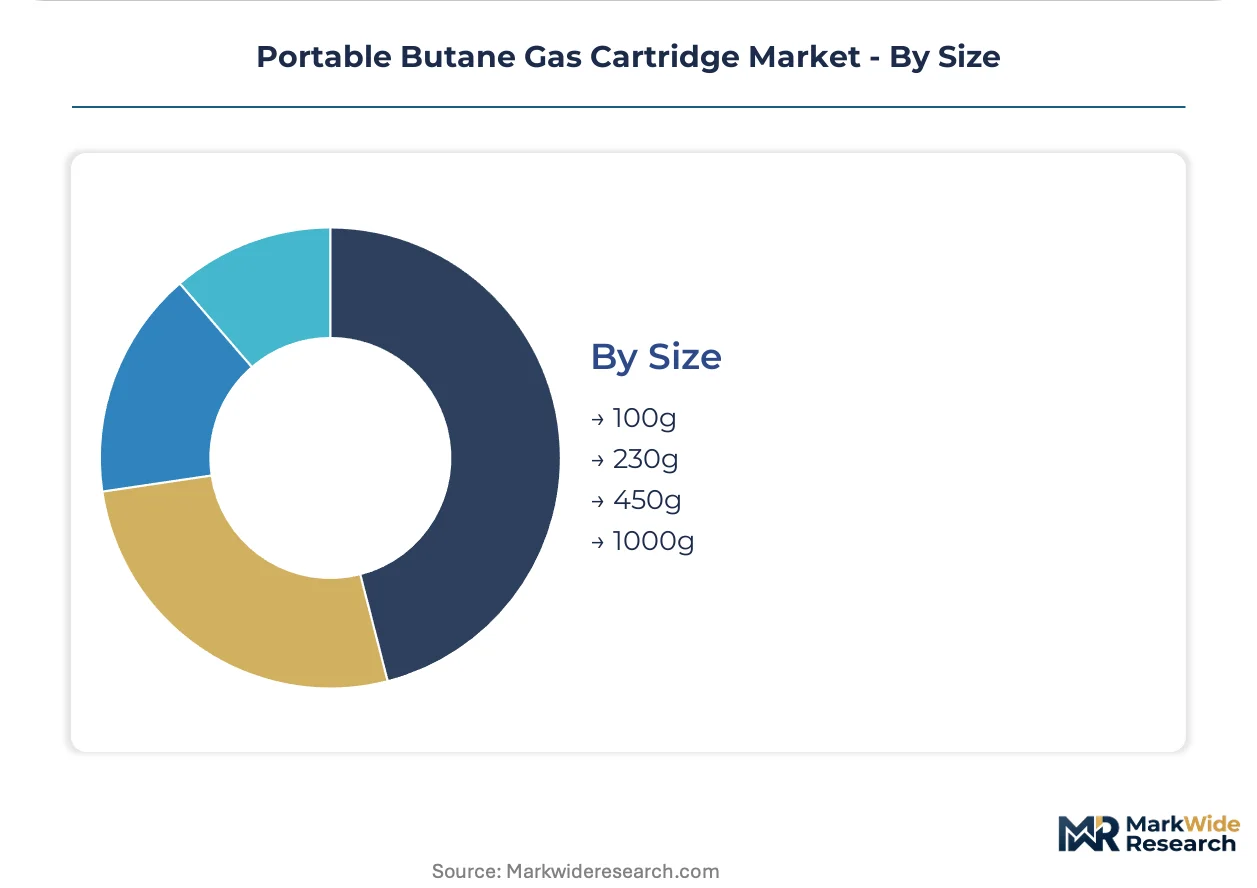
Size:
Weight-to-duration tradeoffs and trip duration patterns determine optimal cartridge capacity for distinct user segments.
- 230g:Mid-capacity vessels balancing portability and burn duration for weekend camping trips. Highest volume turnover in East Asian retail channels due to optimal weight-to-burn-time efficiency.
- 100g:Compact emergency backup formats for ultralight backpacking and vehicle glove compartment storage. Limited burn duration restricts use to supplemental rather than primary fuel sources.
- 450g:Extended-trip capacities for multi-day expeditions requiring reduced resupply frequency. Niche positioning among alpine climbing operations in Japan's Northern Alps.
- 1000g:Commercial-grade formats for stationary heating and high-volume catering applications. Bulk handling requirements limit distribution to institutional procurement channels with dedicated storage infrastructure.
230g leads on scale; 450g leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting portable butane gas cartridge manufacturing toward jurisdictions with harmonized certification regimes, as METI-compliant Japanese producers absorb compliance premiums while Southeast Asian assemblers face exclusion from institutional procurement channels.
Japan
Weekend recreational camping and dense urban residential heating sustain year-round demand for 230g formats. METI pressure vessel certification mandates batch-level digital traceability, creating compliance moats for integrated manufacturers. Tokyo and Osaka hospitality chains now require METI-compliant documentation as a non-negotiable vendor qualification threshold.
China
GB standards alignment for pressurized container safety is harmonizing export specifications and reducing certification friction for cross-border shipments. The country's national carbon neutrality targets subsidize energy-efficient heating appliances, indirectly supporting butane cartridge adoption in compliant portable units. Yangtze River Delta manufacturing clusters are repositioning capacity toward higher-grade sealing technologies and automated fill lines.
South Korea
Established outdoor culture and specialty mountaineering equipment channels drive premium positioning for multi-use cartridges with integrated safety shutoffs. Direct manufacturer relationships are displacing wholesale intermediaries in Gangwon Province's independent alpine shops. Taeyang Corporation anchors domestic production with specialized valve systems.
Vietnam
Underdeveloped camping infrastructure and expanding outdoor retail networks offer first-mover positioning for safety-certified cartridge distribution. GB standards alignment from neighboring China reduces import certification complexity for cross-border supply. Ho Chi Minh City and Hanoi are emerging as distribution hubs for Southeast Asian recreational markets.
United States
Food-service applications face substitution pressure from electric induction cooktops where grid access is reliable, compressing growth in developed urban markets. FDA oversight of food-contact heating applications shapes product design for export-bound manufacturers. Pacific Northwest outdoor retail channels concentrate demand for expedition-grade equipment.
Portable Butane Gas Cartridge Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hospitality procurement channels with automated documentation systems. The vendor base stratifies between integrated manufacturers with captive fill-line automation and smaller assemblers lacking ERP-linked production infrastructure. Three archetypes dominate: century-long gas distribution incumbents, specialized valve engineering shops, and cost-optimized Southeast Asian format specialists. Capacity expansion and METI certification acquisition represent the dominant competitive moves as seasonal demand peaks compress margin recovery windows.
Among East Asian integrated manufacturers, Iwatani Corporation exemplifies the distribution infrastructure archetype, Taeyang Corporation occupies the specialized valve engineering position, and Marina Corporation represents the cost-optimized format specialist tier. These three entities anchor distinct competitive vectors within a market where batch-level traceability and automated fill-line documentation increasingly determine channel access.
| Leading Market Players |
|---|
| Marina Corporation |
| Balkan Gasovi |
| Taeyang Corporation |
| Gasmate |
| Kampa |
| Coleman |
| Iwatani Corporation |
| Ultracare Products |
| Maxsun |
| Others |
Pricing and Supply Chain Analysis
METI batch-level digital traceability mandates in Japan are forcing hospitality procurement channels to exclude assemblers lacking ERP-linked production systems, compressing supplier pools and elevating pricing power for integrated manufacturers with automated fill-line documentation. This demand-side specification tightening feeds directly into supply-side consolidation, as smaller Southeast Asian operators absorb margin erosion or exit institutional channels entirely.
Pricing Analysis
Retailer markup layers in Japanese convenience store networks and South Korean outdoor specialty chains absorb significant channel margin, while direct-to-hospitality contracts command volume discounts with stringent documentation requirements. Three-tier pricing structure across premium multi-use, standard disposable, and economy 100g formats differentiates by certification grade and valve engineering sophistication. Cost compression in the economy tier intensifies because feedstock volatility and refrigerant-phase-down schedules redirect technical butane flows. Hospitality procurement managers in Tokyo and Osaka exhibit lowest price sensitivity due to compliance non-negotiability, whereas weekend campers in mass-market retail channels drive highest price elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated stove manufacturers, while specialty outdoor retailers consolidate assortment authority through direct manufacturer relationships. Manufacturing gravity centers on Japan, South Korea, and China's Yangtze River Delta clusters, with valve engineering expertise concentrating in Japanese and South Korean engineering clusters. Raw material flows draw from technical butane petrochemical streams, Lindal valve component forgings, and advanced polymer gasket formulations. Single-source vulnerability in specialized valve design talent limits rapid capacity scaling outside established East Asian hubs. Distribution runs through layered wholesale intermediaries in standard tiers, with channel compression accelerating in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where METI certification timelines and batch-level traceability mandates continuously elevate compliance barriers, structurally advantaging integrated incumbents while compressing margin recovery windows for seasonal demand peaks.
For Market Incumbents: Extend automated fill-line documentation capabilities to capture hospitality procurement channel expansion, while anchoring valve engineering talent in South Korean and Japanese clusters to defend against emerging Southeast Asian cost-optimized entrants. Backward integration into captive polymer gasket formulation secures supply continuity for multi-use cartridge premium tiers. For New Entrants and Emerging Players: Capture underdeveloped camping infrastructure in Vietnam through GB-standards-aligned import positioning, leveraging China's harmonized export specifications to reduce certification friction. Direct distributor relationships with Ho Chi Minh City and Hanoi outdoor retail hubs offer first-mover positioning ahead of institutional channel consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized valve engineering shops possessing METI-compliant documentation systems and captive fill-line automation, as these assets command scarcity premiums in a market where certification moats determine channel access. Acquisition target archetype: mid-cap integrated manufacturers with ERP-linked production infrastructure and established hospitality procurement relationships. Signal to watch: refrigerant-phase-down schedule acceleration compressing technical butane feedstock availability and triggering cartridge price inflection.| Strategic Initiative | Industry Significance |
|---|---|
| METI Certification Acquisition | Unlocks Tokyo and Osaka hospitality procurement channels with non-negotiable vendor qualification thresholds. |
| Automated Fill-Line Deployment | Enables batch-level digital traceability compliance and excludes ERP-deficient Southeast Asian competitors. |
| Valve Engineering Talent Retention | Secures scarce Lindal design expertise concentrated in Japanese and South Korean technical clusters. |
| Vietnam Distribution Partnership | Establishes first-mover positioning in underdeveloped Southeast Asian camping infrastructure expansion. |
| Polymer Gasket Formulation Integration | Absorbs vibration stresses for multi-use cartridge premium tiers commanding 40-60% price premiums. |
Research Methodology
Coverage spans East Asia, Southeast Asia, and North American import markets, with primary inputs from each region combined with secondary validation. Interviews with valve engineering directors, hospitality procurement managers, outdoor specialty retail buyers, and petrochemical feedstock specialists informed demand-side and supply-side dynamics. Secondary sources include METI pressure vessel certification databases, GB standards documentation, customs trade records for butane cartridge flows, and SEC filings from integrated gas distribution incumbents. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Granularity-level modeling addressed product type tiers, application functions, end-user procurement authority, and size capacity specifications across the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions, with cross-validation against petrochemical feedstock availability projections and regulatory compliance cost absorption curves. Industry-specific inputs incorporated refrigerant-phase-down schedule impacts on technical butane flows and METI certification timeline extensions affecting seasonal demand peak coverage.
Feedstock redirection under refrigerant-phase-down schedules, METI certification timeline volatility, and hospitality procurement channel consolidation are the dominant revision risks to modeled assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Noble Gas Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
North America Syngas Market
Industrial Gases
Welding Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Global Syngas and Derivatives Market